
 Tanker Shipping Market | 2026-2036
Tanker Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Tanker Shipping Market Intelligence
The long-held dominance of Oil Majors in chartering large crude carriers is unwinding as agile commodity traders gain significant market share. Euronav NV leverages its extensive fleet of Very Large Crude Carriers (VLCCs) to serve both these traditional and new charterers. Meanwhile, Scorpio Tankers specializes in the modern, eco-design product tanker segment, catering to refined petroleum product movements. Frontline Ltd. competes across multiple tanker classes, maintaining a flexible operational profile to capture market volatility.
Tanker shipping refers to the maritime transportation of liquid bulk cargo, including crude oil, petroleum products, and chemicals. Modern tankers are defined by their double-hull construction, a design mandated to prevent oil spills. Crude oil tankers, particularly VLCCs and Suezmax vessels, represent the largest segment by deadweight tonnage. In terms of service, time charter agreements provide stable revenue streams, while the voyage charter market offers exposure to spot rate fluctuations.
The International Maritime Organization (IMO) sets the primary framework for safety, pollution, and energy efficiency with its MARPOL and SOLAS conventions. Additionally, the EU's Fit for 55 package and US EPA vessel discharge standards impose regional requirements on emissions and ballast water management. Shipowners now face critical investment decisions regarding dual-fuel propulsion systems and alternative fuels to ensure long-term fleet compliance and competitiveness.
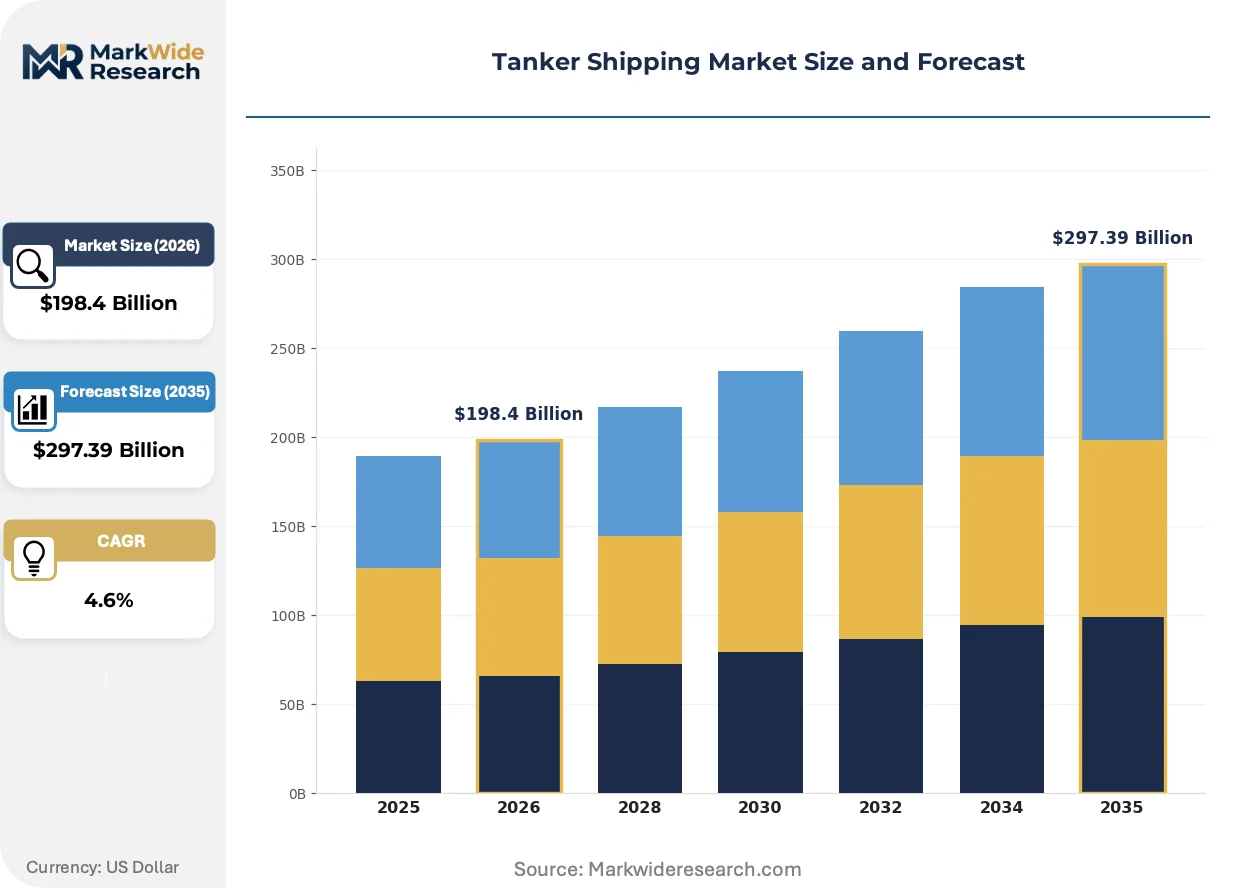
Market Dynamics
The structural tension between meeting stringent decarbonization targets set by the International Maritime Organization and navigating geopolitical shifts that alter global energy trade flows is defining the tanker shipping market's current investment cycle.
Growth Catalysts
- Petrochemical Demand:Expansion of petrochemical facilities in India and the Middle East boosts demand for specialized tankers to transport chemical feedstocks and finished products.
- Regulatory Mandates:The IMO's Carbon Intensity Indicator (CII) framework compels shipowners to invest in newer, more fuel-efficient vessels to avoid operational penalties, stimulating fleet renewal.
- Refinery Expansion:New refinery capacity in China and Nigeria is creating sustained demand for crude oil transportation services into these regions on VLCC and Suezmax tankers.
Market Restraints
- Input Cost Volatility:Extreme fluctuations in the price of marine bunker fuels, including new low-sulfur variants, directly impact voyage profitability and create hedging challenges for operators.
- Regulatory Fragmentation:Shipowners face conflicting compliance demands from the EU's Emissions Trading System (ETS) and potential future carbon levies from the IMO, complicating investment decisions.
- Shipyard Concentration:Newbuild capacity is heavily concentrated in South Korea, China, and Japan, resulting in long waiting times and price inflation for modern, eco-design tankers.
Strategic Opportunities
- Alternative Fuel Transport:The global energy transition will create new markets for transporting alternative fuels like ammonia and hydrogen, requiring purpose-built or retrofitted tankers.
- Carbon Capture Logistics:Developing a seaborne transportation network for captured CO2 offers a new revenue stream for specialized liquid gas carriers, linking industrial clusters to sequestration sites.
- Digitalization Services:Offering advanced data analytics for voyage optimization and emissions monitoring provides a new value-add opportunity beyond simple vessel chartering.
Industry Challenges
- Crew Competency Gap:A shortage of seafarers trained to operate vessels with advanced dual-fuel engines and sophisticated environmental systems threatens fleet operational readiness.
- Capital Intensity:The immense capital outlay needed for methanol or ammonia-powered newbuilds, which cost significantly more than conventional tankers, strains the finances of many operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanker Shipping Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $297.39 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Crude Oil Tankers, Product Tankers, Chemical Tankers, LNG Carriers, LPG Carriers Service Category: Time Charter, Voyage Charter, Bareboat Charter, Contract of Affreightment Cargo Type: Petroleum Products, Liquefied Gas, Chemicals, Vegetable Oils, Molasses Customer Segment: Oil Majors, Refiners, Petrochemical Companies, Shipping Lines, Commodity Traders |
| Companies Covered | Scorpio Tankers, DHT Holdings, Mitsui O.S.K. Lines, Navios Maritime, Tsakos Energy Navigation, Teekay Corp, Frontline Ltd, International Seaways, Euronav NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanker Shipping Market Strategic Shifts & Innovations
Operational efficiency and data-driven compliance are displacing sheer vessel size as the primary competitive differentiators. The convergence of digital technologies and new propulsion systems is fundamentally altering how tanker assets are managed, valued, and deployed in response to regulatory demands.
Advanced onboard sensor arrays provide continuous, real-time data on engine performance, fuel flow, and hull condition. Vessel operators and charterers are adopting these systems to verify efficiency and ensure compliance with environmental regulations. The core component technology is miniaturizing, enabling more granular and cost-effective data acquisition from numerous points across the vessel without complex retrofitting.
The International Maritime Organization's implementation of the Carbon Intensity Indicator (CII) framework establishes mandatory annual efficiency ratings for vessels. This regulation is forcing shipowners to actively manage and improve their fleet's performance to avoid penalties, which can include being required to submit a corrective action plan. The crude oil tanker segment, particularly older VLCCs, is heavily impacted, accelerating decisions on retrofits or scrapping.
Charter party agreements from oil majors and commodity traders now frequently include specific environmental performance clauses. This practice creates a clear commercial advantage for vessels with superior energy efficiency ratings, pushing older, less efficient tonnage from premium routes. This trend is particularly pronounced for voyages into European ports, where the EU ETS adds a direct cost to carbon emissions.
Tanker Shipping Market Segmentation
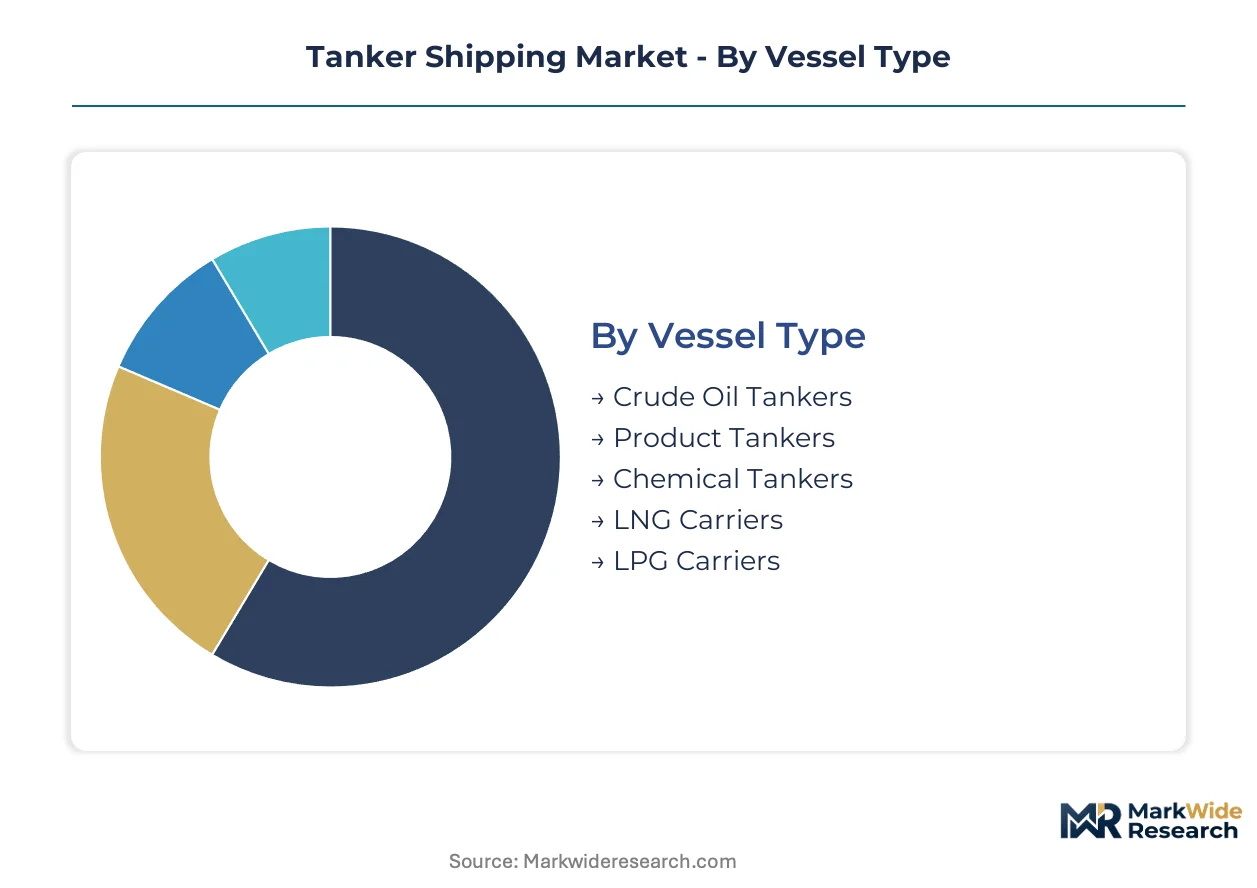
The Tanker Shipping Market transports liquid bulk cargoes through diverse vessel types and service models. Market segmentation reveals the specialized infrastructure and contractual arrangements essential for global energy and chemical supply chains. Understanding these distinctions clarifies operational complexities and commercial opportunities across various liquid bulk commodities.
Vessel Type:
The transportation of liquid bulk commodities relies on a specialized fleet, each vessel type engineered for specific cargo and trade routes, dictating their operational channels.
- Crude Oil Tankers:These vessels, including VLCCs, transport unrefined petroleum from production sites to refineries. Demand concentrates in Asia-Pacific, driven by new refinery projects in China and India requiring substantial crude oil imports.
- Product Tankers:Specializing in refined petroleum products like gasoline and diesel, these ships distribute from refineries to consumption centers. European ports drive demand for eco-design tankers due to stringent environmental performance clauses.
- Chemical Tankers:Highly specialized vessels transport diverse chemical feedstocks and finished products, often requiring stainless steel tanks.
- LNG Carriers:Designed for cryogenic transport of liquefied natural gas, these ships feature advanced containment systems.
- LPG Carriers:These vessels transport liquefied petroleum gas, such as propane and butane, under pressure or refrigeration.
By volume, Crude Oil Tankers lead. By growth pace, LNG Carriers represent the fastest-growing trajectory.
Service Category:
Service categories delineate the contractual frameworks and risk allocation between shipowners and charterers, directly influencing operational cost structures and revenue stability.
- Time Charter:The charterer employs the vessel for a fixed period, paying a daily rate, with the owner providing the ship and crew. This model offers stable revenue for shipowners, especially with modern vessels.
- Voyage Charter:This contract hires a vessel for a single voyage, with the owner covering all operational costs including fuel. This market exposes operators to spot rate fluctuations.
- Bareboat Charter:The charterer assumes full operational control and responsibility for the vessel, including crewing and maintenance.
- Contract of Affreightment:This agreement covers transporting a specific cargo volume over a period, without specifying a particular vessel.
The revenue generation varies significantly, with Time Charter providing stability and Voyage Charter offering market exposure.
Cargo Type:
Cargo types define the specific handling requirements and safety protocols for liquid bulk transportation, influencing vessel design and operational logistics.
- Petroleum Products:This category includes refined fuels such as gasoline and diesel, transported by product tankers for global distribution. Demand is consistently high in industrialized nations.
- Chemicals:Covering various liquid chemicals, these cargoes demand specialized chemical tankers with corrosion-resistant tanks. Petrochemical expansion in the Middle East and India drives feedstock transport demand.
- Liquefied Gas:This segment includes LNG and LPG, requiring specialized carriers with cryogenic or pressurized containment systems.
- Vegetable Oils:Transported in food-grade tanks, these oils serve the food industry and biofuel sector, requiring strict cleanliness.
- Molasses:A byproduct of sugar refining, molasses is transported in bulk for use in animal feed and industrial fermentation.
The market's diversity is evident in Petroleum Products' widespread use and Chemicals' specialized transport requirements.
Customer Segment:
Different customer segments drive distinct demand patterns and contractual preferences within the tanker shipping market, influencing fleet deployment strategies.
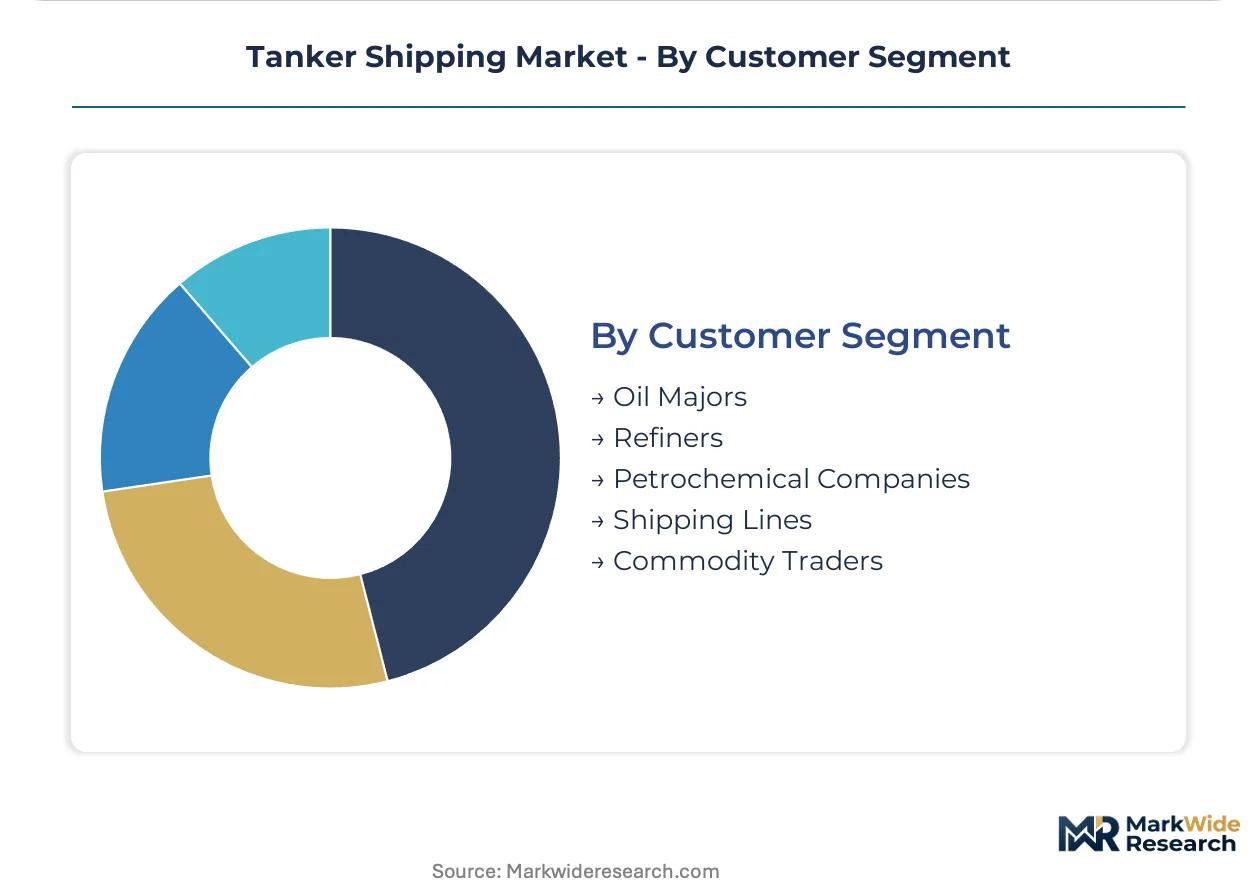
- Oil Majors:These integrated energy companies historically dominated large crude carrier chartering, leveraging extensive global operations and long-term contracts. They prioritize reliability and scale.
- Commodity Traders:Agile and responsive, these entities increasingly gain market share in chartering, utilizing flexible voyage charters to capitalize on spot market fluctuations. Their presence diversifies demand.
- Refiners:Operating refineries, these companies require crude oil feedstock and transport refined products, influencing demand for both crude and product tankers.
- Petrochemical Companies:These firms drive demand for specialized chemical tankers to transport feedstocks like naphtha and finished chemical products.
- Shipping Lines:Diversified shipping groups may operate or charter tankers as part of their broader logistics and supply chain services.
Power dynamics within the market are shifting, with Oil Majors maintaining influence and Commodity Traders gaining significant share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global tanker shipping activity exhibits a strong supply-side concentration in East Asian shipyards, which produce most newbuild vessels. Demand for crude oil tanker services also concentrates in the Asia-Pacific region, driven by extensive refinery expansion projects. European ports, meanwhile, drive demand for specialized eco-design product tankers.
China
China's expanding refinery capacity and robust industrial growth generate significant demand for crude oil and chemical tanker services. The national dual carbon goals are compelling shipping companies to invest in modern, fuel-efficient vessels for Chinese ports. The Yangtze River Delta, a major manufacturing hub, sees continuous tanker traffic for raw material imports.
India
India's rapid petrochemical and refinery expansions are boosting demand for specialized chemical tankers and crude oil carriers. The country's infrastructure development initiatives, including port modernizations, facilitate increased maritime trade. Gujarat, a prominent industrial state, serves as a key destination for chemical feedstocks and refined petroleum products.
South Korea
South Korea remains a global leader in shipbuilding, particularly for advanced eco-design and dual-fuel tankers. The nation's stringent environmental regulations influence the design and construction of next-generation vessels. Ulsan, a major port city, integrates extensive shipbuilding facilities with petrochemical complexes, generating specialized tanker demand.
Netherlands
The Netherlands, with its strategic port infrastructure, drives demand for product tankers distributing refined petroleum across Europe. The EU's Fit for 55 package mandates lower emissions, favoring eco-design vessels for Dutch calls. The Port of Rotterdam, a key European gateway, handles extensive volumes of refined products and chemical cargoes.
Saudi Arabia
Saudi Arabia's position as a major crude oil exporter and its expanding petrochemical industry generate consistent demand for large crude carriers and chemical tankers. The Kingdom's Vision 2030 initiatives aim to increase domestic refining and chemical production capacities. Jubail Industrial City, on the Persian Gulf, represents a significant hub for petrochemical feedstock imports and product exports.
Tanker Shipping Market Key Industry Players
Concentration sits with large, established integrated energy companies, alongside a growing cohort of agile commodity traders. The market structure features a tiered landscape of major oil companies, specialized tanker operators, and independent vessel owners. Strategic archetypes include diversified fleet managers, niche product specialists, and spot market-focused entities. Dominant competitive moves involve fleet modernization for regulatory compliance and investment in advanced digital solutions for operational efficiency.
Within the specialized tanker segment, companies like Scorpio Tankers exemplify the modern product tanker archetype, focusing on refined petroleum movements with their fleet of eco-design vessels. Euronav NV anchors the very large crude carrier (VLCC) market, providing extensive capacity for global crude oil transportation to both traditional oil majors and agile commodity traders. Frontline Ltd. occupies a position across multiple tanker classes, maintaining operational flexibility to navigate market volatility and capture diverse chartering opportunities across crude and product movements. These entities showcase varied strategies, from niche specialization to broad fleet deployment, adapting to evolving market demands and regulatory pressures.
| Leading Market Players |
|---|
| Scorpio Tankers |
| DHT Holdings |
| Mitsui O.S.K. Lines |
| Navios Maritime |
| Tsakos Energy Navigation |
| Teekay Corp |
| Frontline Ltd |
| International Seaways |
| Euronav NV |
| Others |
Cost & Logistics Intelligence
Alternative fuel adoption, such as ammonia and hydrogen, is simultaneously reshaping tanker shipbuilding supply geography and pricing economics for newbuild vessels. This shift influences long-term charter rates and operational costs for shipowners.
Pricing Analysis
The IMO's Carbon Intensity Indicator (CII) framework dictates the pricing tier structure for tanker charter rates. Pricing operates on a hybrid model, combining volatile voyage charter spot rates with stable time charter agreements. Price differentiation stems from eco-design vessel efficiency, dual-fuel capability, and specific cargo handling features. Pricing softness impacts older, less efficient tonnage due to regulatory penalties and charterer preference, while commodity traders exhibit high price sensitivity in the spot market.
Supply Chain Analysis
Fleet deployment strategies often blend just-in-time vessel allocation for spot voyage charters with strategic capacity stockpiling via long-term time charters. Geographic supply concentration for newbuild tankers sits heavily in South Korea, China, and Japan. Raw material dependencies include specialized steel plates, marine engines, and advanced navigation systems. Shipyard concentration presents a structural risk, leading to long waiting times and price inflation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tanker shipping market presents an early-cycle expansion story, driven by mandatory fleet modernization for regulatory compliance. Investment in eco-design and dual-fuel vessels is accelerating across the global fleet.
For Market Incumbents: Shield existing market share by accelerating fleet renewal with eco-design and dual-fuel vessels. Pursue long-term time charter agreements with Oil Majors to counter the volatility introduced by agile commodity traders. Invest in advanced digital optimization platforms to mitigate operational inefficiencies and regulatory fragmentation. This proactive modernization addresses the threat of obsolescence for older tonnage.
For New Entrants and Emerging Players: Differentiate on advanced vessel technology and specialized cargo capabilities. Target underserved niche segments like CO2 capture logistics or alternative fuel transport, which require purpose-built or retrofitted tankers. Focus on a go-to-market angle emphasizing superior environmental performance and data-driven operational efficiency. This approach allows smaller players to gain traction against established fleets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized independent vessel owners navigating fleet modernization pressures. The tanker shipping market maintains long-term viability as an indispensable component of global energy and chemical supply chains. Target acquisition profiles include operators with modern, eco-design, and dual-fuel compliant fleets demonstrating strong charter relationships. The signal to watch is the increasing proportion of alternative fuel vessels in the global newbuild orderbook.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Program | Ensures compliance with IMO regulations and attracts premium charter rates from European ports. |
| Investment in Dual-Fuel Propulsion | Prepares vessels for future alternative fuel mandates and reduces operational emissions for Oil Majors. |
| Digital Voyage Optimization Platform | Enhances fuel efficiency and emissions monitoring, providing a competitive advantage for commodity traders. |
| Specialized Chemical Tanker Newbuilds | Addresses rising demand from petrochemical companies in India and the Middle East for feedstocks. |
| Carbon Capture Logistics Exploration | Creates a new revenue stream for specialized liquid gas carriers linking industrial clusters to sequestration sites. |
Research Approach
Operator-level perspectives from shipowners, chartering managers, refinery logistics heads, and port authorities anchored the qualitative base for this analysis. This primary research combined with extensive secondary validation from IMO reports, EU Fit for 55 documents, and company annual reports. The approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Sensitivity analysis informed the forecast framework, accounting for various market scenarios over the projection horizon. The quantitative model segmented demand across vessel type, service category, cargo type, customer segment, and regional trade lanes. Compound Annual Growth Rates were derived from historical trends and projected market shifts. Key forecast inputs included global energy demand projections and new refinery capacity announcements.
The analysis sits within stated boundaries; outcomes outside major geopolitical shifts or unforeseen propulsion breakthroughs would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement and energy transition. Revision becomes warranted when global trade patterns or fuel technology adoption cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market