
 Baggage Handling System Market | 2026-2036
Baggage Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Baggage Handling System Market Intelligence
Aluminum-reinforced conveyor framing is hardening as the default structural standard over traditional steel assemblies in mid-scale airport retrofits, cutting installed weight and foundation loads. Siemens AG leverages its factory automation heritage to integrate drive controls with building management protocols. Daifuku Co., Ltd. anchors Asian supply chains through captive manufacturing of sorter modules in Japan and Thailand. BEUMER Group competes on bulk-material handling expertise translated into high-throughput baggage applications.
A baggage handling system comprises mechanized conveyor networks, sortation devices, screening apparatus, and control software engineered to transport, track, and inspect luggage from check-in to aircraft loading, typically processing items at speeds of 1.5 to 3 meters per second while maintaining traceability via unique identifier tags. Conveyor systems still occupy the largest installed base across legacy terminals, yet robotic solutions represent the fastest-expanding segment as labor costs rise and 24-hour operational demands intensify. RFID technology leads the technology stack in new-build projects, while barcode scanning sustains dominance in retrofit budgets where infrastructure write-down cycles delay full replacement.
FAA mandates under 49 CFR govern explosives detection system performance standards for all US commercial airports, while EU F-Gas Regulation restricts refrigerants in climate-controlled sorting environments, altering equipment specification sheets. ICAO security frameworks and national aviation authorities in Germany, France, and Japan enforce divergent screening protocols that fragment vendor certification requirements. Stakeholders must monitor harmonization gaps between regional security mandates and sustainability codes when sizing R&D budgets and partnership priorities.
Market Dynamics
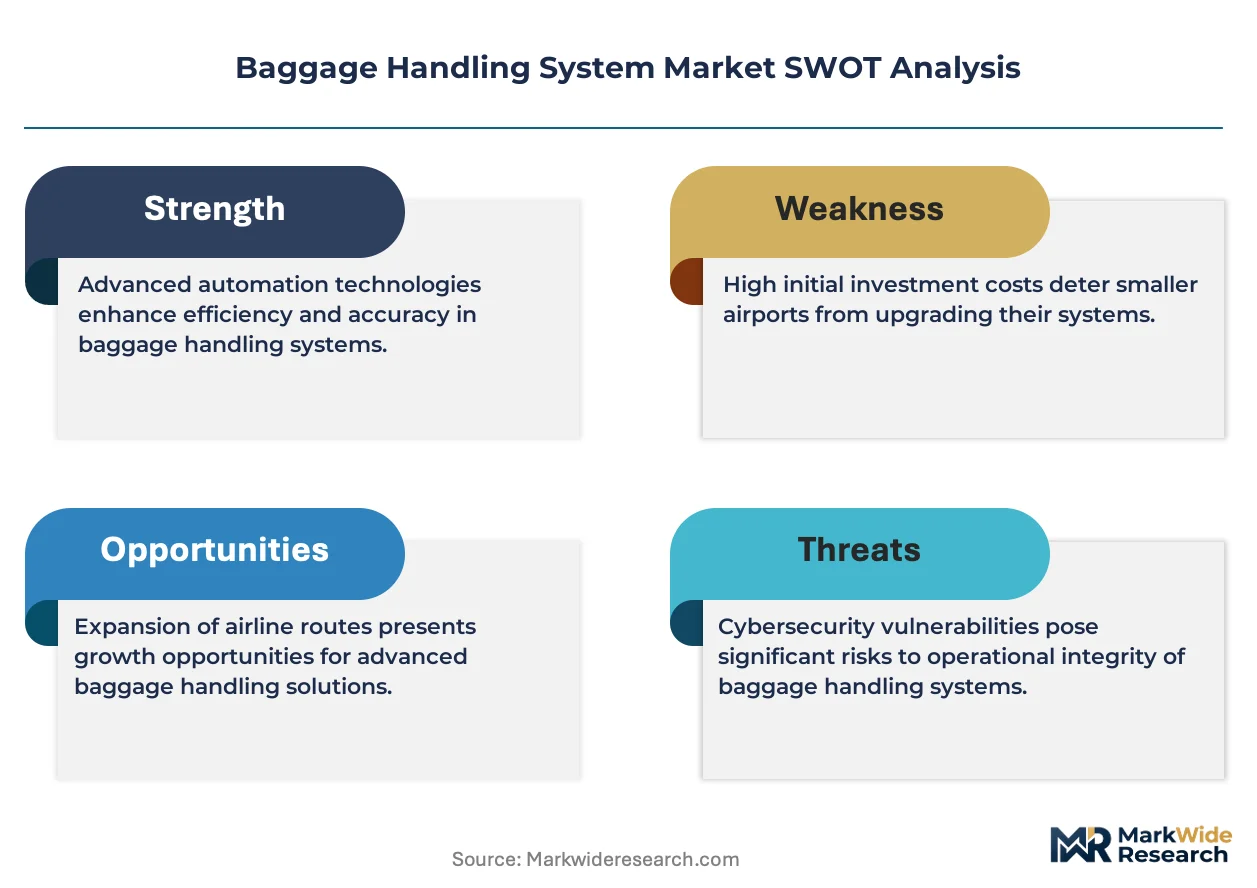
Airport operators are replacing legacy steel-framed conveyor infrastructure with aluminum-reinforced assemblies to cut foundation loads and accelerate retrofit timelines in constrained terminal footprints.
Growth Catalysts
- ICAO Carbon Targets:Binding emissions reduction frameworks for aviation are compelling hub airports to retrofit energy-intensive sortation equipment with regenerative drive systems and low-friction conveyor surfaces.
- China Greenfield Construction:Beijing Daxing and Chengdu Tianfu International Airport expansions are generating concentrated demand for integrated baggage handling infrastructure with native RFID tracking architecture.
- Explosives Detection Mandates:FAA regulations under 49 CFR require commercial airports to maintain certified screening throughput, forcing capacity upgrades at security checkpoints and injection points.
Market Restraints
- Aluminum Price Volatility:Structural framing material costs fluctuate with energy-intensive smelting economics, squeezing margins on fixed-price retrofit contracts.
- Captive Asian Supply:Sorter module production concentrates in Japan and Thailand, exposing non-Asian project timelines to shipping bottlenecks and customs processing delays.
- EU F-Gas Restrictions:Climate-controlled sorting environments face refrigerant phase-out requirements that complicate specification sheets for temperature-sensitive pharmaceutical baggage handling.
Strategic Opportunities
- India Airport Privatization:Greenfield terminals under the government's asset monetization program present first-mover opportunities for full-automation baggage systems without legacy retrofit constraints.
- Robotic Loading Convergence:Integration of autonomous mobile robots with existing conveyor backbones enables incremental automation in terminals where full replacement is capital-prohibitive.
- EU Green Deal Retrofit Incentives:Energy-efficiency subsidies for existing airport infrastructure are accelerating replacement cycles for pneumatic diverters and fixed-speed belt drives.
Industry Challenges
- Mechatronics Talent Scarcity:Maintenance of integrated drive controls and building management protocol interfaces requires specialized technicians that airport authorities struggle to retain.
- Multi-Certification Timelines:Divergent screening protocols enforced by Germany's KBA, France's national aviation authority, and Japan's civil aviation bureau fragment vendor qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baggage Handling System Market |
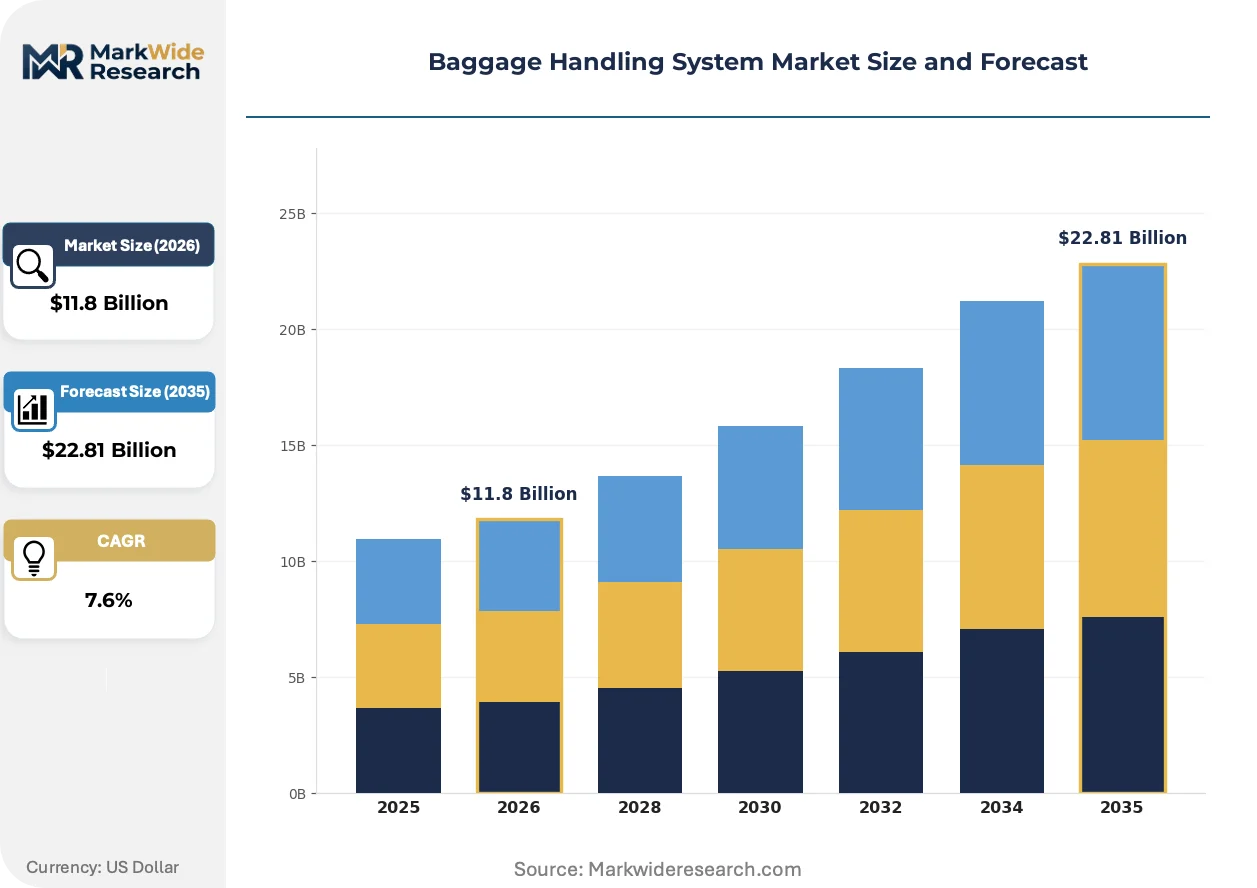
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Conveyor Systems, Tilt Tray Sorters, Crossbelt Sorters, Inline Screening Systems, Robotic Solutions Technology: Barcode Scanning, RFID, Vision Systems, Automated Guided Vehicles, IoT Monitoring Application: Airports, Railway Stations, Seaports, Courier Facilities, Parcel Distribution Centers End User: Airport Authorities, Logistics Providers, Parcel Operators, Security Agencies, Ground Handling Services |
| Companies Covered | Siemens AG, Fives Group, Vanderlande Industries B.V., Honeywell International Inc., Leonardo S.p.A, BEUMER Group, Alstef Group, JBT Corporation, Daifuku Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baggage Handling System Market Strategic Shifts & Innovations
Automation architectures are bifurcating between greenfield native-robotic installations and retrofit conveyor augmentation, with control software emerging as the primary value capture layer.
Autonomous mobile robots equipped with articulated manipulators are overtaking fixed conveyor spurs for last-meter aircraft loading operations. Low-cost carriers operating 24-hour turnarounds are piloting these systems at European hub airports. The technology is overtaking conventional belt-loader contracts by compressing ground handling labor requirements and enabling flexible gate assignments without dedicated infrastructure.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerants in climate-controlled baggage sorting environments. Equipment manufacturers must redesign thermal management systems using natural refrigerants or ambient cooling architectures. Pharmaceutical and perishable cargo handlers in Germany and France are absorbing specification complexity and extended lead times as vendors recertify product lines.
Airport authorities are unbundling after-sales service contracts from initial equipment procurement, creating standalone multi-vendor maintenance markets. Third-party technical service providers are displacing original manufacturer service divisions in the United States and United Kingdom. This shift is most visible at mid-scale airports where capital constraints favor operational expenditure models over comprehensive capital replacement cycles.
Baggage Handling System Market Segmentation
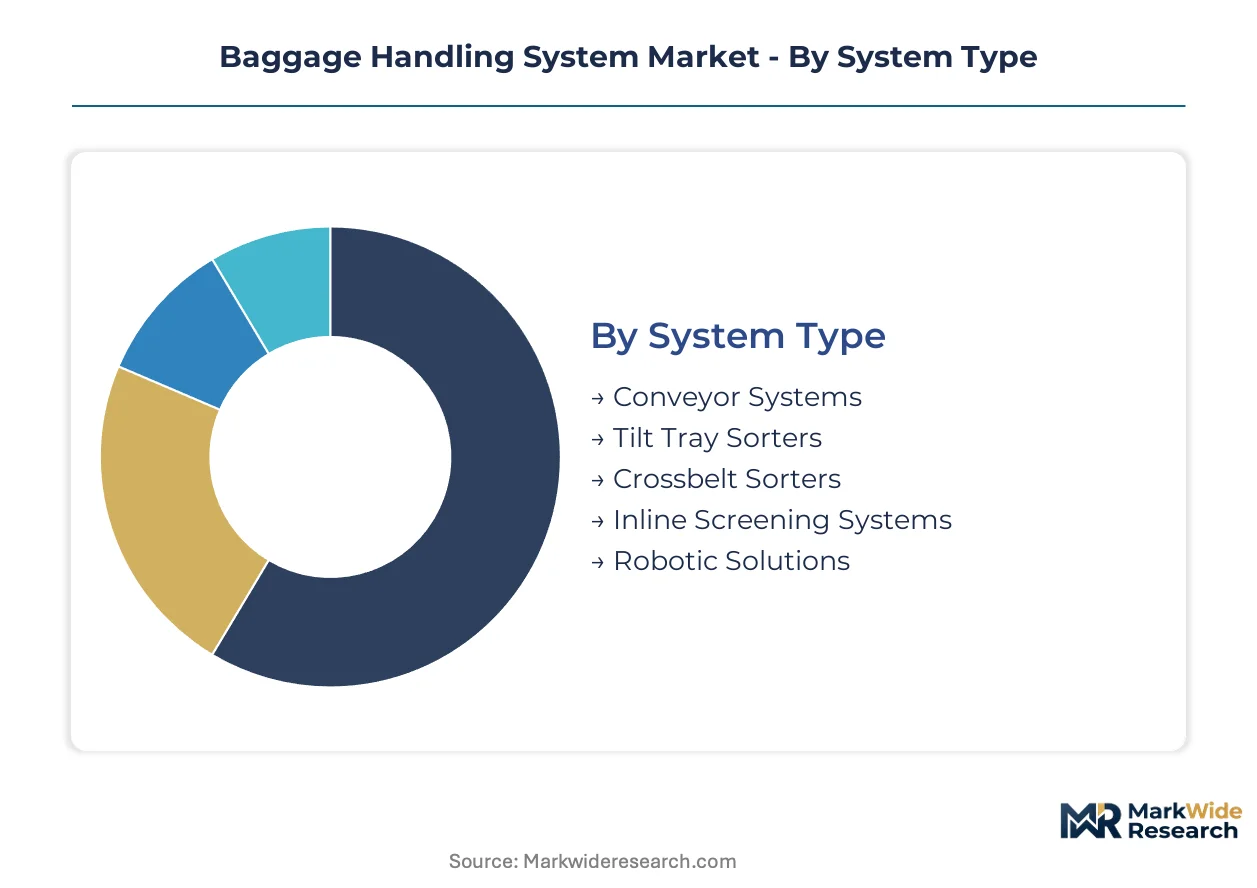
Baggage handling infrastructure segments by integration depth, with standalone conveyor networks dominating legacy retrofits while embedded robotics and vision systems penetrate greenfield installations. Procurement patterns diverge sharply between hub airports demanding native automation and regional facilities prioritizing modular augmentation.
System Type:
Integration depth varies from standalone mechanical assemblies to fully embedded robotic cells, with procurement decisions hinging on terminal footprint constraints and foundation load limits.
- Conveyor Systems:Belt and roller assemblies with aluminum-reinforced framing now displace legacy steel infrastructure in mid-scale retrofits, cutting installed weight by significant margins. Beijing Daxing and Chengdu Tianfu anchor concentrated demand for high-throughput configurations with regenerative drive compatibility.
- Robotic Solutions:Autonomous mobile robots with articulated manipulators compress ground handling labor for last-meter aircraft loading operations. European low-cost carriers pilot these systems for 24-hour turnarounds, bypassing fixed belt-loader infrastructure entirely.
- Tilt Tray Sorters:High-speed diverters process items at 1.5 to 3 meters per second with pneumatic actuation systems now facing EU F-Gas refrigerant restrictions in climate-controlled environments.
- Crossbelt Sorters:Continuous-loop configurations with individual carrier belts enable gentle handling of irregular luggage profiles common in international hub operations.
- Inline Screening Systems:Explosives detection apparatus mandated under FAA 49 CFR specifications, requiring certified throughput capacity at security injection points across US commercial airports.
Volume placements concentrate in Conveyor Systems; the faster expansion belongs to Robotic Solutions.
Technology:
Cost tier stratification separates legacy barcode infrastructure from premium RFID-native architectures, with retrofit budgets sustaining older protocols while greenfield projects bypass transitional generations entirely.
- RFID:Native tracking architecture with unique identifier tags enables real-time traceability without line-of-sight constraints. China greenfield terminals specify RFID as baseline requirement, displacing barcode-dominant legacy specifications.
- Barcode Scanning:Laser and camera-based readers sustain dominance in retrofit budgets where infrastructure write-down cycles delay full replacement. Mid-scale US and European terminals absorb this cost tier to preserve capital for security screening upgrades.
- Vision Systems:Camera arrays with machine learning classification for luggage dimensioning and damage detection, penetrating premium retrofit tiers at German and French hub airports.
- Automated Guided Vehicles:Magnetic and laser-guided transport for bulk baggage movement between check-in halls and sortation facilities, gaining share in expansive terminal footprints.
- IoT Monitoring:Sensor networks feeding predictive maintenance algorithms for drive motor vibration and belt tension anomalies, bundled with third-party service contracts at UK and US mid-scale airports.
Barcode Scanning retains the largest installed base; RFID climbs the fastest in new-build procurement.
Application:
Geographic deployment patterns cluster around passenger volume density, with aviation infrastructure commanding technology leadership while maritime and rail segments adapt proven airside configurations.
- Airports:Primary demand center encompassing check-in, sortation, screening, and aircraft loading operations with speeds of 1.5 to 3 meters per second. ICAO carbon targets and EU Green Deal subsidies accelerate energy-efficient equipment replacement cycles.
- Courier Facilities:Parcel and express handling operations with 24-hour throughput demands, importing baggage handling architectures for hub-and-spoke distribution networks.
- Railway Stations:Checked luggage services at high-speed terminals in China and Japan, adapting conveyor and screening technologies from aviation applications with modified throughput specifications.
- Seaports:Cruise terminal baggage handling with seasonal volume spikes, favoring modular conveyor configurations over fixed robotic infrastructure.
- Parcel Distribution Centers:E-commerce fulfillment networks adopting tilt tray and crossbelt sorter technologies originally developed for airport baggage applications.
Airports absorb the dominant share of capital deployment; Courier Facilities gain share fastest as e-commerce logistics converge with baggage handling architectures.
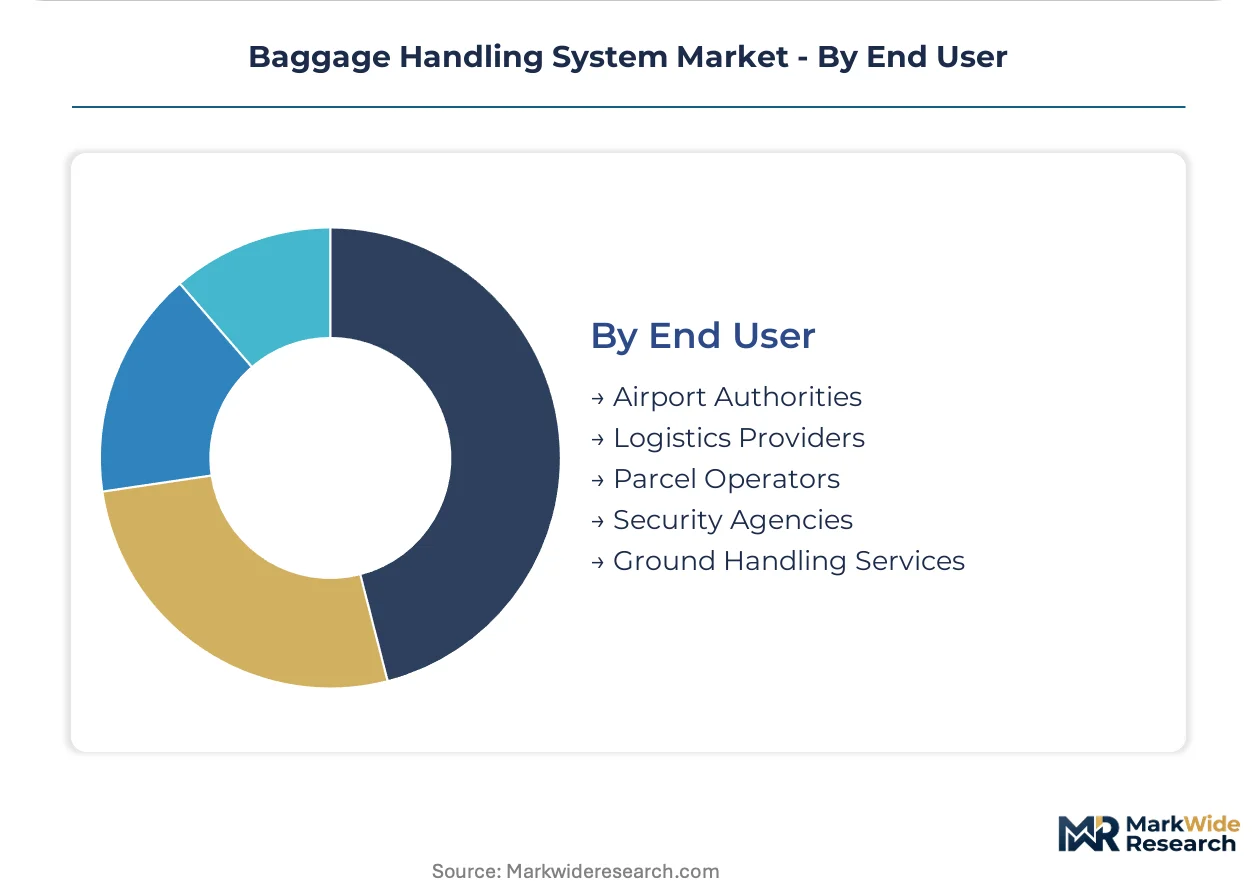
End User:
Customer type determines procurement authority structure, with airport authorities controlling greenfield specifications while ground handlers and logistics providers influence retrofit and service contract decisions.
- Airport Authorities:Capital project owners specifying integrated systems with native RFID and building management protocol integration. China's asset monetization program and India's privatization initiative concentrate procurement authority with these entities.
- Ground Handling Services:Labor-cost-sensitive operators piloting robotic loading systems to compress staffing requirements for 24-hour turnarounds at European hubs.
- Logistics Providers:Third-party integrators bundling baggage handling with broader supply chain services, favoring operational expenditure models over capital ownership.
- Parcel Operators:Express delivery networks specifying high-throughput sortation for hub facilities, cross-shopping baggage handling and parcel automation vendors.
- Security Agencies:Regulatory compliance drivers mandating explosives detection throughput standards under divergent national protocols from FAA, Germany's KBA, and Japan's civil aviation bureau.
Procurement volume concentrates with Airport Authorities; Ground Handling Services are expanding their technology influence fastest through operational leasing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of greenfield demand, with Beijing Daxing and Chengdu Tianfu International Airport expansions driving integrated baggage handling procurement. Germany and the United States anchor retrofit activity through regulatory mandates for explosives detection and energy efficiency. Japan, India, and France complete the five-country demand matrix with divergent infrastructure cycles.
China
Beijing Daxing and Chengdu Tianfu International Airport expansions generate concentrated demand for native RFID tracking architecture and high-throughput conveyor configurations. SAMR certification requirements and GB standards govern equipment specification sheets for domestic procurement. The Yangtze River Delta and Pearl River Delta clusters absorb the majority of greenfield automation deployment.
Germany
Frankfurt and Munich hub airports drive energy-efficient retrofit cycles under EU Green Deal subsidy frameworks. KBA screening protocols diverge from FAA specifications, fragmenting vendor certification requirements for explosives detection systems. Bavaria and North Rhine-Westphalia concentrate maintenance and upgrade activity for legacy pneumatic diverter replacement.
United States
FAA mandates under 49 CFR force certified screening throughput upgrades at security checkpoints across commercial airports. EPA energy efficiency guidelines intersect with airport authority capital planning for drive system replacement. The Southeast and Southwest regions show fastest retrofit velocity as Sun Belt passenger volumes recover.
Japan
Tokyo Haneda and Narita International Airport operators pilot autonomous mobile robots for last-meter aircraft loading operations. METI industrial automation incentives support ground handling service providers in compressing labor requirements for 24-hour turnarounds. The Kanto and Kansai regions concentrate both greenfield robotics trials and legacy tilt tray sorter maintenance.
India
Airport privatization under the government's asset monetization program creates first-mover opportunities for full-automation baggage systems without legacy constraints. BIS equipment standards and DGFT import regulations shape vendor qualification timelines. Maharashtra and Karnataka lead greenfield terminal development with Delhi-NCR following in procurement volume.
Baggage Handling System Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors seek to bridge certification gaps across divergent national aviation authorities. The vendor base stratifies into three tiers: diversified industrial conglomerates with factory automation heritage, specialized material handling firms with bulk-system expertise, and regional system integrators with captive Asian supply chains. Two archetypes command premium positioning: full-stack automation providers and screening-technology specialists. Competitive intensity centers on technology licensing arrangements and multi-vendor service contract unbundling.
Among diversified industrial conglomerates, Siemens AG and Honeywell International Inc. exemplify the full-stack automation archetype with integrated drive control and building management protocol capabilities. Daifuku Co., Ltd. occupies a distinct position within the captive supply chain tier, leveraging Japan and Thailand-based sorter module production. BEUMER Group sits within the bulk-material handling translation segment, applying heavy-industry conveyor expertise to high-throughput aviation applications. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning without requiring specific product or financial disclosure.
| Leading Market Players |
|---|
| Siemens AG |
| Fives Group |
| Vanderlande Industries B.V. |
| Honeywell International Inc. |
| Leonardo S.p.A |
| BEUMER Group |
| Alstef Group |
| JBT Corporation |
| Daifuku Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Aluminum ingot costs cascade through baggage handling system pricing tiers, with energy-intensive smelting economics in China and Russia feeding into structural framing quotations that separate premium retrofit contracts from economy-tier greenfield specifications. Mid-scale airport operators absorb spot-price volatility through fixed-price contract exposure, while hub authorities with captive procurement teams negotiate aluminum-linked escalation clauses.
Pricing Analysis
Volume placements concentrate in standard-tier conveyor retrofits where margins compress under aluminum price volatility; premium-tier robotic installations retain pricing power through embedded software value. Certification grade differentiates FAA-compliant screening systems from base-tier sortation equipment, with EU F-Gas refrigerant restrictions adding specification complexity to climate-controlled pharmaceutical handling tiers. Cost compression in standard-tier retrofits intensifies because fixed-price contracts expose integrators to structural material swings. Regional airport authorities exhibit highest price sensitivity, deferring full RFID replacement until barcode infrastructure reaches depreciation endpoints.
Supply Chain Analysis
Freight cost inflation from Japan and Thailand sorter module production centers squeezes project margins for non-Asian airport authorities, with container rates and customs processing delays extending lead times for tilt tray and crossbelt assemblies. Captive manufacturing in Japan, Thailand, and China anchors global supply, with drive control electronics drawing from German and US automation component sources. Single-source vulnerability concentrates in pneumatic diverter subassemblies, where EU F-Gas refrigerant phase-outs disrupt recertification timelines. Distribution runs through original equipment manufacturer direct sales for greenfield projects, while third-party service providers displace manufacturer divisions in US and UK aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baggage handling system market is becoming a vertical-integration race, with control software and captive sorter module production as the decisive upstream levers separating full-stack providers from assembly integrators.
For Market Incumbents: Lock in aluminum supply agreements and regenerative drive technology partnerships before spot-price volatility destabilizes retrofit contract profitability. Siemens AG and Honeywell International Inc. already embed building management protocol integration; late movers face certification fragmentation as Germany's KBA, France's national aviation authority, and Japan's civil aviation bureau diverge on screening standards. Backward integration into sorter module production insulates against Thailand shipping bottlenecks. For New Entrants and Emerging Players: The price-point gap between premium native-robotic installations and economy-tier barcode-retrofit specifications creates white-space for modular robotic augmentation systems. India's airport privatization program offers the most penetrable geography, with greenfield terminals lacking legacy conveyor constraints. A service-first go-to-market model—unbundling maintenance from equipment procurement—resonates with capital-constrained mid-scale airport authorities in the US Southeast and Southwest. For Investors and Strategic Acquirers: The unbundling of after-sales service contracts from initial equipment procurement is the leading indicator that recurring revenue multiples will separate valuation tiers across the analysis window. Long-term viability favors vendors with software-defined control architectures over hardware-assembly specialists. Acquisition targets should display captive Asian supply chain access or FAA explosives detection certification. Watch for EU Green Deal subsidy acceleration as the inflection signal for energy-efficient retrofit replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorter Module Production | Captive manufacturing in Japan and Thailand insulates project timelines from shipping bottlenecks and customs delays. |
| Control Software Platform Integration | Building management protocol interfaces differentiate Siemens AG and Honeywell International Inc. from hardware assemblers. |
| EU Green Deal Retrofit Certification | Energy-efficient equipment subsidies accelerate replacement cycles for pneumatic diverters and fixed-speed belt drives. |
| Multi-Vendor Service Contract Unbundling | Standalone maintenance markets emerge as US and UK mid-scale airports favor operational expenditure models. |
| RFID-Native Architecture Specification | China greenfield terminals specify baseline RFID tracking, displacing barcode-dominant legacy procurement. |
Research Approach
Document review covered ICAO security framework documentation, FAA 49 CFR regulatory filings, EU F-Gas Regulation implementation guidance, and national aviation authority certification requirements, complemented by interviews with airport authority capital project directors, ground handling service operations managers, baggage handling system integrator sales engineers, and third-party technical service provider executives. Secondary validation drew from customs trade data, SEC 10-K equipment disclosure filings, and SAMR GB standards publications. Bottom-up equipment procurement tracking and top-down aviation infrastructure investment flow analysis enabled triangulation.
Historical capacity deployment patterns were cross-referenced against panel input from airport planning consultants and OEM procurement teams to construct the projection framework. Segmentation dimensions modeled include system integration depth, tracking technology tier, application environment, and end-user procurement authority structure. CAGRs were derived from equipment shipment volumes and installed base replacement cycle analysis, with aluminum price index trajectories and ICAO carbon target compliance timelines as aviation-specific forecast inputs.
Inputs from airport authority procurement committees and ground handling operator maintenance records were available through the study window; gaps in real-time robotic loading pilot performance data introduce uncertainty bands around autonomous mobile robot adoption velocity. Forecasts reflect assumptions about EU subsidy continuity and China greenfield construction schedules. Stakeholders should weight assumptions against their own operating context and regional regulatory enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Control Towers Market