
 Sea Freight Forwarding Market | 2026-2036
Sea Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Freight Forwarding Market Analysis
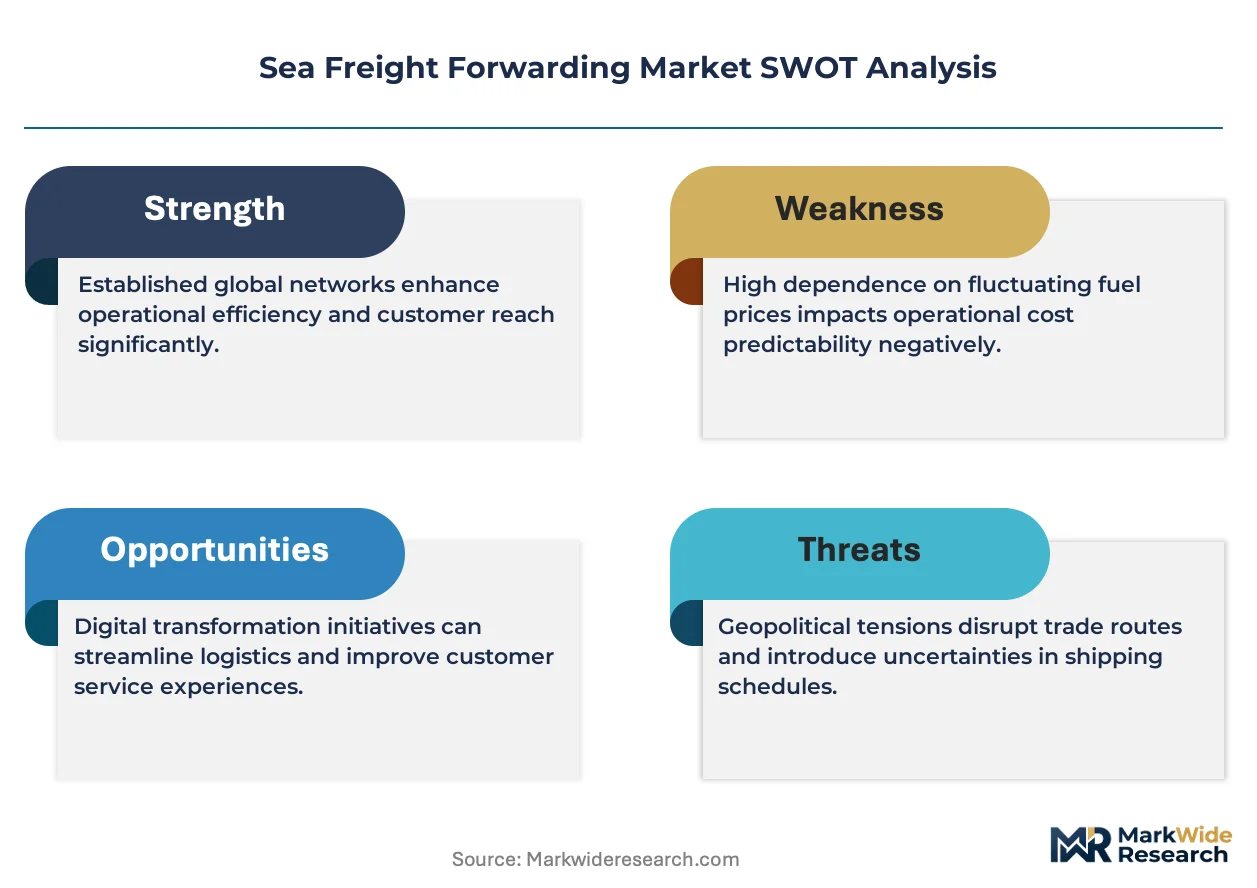
The capital-intensity divergence between asset-heavy carriers and asset-light forwarders is unwinding competitive dynamics across ocean logistics. Kuehne + Nagel leverages its non-vessel operating common carrier model to sustain margin flexibility without fleet ownership. DSV A/S anchors its expansion through integrated sea-air solutions that compete on transit-time reliability. Sinotrans Ltd. dominates intra-Asia volumes through port-centric warehousing networks that extend control over cargo handoffs.
Sea freight forwarding encompasses the coordination of cargo movement via ocean vessels, encompassing documentation, customs clearance, carrier negotiation, and cargo consolidation with vessel capacities ranging from 2,000 to 24,000 TEU depending on trade lane. The practice serves industrial and commercial supply chains by bridging production locations with consumption markets across maritime distances. FCL and LCL service types capture divergent margin structures, with full-container loads occupying stable contract revenue pools while less-than-container-load consolidation yields higher per-TEU yields through cargo mixing. Reefer forwarding represents the fastest-expanding service category as pharmaceutical and fresh-produce cold chains intensify temperature-controlled ocean requirements.
The International Maritime Organization enforces carbon intensity indicator metrics that reshape carrier fuel choices and forwarder routing decisions across regulated trade lanes. EU Green Deal emissions trading system inclusion for maritime transport from European ports elevates compliance costs on Asia-Europe corridors and redirects cargo toward lower-carbon vessel options. China's MEE implements domestic emission control area standards that constrain sulfur oxide outputs near major port clusters. Stakeholders must monitor regulatory fragmentation between IMO global mandates and regional carbon pricing mechanisms when structuring long-term carrier contracts and network investments.
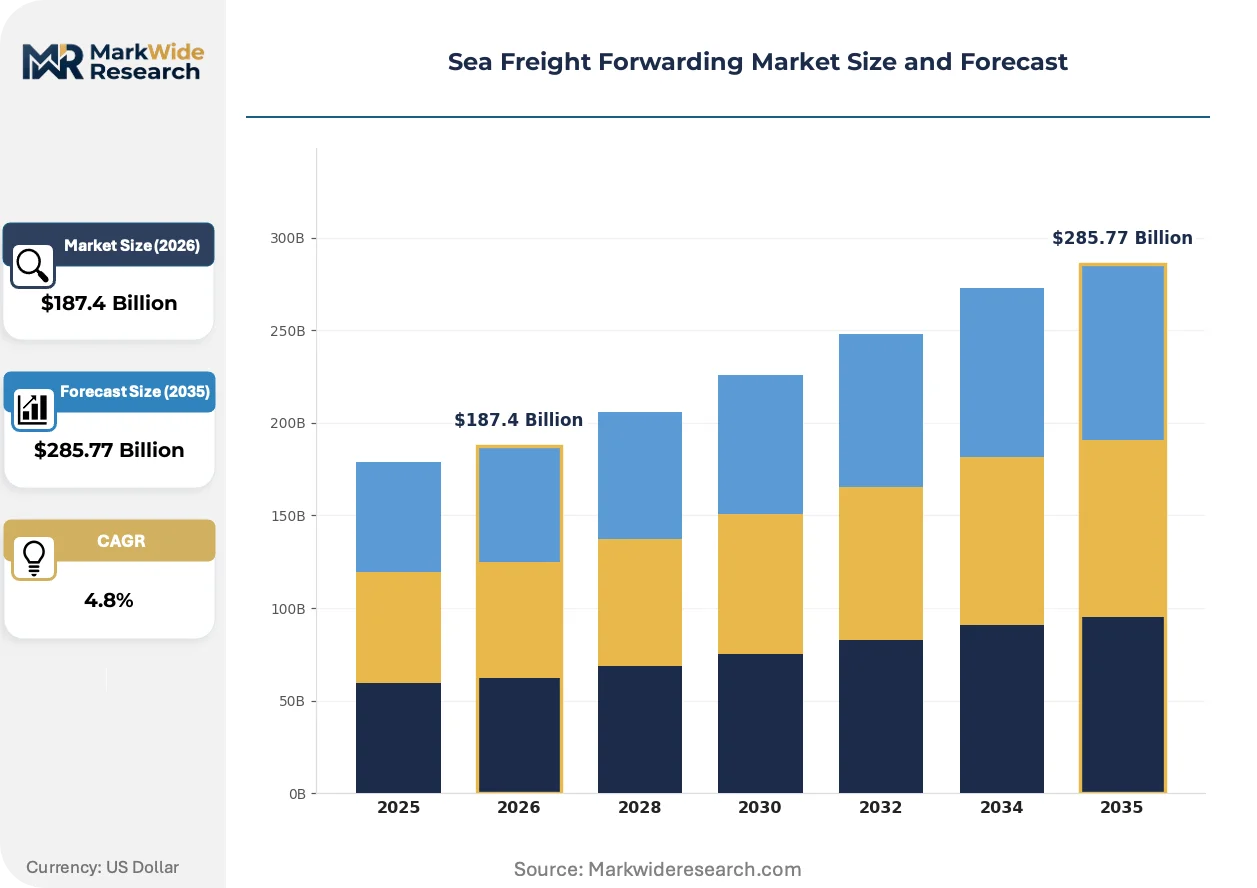
Market Dynamics
The IMO's carbon intensity indicator regulations are compressing carrier fleet economics and forcing forwarders to restructure long-haul routing decisions around fuel transition timelines and vessel age profiles.
Growth Catalysts
- Vietnamese electronics manufacturing:Component import volumes through Ho Chi Minh City and Hai Phong are expanding ocean freight bookings as contract manufacturers diversify beyond China.
- EU Green Deal maritime ETS inclusion:Carbon pricing on Asia-Europe corridors is accelerating demand for lower-emission vessel options and alternative fuel retrofits.
- Reefer container technology:Pharmaceutical cold chains and fresh-produce exporters are intensifying temperature-controlled ocean requirements across the Shanghai-Singapore corridor.
Market Restraints
- Bunker fuel price volatility:VLSFO and LNG price spreads are destabilizing carrier cost structures and contract rate negotiations on long-haul lanes.
- Port concentration risk:Shanghai, Singapore, and Rotterdam handle disproportionate transshipment volumes, creating systemic vulnerability to localized disruptions.
- Container manufacturing bottlenecks:Chinese and Korean producers dominate reefer and specialized box output, constraining fleet expansion for niche cargo categories.
Strategic Opportunities
- Intra-ASEAN manufacturing deepening:Indonesia, Thailand, and Vietnam are attracting component assembly investments that require new feeder network configurations.
- Digital freight platform convergence:Blockchain-based bill-of-lading systems and AI-powered cargo matching are compressing documentation friction and spot-market discovery costs.
- India's coastal shipping incentives:The country's Maritime India Vision targets modal shift from road and rail, opening breakbulk and project cargo forwarding potential.
Industry Challenges
- Decarbonization skill deficits:Forwarders lack personnel trained in alternative fuel certification, carbon accounting, and EU ETS compliance documentation.
- Legacy TMS integration friction:Carrier EDI protocols and port community systems resist real-time data exchange with modern freight management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Freight Forwarding Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: FCL, LCL, Dry Bulk, Reefer Delivery Model: Door-to-Door, Port-to-Port, Intermodal, Port-to-Door Customer Type: Manufacturers, Retailers, Importers, Exporters Packaging Type: Containerized, Palletized, Bulk, Fragile |
| Companies Covered | Sinotrans Ltd., Kuehne + Nagel, DHL Supply Chain & Global Forwarding, DSV A/S, Ceva Logistics, Nippon Express, DB Schenker, LX Pantos, Expeditors International of Washington, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Freight Forwarding Market Emerging Trajectories
Digital infrastructure and environmental compliance frameworks are simultaneously compressing operational margins and opening new service differentiation vectors across ocean logistics coordination.
Artificial intelligence-powered cargo forecasting is bifurcating forwarder competitive positioning. Predictive demand modeling enables Kuehne + Nagel and DSV A/S to pre-position container inventory at origin ports. Asset-light operators with superior data infrastructure are capturing margin from traditional carriers dependent on static annual contracts.
REACH chemical registration requirements and the EU Green Deal's maritime emissions trading system are elevating documentation complexity for Asia-Europe chemical and automotive shipments. Forwarders must now verify vessel carbon intensity ratings and fuel provenance alongside standard customs declarations. German and Dutch chemical exporters are prioritizing forwarders with integrated carbon accounting capabilities.
Shipper procurement patterns are compressing contract durations from annual to quarterly frameworks. Retail and consumer electronics buyers in the United States and Germany are demanding rate visibility tied to bunker adjustment factor transparency. Spot-market exposure is rising as volume commitments shorten, favoring forwarders with hybrid digital-physical service models over pure asset-heavy carriers.
Sea Freight Forwarding Market Segmentation
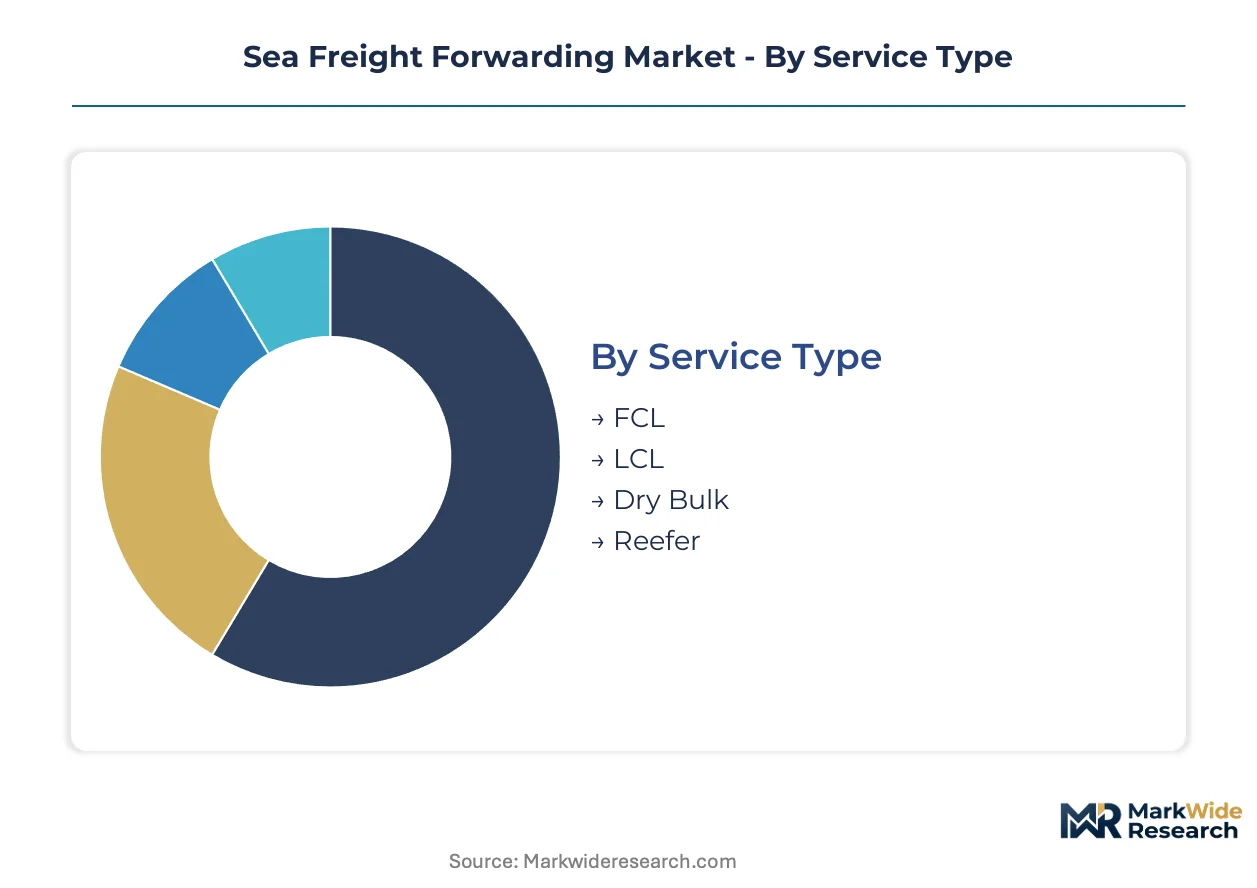
Segmentation in sea freight forwarding reveals how margin pools fragment across service configurations and customer workflows. Understanding these divisions exposes where forwarders capture premium yields versus commodity rate compression.
Service Type:
FCL commands the deepest margin pools through long-term contract structures, while reefer services extract premium per-TEU yields from temperature-sensitive cargo verticals.
- FCL:Full-container-load coordination locks shippers into dedicated vessel slots with stable annual rate frameworks. Automotive and electronics manufacturers in Vietnam favor FCL for component import reliability through Ho Chi Minh City and Hai Phong.
- Reefer:Refrigerated container forwarding maintains precise temperature protocols for pharmaceutical cold chains and fresh-produce exporters. Demand concentrates along the Shanghai-Singapore corridor as Southeast Asian agricultural and healthcare manufacturing deepens.
- LCL:Less-than-container-load consolidation mixes cargo from multiple shippers into shared vessel space.
- Dry Bulk:Unpacked commodity cargo coordination serves mineral and agricultural raw material flows.
The dominant share belongs to FCL, while reefer is closing the gap fastest.
Delivery Model:
Door-to-door configurations capture integrated margin stacks by controlling inland legs, whereas port-to-port remains vulnerable to carrier rate volatility.
- Door-to-Door:End-to-end coordination spans origin pickup, ocean transit, and final-mile delivery under single forwarder accountability. Retailers in Germany and the United States procurement teams demand this model for inventory visibility.
- Intermodal:Seamless rail-truck-vessel handoffs optimize transit time against pure ocean economics. India's Maritime India Vision coastal shipping incentives are expanding breakbulk intermodal configurations for project cargo.
- Port-to-Port:Terminal-to-terminal vessel space procurement leaves inland logistics to shipper arrangement.
- Port-to-Door:Ocean leg plus destination inland delivery splits responsibility at discharge port.
Door-to-door holds the revenue concentration, yet intermodal is gaining share fastest among sustainability-focused shippers.
Customer Type:
Manufacturers generate the most predictable volume commitments, while retailer procurement patterns are compressing contract durations toward quarterly frameworks.
- Manufacturers:Industrial production supply chains require synchronized component arrival for just-in-time assembly. Electronics contract manufacturers expanding in Vietnam are expanding ocean freight bookings for semiconductor and display panel imports.
- Retailers:Seasonal inventory replenishment drives spot-market exposure and demands bunker adjustment factor transparency. United States and German retail procurement teams now mandate rate visibility tied to fuel cost indices.
- Importers:Distribution-focused buyers prioritize customs clearance speed and duty optimization.
- Exporters:Origin-country shippers concentrate on cargo consolidation efficiency and documentation accuracy.
Manufacturers retain the volume leadership, though retailers are climbing the fastest as e-commerce fulfillment reshapes ocean procurement.
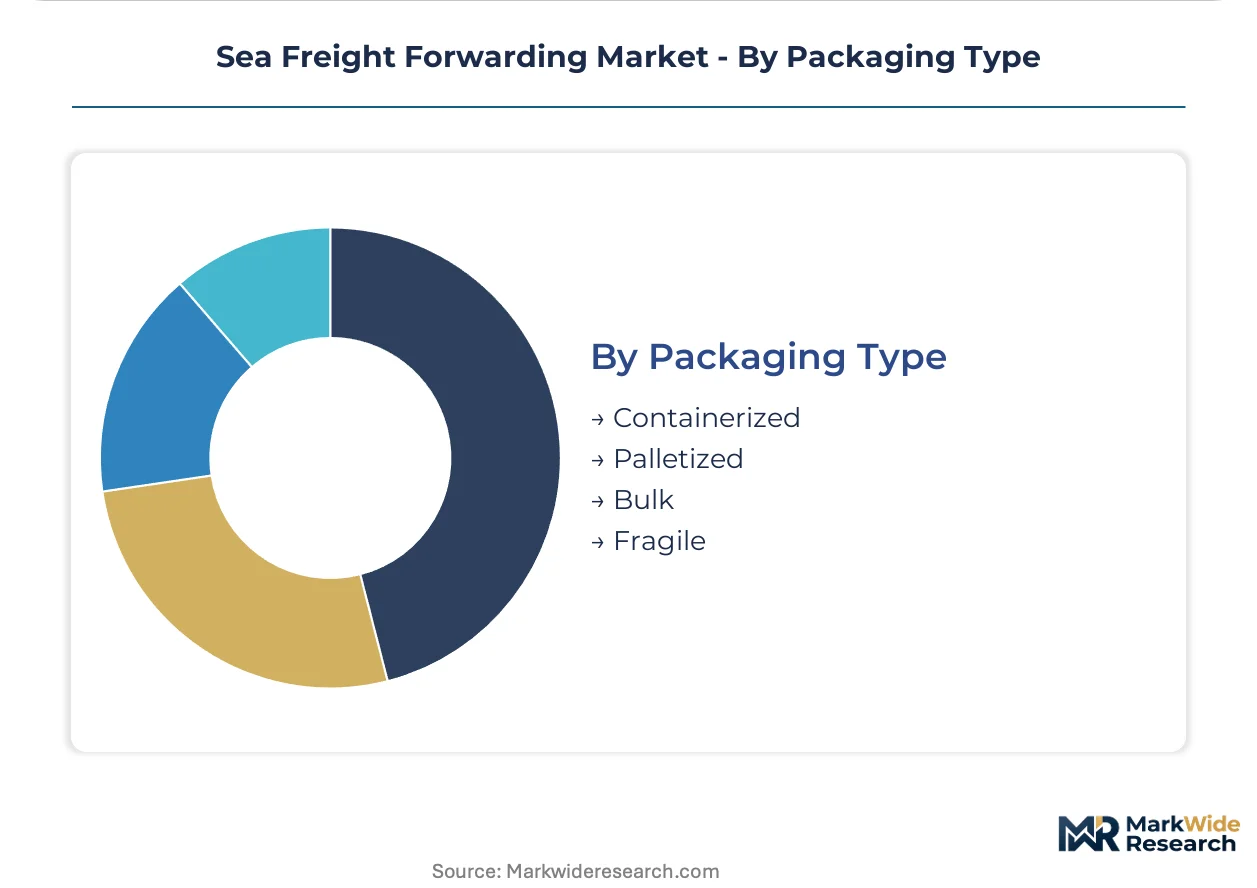
Packaging Type:
Containerized cargo dominates throughput scale, while fragile packaging commands premium handling fees from specialized forwarder capabilities.
- Containerized:Standard ISO box utilization maximizes vessel slot efficiency and enables intermodal rail-truck transfer. The Shanghai-Singapore corridor concentrates containerized volume as Southeast Asian manufacturing deepens.
- Fragile:Breakable goods demand customized stowage plans, dunnage materials, and shock-monitoring sensors. German and Dutch chemical exporters prioritize forwarders with integrated handling protocols for glass and precision equipment.
- Palletized:Unitized cargo loads simplify forklift handling at origin and destination terminals.
- Bulk:Unpacked homogeneous commodities flow through specialized vessel holds without container intermediation.
Containerized cargo maintains the throughput dominance, while fragile packaging is expanding most quickly among high-value manufacturing exports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight rate negotiation leverage concentrates in German and Dutch chemical export corridors, while Vietnamese electronics manufacturers absorb premium pricing for component import reliability through Ho Chi Minh City and Hai Phong.
China
Shanghai and Ningbo port clusters handle the densest transshipment volumes for intra-Asia manufacturing inputs. The MEE enforces domestic emission control area standards that constrain sulfur oxide outputs near major port clusters. Yangtze River Delta electronics exporters are consolidating FCL bookings through Sinotrans Ltd. port-centric warehousing networks.
Germany
Hamburg and Bremerhaven serve as the primary European gateways for automotive and chemical container flows. EU Green Deal emissions trading system inclusion for maritime transport elevates compliance costs on Asia-Europe corridors. Rhine-Ruhr industrial shippers now mandate forwarders with integrated carbon accounting capabilities for REACH chemical registration compliance.
Vietnam
Electronics contract manufacturers in Ho Chi Minh City and Hai Phong are expanding ocean freight bookings for semiconductor and display panel imports. The government implements Maritime Vietnam development programs targeting port capacity expansion and coastal shipping modal shift. Northern manufacturing zones near Hai Phong are attracting feeder network investments from regional forwarders.
Singapore
The city-state anchors the Shanghai-Singapore corridor as Southeast Asian manufacturing deepens and reefer container demand intensifies. The Maritime and Port Authority administers port dues incentives for vessels meeting low-carbon fuel standards. Jurong Island petrochemical exporters are prioritizing temperature-controlled ocean solutions for pharmaceutical cold chains.
United States
Los Angeles-Long Beach and Savannah port complexes absorb the largest Asia-Pacific import volumes for retail and consumer electronics distribution. Retail procurement teams mandate rate visibility tied to bunker adjustment factor transparency. Midwest manufacturing shippers are demanding quarterly contract frameworks rather than annual rate locks.
Sea Freight Forwarding Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across sea freight forwarding. Asset-heavy ocean carriers control vessel capacity and terminal access, while asset-light forwarders capture margin flexibility through data infrastructure and cargo consolidation expertise. Three strategic archetypes dominate: integrated logistics conglomerates with hybrid digital-physical service models, specialized NVOCC operators leveraging non-vessel operating common carrier structures, and regional port-centric networks controlling inland warehousing handoffs. Competitive moves concentrate on M&A-driven network expansion and AI-powered cargo forecasting platforms that compress spot-market discovery costs.
Within the asset-light NVOCC tier, Kuehne + Nagel and DSV A/S occupy positions defined by predictive demand modeling and sea-air solution integration. Kuehne + Nagel leverages its Swiss-heritage structure to sustain margin flexibility without fleet ownership obligations. DSV A/S anchors its Danish-rooted expansion through transit-time reliability competition against pure ocean alternatives. Sinotrans Ltd. represents the regional port-centric archetype, dominating intra-Asia volumes through Chinese state-linked warehousing networks that extend control over cargo handoffs at origin and destination clusters.
| Leading Market Players |
|---|
| Sinotrans Ltd. |
| Kuehne + Nagel |
| DHL Supply Chain & Global Forwarding |
| DSV A/S |
| Ceva Logistics |
| Nippon Express |
| DB Schenker |
| LX Pantos |
| Expeditors International of Washington |
| Others |
Supply Flow & Price Mechanics
IMO carbon intensity indicator certification gates both carrier qualification and forwarder price differentiation simultaneously. Shippers now pay premiums for verified low-carbon vessel slots while standard bookings face bunker adjustment factor volatility. This regulatory threshold simultaneously filters supply base access and stratifies service tiers across Asia-Europe corridors.
Pricing Analysis
Configured-to-order pricing for reefer and project cargo commands spreads over standard FCL rates. Contract-based long-term offtake structures dominate manufacturer procurement, though quarterly frameworks are displacing annual locks among retailers. Price differentiation rests on carbon intensity ratings and door-to-door integration depth. Retail procurement teams in the United States exhibit highest price sensitivity due to spot-market exposure, while pharmaceutical cold chain buyers absorb premium pricing for temperature integrity guarantees.
Supply Chain Analysis
Just-in-time inventory strategies dominate electronics and automotive supply chains, while strategic stockpiling persists for reefer equipment and specialized container assets. Manufacturing concentrates in China, Vietnam, and South Korea for component assembly and vessel production. Raw material dependencies span steel plate from Chinese mills, reefer machinery from Japanese and German suppliers, and marine coatings from European chemical producers. Single-source vulnerability concentrates in Chinese container manufacturing. Distribution runs through port-centric warehousing networks controlled by regional forwarders at Shanghai, Singapore, and Rotterdam clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across IMO mandates and regional carbon pricing is fragmenting service requirements, creating niche specialization opportunities for forwarders with compliance infrastructure.
For Market Incumbents: Fortify data infrastructure advantages against asset-heavy carrier digitalization pushes. Expand predictive cargo forecasting capabilities to defend margin position against platform-based entrants. Prioritize certification investment in EU ETS compliance documentation and alternative fuel verification protocols. Secure capacity addition in Vietnamese port clusters to capture electronics manufacturing diversification flows. For New Entrants and Emerging Players: Anchor in reefer forwarding specialization where temperature-controlled expertise barriers limit pure-platform competition. Target India's coastal shipping incentives under Maritime India Vision for breakbulk and project cargo white space. Pursue port-to-door configurations in underdeveloped feeder networks across Indonesia and Thailand. Build go-to-market angles around integrated carbon accounting for German and Dutch chemical exporters facing REACH complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light NVOCC segments as digital infrastructure substitutes for physical network scale. Long-term viability favors forwarders with hybrid digital-physical service models over pure technology platforms or legacy asset-heavy carriers. Acquisition target archetype: regional port-centric networks with established warehousing handoff control in Southeast Asian manufacturing corridors. Monitor EU ETS carbon price trajectories as inflection indicator for compliance service premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Cargo Forecasting Platform | Kuehne + Nagel and DSV A/S compress spot-market discovery costs through predictive demand modeling. |
| Reefer Fleet Expansion | Pharmaceutical cold chains and fresh-produce exporters intensify temperature-controlled ocean requirements. |
| EU ETS Compliance Infrastructure | German and Dutch chemical exporters prioritize forwarders with integrated carbon accounting capabilities. |
| Intra-ASEAN Feeder Network Buildout | Indonesia, Thailand, and Vietnam assembly investments demand new port-centric warehousing configurations. |
| Blockchain Bill-of-Lading Integration | Documentation friction compression enables margin capture from legacy paper-based forwarders. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across authoritative sources. Primary fieldwork engaged sea freight forwarding executives, carrier procurement leads, port operations managers, shipper supply chain directors, and regulatory compliance officers. Secondary sources encompassed IMO regulatory filings, EU ETS implementation documents, customs trade data, carrier financial disclosures, and port authority throughput statistics. Bottom-up volume triangulation against top-down market sizing anchored forecast integrity.
Across the analysis window, projections employed segmented modeling across service type, delivery model, customer category, and packaging configuration dimensions. CAGRs derived from historical trajectory analysis modified by regulatory inflection points and manufacturing relocation patterns. Industry-specific forecast inputs incorporated vessel orderbook data, bunker fuel price correlation models, and electronics manufacturing investment flows.
Material uncertainties — bunker fuel price volatility, port disruption events, and regulatory enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions about carbon pricing implementation timelines and alternative fuel adoption curves. Revision becomes warranted when EU ETS carbon price thresholds or IMO enforcement intensity crosses materiality bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Apparel Logistics Market