
 Automotive Crash Sensor Market | 2026-2036
Automotive Crash Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crash Sensor Market Outlook
Chinese sensor foundries is expanding MEMS wafer capacity to serve tier-one automotive module suppliers. Bosch Mobility Solutions leverages its Stuttgart engineering base to sustain integrated accelerometer-gyroscope portfolios for European OEMs. Continental AG anchors crash-sensor development through in-house MEMS fabrication and calibration labs in Germany and Romania. NXP Semiconductors N.V. competes on automotive radar co-packaging, combining 77 GHz front-ends with baseband processing for pre-crash detection.
Automotive crash sensors are transducer-based safety devices that detect rapid deceleration, collision force vectors, or structural pressure pulses and convert these physical inputs into electrical signals for airbag control units, typically operating within millisecond response windows to meet occupant-protection timing requirements. Accelerometer and pressure-sensor product types dominate volume shipments due to their integration into frontal and side-impact modules, while gyroscope adoption is accelerating for rollover-detection algorithms in sport-utility and commercial-vehicle platforms. Microelectromechanical Systems technology leads unit economics through silicon-batch fabrication, though radar-based crash-sensing architectures are displacing legacy infrared proximity methods in premium passenger-car segments.
NHTSA in the United States enforces Federal Motor Vehicle Safety Standard 208, which mandates airbag deployment performance and directly governs crash-sensor response thresholds for vehicles sold domestically. The EU's General Safety Regulation, administered through type-approval bodies aligned with UNECE frameworks, requires advanced emergency braking and intelligent speed assistance systems that expand sensor node counts per vehicle platform. Stakeholders must monitor how pending updates to FMVSS 214 side-impact protocols and the EU's evolving pedestrian-protection standards reshape sensor placement density and fusion-architecture requirements across vehicle programs.
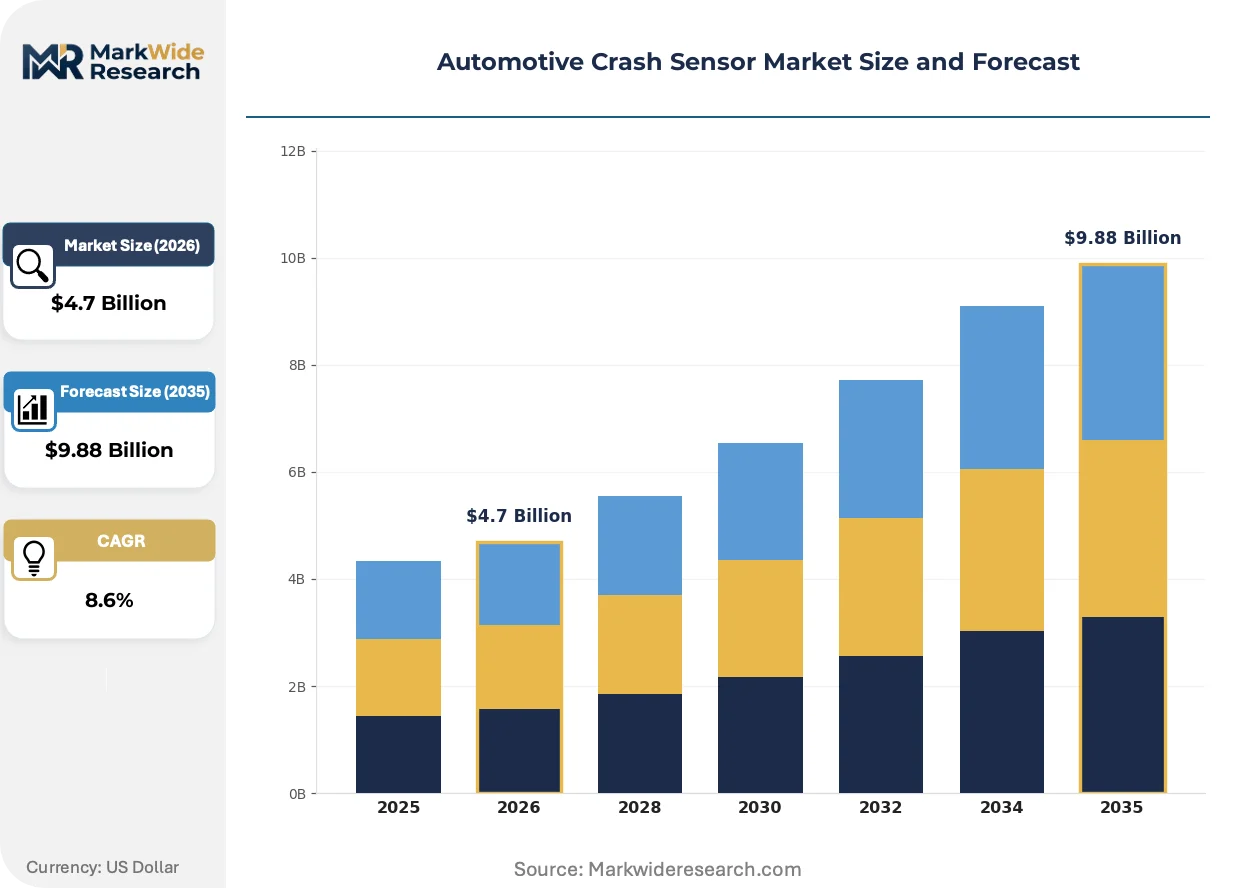
Market Dynamics
Multi-sensor fusion architectures are forcing tier-one suppliers to reconfigure module integration strategies around millisecond-latency requirements for occupant protection systems.
Growth Catalysts
- NHTSA FMVSS 208:Federal airbag deployment mandates in the United States enforce stricter response thresholds, compelling sensor node upgrades across domestic vehicle platforms.
- MEMS batch fabrication:Silicon-wafer economics at Chinese foundries compress unit costs for accelerometer-gyroscope combinations, enabling broader OEM adoption.
- Commercial-vehicle rollover detection:Gyroscope integration into sport-utility and heavy-truck platforms expands addressable sensor counts per vehicle.
Market Restraints
- MEMS wafer supply concentration:Foundry capacity bottlenecks in East Asia create single-source vulnerability for automotive-grade silicon.
- Radar front-end silicon costs:77 GHz compound-semiconductor substrates remain input-cost volatile, pressuring margins on pre-crash detection modules.
- UNECE type-approval fragmentation:Divergent certification timelines across EU member states delay platform homologation for integrated sensor systems.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Production-linked incentives attract module assembly investment, creating captive demand for localized sensor sourcing.
- Radar-lidar convergence:Co-packaging of 77 GHz radar with solid-state lidar emitters enables redundant object detection for autonomous emergency braking.
- Over-the-air calibration channels:Remote sensor recalibration via vehicle telematics reduces dealer-network dependency for post-collision system resets.
Industry Challenges
- Embedded firmware talent scarcity:Automotive functional-safety engineering to ISO 26262 standards faces qualified practitioner shortages in Western Europe.
- Legacy airbag ECU integration:Backward compatibility requirements with 1990s-era controller architectures complicate signal-protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crash Sensor Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometer, Pressure Sensor, Gyroscope, Impact Sensor End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Microelectromechanical Systems, Radar, Infrared, Ultrasonic Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Autonomous Vehicles |
| Companies Covered | ZF Friedrichshafen AG, Hyundai Mobis Co., Ltd., Bosch Mobility Solutions, Infineon Technologies AG, Joyson Safety Systems, Continental AG, Autoliv Inc., NXP Semiconductors N.V., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crash Sensor Market Strategic Shifts
Sensor fusion is compressing discrete component counts into unified detection modules, while regulatory latency requirements and procurement centralization reshape how tier-one suppliers compete.
Capacitive MEMS accelerometers are absorbing the high-g shock-detection function previously served by piezoelectric alternatives. European OEMs are adopting these devices for frontal-impact modules at accelerated qualification cycles. The technology is absorbing cost premiums through monolithic integration with temperature compensation circuits, compressing bill-of-materials complexity.
REACH substance restrictions on lead-based solders are forcing MEMS package redesigns across EU-bound sensor modules. Industrial consequence includes migration to gold-tin eutectic bonding processes and associated capital equipment retooling. Side-impact pressure sensors face the steepest compliance timeline, with suppliers accelerating validation programs ahead of 2025 enforcement windows.
Fleet operators are consolidating sensor procurement through direct tier-one contracts, bypassing traditional aftermarket distribution layers. Large rental and logistics buyers now specify performance warranties rather than unit-price negotiations, shifting supplier risk onto field-reliability metrics. This pattern concentrates most visibly in Germany's commercial-vehicle segment, where Daimler Truck and MAN Group exercise consolidated purchasing leverage.
Automotive Crash Sensor Market Segmentation
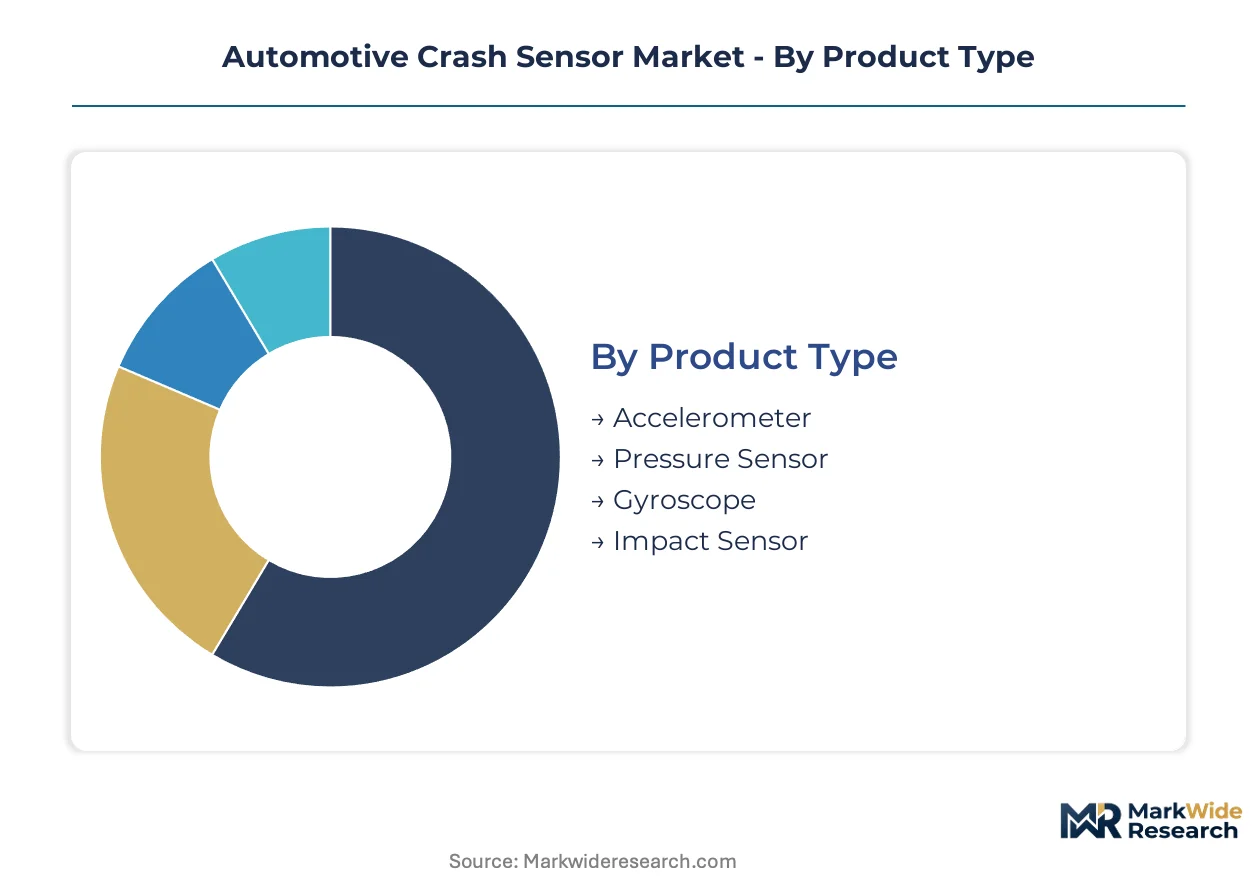
Crash sensor procurement splits across multiple technical and commercial dimensions. OEMs prioritize response latency and fusion compatibility when selecting product categories, while fleet operators weight field reliability and warranty terms more heavily.
Product Type:
Integration complexity with airbag control units drives tier-one supplier selection.
- Accelerometer:Capacitive MEMS devices detect high-g deceleration events through silicon proof-mass displacement. Frontal-impact modules in German passenger-car platforms absorb the majority of accelerometer shipments as NHTSA FMVSS 208 tightens deployment timing requirements.
- Pressure Sensor:Side-impact detection relies on structural pressure-pulse measurement through piezoresistive or capacitive transduction. Demand concentrates in EU type-approval programs where UNECE side-impact protocols mandate expanded sensor node density for occupant protection.
- Gyroscope:Angular rate sensors enable rollover-detection algorithms for SUV and commercial-vehicle platforms.
- Impact Sensor:Discrete mechanical switches provide redundant crash confirmation in legacy airbag architectures.
Volume sits with accelerometers; growth tilts toward gyroscopes.
End User:
Contract structure and specification authority reshape supplier engagement models.
- OEMs:Original equipment manufacturers hold design-in authority for multi-sensor fusion architectures and mandate ISO 26262 functional-safety compliance across module suppliers.
- Aftermarket Providers:Independent distributors serve collision-repair channels with replacement sensors calibrated to specific vehicle platform protocols.
- Vehicle Assemblers:Contract manufacturers integrate pre-certified sensor modules into final vehicle assembly lines under OEM-directed sourcing agreements.
- Fleet Operators:Large rental and logistics buyers now specify performance warranties and consolidated procurement terms, bypassing traditional distribution layers.
Procurement leverage concentrates with OEMs; fleet direct-contracting expands most quickly.
Technology:
Unit economics and detection range specifications determine architecture selection.
- Microelectromechanical Systems:Silicon-batch fabrication at Chinese foundries compresses unit costs for accelerometer-gyroscope combinations serving high-volume passenger-car programs.
- Radar:77 GHz front-end co-packaging with baseband processing enables pre-crash detection and autonomous emergency braking functionality in premium vehicle segments.
- Infrared:Legacy proximity-sensing methods face displacement by radar-lidar convergence in next-generation safety systems.
- Ultrasonic:Low-cost parking-assist applications retain ultrasonic architectures for near-field obstacle detection with limited crash-sensing relevance.
MEMS dominates unit shipments; radar claims the steepest expansion trajectory.
Application:
Platform weight, occupancy patterns, and regulatory exposure shape sensor configuration.
- Passenger Cars:Multi-point sensor arrays integrate frontal, side, and curtain airbag modules with millisecond-latency requirements for occupant protection.
- Commercial Vehicles:Heavy-truck and bus platforms require gyroscope-enabled rollover detection alongside standard impact sensing for driver and cargo safety.
- Two-Wheelers:Motorcycle airbag systems and advanced rider-assistance systems represent an emerging sensor application with distinct packaging and environmental robustness requirements.
- Autonomous Vehicles:Redundant crash-sensing architectures fuse radar, lidar, and inertial measurement units to support both occupant protection and collision-avoidance autonomy stacks.
Passenger cars anchor current volume; autonomous vehicle sensor counts per platform multiply fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon feedstock from Chinese foundries anchors automotive crash sensor fabrication across multiple geographies. MEMS wafer capacity expansion in East Asia supplies tier-one module suppliers in Germany, the United States, Japan, and South Korea. Regional demand patterns diverge between mature regulatory environments mandating faster response thresholds and emerging markets building assembly infrastructure.
United States
NHTSA's FMVSS 208 mandates stricter airbag deployment timing for domestic passenger-car platforms. Federal Motor Vehicle Safety Standard 214 updates are pending for side-impact protocols. Detroit-area engineering clusters coordinate with tier-one suppliers on multi-sensor fusion architectures for occupant protection systems.
Germany
EU General Safety Regulation through UNECE frameworks expands sensor node counts per vehicle for advanced emergency braking. REACH substance restrictions force MEMS package redesigns toward gold-tin eutectic bonding. Stuttgart and Ingolstadt anchor Bosch Mobility Solutions and Continental AG development clusters for integrated accelerometer-gyroscope portfolios.
China
Domestic OEM procurement of advanced driver-assistance systems intensifies multi-sensor fusion adoption. MIIT oversees national standards alignment with UNECE technical regulations for vehicle safety systems. Yangtze River Delta foundries expand MEMS wafer capacity to serve both local module suppliers and export markets.
Japan
METI coordinates industrial policy supporting autonomous emergency braking and intelligent speed assistance mandates. JIS standards govern automotive-grade sensor reliability specifications for domestic manufacturers. Kanto region engineering bases maintain close supplier relationships with tier-one module integrators serving Toyota and Honda platforms.
South Korea
Hyundai-Kia platform expansion drives gyroscope adoption for SUV rollover-detection algorithms. MFDS maintains separate pharmaceutical jurisdiction; automotive safety falls under KATRI type-approval procedures. Seoul Capital Area hosts Denso Corporation affiliate operations and domestic module assembly for export programs.
Automotive Crash Sensor Market Competitive Environment
Global majors compete with regional champions across technology licensing and module integration capabilities. The vendor base concentrates around three tiers: diversified automotive suppliers with captive semiconductor fabrication, specialized MEMS foundry services, and module integrators dependent on external sensor sourcing. Archetypes include full-stack system houses, silicon-batch specialists, and fusion-software layer developers. Capacity expansion and strategic partnerships dominate competitive moves as response-latency requirements tighten.
Among diversified European system houses, ZF Friedrichshafen AG and Continental AG occupy positions spanning sensor fabrication through module integration. Bosch Mobility Solutions exemplifies the vertically integrated archetype with Stuttgart-based engineering controlling accelerometer-gyroscope portfolio development. Infineon Technologies AG represents the semiconductor-specialist tier supplying MEMS die to tier-one module assemblers across multiple geographies.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hyundai Mobis Co., Ltd. |
| Bosch Mobility Solutions |
| Infineon Technologies AG |
| Joyson Safety Systems |
| Continental AG |
| Autoliv Inc. |
| NXP Semiconductors N.V. |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Fleet operators and consolidated OEM procurement offices command contract structures that bundle multi-year performance warranties with sensor module supply, compressing spot-market pricing leverage for tier-two suppliers. This buyer concentration forces tier-one module integrators toward value-based pricing that internalizes field-reliability risk rather than competing on unit cost alone.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering end-to-end calibration support from unbundled commodity vendors serving aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 26262 certification grade and volume commitment scale. Cost compression in standard-tier MEMS accelerometers is intensifying because Chinese foundry capacity expansion outpaces German module demand growth. Fleet operators exhibit highest price sensitivity, while autonomous vehicle programs prioritize detection latency over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle consolidated procurement from German and Japanese automakers, while aftermarket distributors serve collision-repair networks. MEMS wafer fabrication concentrates in China, Taiwan, and South Korea, with module assembly anchored in Germany, Romania, and Mexico. Raw material dependencies include silicon feedstock, gold-tin eutectic bonding alloys, and 77 GHz compound-semiconductor substrates. Single-source vulnerability in East Asian foundry capacity creates supply chain risk. Distribution runs through tier-one system houses rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around tier-one system houses with captive MEMS fabrication, as NHTSA latency requirements and REACH compliance timelines force sub-scale module vendors toward acquisition or exit.
For Market Incumbents: Anticipate radar-lidar convergence displacing discrete accelerometer-only architectures in premium passenger-car platforms. Deepen backward integration into 77 GHz front-end silicon through foundry partnerships in Taiwan or South Korea. Prioritize ISO 26262 functional-safety certification investment to defend against emerging MEMS specialists from China's Yangtze River Delta. For New Entrants and Emerging Players: Begin with India's PLI scheme for automotive electronics, where localized module assembly creates captive demand without direct competition from Bosch or Continental. Target two-wheeler advanced rider-assistance systems as the most penetrable application, given distinct packaging requirements that favor specialized entrants over incumbent passenger-car suppliers. Pursue direct fleet-operator contracting to bypass entrenched tier-one distribution layers. For Investors and Strategic Acquirers: The window for entry favors mid-cap MEMS foundry services with automotive-grade qualification pathways. Long-term viability rests on silicon-batch economics and regulatory compliance depth rather than software differentiation. Monitor NHTSA FMVSS 214 side-impact protocol finalization as the inflection signal for sensor node density expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Chinese Yangtze River Delta foundries are scaling wafer output to serve tier-one module suppliers in Germany and Japan. |
| Radar-Lidar Co-Packaging Development | 77 GHz radar front-end integration with solid-state lidar enables redundant pre-crash detection for autonomous emergency braking. |
| ISO 26262 Functional-Safety Certification | Automotive safety integrity level compliance separates qualified module suppliers from commodity aftermarket vendors. |
| Direct Fleet Procurement Contracts | Daimler Truck and MAN Group in Germany bypass traditional distribution through consolidated performance-warranty agreements. |
| Over-the-Air Calibration Infrastructure | Remote sensor recalibration via vehicle telematics reduces dealer-network dependency for post-collision system resets. |
Study Parameters
Regulatory filings from NHTSA and UNECE, automotive production databases, and tier-one supplier technical disclosures formed the secondary backbone of this analysis. Primary interviews with OEM platform engineers, Tier 1 procurement directors, MEMS foundry operations managers, and aftermarket distribution heads validated demand assumptions and response-latency requirements. Bottom-up and top-down triangulation cross-checked module shipment volumes against vehicle production data and sensor content-per-vehicle estimates.
Bottom-up modeling aggregated country-level vehicle production by platform type, applied sensor node counts per application, and projected technology mix shifts across the analysis window. Segmentation dimensions included product type, end-user contract structure, MEMS versus radar technology architecture, and vehicle class from passenger cars through commercial trucks. CAGRs derived from fitted growth curves incorporating regulatory mandate timelines and foundry capacity expansion schedules. Forecast inputs weighted NHTSA rulemaking pace and EU General Safety Regulation implementation phasing.
Underlying measurement precision varies by segment; passenger-car accelerometer volumes carry tighter precision than emerging two-wheeler applications. Forecasts reflect assumptions about regulatory enforcement timing, foundry yield rates, and OEM platform consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Radar Market