
 US Event Logistics Market | 2026-2036
US Event Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Event Logistics Market Insights
Driver availability for specialized freight is reorganizing capacity planning across the US event logistics sector. C.H. Robinson Worldwide, Inc. leverages its digital freight brokerage to match volatile event schedules with compliant carrier networks. United Parcel Service of America, Inc. sustains last-mile dominance through pre-positioned warehouse nodes near Las Vegas, Orlando, and Chicago convention corridors. XPO, Inc. competes on less-than-truckload flexibility, offering fractional trailer space for exhibitors with irregular booth hardware volumes.
US event logistics encompasses the planning, coordination, and physical movement of materials, equipment, and personnel required to stage temporary gatherings, with freight specifications ranging from climate-sensitive floral arrangements to modular stage systems exceeding dimensional regulations. The primary commercial purpose is time-definite delivery to non-recurring destinations lacking permanent material-handling infrastructure. Transportation commands the largest share of service-type revenue due to fuel and labor intensity, while equipment rental yields wider margins through asset reuse across multiple events in compressed seasonal windows. RFID tracking within the technology segment is displacing manual check-in for high-value audiovisual gear, reducing loss rates and accelerating strike-to-load turnaround times.
DOT enforces hours-of-service limits that constrain overnight hauls for touring productions, while OSHA standards govern temporary rigging and elevated load handling at venue sites. EPA Tier 4 emissions rules elevate fleet procurement costs for diesel tractors serving outdoor festival circuits. Stakeholders must monitor state-level permitting variance for oversize loads, as California, Texas, and New York maintain divergent escort vehicle and route-timing requirements that complicate national tour planning.
Market Dynamics
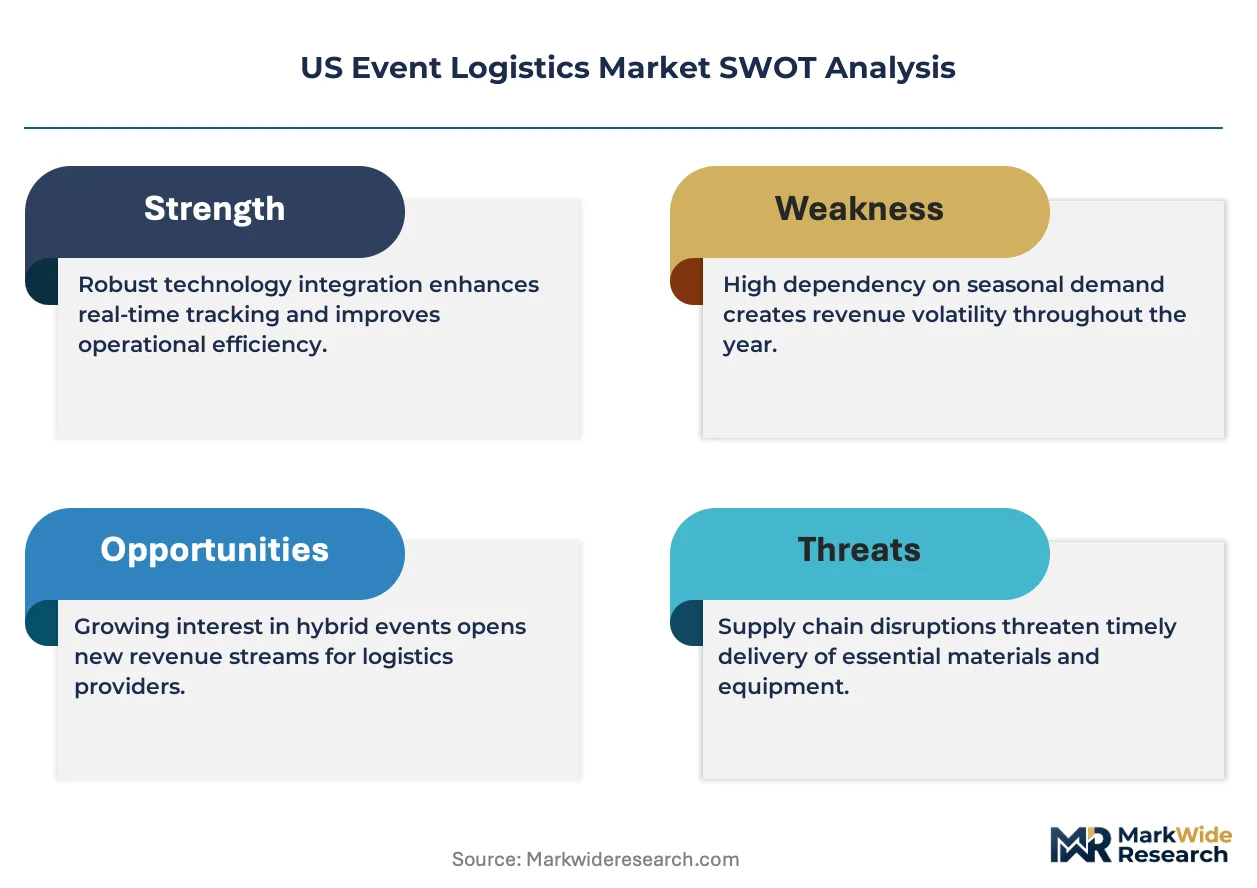
Hybrid event formats are fragmenting freight demand into smaller, more frequent shipments while tightening delivery windows, forcing logistics coordinators to rebuild capacity models around fractional loads rather than traditional full-truck staging.
Growth Catalysts
- Convention center expansions:Texas, California, and Florida are adding exhibition square footage that requires sustained equipment mobilization and freight services.
- EPA Tier 4 emissions standards:Fleet modernization mandates are accelerating replacement of older diesel tractors with compliant units capable of serving outdoor festival circuits.
- RFID tracking systems:Automated inventory management for high-value audiovisual equipment is reducing loss rates and compressing strike-to-load turnaround times at venue sites.
Market Restraints
- DOT hours-of-service limits:Overnight haul constraints for touring productions reduce driver utilization rates and extend transit schedules.
- Diesel fuel cost volatility:Transportation margins compress unpredictably as fuel represents the largest variable cost component in over-the-road event freight.
- State-level permitting variance:California, Texas, and New York maintain divergent escort vehicle and route-timing requirements that fragment national tour planning.
Strategic Opportunities
- Pre-positioned warehouse nodes:Secondary markets near Las Vegas, Orlando, and Chicago convention corridors offer last-mile density advantages for rapid deployment.
- Less-than-truckload fractional space:Exhibitors with irregular booth hardware volumes represent underserved demand for flexible trailer allocation.
- OSHA temporary rigging standards:Specialized elevated load handling certification creates premium service tiers for complex stage system installations.
Industry Challenges
- Commercial driver shortage:Specialized freight capacity for dimensional stage systems and climate-sensitive cargo faces recruitment gaps in key corridor states.
- Legacy manual check-in systems:Venue sites lacking RFID infrastructure create integration friction with automated tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Event Logistics Market |
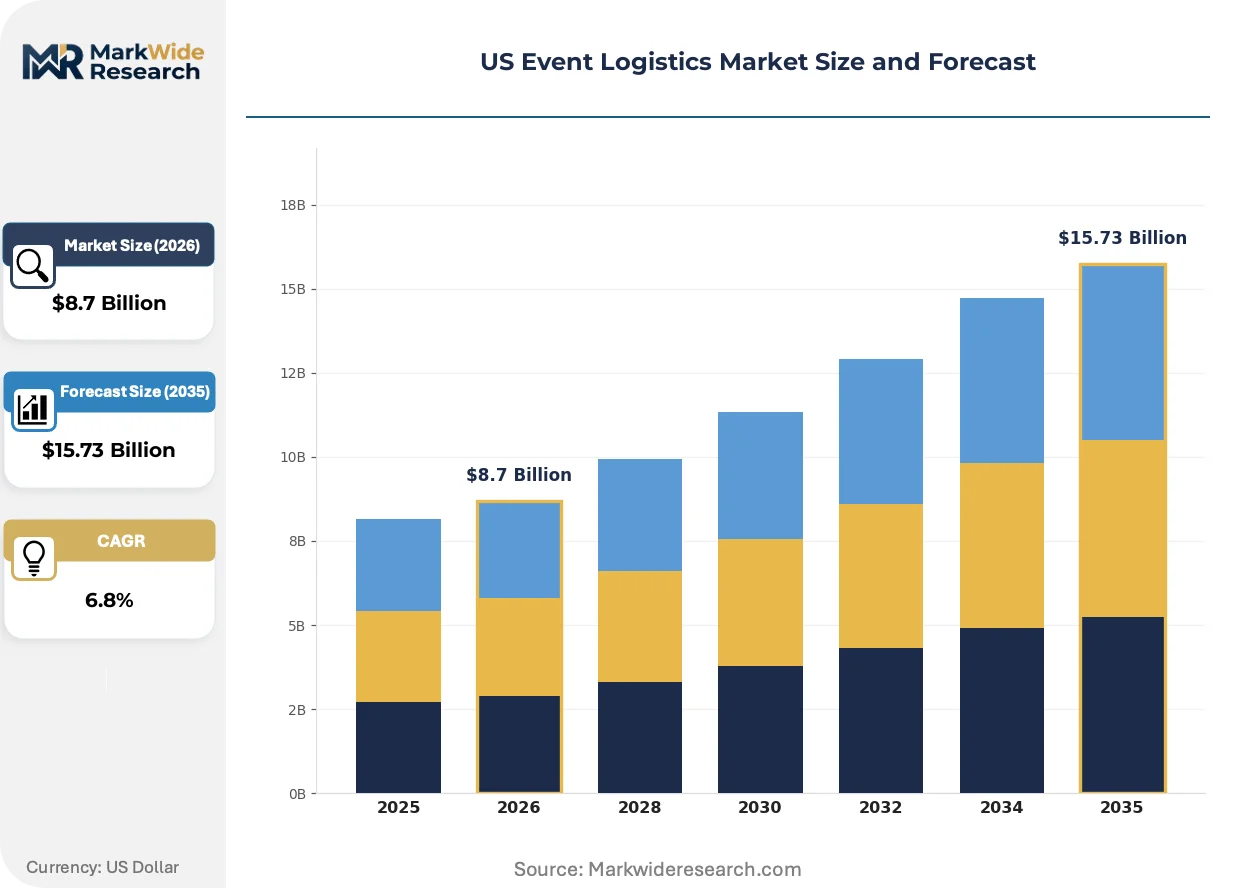
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Venue Management, Transportation, Equipment Rental, Staffing Industry Vertical: Corporate Events, Weddings, Trade Shows, Festivals Technology: Event Management Software, RFID Tracking, Virtual Platforms, Ticketing Solutions Customer Type: Event Organizers, Corporations, Non-Profits, Individual Clients |
| Companies Covered | Kuehne+Nagel, CEVA Logistics, DB Schenker, DHL Group, FedEx, United Parcel Service of America, Inc., C.H. Robinson Worldwide, Inc., XPO, Inc., Rhenus Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Event Logistics Market Trends and Innovations
Digital freight matching platforms are compressing the time between event schedule volatility and carrier allocation, while regulatory pressure on emissions and labor hours forces simultaneous investment in fleet technology and route optimization.
RFID-enabled asset tracking is bifurcating the equipment rental segment. Large audiovisual houses deploy item-level tracking for high-value gear across compressed seasonal windows. Smaller regional rental operators without capital for sensor infrastructure face margin compression from loss rates and slower inventory turns. The technology is bifurcating competitive position between capitalized national networks and underinvested local providers.
DOT hours-of-service enforcement is tightening compliance verification through electronic logging device mandates. Commercial carriers serving touring productions must restructure driver rotations around mandatory rest periods. The regulation most affects multi-city music and sports circuits operating on tight load-in schedules, forcing coordination with local shuttle networks to maintain staging timelines.
Experiential format proliferation is fragmenting buyer procurement patterns. Corporate event planners now source logistics through multiple specialized coordinators rather than single full-service vendors. The shift is most visible in technology sector conferences, where hybrid broadcast requirements demand simultaneous freight, streaming infrastructure, and on-site technical labor from distinct supplier networks.
US Event Logistics Market Segmentation
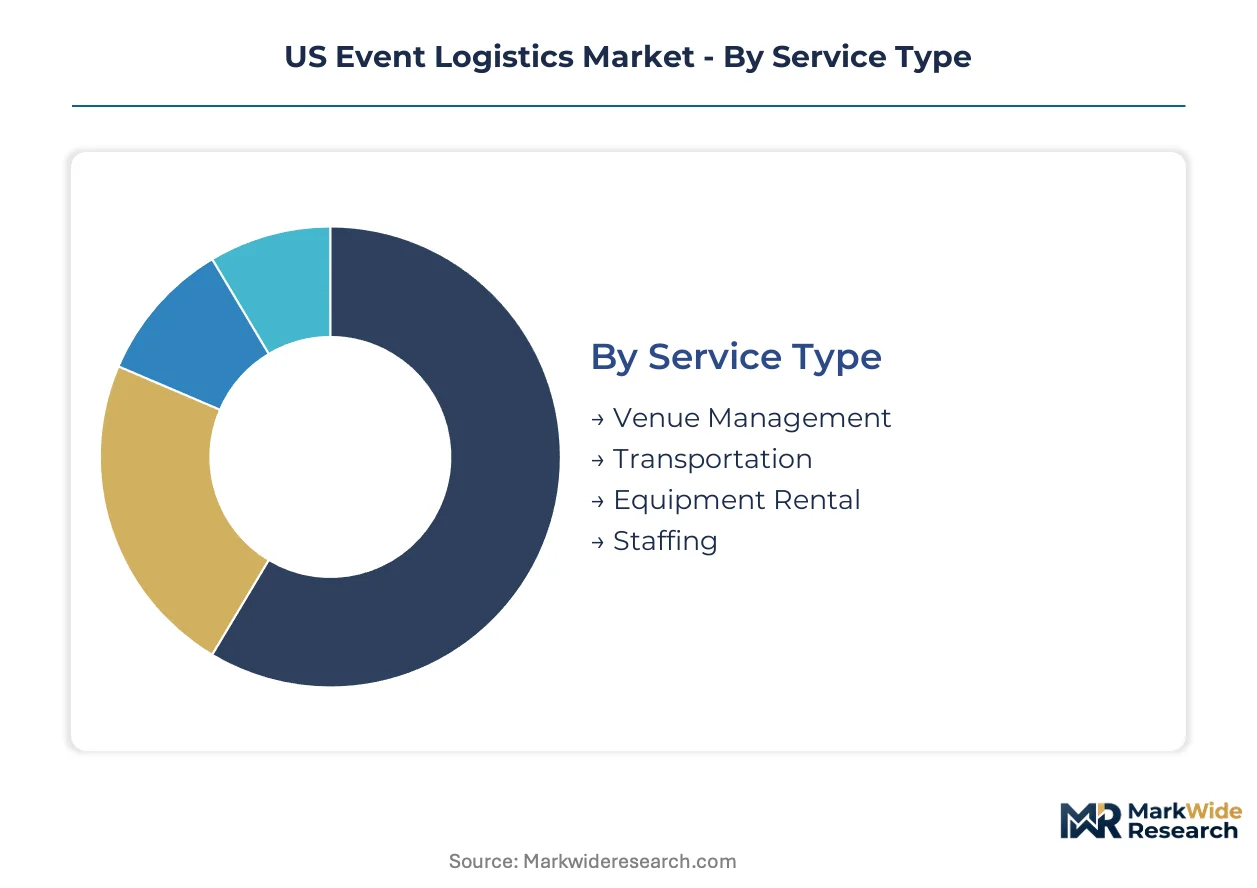
Segmentation in US event logistics reveals how service specialization and technology adoption fragment procurement patterns across temporary gathering formats. Each dimension exposes distinct capacity requirements, from climate-controlled freight lanes to RFID-enabled asset recovery systems.
Service Type:
Transportation faces the strongest substitution pressure as digital freight platforms enable direct shipper-carrier matching that bypasses traditional logistics coordinators.
- Transportation:Fuel and labor intensity dominate cost structures for over-the-road freight serving non-recurring destinations. Demand concentrates in Texas, California, and Florida corridor states where convention center expansions sustain equipment mobilization needs.
- Equipment Rental:Asset reuse across compressed seasonal windows generates wider margins than transport services. RFID tracking integration is reducing loss rates for high-value audiovisual gear at Las Vegas and Orlando venue clusters.
- Venue Management:Temporary rigging and elevated load handling governed by OSHA standards create premium certification tiers for complex stage installations.
- Staffing:Local shuttle networks compensate for DOT hours-of-service constraints on touring production driver rotations.
Transportation anchors the volume base while equipment rental gains share at the steepest rate.
Industry Vertical:
Cost tier stratification separates high-budget corporate programs from price-sensitive social gatherings with divergent logistics sophistication requirements.
- Corporate Events:Hybrid broadcast requirements demand simultaneous freight, streaming infrastructure, and on-site technical labor from distinct supplier networks. Procurement is shifting toward multiple specialized coordinators rather than single full-service vendors.
- Trade Shows:Modular booth hardware and dimensional stage systems require fractional trailer space allocation. Less-than-truckload flexibility serves irregular volumes from exhibitors with unpredictable freight patterns.
- Festivals:EPA Tier 4 emissions standards elevate fleet procurement costs for diesel tractors serving outdoor circuits with extended haul requirements.
- Weddings:Climate-sensitive floral arrangements and compressed setup windows drive demand for specialized refrigerated transport and rapid deployment capacity.
Corporate events dominate revenue contribution while trade shows expand most quickly through convention center square footage additions.
Technology:
Application maturity bifurcates between established inventory systems and emerging virtual infrastructure with unequal capital requirements.
- RFID Tracking:Item-level sensor deployment accelerates strike-to-load turnaround times at venue sites. Large audiovisual houses leverage capitalized national networks while smaller regional operators face margin compression from slower inventory turns.
- Event Management Software:Digital freight matching compresses schedule volatility response times for logistics coordinators managing volatile touring productions.
- Virtual Platforms:Hybrid format proliferation fragments freight demand into smaller, more frequent shipments with tightened delivery windows.
- Ticketing Solutions:Integration with access control systems streamlines personnel movement coordination at temporary gathering sites.
RFID tracking commands the deepest infrastructure investment while virtual platforms climb the fastest on hybrid event format adoption.
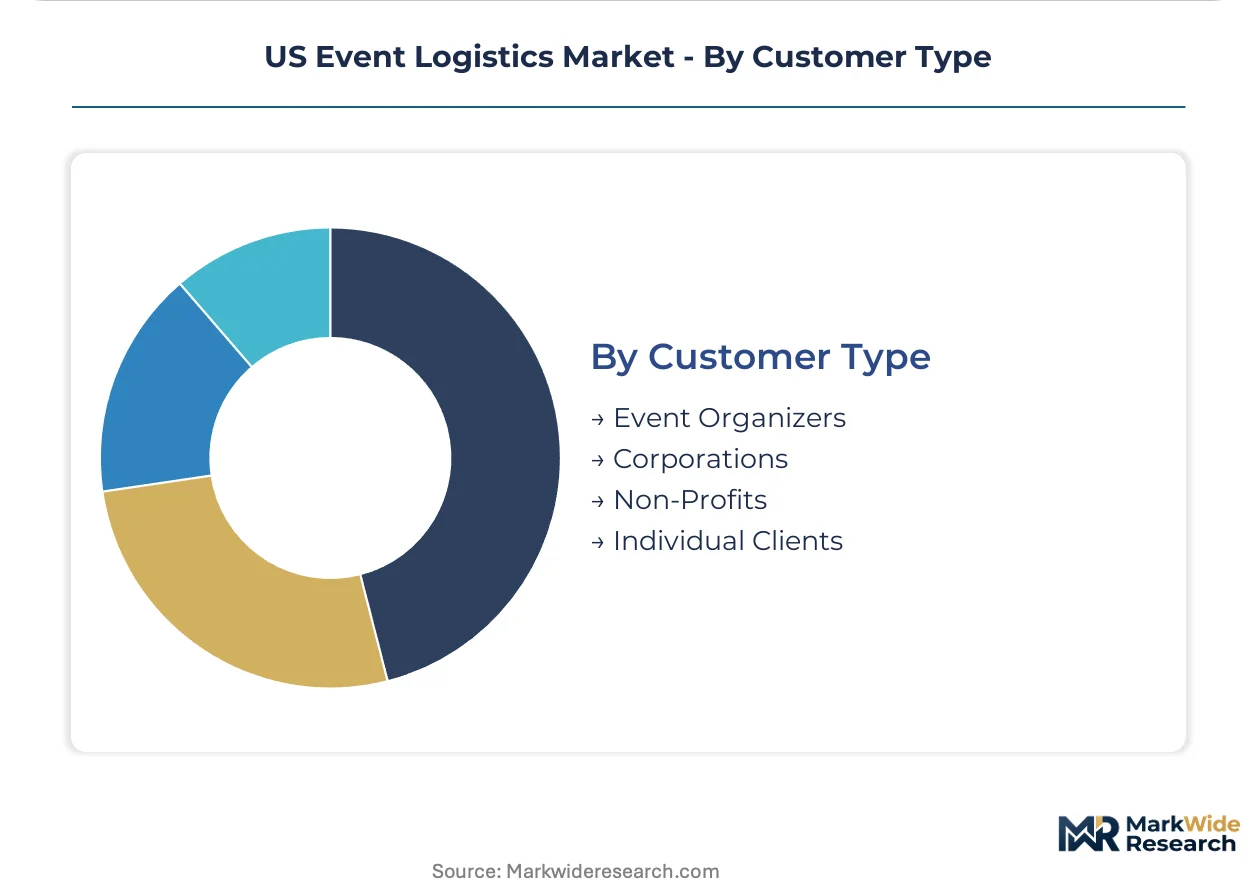
Customer Type:
Customer sophistication determines whether procurement flows through specialized coordinators or direct carrier relationships with divergent service level expectations.
- Corporations:Technology sector conferences drive simultaneous sourcing of freight, streaming infrastructure, and technical labor from distinct networks. Experiential format proliferation fragments legacy full-service vendor relationships.
- Event Organizers:Professional planners expanding reliance on third-party logistics coordinators as hybrid and experiential formats proliferate across multiple venue types.
- Non-Profits:Budget constraints favor shared freight consolidation and equipment rental pools across complementary event schedules.
- Individual Clients:Wedding and social gathering planners access last-mile density through pre-positioned warehouse nodes near major metropolitan corridors.
Corporations generate the highest per-event logistics expenditure while event organizers represent the broadest customer base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DOT hours-of-service regulations and EPA emissions standards anchor compliance requirements across the dominant US event logistics corridor. Texas, California, and Florida concentrate demand through convention center expansions and festival circuit density. State-level permitting variance fragments national tour planning.
Texas
Houston and Dallas convention center expansions sustain equipment mobilization needs for energy sector conferences. The Texas Department of Transportation enforces oversize load escort vehicle requirements that diverge from federal guidelines. Austin's festival circuit drives diesel tractor demand for outdoor productions facing EPA Tier 4 compliance costs.
California
Los Angeles and San Francisco technology conferences fragment procurement through simultaneous freight, streaming infrastructure, and technical labor sourcing. CARB emissions rules exceed federal EPA standards, elevating fleet procurement costs for compliant tractors. The Las Vegas-Orlando corridor anchors pre-positioned warehouse nodes for rapid deployment capacity.
Florida
Orlando's venue cluster and Miami's trade show calendar generate sustained freight demand for climate-sensitive cargo. Florida DOT maintains distinct route-timing requirements for oversize loads that complicate multi-state tour coordination. Tampa and Jacksonville convention expansions drive fractional trailer space allocation for irregular exhibitor volumes.
Illinois
Chicago's McCormick Place anchors Midwest equipment mobilization for trade shows and corporate events. Illinois Commerce Commission enforces commercial vehicle weight limits that constrain modular stage system transport. The city's pre-positioned warehouse infrastructure supports last-mile density for rapid deployment to secondary markets.
New York
New York Metro's experiential format proliferation drives demand for specialized elevated load handling certification. NYSDOT escort vehicle requirements diverge from neighboring states, fragmenting national tour planning for touring productions. Javits Center expansions sustain RFID-enabled equipment rental demand for high-value audiovisual gear.
US Event Logistics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US event logistics sector. Digital freight brokerage platforms consolidate schedule volatility management while asset-heavy carriers dominate last-mile density. Three archetypes define competitive positioning: integrated parcel networks, specialized freight brokers, and fractional capacity providers. M&A activity concentrates among digital platform operators while regional carriers pursue strategic partnerships for national coverage.
Within the integrated network tier, United Parcel Service of America, Inc. and FedEx exemplify scale-driven last-mile dominance through pre-positioned infrastructure. C.H. Robinson Worldwide, Inc. occupies the digital brokerage archetype, matching volatile event schedules with compliant carrier networks. XPO, Inc. represents fractional capacity specialization, serving exhibitors with irregular booth hardware volumes through less-than-truckload flexibility. These three anchors illustrate how technology investment, asset ownership, and service modularity divide competitive position in event logistics coordination.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| CEVA Logistics |
| DB Schenker |
| DHL Group |
| FedEx |
| United Parcel Service of America, Inc. |
| C.H. Robinson Worldwide, Inc. |
| XPO, Inc. |
| Rhenus Group |
| Others |
Pricing and Supply Chain Analysis
Fleet utilization rates above eighty percent in Texas corridor states compress marginal costs for asset-heavy carriers while elevating price floors for specialized freight serving non-recurring destinations. This scale concentration rewards pre-positioned warehouse infrastructure near Las Vegas, Orlando, and Chicago convention clusters, locking in last-mile density advantages that smaller coordinators cannot replicate without capital deployment.
Pricing Analysis
California-to-Texas freight spreads widen during compressed festival seasons as EPA Tier 4 compliance costs concentrate among diesel tractor operators serving outdoor circuits. Project-based pricing dominates transportation services, with fuel surcharges and driver availability premiums differentiating quotes across DOT-regulated corridors. Price differentiation rests on certification tiers for OSHA temporary rigging compliance and RFID-enabled asset tracking integration. Margins are tightening due to diesel fuel cost volatility and commercial driver recruitment gaps in key corridor states. Non-profit event organizers exhibit highest price sensitivity through shared freight consolidation demands, while technology sector corporate clients prioritize time-definite delivery over rate minimization.
Supply Chain Analysis
Inbound logistics costs for modular stage systems and audiovisual gear hinge on container availability at Los Angeles and Houston ports serving exhibition hardware imports. Domestic manufacturing concentrates in Indiana, Ohio, and Tennessee for modular booth components and rigging equipment. Raw material dependencies include aluminum extrusions for stage framing, LED panel assemblies for display systems, and specialized textiles for scenic elements. Tariff exposure on Chinese-manufactured LED components creates single-source vulnerability for rental houses without diversified supplier networks. Distribution runs through fractional trailer allocation networks coordinated by digital freight platforms, with final-mile deployment from pre-positioned nodes near venue clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network effects from carrier relationship density and regulatory compliance databases create defensive moats for established coordinators. Switching costs escalate as corporate clients embed specialized logistics coordinators into multi-year event programming workflows.
For Market Incumbents: Consolidate carrier relationship density through exclusive capacity agreements with DOT-compliant fleets serving Texas, California, and Florida corridors. Acquire RFID infrastructure capabilities to capture equipment rental margin expansion from smaller regional operators facing loss-rate compression. Vertical integration into temporary staffing pools addresses driver shortage risks while creating premium OSHA certification tiers.
For New Entrants and Emerging Players: Fractional trailer space allocation for trade show exhibitors with irregular booth hardware volumes represents the most penetrable service gap. Target secondary market warehouse positioning near emerging convention center expansions in Tampa and Jacksonville where incumbent pre-positioning remains thin. Deploy digital freight matching platforms with faster schedule volatility response times than legacy coordinator networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment rental operators with RFID-enabled asset tracking and compressed seasonal window utilization. Long-term viability favors asset-light digital brokerage models over capital-intensive fleet ownership given EPA Tier 4 procurement cost trajectories. Acquisition target archetype: regional coordinators with dense carrier relationships in single corridor states. Monitor DOT hours-of-service enforcement tightening as inflection signal for shuttle network dependency expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Node Expansion | Pre-positioned capacity near Orlando and Las Vegas corridors captures last-mile density premiums. |
| RFID Infrastructure Deployment | Item-level tracking reduces audiovisual gear loss rates and accelerates strike-to-load turnaround. |
| OSHA Certification Investment | Temporary rigging compliance creates premium service tiers for complex stage system installations. |
| Carrier Network Consolidation | Exclusive DOT-compliant fleet agreements lock in capacity during compressed festival seasons. |
| Digital Freight Platform Integration | Schedule volatility matching compresses response times for hybrid event format fragmentation. |
Research Methodology
Desk research of trade association filings, DOT regulatory databases, and convention center development records preceded structured interviews with corporate event planners, third-party logistics coordinators, commercial fleet operators, and venue management executives. Primary fieldwork combined telephone and video interviews with secondary validation against EPA emissions compliance filings and state-level permitting variance documentation. Bottom-up equipment rental utilization rates and top-down transportation revenue estimates were triangulated against corridor-specific freight volume indicators.
Variance decomposition across service type, industry vertical, technology adoption, and customer sophistication dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic freight demand indicators. Modeled inputs included DOT hours-of-service constraint scenarios, EPA Tier 4 fleet replacement timelines, and RFID tracking penetration curves across audiovisual rental houses.
Forecasts assume regulatory continuity in DOT hours-of-service enforcement and EPA emissions standards; material policy shifts would require re-modeling of driver utilization assumptions and fleet procurement cost trajectories. Diesel fuel price volatility and commercial driver shortage severity represent specific risk factors that could compress transportation margins or extend transit schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market