
 Indonesia Freight and Logistics Market | 2026-2036
Indonesia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Freight and Logistics Market Outlook
Last-mile delivery revenue is rewriting profit pool distribution across Indonesian logistics networks. J&T Express leverages its parcel-sorting automation to dominate e-commerce fulfillment in Greater Jakarta. DHL Group sustains premium air freight corridors linking Surabaya and Medan to intra-Asian trade lanes. Kuehne+Nagel anchors pharmaceutical cold-chain logistics through temperature-controlled warehouse investments in East Java.
Indonesia freight and logistics encompasses the multimodal movement of goods across archipelagic territory spanning 17,000 islands, requiring inter-island ferry integration, container transshipment, and bonded zone coordination with minimum 20-foot equivalent unit handling capacity at major ports. Road freight commands volume leadership due to Java's highway network density, while sea freight carries bulk commodity flows between Kalimantan resource terminals and Java industrial centers. Warehouse management technology adoption accelerates among third-party logistics providers serving Jakarta's consumer goods distribution cluster.
BIS logistics standards, Indonesian Ministry of Transportation port modernization mandates, and ASEAN Single Window customs protocols shape equipment specifications, cross-border documentation requirements, and terminal automation timelines. The national shipping regulator enforces cabotage rules that reserve domestic cargo carriage for Indonesian-flagged vessels, constraining foreign fleet participation. Stakeholders must monitor toll-road concession expansions and emerging industrial zone locations to align capacity investments with demand migration patterns.
Market Dynamics
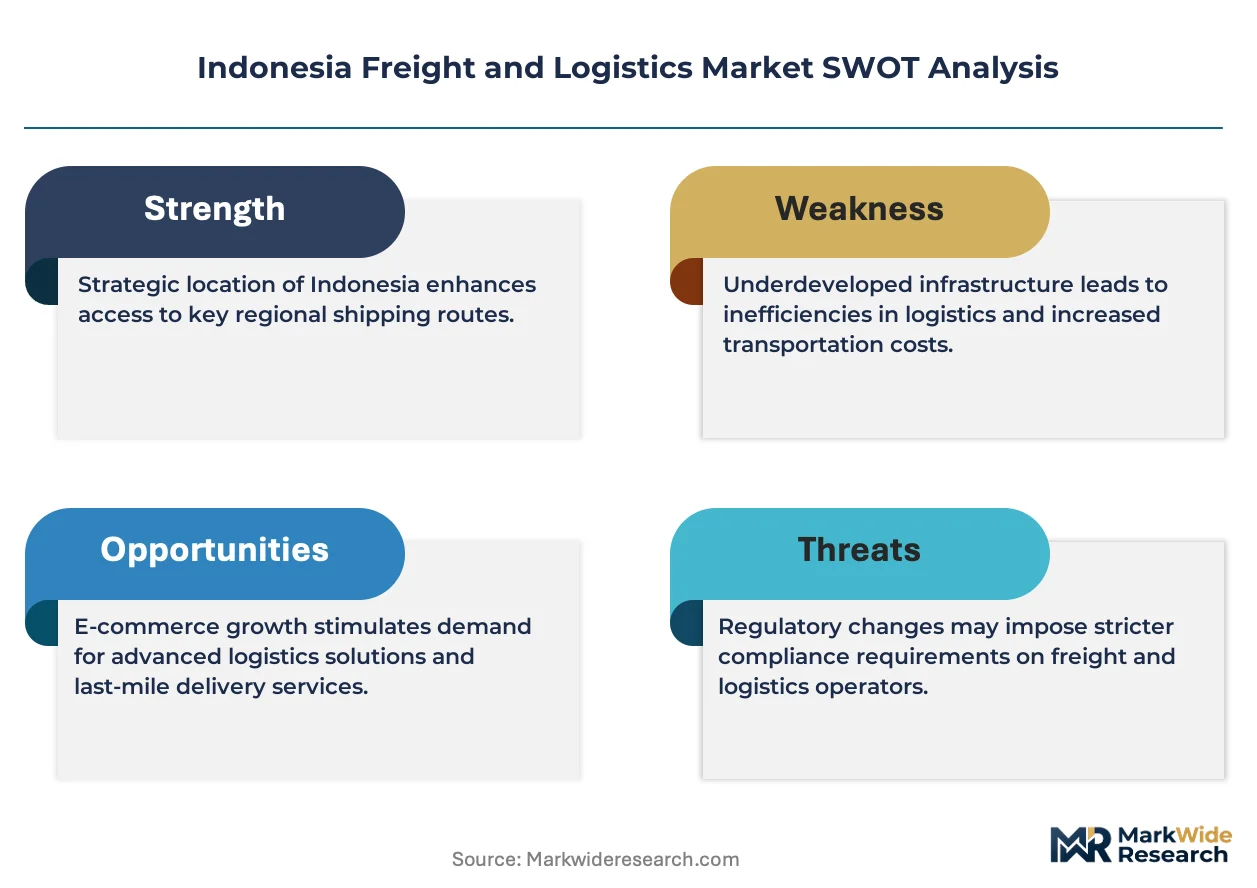
Indonesia's archipelagic geography forces freight networks to absorb inter-island ferry bottlenecks while the Ministry of Transportation enforces cabotage rules that reserve domestic cargo carriage for Indonesian-flagged vessels, creating artificial fleet scarcity that distorts capacity planning across Java-Sumatra corridors.
Growth Catalysts
- National Logistics System integration:The Indonesian government's port automation mandates and bonded zone coordination frameworks are compressing customs clearance timelines at Tanjung Priok and Surabaya terminals.
- E-commerce fulfillment density:Parcel volumes from Jakarta-Bandung-Surabaya manufacturing belt retailers are saturating Greater Jakarta sortation infrastructure and forcing warehouse management technology adoption.
- Batam free trade zone expansion:Electronics manufacturers are relocating assembly operations to leverage duty exemptions and proximity to Singapore transshipment hubs.
Market Restraints
- Fuel cost volatility:Road freight operators across Java's highway network face margin compression from diesel price fluctuations that resist pass-through to contract shippers.
- Fleet nationality constraints:Cabotage enforcement limits foreign-flagged vessel participation in domestic routes, constraining Kalimantan-Java bulk commodity flows during peak agricultural harvest windows.
- Terminal automation gaps:Smaller ports outside Surabaya and Jakarta lack minimum twenty-foot equivalent unit handling capacity, forcing cargo aggregation delays.
Strategic Opportunities
- East Java pharmaceutical cold-chain:Temperature-controlled warehouse investments serving generic drug distributors are capturing value from ASEAN Single Window customs protocol harmonization.
- Sumatra rubber and palm oil corridors:Underpenetrated Medan-Belawan export lanes offer first-mover advantages for integrated logistics providers bundling plantation collection with port stuffing.
- Digital freight matching platforms:Technology convergence between GPS tracking and mobile payment systems is enabling spot-market rate discovery for fragmented trucking fleets.
Industry Challenges
- Warehouse management system integration:Third-party logistics providers struggle to synchronize legacy inventory databases with real-time parcel-sorting automation demanded by e-commerce clients.
- Refrigeration technician scarcity:Pharmaceutical cold-chain expansion outpaces vocational training output for compressor maintenance and temperature validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Freight and Logistics Market |
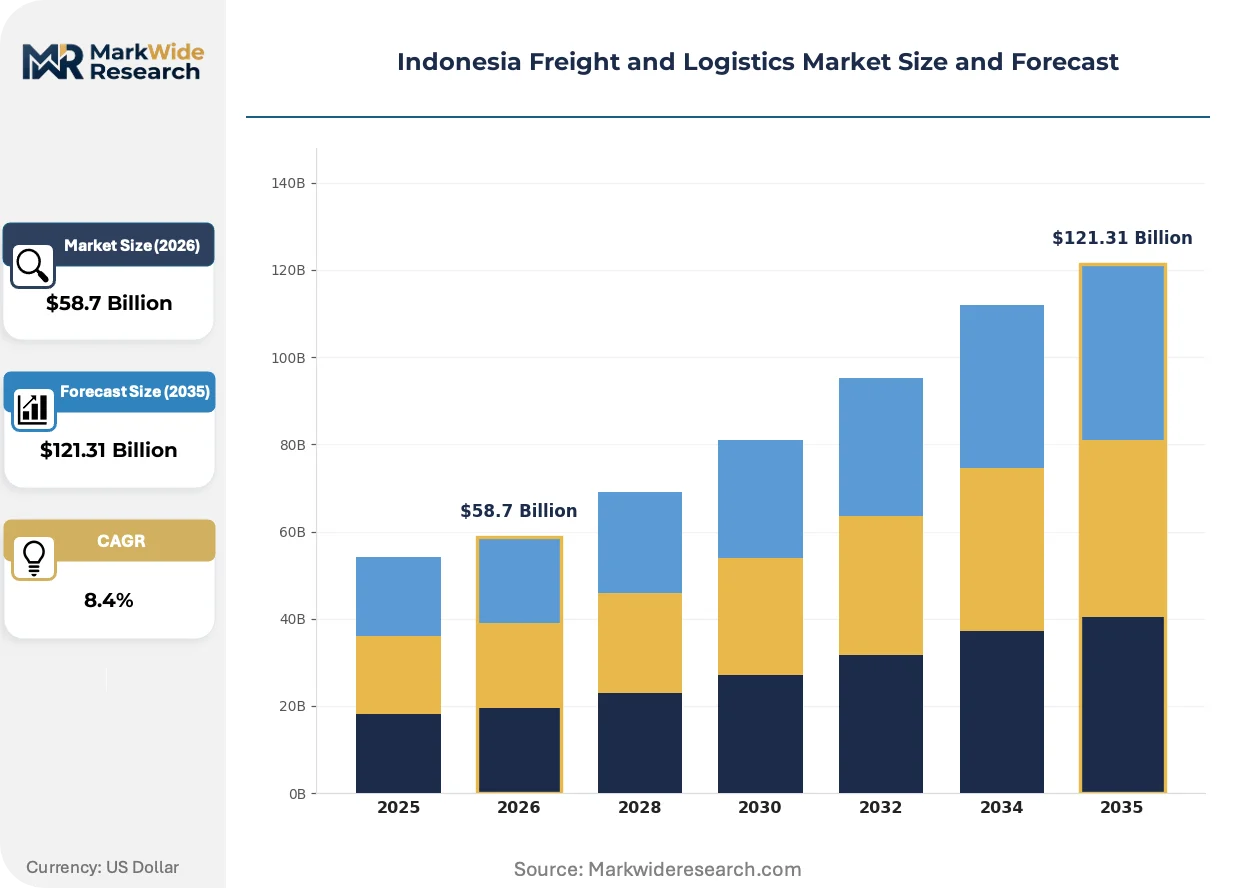
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Sea Freight, Air Freight Technology: Fleet Management, Warehouse Management, GPS Tracking, Automated Systems Customer Type: Retailers, Manufacturers, E-commerce, Distributors Delivery Model: Direct Shipping, Cross-Docking, Last-Mile Delivery, Third-Party Logistics |
| Companies Covered | FedEx, Ninja Van, DHL Group, DB Schenker, Kuehne+Nagel, J&T Express, TIKI, Agility Logistics, JNE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Freight and Logistics Market Strategic Shifts
Automation investments are compressing labor dependency in Indonesian logistics while regulatory mandates force interoperability upgrades across fragmented port systems. Three forces are restructuring competitive positioning.
Automated parcel-sorting systems are migrating from belt-driven mechanical sorters to vision-guided robotic pick stations. E-commerce fulfillment centers in Greater Jakarta are adopting these systems at replacement cycle pace. This technology shift is enabling same-day delivery promises while compressing headcount per thousand parcels processed.
ASEAN Single Window customs protocols are mandating standardized electronic documentation across Indonesian port terminals. The industrial consequence is forced IT infrastructure replacement for customs brokers and freight forwarders. Batam and Surabaya operators are responding fastest due to higher cross-border transaction volumes with Singapore and Malaysia.
Shippers are consolidating vendor relationships around integrated logistics providers offering bonded warehousing bundled with domestic distribution. Fragmented trucking brokers and standalone warehouse operators are losing share to asset-light platform models. This concentration is most visible in Jakarta's consumer goods distribution cluster serving modern retail chains.
Indonesia Freight and Logistics Market Segmentation
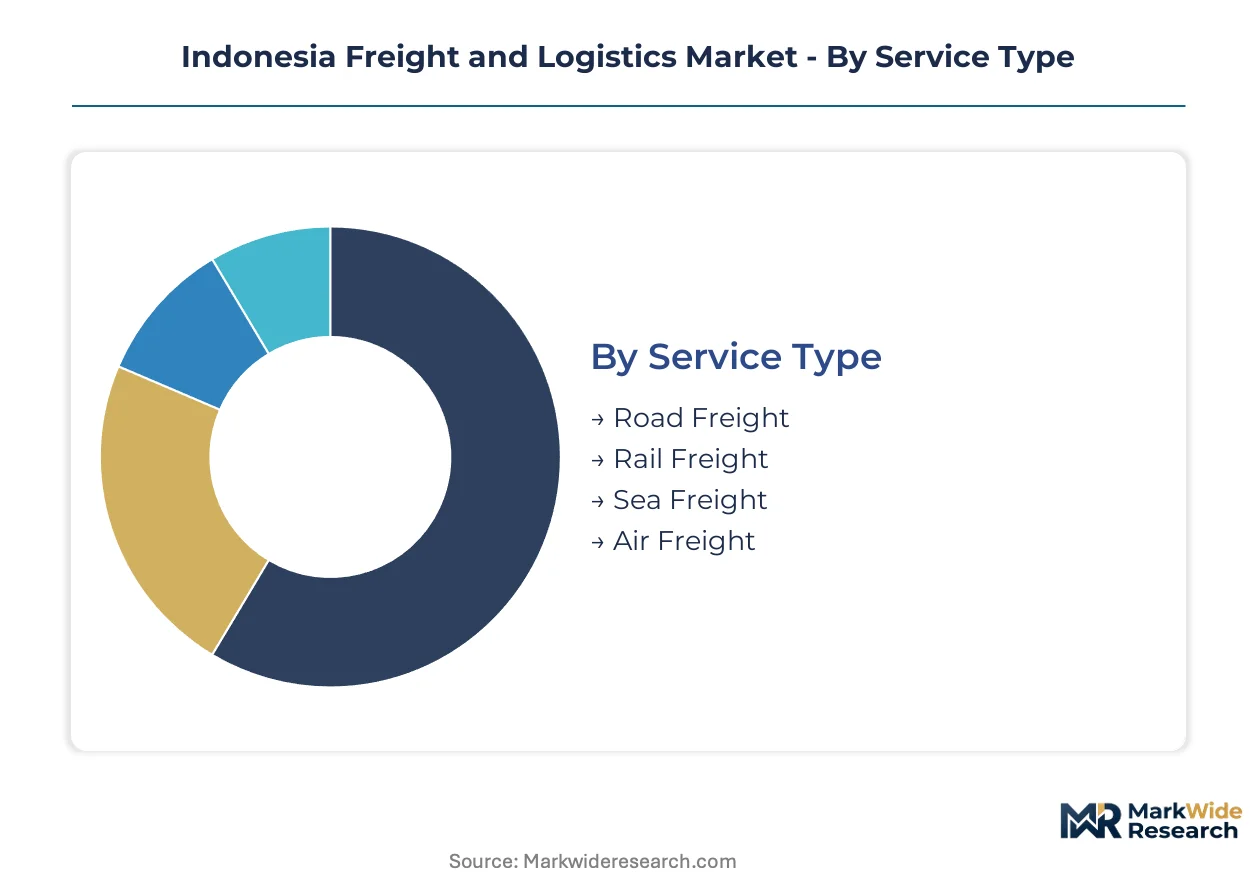
Segmentation in Indonesian freight and logistics reveals how archipelagic geography fragments service requirements across modes and technologies. Each dimension exposes distinct capacity constraints and investment priorities shaping vendor selection.
Service Type:
Road freight dominates Java's manufacturing belt while sea freight carries inter-island bulk flows, with each mode serving distinct cargo profiles and transit time requirements.
- Road Freight:Container trucks and flatbeds move finished goods across Java's Trans-Java toll network connecting Jakarta, Bandung, and Surabaya industrial zones. Demand concentrates in the Jakarta-Bandung corridor where e-commerce fulfillment centers require daily replenishment cycles from manufacturing plants.
- Sea Freight:Roll-on/roll-on vessels and container ships handle bulk commodities between Kalimantan resource terminals and Java processing facilities. Kalimantan-Java coal and palm oil flows absorb the majority of domestic fleet capacity under Ministry of Transportation cabotage enforcement.
- Rail Freight:Limited network coverage restricts deployment to Java north coast corridors serving cement and fertilizer distributors with scheduled block trains.
- Air Freight:Narrow-body belly cargo and dedicated freighters serve high-value electronics and pharmaceutical shipments through Soekarno-Hatta and Juanda airports.
The dominant share belongs to road freight, while sea freight is closing the gap fastest through port automation investments at Tanjung Priok and Surabaya.
Technology:
Technology adoption splits between asset-heavy infrastructure and software platforms, with deployment patterns tracking customer sophistication and shipment value density.
- Fleet Management:Telematics systems monitor fuel consumption and driver behavior across fragmented trucking fleets. Greater Jakarta operators deploy these systems to optimize route planning through the city's congestion-prone arterial roads.
- Warehouse Management:Inventory control software coordinates receiving, put-away, and order fulfillment in third-party logistics facilities. East Java pharmaceutical distributors require temperature-validated WMS modules to maintain cold-chain integrity.
- GPS Tracking:Real-time location monitoring enables shipper visibility across multi-day inter-island voyages and overland hauls.
- Automated Systems:Vision-guided robotic pick stations and automated sortation equipment compress labor dependency in high-volume e-commerce fulfillment centers.
Warehouse management systems command the largest installed base, though automated systems are expanding most quickly in Greater Jakarta parcel hubs.
Customer Type:
Customer segmentation reflects order size variability, delivery velocity requirements, and integration depth with logistics provider systems.
- E-commerce:Marketplace sellers and direct-to-consumer brands require same-day and next-day delivery promises with real-time tracking. Jakarta-Bandung-Surabaya fulfillment density drives automated sortation investments to handle parcel volume spikes during promotional windows.
- Retailers:Modern trade chains and traditional distributors need scheduled replenishment with consolidated multi-SKU deliveries. Modern retail expansion in secondary Java cities is pulling distribution center capacity eastward from Jakarta.
- Manufacturers:Industrial producers seek inbound material coordination and finished goods distribution with vendor-managed inventory arrangements.
- Distributors:Wholesalers aggregate products from multiple suppliers for resale to smaller retailers with fragmented order patterns.
E-commerce holds the dominant revenue share, while manufacturers are deepening provider integration fastest through bonded warehousing contracts.
Delivery Model:
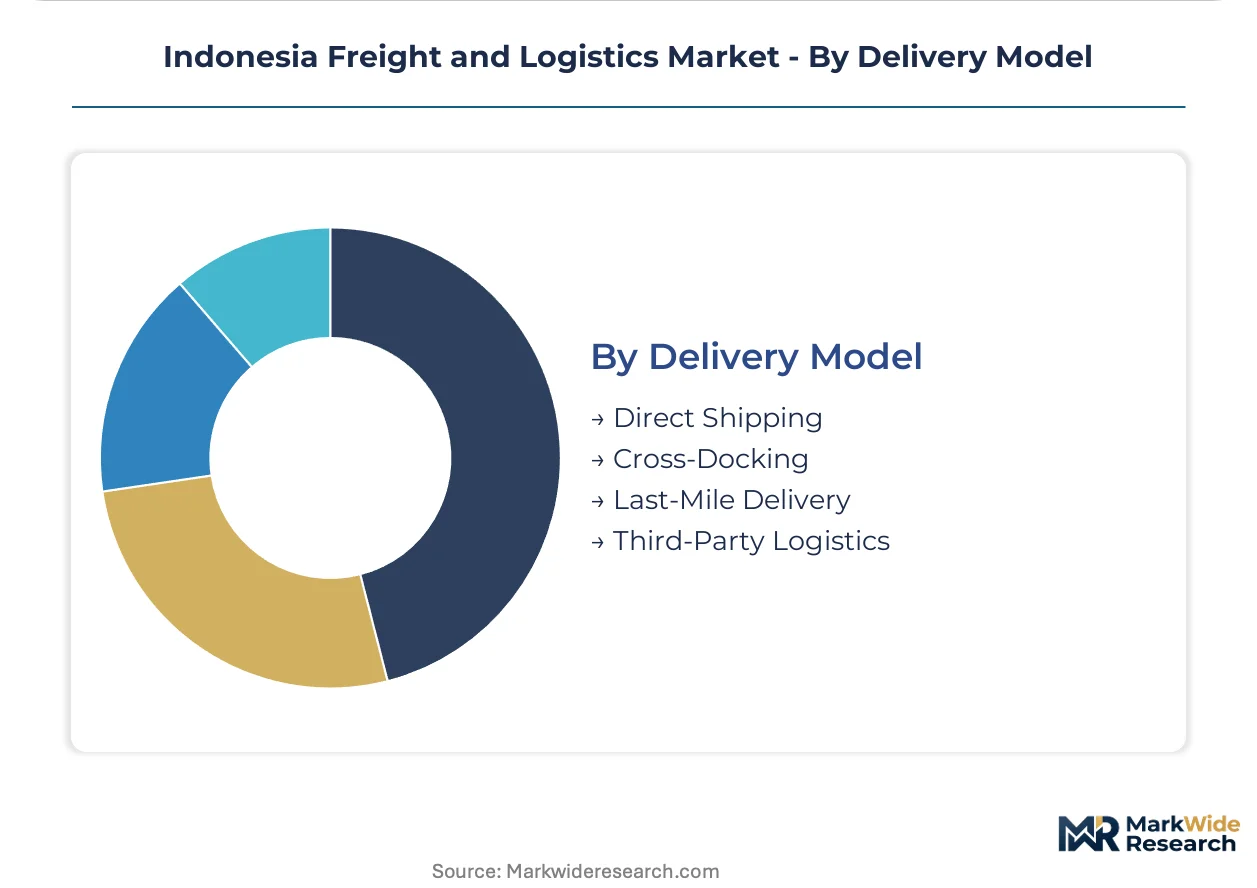
Delivery model selection trades speed against handling cost, with model penetration varying by customer sophistication and cargo value.
- Third-Party Logistics:Integrated providers bundle warehousing, transportation, and value-added services under single contracts. Consumer goods multinationals in Jakarta's industrial suburbs prefer 3PL arrangements to avoid fixed asset commitments.
- Last-Mile Delivery:Final-leg distribution to residences and small retailers requires dense pickup point networks and flexible fleet scaling. Greater Jakarta's traffic congestion forces micro-fulfillment hub placement within 10 kilometers of dense residential clusters.
- Direct Shipping:Point-to-point movement without intermediate handling suits high-value, time-sensitive shipments with dedicated vehicle allocation.
- Cross-Docking:Rapid freight transfer between inbound and outbound vehicles minimizes inventory holding at distribution facilities.
Third-party logistics retains the largest share, though last-mile delivery is gaining ground fastest through e-commerce volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java absorbs the majority of Indonesia's freight infrastructure investment while Sumatra and Kalimantan operate on fundamentally different logistics economics shaped by bulk commodity extraction rather than manufacturing density.
Java
The Jakarta-Bandung-Surabaya corridor drives automated sortation demand from e-commerce fulfillment centers clustered around Cikarang industrial zones. Ministry of Transportation port automation mandates compress customs clearance at Tanjung Priok and Surabaya terminals. Greater Jakarta's micro-fulfillment hub placement within 10 kilometers of dense residential clusters addresses last-mile congestion constraints.
Sumatra
Medan-Belawan export lanes handle rubber and palm oil flows with limited integrated logistics bundling between plantation collection and port stuffing. Cabotage enforcement reserves domestic cargo carriage for Indonesian-flagged vessels, constraining fleet flexibility during peak agricultural harvest windows. The Belawan port expansion targets electronics assembly relocation from Batam free trade zone spillover.
Kalimantan
Coal and palm oil terminals feed Java processing facilities through roll-on/roll-on vessel networks subject to seasonal capacity bottlenecks. The Ministry of Energy and Mineral Resources coordinates bulk commodity export licensing with port queue management. Samarinda and Balikpapan anchor resource logistics clusters with limited manufacturing value-add infrastructure.
Sulawesi
Nickel processing investments around Morowali Industrial Park generate specialized bulk chemical and equipment logistics demand distinct from Java's consumer goods profile. The Indonesia Investment Coordinating Board oversees bonded zone status for battery precursor material exports. Makassar functions as the primary transshipment hub for eastern archipelago distribution.
Batam
Electronics manufacturers leverage duty exemptions and Singapore transshipment proximity for component import and finished goods export cycles. The Batam Free Trade Zone Authority coordinates customs protocols with ASEAN Single Window electronic documentation standards. The Batam-Bintan-Karimun growth triangle competes with Johor-Singapore corridor for semiconductor assembly logistics.
Indonesia Freight and Logistics Market Competitive Environment
Capability concentration sits with integrated global forwarders possessing pharmaceutical cold-chain and bonded warehousing expertise; scale advantage sits with domestic parcel networks leveraging Java's highway density for e-commerce fulfillment. The market structures around three tiers: multinational forwarders with premium air freight corridors, domestic express operators with automated sortation infrastructure, and fragmented trucking brokers losing share to platform consolidation. M&A activity concentrates on last-mile delivery acquisitions and warehouse management technology licensing.
Within the integrated global tier, DHL Group and Kuehne+Nagel exemplify forwarders anchoring temperature-controlled logistics and premium air freight positioning. Among domestic express specialists, J&T Express occupies a scale-driven position in Greater Jakarta automated sortation. The competitive dynamic pits global forwarder expertise against domestic operator density, with technology licensing emerging as the primary vector for capability bridging between tiers.
| Leading Market Players |
|---|
| FedEx |
| Ninja Van |
| DHL Group |
| DB Schenker |
| Kuehne+Nagel |
| J&T Express |
| TIKI |
| Agility Logistics |
| JNE |
| Others |
Value Chain & Pricing Dynamics
Fuel cost volatility across Java's highway network determines both contract rate spreads and fleet operator supply chain configurations, compressing margins for road freight carriers while forcing cargo aggregation strategies that lengthen transit times through smaller ports.
Pricing Analysis
Long-term offtake contracts dominate bulk commodity flows between Kalimantan and Java, while spot-market rate discovery governs fragmented trucking fleets in Greater Jakarta. Price differentiation rests on fuel surcharge pass-through mechanisms and bonded warehousing bundling with domestic distribution. Pricing pressure stems from diesel price fluctuations that resist full pass-through to contract shippers. Small trucking operators exhibit highest price sensitivity, while pharmaceutical cold-chain clients accept premium tiers for temperature-validated service.
Supply Chain Analysis
ASEAN Single Window customs protocols function as de facto export-control mechanisms limiting documentation flow efficiency across Indonesian port terminals. Equipment and systems draw from Singapore, China, and Malaysia for port automation and warehouse management technology. Supply chain risk centers on single-source vulnerability for automated sortation hardware. Distribution runs through bonded zone coordination frameworks at Tanjung Priok and Surabaya terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight matching platforms threaten traditional trucking broker margins, forcing incumbents to defend through automation investments that compress labor dependency per parcel processed.
For Market Incumbents: Build switching-cost moats through warehouse management system integration that locks e-commerce clients into real-time inventory synchronization. Invest in temperature-controlled warehouse capacity in East Java to capture pharmaceutical distributor consolidation. Defend against platform-based freight matching by embedding GPS tracking and mobile payment systems into proprietary shipper interfaces. For New Entrants and Emerging Players: Build out micro-fulfillment hub networks within 10 kilometers of dense residential clusters in secondary Java cities where modern retail expansion outpaces distribution capacity. Target Medan-Belawan rubber and palm oil corridors for integrated logistics bundling between plantation collection and port stuffing. Pursue go-to-market partnerships with electronics manufacturers relocating assembly operations to Batam free trade zone. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light platform models with automated sortation infrastructure over fragmented trucking brokers. Long-term viability hinges on bonded warehousing expertise and ASEAN Single Window customs protocol mastery. Watch for Ministry of Transportation cabotage enforcement relaxation as signal for foreign fleet participation and capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Deployment | Vision-guided robotic pick stations at Cikarang fulfillment centers compress labor dependency per thousand parcels processed. |
| Bonded Warehouse Expansion | Temperature-controlled facilities in East Java capture pharmaceutical distributor consolidation under ASEAN Single Window protocols. |
| Micro-Fulfillment Hub Placement | Last-mile nodes within 10 kilometers of Jakarta residential clusters address congestion constraints for same-day delivery promises. |
| Digital Freight Platform Integration | GPS tracking convergence with mobile payment systems enables spot-market rate discovery for fragmented Java trucking fleets. |
| Cold-Chain Technician Training | Vocational programs for compressor maintenance and temperature validation protocols close pharmaceutical logistics capability gaps. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations managers, customs brokerage principals, warehouse technology vendors, and pharmaceutical distribution executives and refined through secondary validation against Ministry of Transportation port modernization mandates, ASEAN Single Window protocol documentation, BIS logistics standards filings, and customs clearance performance data at Tanjung Priok and Surabaya terminals. Bottom-up parcel volume modeling and top-down GDP elasticity approaches were triangulated.
Demand-supply balance across the analysis window was assessed through corridor-specific capacity utilization and bonded zone throughput metrics. Segmentation dimensions modeled include service type, technology deployment, customer archetype, and delivery model complexity. CAGRs were derived from elasticity-adjusted volume projections. Forecast inputs incorporated e-commerce fulfillment density trajectories and port automation investment timelines.
Stress conditions across fuel price bands, cabotage enforcement intensity, and customs clearance automation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about National Logistics System integration progress. Material shifts in Ministry of Transportation port modernization mandates or ASEAN Single Window protocol harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Czech Republic Freight and Logistics Market