
 Global Segway Consumption Market | 2026-2036
Global Segway Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Segway Consumption Market Outlook
Modular battery-swappable configurations is pivoting buyer choice toward fleet-ready platforms over consumer-only models. Segway Inc. anchors North American commercial channel relationships through dealer networks serving police and campus security segments. INMOTION Technologies Co., Ltd. specializes in compact form factors for Asian urban commuters. Ninebot Limited extends manufacturing scale across Shenzhen facilities to supply European rental operators.
Global Segway consumption encompasses self-balancing electric personal transporters powered by gyroscopic stabilization systems, typically employing dual brushless hub motors rated between 400W and 2000W and lithium-ion battery packs delivering 15-40 km range per charge, designed for short-distance urban mobility and commercial fleet applications. Kick scooters dominate volume shipments due to lower price points and minimal rider training requirements, while personal transporters command premium positioning in corporate security and guided tourism deployments where stability and brand recognition justify higher acquisition costs. Lithium-ion configurations are displacing nickel-metal hydride across all product tiers as energy density improvements reduce per-unit battery mass and extend operational uptime for rental fleet operators.
The EU Machinery Directive and CE marking framework mandate third-party conformity assessment for self-balancing vehicles sold within member states, while the US Consumer Product Safety Commission enforces electrical and mechanical safety standards that shape import eligibility and product liability exposure for manufacturers. China's GB standards administered by SAMR establish domestic baseline requirements that parallel export-market certifications and reduce retesting burdens for Shenzhen-based producers. Stakeholders must monitor evolving municipal permit regimes and battery recycling mandates as cities tighten micromobility governance without harmonized international frameworks.
Market Dynamics
Fleet operators in Barcelona, Paris, and Berlin are consolidating procurement around modular battery-swappable platforms, compressing replacement cycles and reshaping vendor qualification criteria toward uptime guarantees over unit economics.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for self-balancing vehicles are filtering out uncertified suppliers and concentrating demand among pre-approved vendors serving municipal micromobility programs.
- Guided tourism fleet expansion:Urban sightseeing operators across Germany, France, and Spain are replacing walking tours with personal transporter deployments, creating recurring bulk procurement channels.
- Lithium-ion energy density improvements:Reduced battery mass per kilowatt-hour is extending operational range for rental fleets without expanding charging infrastructure footprints.
Market Restraints
- Cobalt and lithium price volatility:Raw material input costs for battery cathodes create margin compression for manufacturers without long-term offtake agreements.
- Shenzhen manufacturing concentration:Over-reliance on Guangdong Province assembly facilities exposes supply continuity to regional logistics disruptions and power rationing events.
- CE conformity assessment timelines:Third-party certification bottlenecks for gyroscopic stabilization systems delay product launches by six to twelve months for new market entrants.
Strategic Opportunities
- India micromobility permit liberalization:State-level urban transport reforms in Maharashtra and Karnataka are opening fleet deployment opportunities previously restricted to two-wheelers.
- Police and campus security procurement:North American institutional buyers are expanding patrol vehicle replacement programs beyond traditional golf carts into personal transporter categories.
- ISO 13482 service robot convergence:Personal care robotics standards are creating regulatory pathways for mobility devices with autonomous navigation capabilities in healthcare facilities.
Industry Challenges
- Brushless motor controller firmware expertise:Shortages of embedded systems engineers with gyroscopic stabilization experience are extending R&D timelines for stability algorithm optimization.
- Hub motor thermal management certification:Sustained load testing requirements for 2000W-rated dual motor configurations are creating prototype-to-production gaps.
- Reverse logistics for end-of-life batteries:Fleet operators lack standardized collection networks for lithium-ion pack recycling under emerging extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Segway Consumption Market |
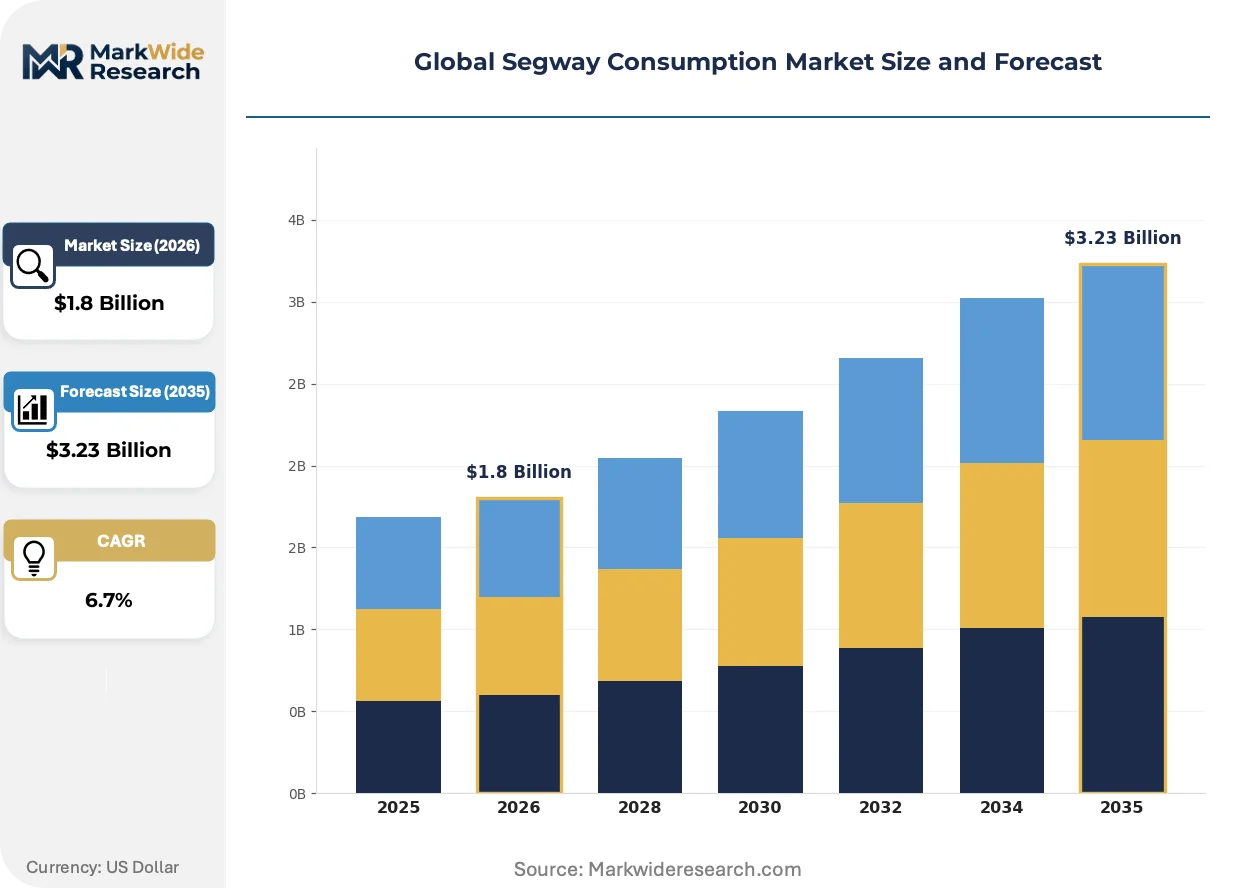
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Segways, Kick Scooters, Hoverboards, Personal Transporters End User: Individual Consumers, Corporate Usage, Tours & Sightseeing, Rentals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Others |
| Companies Covered | Airwheel Technology Holding (USA) Co., Ltd., INMOTION Technologies Co., Ltd., Segway Inc., ESWING Tech. Co., Ltd., Razor USA LLC, Ninebot Limited, Swagtron, Fosjoas Technology Co. Ltd., Robstep Robot Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Segway Consumption Market Strategic Shifts
Hardware modularity and software-defined fleet management are converging to transform how rental operators specify, deploy, and maintain personal transporter assets at scale.
Solid-state battery prototyping is rewriting range and charging expectations for next-generation personal transporters. Early-stage cell samples from Korean and Japanese materials suppliers are entering validation programs with European fleet operators. The technology is compressing the competitive window for incumbent lithium-ion pack architectures before commercial scale-up.
REACH substance restrictions on nickel-cadmium battery chemistries are accelerating chemistry transitions across EU-bound product lines. Manufacturers with Shenzhen assembly footprints are reformulating cathode compositions to maintain CE marking eligibility. The directive is forcing component-level redesigns for entry-level kick scooter segments most exposed to cost-sensitive substitution.
Telemetry-enabled predictive maintenance contracts are displacing traditional break-fix service arrangements in commercial fleet accounts. Rental operators in Barcelona and Paris are unbundling hardware acquisition from uptime guarantees, shifting vendor relationships toward availability-based pricing. The model is concentrating procurement authority among fleet management platforms with integrated diagnostic capabilities.
Global Segway Consumption Market Segmentation
Segmentation in the personal transporter market reveals divergent engineering priorities between consumer convenience and commercial durability requirements. Fleet operators demand modular architectures with standardized interfaces, while individual buyers prioritize portability and aesthetic differentiation.
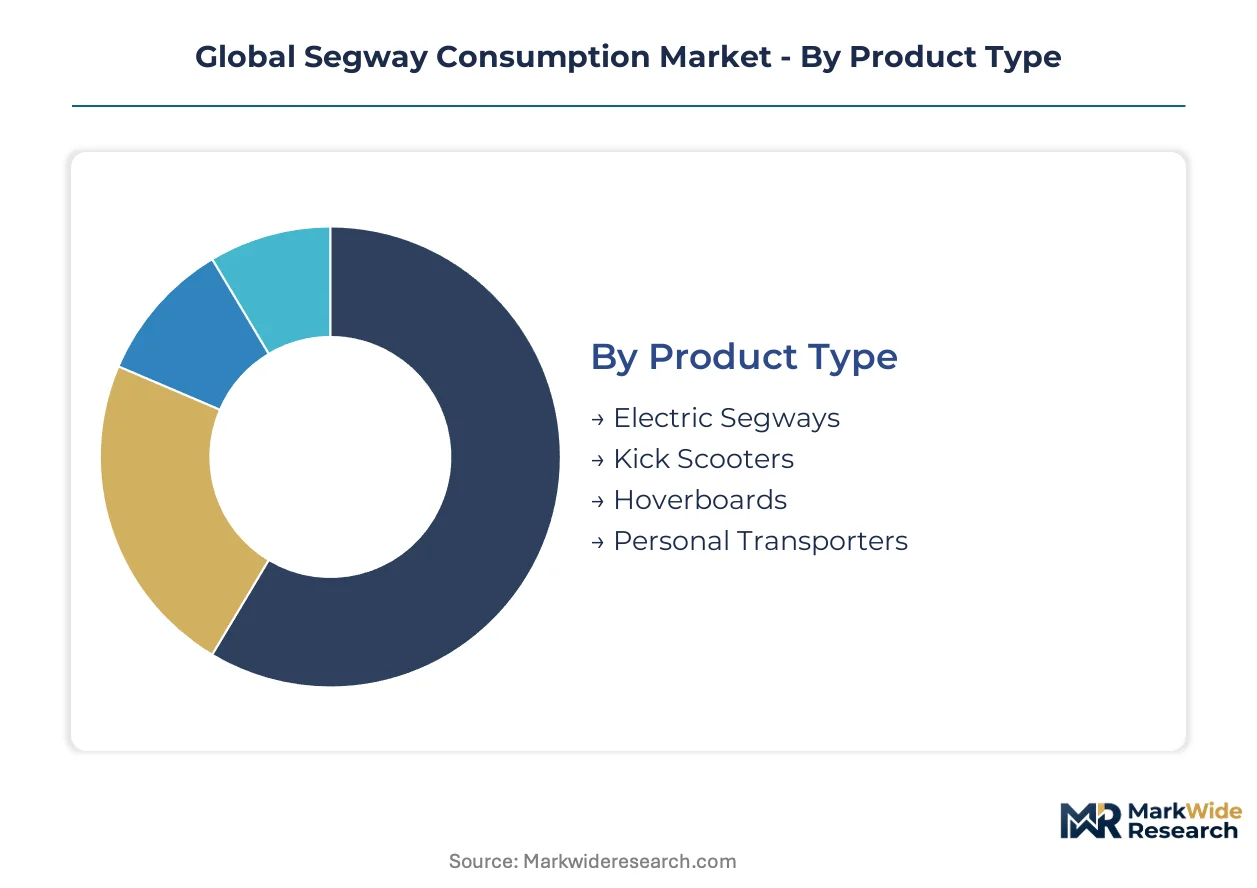
Product Type:
Customization intensity varies sharply across this category, from mass-produced kick scooters with minimal configuration options to bespoke personal transporters engineered for specific terrain and duty cycles.
- Kick Scooters:Lightweight folding frames with 250-500W hub motors and 20-30 km range dominate urban commuter volumes. Demand concentrates in German and French municipal micromobility permits where operators favor low-maintenance, minimal-training platforms.
- Personal Transporters:Dual-motor gyroscopic stabilization systems rated 800-2000W serve corporate security patrols and guided tourism fleets. Barcelona and Paris tour operators specify these for brand differentiation and rider stability on cobblestone surfaces.
- Electric Segways:Self-balancing platforms with handlebar steering retain niche positioning in North American campus and airport security applications.
- Hoverboards:Compact dual-wheel units without handlebars target youth recreational segments with aggressive price positioning.
Leading the category by volume: Kick Scooters. Expanding most quickly: Personal Transporters.
End User:
Volume concentration tilts toward institutional buyers with multi-year procurement horizons and standardized replacement schedules rather than discretionary consumer purchases.
- Tours & Sightseeing:Guided urban experience operators in Spain, France, and Germany deploy 10-50 unit fleets with centralized charging depots. CE marking compliance and liability insurance requirements filter vendor selection toward established certification holders.
- Rentals:Dockless and docked micromobility programs in Berlin and Barcelona specify swappable battery architectures to maximize asset utilization rates.
- Corporate Usage:Campus security, warehouse logistics, and airport operations in the US specify ruggedized frames with extended warranty terms.
- Individual Consumers:Price-sensitive purchasers drive entry-level kick scooter volumes through online channels with minimal after-sales service expectations.
Procurement scale concentrates with: Tours & Sightseeing. Steepest expansion trajectory: Rentals.
Distribution Channel:
Channel selection correlates directly with buyer technical sophistication and service dependency, separating self-serve online purchasers from buyers requiring configuration support.
- Direct Sales:Fleet operators in Germany and France negotiate volume contracts with manufacturers for customized firmware, branded livery, and integrated telemetry platforms.
- Online Retail:Consumer-directed e-commerce channels move standardized kick scooter SKUs with minimal customization and 7-14 day delivery windows.
- Specialty Stores:Urban showrooms in Barcelona and Paris offer test-ride experiences and maintenance packages for premium personal transporter segments.
- Supermarkets:Mass retail placement captures impulse purchases of entry-level hoverboards and basic kick scooters with limited technical specifications.
Dominant by transaction volume: Online Retail. Fastest channel growth: Direct Sales.
Battery Type:
Energy density requirements and regulatory chemistry restrictions are fragmenting this category between legacy installed base and next-generation fleet specifications.
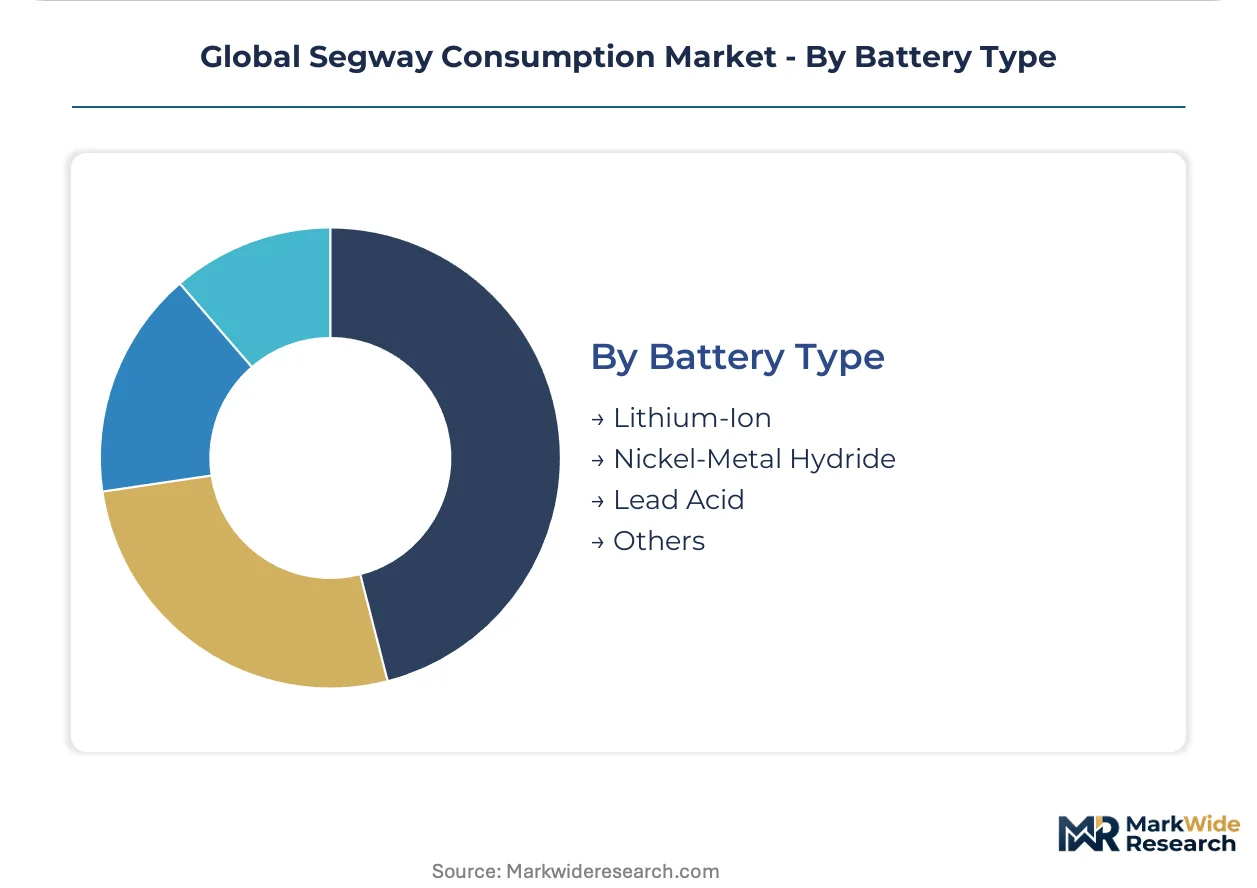
- Lithium-Ion:NMC and LFP cell configurations deliver 30-40 km range at 25-35% reduced mass versus predecessor chemistries. European fleet operators specify these for REACH compliance and extended cycle life under commercial duty cycles.
- Nickel-Metal Hydride:Declining installed base in early-generation personal transporters faces replacement demand as cells reach end-of-life in North American campus security fleets.
- Lead Acid:Cost-driven selection for price-sensitive hoverboard segments in developing markets with minimal environmental disposal enforcement.
- Others:Solid-state prototypes and sodium-ion alternatives enter validation programs with Korean and Japanese materials suppliers targeting post-lithium architectures.
Technology leadership sits with: Lithium-Ion. Gaining share fastest: Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Shenzhen and Dongguan manufacturing corridors, while consumption patterns diverge sharply across regulatory environments. Fleet operators in Western Europe drive premium demand through CE-certified procurement mandates. Asian markets absorb volume through commuter-oriented kick scooter deployments.
Germany
Municipal micromobility permits in Berlin and Munich favor certified personal transporter vendors with established conformity documentation. The KBA enforces type approval requirements for self-balancing vehicles operating on public thoroughfares. Bavarian tour operators in Nuremberg and Munich maintain the densest guided sightseeing fleet deployments in Europe.
France
Parisian rental operators specify swappable-battery platforms to maximize asset utilization across dockless micromobility zones. ANSM oversees product safety notifications for lithium-ion powered personal mobility devices. Île-de-France regional authorities coordinate charging infrastructure subsidies that concentrate fleet depots in central arrondissements.
Spain
Barcelona's tourism board licenses personal transporter operators for guided urban experiences along the Gothic Quarter waterfront. The country's national consumer protection authority enforces battery safety labeling requirements for imported hoverboard segments. Catalan fleet managers are consolidating procurement around modular architectures with standardized charging interfaces.
United States
Campus security departments in California and Texas are replacing golf cart patrol fleets with personal transporter categories. The Consumer Product Safety Commission enforces electrical and mechanical safety standards that shape import eligibility for Shenzhen-produced units. Midwestern warehouse logistics operators in Ohio and Illinois are piloting gyroscopic stabilization platforms for indoor material transport.
China
Shenzhen-based assembly facilities supply European rental operators through direct volume contracts with firmware customization. SAMR administers GB standards that establish domestic baseline requirements paralleling export-market certifications. Dongguan industrial clusters specialize in brushless hub motor production for 2000W-rated dual motor configurations.
Global Segway Consumption Market Competitive Environment
The competitive structure tilts toward vertically integrated manufacturers with captive battery pack assembly capabilities. Shenzhen-based producers dominate unit volume through scale economies in motor controller production. Three archetypes occupy distinct positions: fleet-focused platform vendors with telemetry integration, consumer-brand distributors with e-commerce channel dominance, and component specialists supplying hub motor assemblies. Capacity expansion and strategic partnerships with rental operators constitute the dominant competitive moves.
Within the fleet-platform tier, Segway Inc. and Ninebot Limited occupy positions anchoring North American and European commercial channel relationships respectively. INMOTION Technologies Co., Ltd. exemplifies the compact-form-factor specialist archetype serving Asian urban commuter segments. Razor USA LLC represents the consumer-brand distributor model with mass retail placement strategies.
| Leading Market Players |
|---|
| Airwheel Technology Holding (USA) Co., Ltd. |
| INMOTION Technologies Co., Ltd. |
| Segway Inc. |
| ESWING Tech. Co., Ltd. |
| Razor USA LLC |
| Ninebot Limited |
| Swagtron |
| Fosjoas Technology Co. Ltd. |
| Robstep Robot Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive battery pack assembly in Shenzhen and Dongguan manufacturing corridors anchors both supply security and pricing leverage for personal transporter producers. This integration pattern compresses procurement cycles for lithium-ion cells while insulating tier-one vendors from spot-market cobalt volatility that erodes margins at the module level.
Pricing Analysis
Margin tightening in kick scooter tiers reflects REACH compliance costs and nickel-cadmium chemistry phase-outs that force component-level redesigns. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified fleet platforms from consumer-grade hoverboards, with tour operators in Barcelona and Paris showing lowest price sensitivity due to liability insurance requirements. Cost compression accelerates in entry-level segments as Shenzhen producers compete on hub motor controller firmware customization.
Supply Chain Analysis
Lithium carbonate and cobalt hydroxide feedstock rests on Chilean mining operations, Australian spodumene concentrate, and Indonesian nickel processing corridors. Brushless hub motor production draws from Dongguan industrial clusters specializing in 2000W-rated dual motor configurations. Single-source vulnerability concentrates in Guangdong Province assembly footprints exposed to regional power rationing. Distribution runs through direct volume contracts with European rental operators and North American dealer networks serving campus security segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CE marking compliance timelines and battery chemistry transitions are forcing consolidation among uncertified suppliers, concentrating procurement authority with pre-approved vendors.
For Market Incumbents: Deploy telemetry-enabled predictive maintenance contracts to displace break-fix arrangements in Barcelona and Paris fleet accounts. Deepen backward integration into brushless motor controller firmware development to offset embedded systems engineer shortages. Certification investment in ISO 13482 service robot pathways creates defensive positioning against autonomous navigation entrants in healthcare facilities. For New Entrants and Emerging Players: Fleet management platforms with integrated diagnostic capabilities represent the most penetrable channel archetype. Target Indian state-level micromobility permit liberalization in Maharashtra and Karnataka where two-wheeler restrictions previously blocked deployment. White-space exists in police and campus security procurement beyond traditional golf cart replacement programs in Texas and California. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by vertically integrated mobility platforms seeking captive battery assembly capabilities. Long-term viability favors vendors with Shenzhen manufacturing scale and established European conformity documentation. Watch solid-state battery validation milestones with Korean and Japanese materials suppliers as inflection indicators for lithium-ion architecture displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Platform Development | Swappable architectures maximize fleet utilization rates for Berlin and Barcelona rental operators. |
| CE Marking Pathway Investment | Third-party conformity assessment filters uncertified competitors from EU municipal permit programs. |
| Fleet Telemetry Integration | Diagnostic capabilities enable availability-based pricing contracts displacing traditional hardware sales. |
| Brushless Motor Controller R&D | Stability algorithm expertise addresses thermal management certification gaps for 2000W configurations. |
| Reverse Logistics Network Buildout | Standardized lithium-ion collection infrastructure satisfies emerging extended producer responsibility frameworks. |
Study Parameters
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by regulatory documentation from the EU Machinery Directive and China's SAMR. Primary interviews with fleet procurement managers at Barcelona and Paris rental operators, embedded systems engineers at Shenzhen motor controller specialists, and campus security directors in California and Texas provided operational validation. Bottom-up unit shipment estimates triangulated against top-down value projections across the analysis window.
Historical trendline analysis examined lithium-ion energy density improvements and CE marking adoption curves without year-specific anchoring. Segmentation modeling spanned product type, end-user category, distribution channel, and battery chemistry tiers throughout the forecast period. CAGRs derived from fleet deployment trajectories in German municipal micromobility programs and guided tourism expansion patterns across Spain, France, and Germany. Solid-state battery prototyping timelines and cobalt price volatility scenarios informed sensitivity bounds.
Several conditions sit outside the modeled scope, including unannounced municipal permit regime changes and battery recycling mandate acceleration. Forecasts reflect assumptions about lithium-ion chemistry dominance and Shenzhen manufacturing continuity. Supply disruption from regional logistics bottlenecks, power rationing events, or raw material export restrictions could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Deck Boat Market