
 Brush Motor Control Unit Market | 2026-2036
Brush Motor Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Brush Motor Control Unit Market Outlook
East Asian semiconductor foundry capacity expansion is repositioning the supply base for insulated-gate bipolar transistors and MOSFETs that underpin brush motor control architectures. Infineon Technologies AG leverages its Dresden fab complex to sustain a captive supply of power semiconductors for automotive motor control modules. Texas Instruments anchors its position through integrated motor driver portfolios that dominate small-appliance and tool applications. Nidec Corporation competes via vertical magnetics expertise, extending from motor design into control electronics for precision servo systems.
A brush motor control unit is an electronic subsystem that modulates voltage and current to direct-current brushed motors through pulse-width modulation or hysteresis-based switching, typically operating at frequencies between 15 and 50 kHz to balance thermal losses against torque ripple. Its primary commercial purpose is to deliver variable speed, directional control, and overload protection in applications where brush commutation remains cost-advantageous over brushless alternatives. Digital controllers are capturing specification share in automotive and renewable energy installations where software-defined torque profiles and diagnostic telemetry are becoming baseline requirements. Analog controllers still dominate consumer electronics and budget-tier power tools where bill-of-materials compression outweighs feature complexity. Field-oriented control technology is displacing simpler PWM schemes in industrial automation segments where energy recovery and regenerative braking justify algorithmic investment.
The EPA's efficiency standards for fractional horsepower motors and the EU F-Gas Regulation's compressor electrification mandates are reshaping product standards across HVAC and refrigeration applications, compelling redesigns of legacy analog control architectures. NHTSA crashworthiness and electromagnetic compatibility requirements for electric power steering systems are tightening qualification protocols for automotive-grade motor controllers. China's GB standards for motor efficiency and MIIT industrial electrification directives are converging with REACH substance restrictions on leaded solder and cadmium-plated terminals to elevate material and design compliance costs. Stakeholders must monitor how dual carbon goals in East Asian manufacturing hubs and evolving automotive functional-safety certifications restructure the competitive boundary between discrete-component and fully integrated motor control solutions.
Market Dynamics
Field-oriented control algorithms are compressing specification timelines for brush motor control units as automotive OEMs demand software-defined torque profiles that legacy analog architectures cannot deliver. This technology shift is restructuring competitive boundaries between discrete-component suppliers and fully integrated module providers.
Growth Catalysts
- EU F-Gas Regulation:Compressor electrification mandates in HVAC and refrigeration applications are forcing redesigns of legacy control systems toward higher-efficiency architectures.
- Automotive EPS adoption:Electric power steering systems in passenger vehicles require precision motor control with diagnostic telemetry, pulling digital controller specifications.
- East Asian foundry expansion:Semiconductor capacity growth for IGBTs and MOSFETs is stabilizing power component supply for motor control module production.
Market Restraints
- Raw material cost volatility:Copper magnet wire and rare-earth magnet prices fluctuate with energy market swings, compressing margin predictability for controller manufacturers.
- Supply concentration risk:Advanced power semiconductor fabrication clusters in Taiwan and South Korea create geographic single-points-of-failure for automotive-grade IGBT sourcing.
- Brushless substitution threat:Permanent-magnet synchronous motors with integrated electronics are capturing cost-advantaged positions in cordless power tools and small appliances.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for manufacturing automation equipment are opening specification windows for precision servo control in textile and packaging machinery.
- Regenerative braking convergence:Field-oriented control paired with energy recovery circuits creates white space in material handling and warehouse automation equipment.
- Direct OEM contracting:Tier-1 automotive suppliers are bypassing traditional distribution to source custom-programmed control modules with proprietary firmware.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for electric power steering controllers extends development cycles by 18-24 months.
- Legacy system integration friction:Analog controller replacement in installed industrial equipment requires mechanical retrofitting and control protocol translation.
- Power electronics talent scarcity:Shortage of engineers with combined motor control algorithm and thermal management expertise constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brush Motor Control Unit Market |
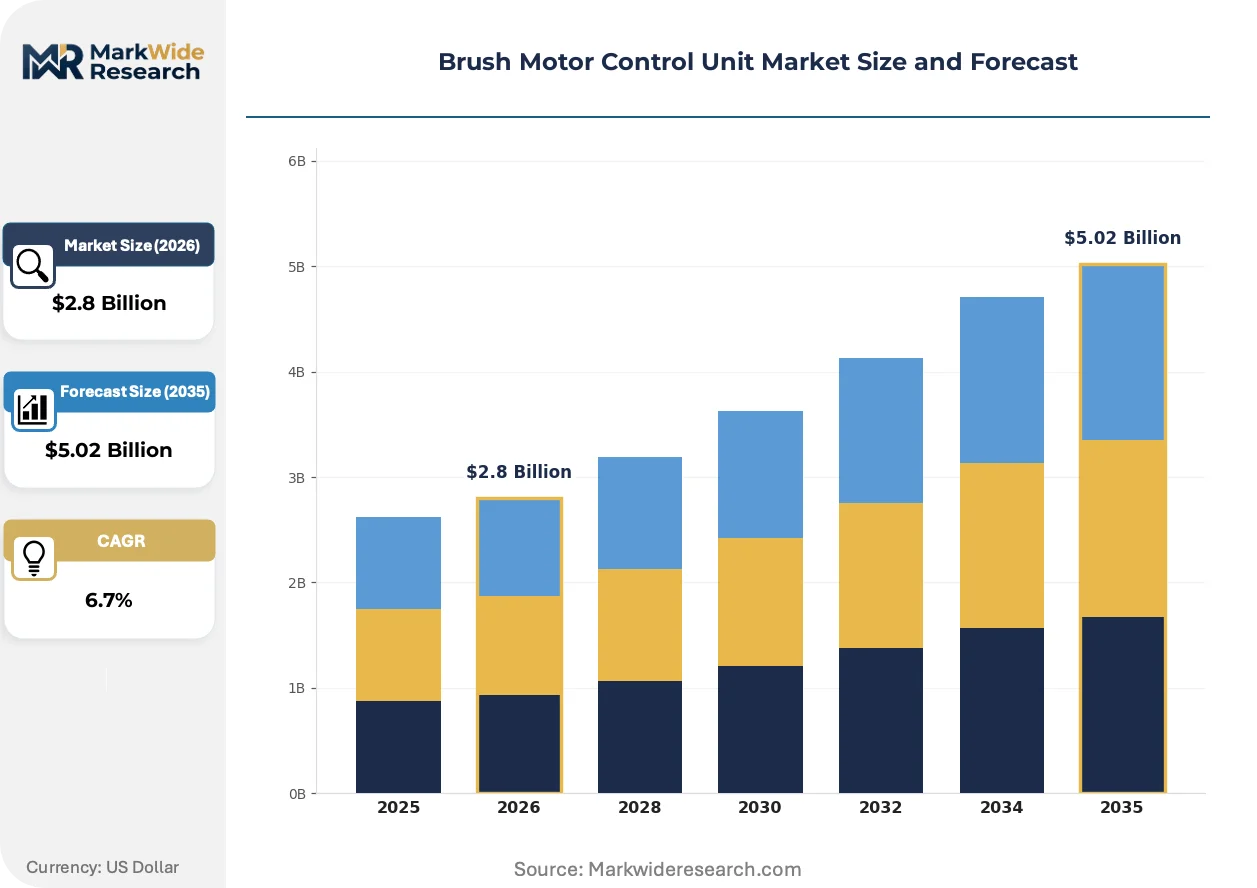
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Controllers, Analog Controllers, Programmable Controllers, Hybrid Controllers Technology: Hysteresis Control, Pulse Width Modulation, Field-Oriented Control, Direct Torque Control End User: Automotive OEMs, Consumer Electronics, Industrial Automation, Renewable Energy Installation: Embedded Systems, Standalone Units, Modular Designs, Integrated Solutions |
| Companies Covered | Infineon Technologies AG, Texas Instruments, Nidec Corporation, STMicroelectronics, Bosch Rexroth AG, ABB Ltd, Allied Motion Technologies Inc., Delta Electronics, Inc., Maxon Motor AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brush Motor Control Unit Market Strategic Shifts
Digital control architectures are displacing analog dominance as software-defined functionality becomes baseline across automotive and renewable energy installations. Three interconnected developments are compressing product lifecycles and restructuring supplier value capture.
Model-predictive current control is automating torque ripple suppression in fractional-horsepower industrial drives. Packaging machinery OEMs in Germany and Japan are adopting these algorithms to meet energy efficiency targets without mechanical redesign. The technology is compressing the performance gap between brushed and brushless systems in cost-sensitive automation segments.
REACH substance restrictions on leaded solder and cadmium-plated terminals are forcing material transitions in terminal plating and PCB finishing. Controller manufacturers serving European automotive and appliance markets must requalify supply chains for compliant alternatives. This regulatory pressure is accelerating consolidation among plating specialists capable of tin-bismuth and nickel-palladium-gold processes.
Specification authority is migrating from distributor technical sales teams toward OEM platform engineering groups with direct semiconductor relationships. Automotive and appliance manufacturers now source reference designs and program firmware in-house, treating motor control modules as configurable subsystems rather than finished components. This pattern is most pronounced in Germany and Japan, where vertical engineering integration remains strongest.
Brush Motor Control Unit Market Segmentation
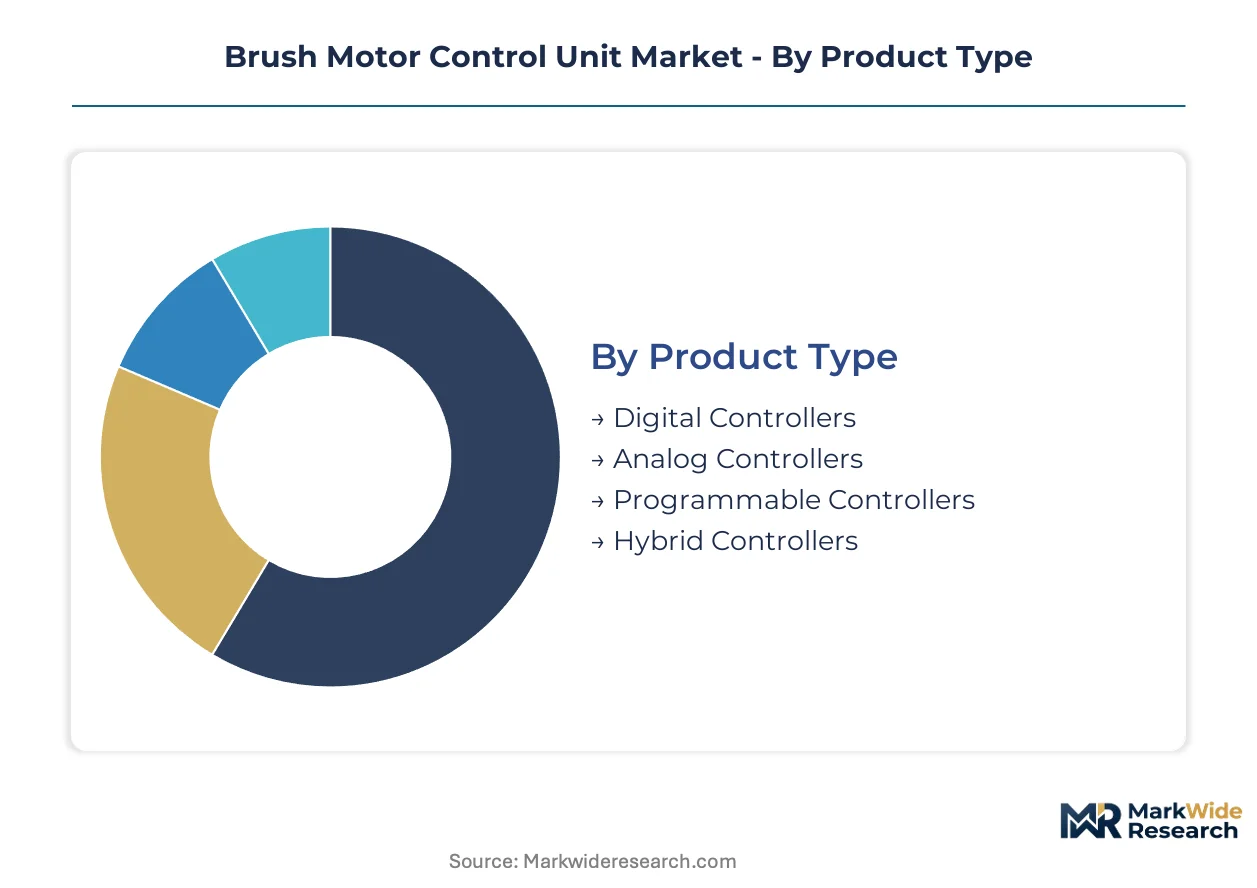
Brush motor control unit architectures fragment across four critical dimensions that determine design priorities, qualification protocols, and margin structures. Product type and technology selections drive semiconductor content and software development intensity, while end-user concentration shapes geographic demand patterns and regulatory compliance requirements.
Product Type:
Capital intensity escalates sharply from legacy analog architectures through software-defined digital platforms, with programmable variants demanding the heaviest upfront firmware investment.
- Digital Controllers:Microcontroller-based architectures with embedded PWM generators and ADC channels enable software-defined torque profiles and diagnostic telemetry. Automotive OEMs in Germany specify these for electric power steering modules where ISO 26262 functional safety compliance is mandatory. The EU F-Gas Regulation's compressor electrification mandates are accelerating specification shifts from analog alternatives.
- Programmable Controllers:Flash-memory-based units with field-upgradable firmware support application-specific parameter sets without hardware redesign. Industrial automation clusters in Japan and Germany deploy these for precision servo systems requiring rapid control loop tuning. The capital burden of qualification and toolchain development concentrates supply among semiconductor-integrated module providers.
- Analog Controllers:Discrete op-amp and comparator circuits with fixed switching frequencies dominate budget-tier power tools and small appliances where bill-of-materials compression outweighs feature complexity.
- Hybrid Controllers:Mixed-signal architectures combine analog power stages with digital supervision logic for cost-optimized automotive auxiliary motor applications.
Most installed capacity flows through Analog Controllers. Expansion is steepest in Digital Controllers.
Technology:
Algorithm sophistication determines energy recovery capability, torque ripple suppression, and semiconductor switching losses across end-use applications.
- Field-Oriented Control:Coordinate transformation algorithms decouple torque and flux components to enable regenerative braking and energy recovery. Warehouse automation OEMs in Germany and material handling equipment manufacturers specify these for battery-powered forklifts where duty cycle efficiency determines operating economics. The control complexity demands 32-bit DSP or ARM Cortex-M4 class processors.
- Pulse Width Modulation:Fixed-frequency voltage chopping at 15-50 kHz balances thermal dissipation against audible noise in fractional-horsepower drives. HVAC compressor manufacturers across the EU adopt enhanced PWM variants with variable dead-time insertion to meet Ecodesign efficiency targets.
- Hysteresis Control:Variable-frequency current regulation with minimal hardware complexity serves cost-sensitive appliance motor applications where precise speed control is secondary to startup reliability.
- Direct Torque Control:Lookup-table-based switching state selection delivers rapid torque response without current regulators in high-dynamic-performance industrial spindle drives.
Field-Oriented Control commands the highest average selling prices. Hysteresis Control maintains volume leadership in emerging market appliance production.
End User:
Customer concentration and qualification rigor separate automotive-grade specifications from consumer electronics commodity procurement.
- Automotive OEMs:Tier-1 suppliers source custom-programmed modules with proprietary firmware for electric power steering, HVAC compressors, and seat adjustment mechanisms. NHTSA electromagnetic compatibility requirements and crashworthiness protocols extend development cycles substantially.
- Industrial Automation:Packaging machinery and textile equipment manufacturers in India's PLI-incentivized automation sector specify precision servo control with fieldbus connectivity.
- Consumer Electronics:Cordless power tool and small appliance brands prioritize bill-of-materials compression over diagnostic features, sourcing analog controllers through distribution.
- Renewable Energy:Solar tracking and small wind turbine applications specify extended temperature range operation and moisture ingress protection.
Automotive OEMs absorb the majority of R&D investment. Industrial Automation is gaining share fastest among specification-intensive segments.
Installation:
Physical integration depth determines thermal management architecture, electromagnetic shielding requirements, and supply chain configuration.
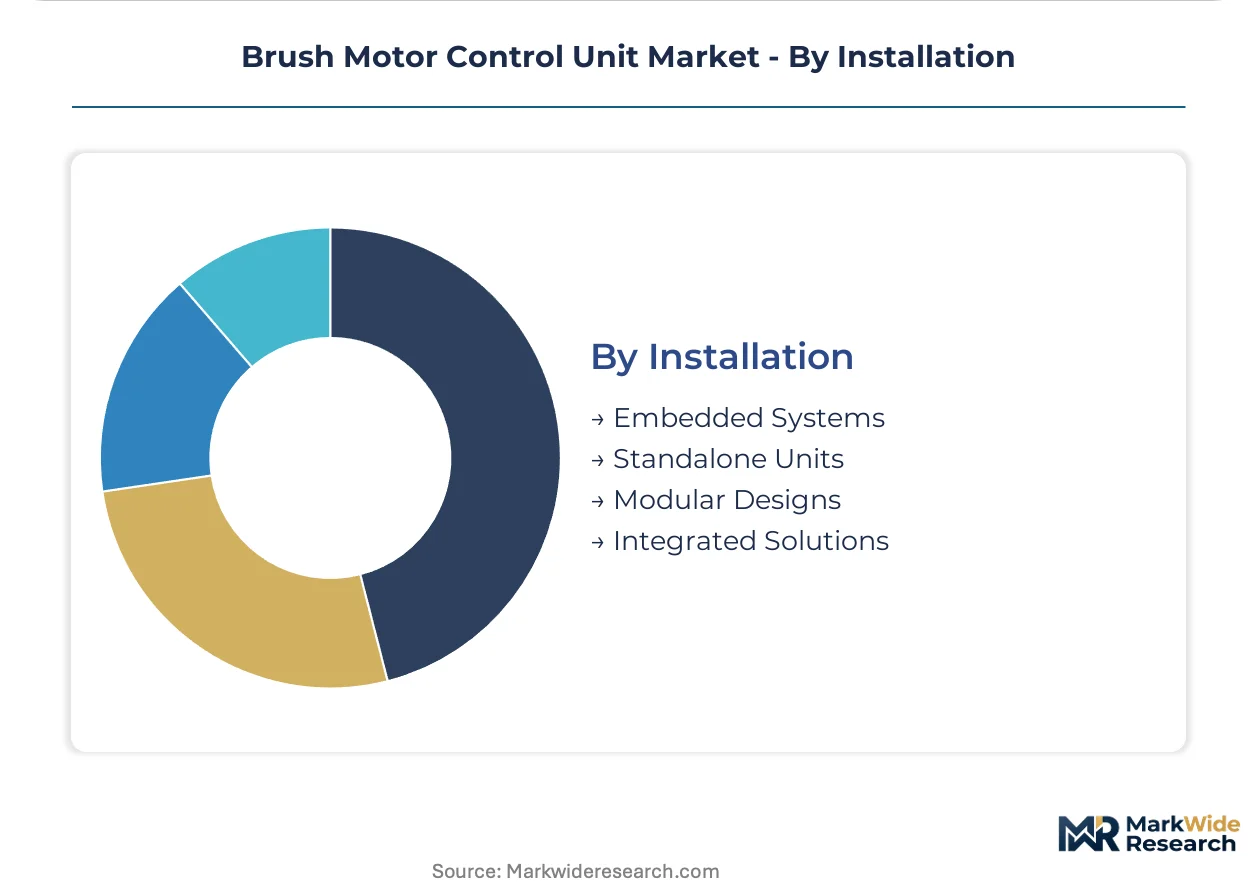
- Embedded Systems:Controller PCBs mounted directly within motor housings eliminate wiring harnesses and connector costs. Automotive HVAC compressor modules from German Tier-1 suppliers adopt this architecture to reduce assembly labor.
- Standalone Units:DIN-rail or panel-mounted enclosures with terminal blocks serve retrofit industrial automation applications requiring protocol translation from legacy analog systems.
- Modular Designs:Pluggable power stage and control logic subassemblies enable field service replacement without full system shutdown in material handling equipment.
- Integrated Solutions:Motor-control-encoder combinations with pre-tuned parameters ship as complete subsystems to appliance OEMs lacking in-house motor control expertise.
Embedded Systems dominate new automotive platform designs. Standalone Units retain installed base replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specification authority for precision motor control systems, while China scales production capacity for power semiconductor components that underpin controller architectures worldwide.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich drive demand for ISO 26262-compliant electric power steering controllers. The EU F-Gas Regulation compels HVAC compressor electrification, forcing redesigns toward digital motor control architectures. Industrial automation clusters in Bavaria specify field-oriented control systems for packaging machinery.
China
MIIT industrial electrification directives and dual carbon goals accelerate factory automation adoption across Yangtze River Delta manufacturing hubs. GB standards for motor efficiency elevate compliance costs for controller imports. Shenzhen and Shanghai semiconductor foundries expand IGBT capacity for domestic motor control module production.
United States
NHTSA electromagnetic compatibility requirements tighten qualification protocols for automotive-grade motor controllers serving Detroit-area OEMs. EPA efficiency standards for fractional horsepower motors reshape HVAC and refrigeration control specifications. Texas-based integrated circuit designers anchor supply for small-appliance motor driver portfolios.
Japan
METI energy efficiency targets push industrial equipment OEMs toward regenerative braking and field-oriented control adoption. Precision servo system demand concentrates in Nagoya-area automotive component manufacturing. JIS standards convergence with REACH substance restrictions forces material transitions in terminal plating processes.
India
PLI scheme incentives for manufacturing automation equipment open specification windows for textile and packaging machinery controllers in Gujarat and Maharashtra. BIS motor efficiency standards elevate import compliance requirements. Chennai and Pune industrial clusters drive demand for cost-optimized analog control solutions.
Brush Motor Control Unit Market Competitive Environment
German and Japanese producers anchor the premium-tier specification channel; Taiwanese and Chinese fabricators hold volume production capacity for consumer electronics applications. Market structure bifurcates between semiconductor-integrated module providers and discrete-component specialists serving retrofit industrial markets. Three archetypes dominate: captive power semiconductor suppliers, vertically integrated motor manufacturers, and fabless controller design houses. Capacity expansion in East Asian foundries and direct OEM contracting relationships constitute the primary competitive vectors reshaping supplier positioning.
Among semiconductor-integrated providers, Infineon Technologies AG and Texas Instruments occupy positions that exemplify the captive supply archetype, leveraging in-house fabrication to secure automotive-grade controller specifications. Nidec Corporation represents the vertical integration model, extending magnetics expertise into control electronics for precision servo applications. These three anchors illustrate how technology ownership depth separates premium-tier competitors from distribution-dependent commodity suppliers.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Texas Instruments |
| Nidec Corporation |
| STMicroelectronics |
| Bosch Rexroth AG |
| ABB Ltd |
| Allied Motion Technologies Inc. |
| Delta Electronics, Inc. |
| Maxon Motor AG |
| Others |
Value Chain & Pricing Dynamics
Field-oriented control algorithm adoption is simultaneously elevating semiconductor content costs and concentrating procurement leverage among automotive OEMs with direct foundry relationships. This technology transition compresses margins for analog controller specialists while rewarding integrated module providers with captive silicon supply.
Pricing Analysis
Capacity additions in China and Taiwan are reshaping price floors for IGBT and MOSFET power stages that dominate controller bill-of-materials. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified automotive modules from industrial-grade programmable units and commodity analog controllers. Price differentiation hinges on certification grade and volume scale, with automotive OEMs absorbing premium pricing for functional safety compliance while consumer electronics buyers drive cost compression in the economy tier. Pricing pressure stems from raw material volatility in copper magnet wire and rare-earth magnet inputs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tier-1 automotive suppliers, while distribution networks serve fragmented industrial automation and consumer electronics procurement. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with controller assembly gravitating toward Germany and Japan for premium-tier specifications. Raw material dependencies span silicon wafers, copper magnet wire, and epoxy molding compounds. Single-source vulnerability in advanced IGBT sourcing from Taiwanese foundries creates exposure for automotive qualification timelines. Distribution runs through specialized electronics distributors and direct semiconductor relationships for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brush Motor Control Unit Market functions as a stable compounder anchored by automotive electrification mandates that institutionalize replacement demand across vehicle platforms. Regulatory tailwinds in the EU, China, and India create sustained specification windows for precision motor control architectures.
For Market Incumbents: To counter brushless motor substitution in cordless power tools and small appliances, deepen captive supply of power semiconductors through foundry partnerships in East Asia, and accelerate ISO 26262 ASIL-D certification investment to defend automotive specification share against emerging module providers. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and France opens a window for compressor electrification controllers in HVAC retrofit applications. Target India's PLI-incentivized textile and packaging machinery automation with cost-optimized programmable controllers. Pursue direct OEM engineering relationships rather than distributor-dependent channels to bypass incumbent lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among analog controller specialists facing technology obsolescence pressure. The 5-10 year viability window favors semiconductor-integrated module providers with automotive qualification depth. Watch for inflection in direct OEM contracting patterns as the signal for consolidation timing among Tier-2 controller suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Secures IGBT supply from Taiwan and South Korea for automotive qualification pipelines. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D compliance opens electric power steering specifications at German OEMs. |
| Direct OEM Engineering Engagement | Bypasses distributor intermediaries to capture proprietary firmware programming relationships. |
| Regenerative Braking Control Development | Field-oriented control integration targets warehouse automation OEMs in Germany and Japan. |
| Material Compliance Transition | REACH-compliant tin-bismuth plating maintains European automotive and appliance market access. |
Study Parameters
Direct dialogue with Tier-1 automotive procurement managers, industrial automation plant engineers, semiconductor foundry planning officers, and motor control firmware architects grounded the qualitative foundation. Secondary validation drew from EPA efficiency standard filings, EU F-Gas Regulation implementation documents, MIIT industrial electrification directives, SEC 10-K disclosures from listed component suppliers, and customs trade data for power semiconductor imports. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the projection horizon.
Segmentation outputs reflect discrete modeling across product type, control technology, end-user concentration, and installation architecture dimensions. The analytical framework incorporated automotive content-per-vehicle trajectories, industrial automation capex cycles, and appliance production forecasts throughout the modeling period. CAGRs derived from regression analysis of historical semiconductor content trends and regulatory compliance cost escalations, with cross-validation against OEM platform rollout schedules.
Revisions become necessary when semiconductor foundry capacity expansion timelines shift, automotive functional safety certification protocols tighten, or raw material cost trajectories diverge from base assumptions. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology substitution thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Fluid Conveyance Products Motors Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Starter Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Large Synchronous Motor Market