
 North America Freight Brokerage Market | 2026-2036
North America Freight Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freight Brokerage Market Insights
The shift from in-house fleet ownership toward outsourced freight procurement is consolidating across North American supply chains. C.H. Robinson Worldwide leverages its digital freight platform to sustain density across major trade lanes. Total Quality Logistics anchors its position through specialized heavy-haul and project cargo expertise.
Freight brokerage denotes the intermediation of truck capacity between shippers and motor carriers, typically executed via load boards, transportation management systems, and API-enabled matching algorithms that optimize route density and equipment utilization. Full truckload brokerage commands the largest revenue pool due to consistent contract volumes from automotive and food manufacturers, while cloud-based matching platforms represent the fastest-expanding technology segment as shippers prioritize real-time visibility. Less than truckload services retain stable margins in urban last-mile corridors where carrier consolidation limits direct shipper alternatives.
The US DOT enforces hours-of-service regulations and electronic logging device mandates that constrain carrier supply and amplify broker intermediation value. FMCSA compliance requirements around broker surety bonds and transparency rules shape market access thresholds for new entrants. Stakeholders must monitor how cross-border customs modernization and autonomous truck pilot programs recalibrate the broker-carrier power balance.
Market Dynamics
The US DOT hours-of-service enforcement and FMCSA electronic logging device mandates are compressing carrier supply, amplifying broker intermediation value as shippers face sustained capacity tightness across major freight corridors.
Growth Catalysts
- E-commerce fulfillment surge:Retailers expanding outsourced logistics procurement to manage seasonal volume spikes and multi-node distribution requirements across Texas-Mexico manufacturing clusters.
- FMCSA compliance thresholds:Broker surety bond and transparency rules elevating market access barriers, concentrating intermediation among established operators with regulatory infrastructure.
- Real-time visibility platforms:Cloud-based matching algorithms optimizing route density and equipment utilization, reducing deadhead miles for contracted automotive and food manufacturing shippers.
Market Restraints
- Carrier supply concentration:Small fleet bankruptcies and driver retention challenges limiting truck availability during peak demand windows, forcing rate volatility absorption by brokers.
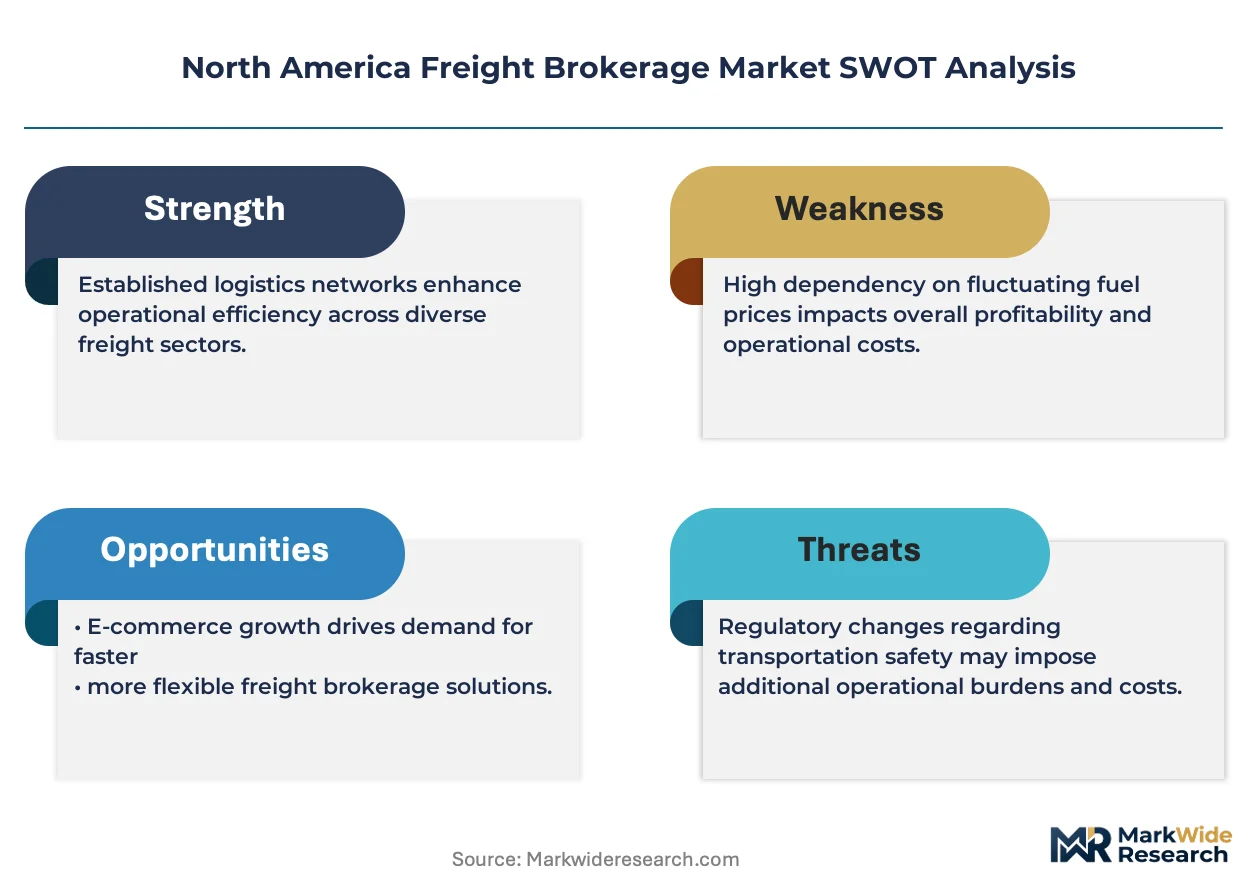
- Diesel price input volatility:Fuel cost pass-through mechanisms creating margin compression when hedge positions misalign with spot market movements.
- Cross-border customs friction:Inspection delays at Laredo and Otay Mesa corridors disrupting just-in-time manufacturing schedules and eroding broker service reliability metrics.
Strategic Opportunities
- Autonomous truck pilot corridors:Texas and Arizona permitting programs creating first-mover positioning for brokers integrating self-driving capacity into lane-specific service offerings.
- Project cargo specialization:Heavy-haul and over-dimensional freight expertise commanding premium positioning in energy infrastructure and renewable component logistics.
- Mexico nearshoring acceleration:Manufacturing relocation from Asia to Monterrey and Guadalajara expanding cross-border contract volumes requiring bilingual brokerage operations.
Industry Challenges
- Transportation management system integration:Legacy shipper ERP platforms requiring costly API development for real-time data exchange, delaying digital freight adoption timelines.
- Claims and cargo liability expertise:Specialized insurance negotiation and loss prevention capabilities scarce among mid-sized brokerages competing on price.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freight Brokerage Market |
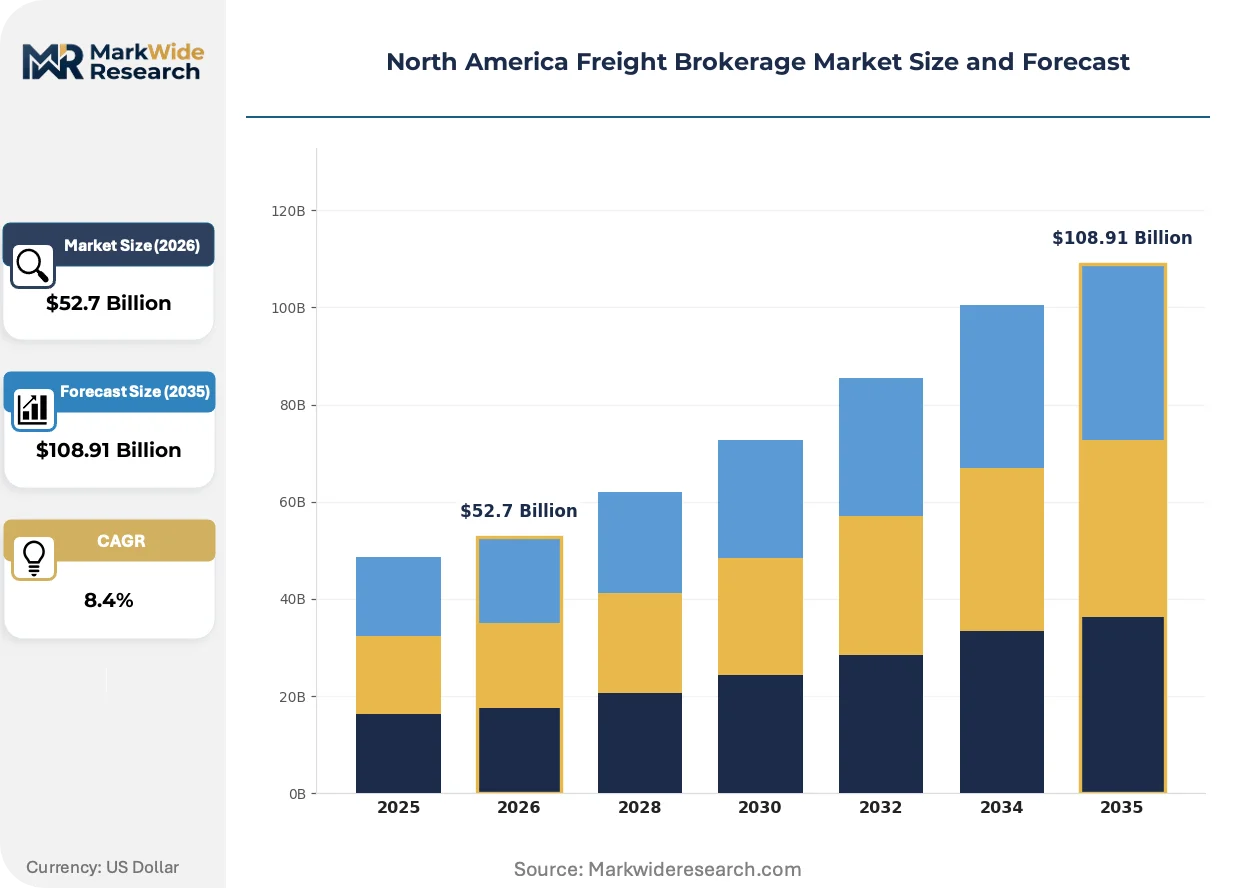
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less than Truckload, Intermodal, Expedited Customer Type: Manufacturers, Retailers, Distributors, Wholesalers Technology: Cloud-Based, TMS, EDI, Blockchain Contract Type: Spot Market, Long-Term Contracts, Dedicated Contracts, Freight Forwarding |
| Companies Covered | C.H. Robinson Worldwide, Total Quality Logistics, XPO, RXO, J.B. Hunt ICS, Schneider, Echo Global Logistics, Landstar System, Uber Freight, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freight Brokerage Market Trends and Innovations
Digital freight matching is compressing traditional broker-carrier relationships while regulatory transparency mandates reshape competitive positioning across North American logistics networks.
API-enabled load boards is rewriting how truck capacity gets priced and committed. Mid-sized food manufacturers and automotive suppliers are adopting these platforms fastest, migrating from phone-based dispatch to algorithmic matching. The technology is rewriting rate discovery mechanics, compressing bid-ask spreads and forcing traditional brokers to differentiate through specialized services rather than information asymmetry.
The US DOT electronic logging device mandate and FMCSA hours-of-service enforcement are constraining available driving hours across the for-hire trucking fleet. Carrier compliance costs have elevated operating thresholds, pushing small operators toward broker networks rather than direct shipper contracts. The less-than-truckload segment in dense urban corridors faces the tightest capacity pressure, with brokers capturing expanded margin through consolidation services.
Shippers are unbundling transportation management from integrated 3PL contracts, opting for modular broker relationships with specialized lane expertise. Direct carrier contracting is losing share to digital intermediaries offering real-time visibility and flexible capacity scaling. The cross-border automotive supply chain between Michigan and Mexico exhibits this pattern most acutely, where OEMs prioritize broker-managed capacity over captive fleet investment.
North America Freight Brokerage Market Segmentation
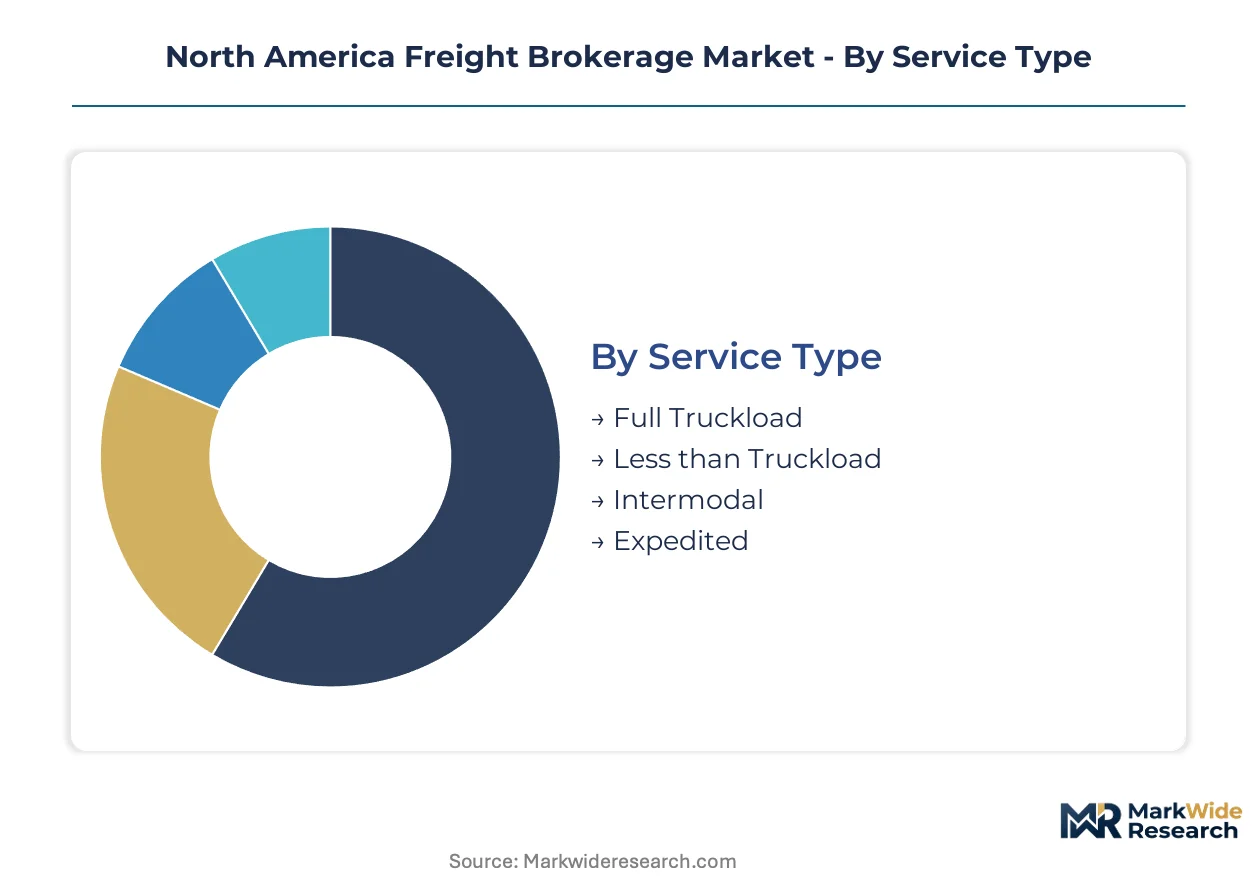
Freight brokerage segmentation reveals how intermediation value concentrates across service modalities, customer procurement patterns, and technology adoption curves. Understanding these divisions exposes where broker margins expand under capacity constraints and regulatory pressure.
Service Type:
Transportation mode dictates equipment requirements, route density economics, and margin capture potential across North American corridors.
- Full Truckload:Dedicated trailer capacity for single-shipper loads moving direct from origin to destination without intermediate handling. Automotive manufacturers and food processors in Michigan-Texas-Mexico lanes sustain contract volumes that amortize broker network investments across high-frequency lanes.
- Less than Truckload:Consolidated freight from multiple shippers sharing trailer space, requiring terminal infrastructure and precise load sequencing. Urban last-mile corridors in California and Northeast megaregions concentrate demand where carrier consolidation limits direct shipper alternatives, preserving broker intermediation value.
- Intermodal:Rail-truck combinations leveraging Class I railroad networks for long-haul segments with drayage at endpoints. Chicago and Memphis intermodal ramps anchor volume.
- Expedited:Time-critical capacity procurement for production line-down scenarios and medical supply chains. Premium rate structures compensate for asset intensity.
Full Truckload leads on scale; Expedited leads on momentum.
Customer Type:
Procurement sophistication and volume predictability shape broker relationship structures and pricing mechanisms across shipper categories.
- Manufacturers:Industrial shippers with scheduled production outputs requiring synchronized inbound materials and outbound finished goods movement. Automotive OEMs and appliance producers in Mexico nearshoring zones generate cross-border contract volumes demanding bilingual brokerage operations and customs documentation expertise.
- Retailers:Seasonal volume spikes from e-commerce fulfillment and promotional cycles driving outsourced logistics procurement. Texas-Mexico manufacturing clusters feed distribution centers with just-in-time replenishment requirements that strain in-house fleet capacity.
- Distributors:Intermediate inventory holders managing SKUs across multiple supplier relationships. Procurement patterns favor TMS-integrated broker networks.
- Wholesalers:Bulk commodity movers with lower shipment frequency but higher per-load value concentration. Price sensitivity elevates spot market participation.
Manufacturers anchor revenue concentration; Retailers are expanding most quickly.
Technology:
Digital infrastructure determines matching efficiency, visibility depth, and API integration capabilities that separate competitive tiers.
- Cloud-Based:API-enabled platforms executing algorithmic carrier-shipper matching without proprietary hardware investment. Real-time rate discovery and automated tendering compress traditional broker information advantages while expanding addressable shipper segments among mid-sized food manufacturers migrating from phone-based dispatch.
- TMS:Transportation management systems embedding brokerage functionality within broader supply chain orchestration suites. Enterprise shippers in automotive verticals prioritize modular procurement relationships with specialized lane expertise over integrated 3PL contracts.
- EDI:Electronic data interchange protocols maintaining legacy connectivity with established shipper ERP platforms. Compliance requirements sustain incumbent positioning.
- Blockchain:Distributed ledger applications for documentation integrity and smart contract execution in cross-border corridors. Pilot programs concentrate at Laredo and Otay Mesa customs modernization initiatives.
Cloud-Based platforms gain share fastest; TMS retains enterprise anchoring.
Contract Type:
Commitment duration and capacity exclusivity arrangements calibrate risk allocation between shippers, brokers, and underlying carriers.
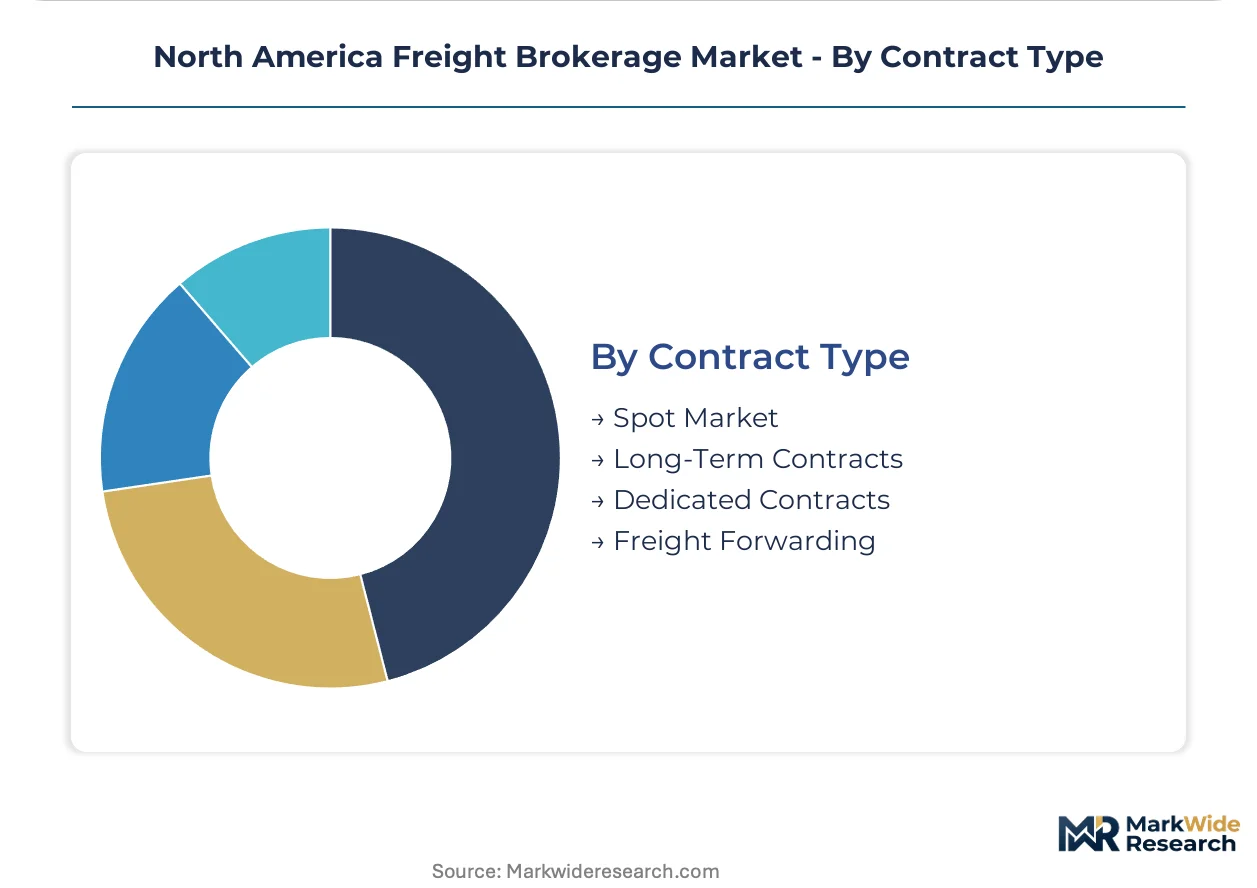
- Spot Market:Transactional capacity procurement for unplanned shipments and volume overflow, priced against real-time supply-demand imbalances. Rate volatility absorption by brokers concentrates margin in peak windows when small fleet bankruptcies and driver retention challenges constrain truck availability.
- Long-Term Contracts:Annual or multi-year rate agreements securing baseline capacity commitments across defined lane networks. Food manufacturers and automotive suppliers prioritize cost predictability over flexibility.
- Dedicated Contracts:Exclusive equipment and driver allocation for single-shipper accounts, blending asset-light brokerage with performance guarantees. Energy infrastructure project cargo commands premium positioning.
- Freight Forwarding:International multimodal coordination extending beyond North American surface transportation into ocean and air cargo. Customs brokerage integration differentiates providers.
Long-Term Contracts dominate revenue stability; Spot Market shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Mexico manufacturing corridor anchors freight brokerage demand across North American surface transportation networks. Cross-border capacity procurement concentrates in Laredo and Otay Mesa customs zones where automotive and electronics shippers require bilingual brokerage operations. Regulatory modernization and nearshoring acceleration are redrawing lane density economics.
United States
Automotive OEMs in Michigan and electronics manufacturers in California drive contract freight volumes through major interstate corridors. The US DOT enforces hours-of-service regulations and electronic logging device mandates that constrain carrier supply and amplify broker intermediation value. Chicago and Memphis intermodal ramps anchor rail-truck combinations for long-haul freight movement.
Mexico
Manufacturing relocation from Asia to Monterrey and Guadalajara expands cross-border contract volumes requiring specialized customs documentation expertise. The Mexican government's nearshoring incentive programs accelerate industrial park development in Nuevo León. Laredo processes the highest commercial truck volume of any US-Mexico border crossing.
Canada
Energy infrastructure and agricultural commodity exporters in Alberta and Saskatchewan generate heavy-haul and project cargo demand. Transport Canada harmonizes cross-border safety regulations with US FMCSA standards to facilitate integrated North American fleet operations. The Windsor-Detroit corridor remains the busiest Canada-US commercial crossing for automotive parts.
North America Freight Brokerage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital freight matching and API-enabled visibility platforms. The market structure concentrates intermediation value among operators with regulatory infrastructure and lane-specific density. Three archetypes dominate: asset-light digital platforms, specialized heavy-haul brokers, and integrated transportation management providers. Competitive moves center on technology licensing partnerships and geographic expansion into Mexico nearshoring zones.
Within the integrated logistics tier, C.H. Robinson Worldwide and Total Quality Logistics occupy positions representing scale-driven network density and specialized project cargo expertise respectively. XPO exemplifies the transportation management system-anchored archetype. These entities sit within a competitive set where digital matching algorithms compress traditional information advantages while regulatory compliance thresholds elevate barriers for new entrants.
| Leading Market Players |
|---|
| C.H. Robinson Worldwide |
| Total Quality Logistics |
| XPO |
| RXO |
| J.B. Hunt ICS |
| Schneider |
| Echo Global Logistics |
| Landstar System |
| Uber Freight |
| Others |
Pricing and Supply Chain Analysis
US DOT emissions compliance thresholds for Class 8 trucks gate qualified carrier supply and premium-tier broker pricing access, as shippers with sustainability mandates pay margin premiums for carriers meeting CARB and EPA certification tiers.
Pricing Analysis
Input-cost pass-through mechanics dominate freight brokerage economics, with diesel price volatility and driver wage inflation flowing through to shipper invoices via fuel surcharge indices and accessorial fees. Contract pricing stratifies across dedicated capacity commitments, committed contract volumes, and spot market transactional tiers, with automotive OEMs showing least price sensitivity due to line-down risk while wholesale commodity shippers drive hardest rate negotiations. Pricing pressure stems from small fleet bankruptcies concentrating carrier supply among larger broker networks. Cross-border customs delays at Laredo erode service reliability premiums, compressing margins on Mexico-bound lanes.
Supply Chain Analysis
Dual-sourcing requirements from automotive and food manufacturing shippers mandate multi-carrier qualification across Texas, Mexico, and Midwest corridor networks, preventing single-source dependency. The supply chain draws from US owner-operator pools, Mexican cross-border carriers, and Canadian long-haul fleets as primary capacity sources. Diesel fuel, driver labor, and trailer equipment constitute the critical input dependencies. Tariff exposure on steel and aluminum trailer components creates equipment procurement risk. Distribution runs through Chicago and Memphis intermodal ramps, with drayage and final-mile trucking completing delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America freight brokerage market presents a late-cycle quality story, with e-commerce fulfillment complexity and FMCSA compliance mandates shifting procurement toward premium-tier digital intermediaries with regulatory infrastructure.
For Market Incumbents: Anticipate margin compression from digital freight platforms by deepening API integration with shipper TMS systems and securing bilingual operations in Monterrey and Guadalajara nearshoring zones. Invest in autonomous truck pilot corridor relationships in Texas and Arizona to capture first-mover positioning as self-driving capacity enters lane-specific service offerings. Carrier supply concentration and driver retention challenges threaten rate volatility absorption capacity. For New Entrants and Emerging Players: API-enabled load board technology offers a technology-first wedge into mid-sized food manufacturer and automotive supplier segments migrating from phone-based dispatch to algorithmic matching. Target cross-border customs documentation services as the most penetrable white-space, where established brokers lack bilingual expertise. Pursue lane-specific density strategies in California-Nevada urban last-mile corridors before attempting national scale. For Investors and Strategic Acquirers: Roll-up economics work for specialized heavy-haul and project cargo brokers because energy infrastructure and renewable component logistics command premium positioning with limited digital disruption risk. The long-term viability window favors asset-light platforms with regulatory compliance infrastructure over pure technology plays. Watch autonomous truck permitting acceleration in Texas and Arizona as the signal for broker-carrier power balance inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Cloud-based matching algorithms from digital platforms compress traditional broker information advantages fastest. |
| Geographic Expansion | Bilingual brokerage operations in Nuevo León capture Mexico nearshoring acceleration from Asia manufacturing relocation. |
| Specialized Service Development | Heavy-haul expertise in energy infrastructure commands premium positioning against commodity truckload brokers. |
| Regulatory Infrastructure Investment | FMCSA surety bond and transparency compliance elevates barriers against unqualified market entrants. |
| Carrier Network Density Build | Route density optimization across Texas-Mexico manufacturing clusters amortizes fixed network investments. |
Research Methodology
Multiple input streams — structured interviews with freight brokerage operations executives, carrier fleet managers, and shipper procurement directors, alongside FMCSA regulatory filings, US DOT freight flow databases, and customs trade records — were reconciled through bottom-up volume modeling and top-down market sizing triangulation. Primary fieldwork captured lane-specific rate dynamics and technology adoption patterns across automotive, food manufacturing, and retail verticals. Secondary validation drew from carrier operating authority databases, transportation management system vendor disclosures, and cross-border customs modernization program documentation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service modality, customer procurement sophistication, technology infrastructure, and contract commitment duration. CAGRs were derived from trend extrapolation of outsourced logistics penetration rates and e-commerce fulfillment volume growth, calibrated against carrier supply constraints from hours-of-service enforcement and electronic logging device mandates. Forecast inputs incorporated nearshoring acceleration timelines and autonomous truck pilot program expansion scenarios.
The model holds under sustained FMCSA compliance enforcement and diesel price volatility within historical bands; deviation in cross-border trade policy or accelerated autonomous truck commercialization would shift the outlook materially. Forecasts reflect assumptions regarding carrier retention challenges and shipper unbundling of transportation management from integrated 3PL contracts. Deviation in Mexico manufacturing relocation velocity or US-Mexico customs modernization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Rail Logistics Market
Logistics and Shipping
Myanmar Freight and Logistics Market