
 United States Freight Brokerage Market | 2026-2036
United States Freight Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Freight Brokerage Market Outlook
Digital freight matching is shifting load-booking economics away from traditional phone-and-email dispatch toward algorithmic pricing and automated carrier procurement. C.H. Robinson leverages its proprietary Navisphere platform to sustain North America's largest freight brokerage volume. Total Quality Logistics anchors its competitive position through intensive agent-based sales coverage across industrial freight lanes. XPO Logistics differentiates via integrated less-than-truckload and truck brokerage bundling for mid-market shippers.
Freight brokerage denotes the commercial arrangement wherein licensed intermediaries coordinate transportation of goods between shippers and motor carriers without assuming asset ownership, typically earning margin spreads of 10-20 percent on contracted lane rates while managing carrier compliance, cargo insurance verification, and shipment tracking. The service primarily facilitates efficient matching of irregular freight demand with available trucking capacity across fragmented national carrier networks. Full truckload brokerage dominates transaction volume due to consistent demand from manufacturing and retail replenishment cycles, while specialty freight commands premium margins from temperature-controlled and oversized cargo requirements. Intermodal brokerage gains structural momentum as rail-road combinations offer fuel efficiency on long-haul corridors exceeding seven hundred miles.
The Federal Motor Carrier Safety Administration enforces hours-of-service regulations and broker surety bond requirements that elevate compliance costs for new market entrants while reinforcing established operators with dedicated safety departments. The Surface Transportation Board retains oversight of rail-intermodal rate disputes, indirectly shaping broker pricing power on multimodal lanes. Stakeholders must monitor evolving autonomous trucking pilot programs and their potential to compress spot-market volatility that currently sustains broker intermediation value.
Market Dynamics
Digital freight matching platforms are compressing traditional broker margins by automating load-carrier pairing and collapsing the information asymmetry that once sustained phone-based dispatch operations. The FMCSA's electronic logging device mandate and broker surety bond requirements have simultaneously elevated compliance costs while accelerating platform adoption among small carriers seeking administrative relief.
Growth Catalysts
- E-commerce fulfillment networks:Amazon, Walmart, and direct-to-consumer retailers require dynamic capacity sourcing for irregular shipment volumes, driving demand for algorithmic freight matching across Texas, California, and Illinois corridors.
- FMCSA electronic logging device mandate:Hours-of-service tracking requirements push small carriers toward broker platforms that automate compliance documentation and carrier qualification verification.
- Intermodal rail-road combinations:Fuel efficiency advantages on corridors exceeding seven hundred miles attract manufacturing and retail shippers seeking cost alternatives to pure truckload brokerage.
Market Restraints
- Driver shortage concentration:The Owner-Operator Independent Drivers Association reports persistent capacity constraints in specialized freight segments, inflating spot-market volatility and broker procurement costs.
- Surety bond escalation:The FMCSA's $75,000 broker bond requirement, increased from $10,000 in 2013, creates working capital barriers for new entrants and regional specialists.
- Insurance premium volatility:Nuclear verdict trends in trucking liability litigation compress net margins for brokers managing contingent cargo and auto liability coverage.
Strategic Opportunities
- Autonomous trucking pilot corridors:Arizona, Texas, and California permit testing zones create partnership opportunities for brokers positioning as capacity aggregators for self-driving fleet operators.
- Cold-chain pharmaceutical distribution:Temperature-controlled freight for biologics and vaccines commands premium spreads and requires specialized compliance infrastructure that generalist platforms underserve.
- Small fleet digital onboarding:Owner-operators with ten or fewer trucks remain underserved by legacy broker technology stacks, representing white space for mobile-first carrier acquisition platforms.
Industry Challenges
- Talent scarcity in freight technology:Data science and platform engineering expertise concentrates at coastal technology firms, forcing Midwest-based brokers into compensation wars for digital operations talent.
- Legacy TMS integration friction:Shipper enterprise resource planning systems require expensive custom API development to connect with modern broker platforms, slowing sales cycles for mid-market accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Freight Brokerage Market |
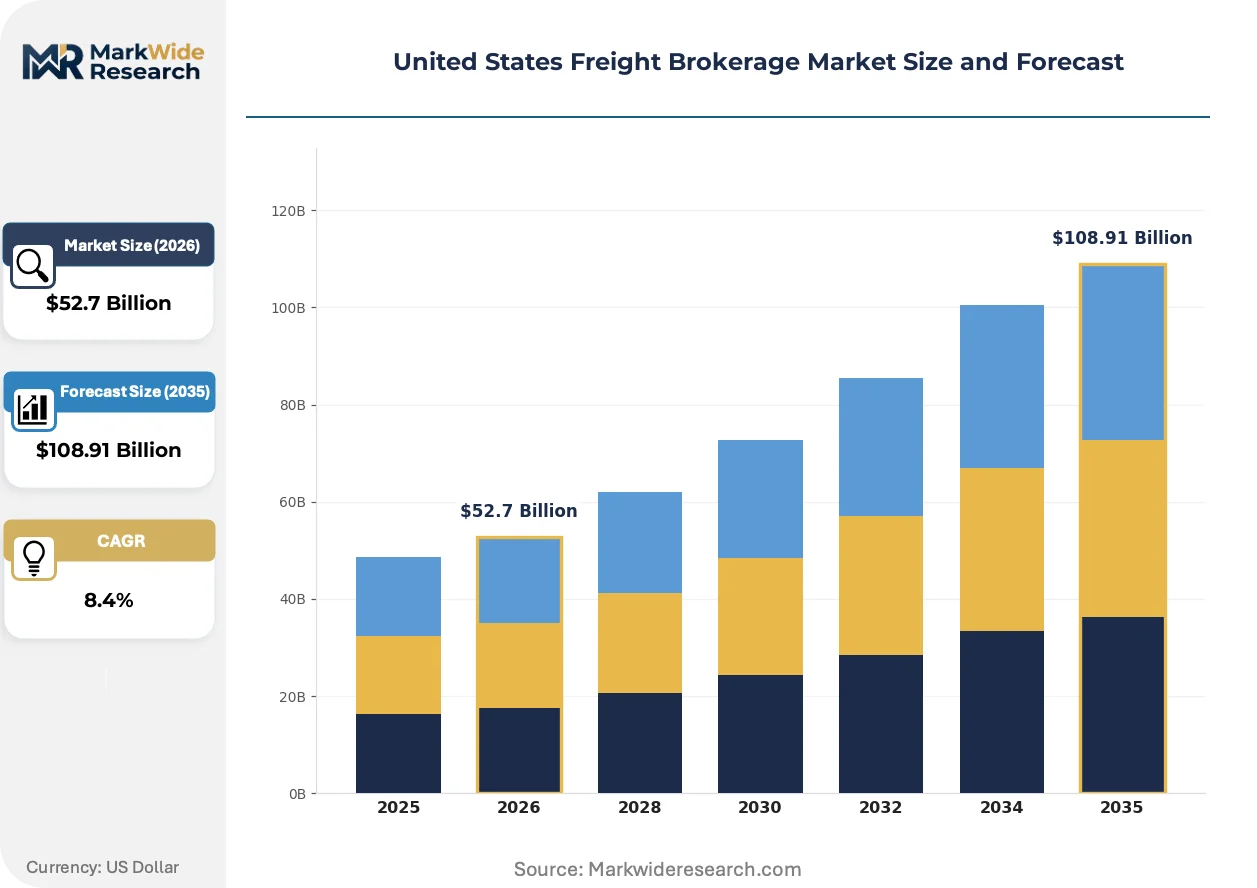
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Intermodal, Specialty Freight End User: Retail, Manufacturing, E-Commerce, Wholesale Distribution Channel: Direct, Brokers, Online Platforms, Third-Party Logistics Technology: Tracking Systems, Freight Management Software, AI Optimization, Blockchain Solutions |
| Companies Covered | C.H. Robinson, Total Quality Logistics, XPO Logistics, Echo Global Logistics, Landstar System, Hub Group, J.B. Hunt Transport Services, GlobalTranz, Arrive Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Freight Brokerage Market Strategic Shifts
Algorithmic pricing engines and automated carrier procurement are displacing relationship-based dispatch operations, while regulatory data mandates force technology infrastructure upgrades across the broker-carrier interface.
Machine learning freight pricing is expanding into spot-market rate prediction and dynamic lane optimization. Third-party logistics providers and large shippers deploy predictive models to forecast capacity tightness seventy-two hours in advance. The structural consequence is compressing the bid-ask spreads that traditional brokers extracted from information delays, forcing intermediaries to differentiate through value-added services rather than price arbitrage.
The FMCSA's broker transparency regulations require immediate disclosure of rate components to motor carriers, eliminating historical opacity in shipper-broker-carrier transactions. Small carriers gain negotiating leverage through mandated visibility into load economics. The segment most affected is mid-sized brokers dependent on margin opacity, which are responding by investing in cargo insurance, payment acceleration, and fuel advance products to justify spreads through service rather than information control.
Shippers are consolidating freight procurement through centralized transportation management systems that disintermediate smaller brokers lacking API connectivity. Manufacturing and retail verticals demand real-time visibility and predictive ETAs as table stakes. This pattern concentrates volume with technology-enabled brokers in the automotive parts and consumer packaged goods sectors, where just-in-time inventory requirements punish carrier failure with production shutdown costs.
United States Freight Brokerage Market Segmentation
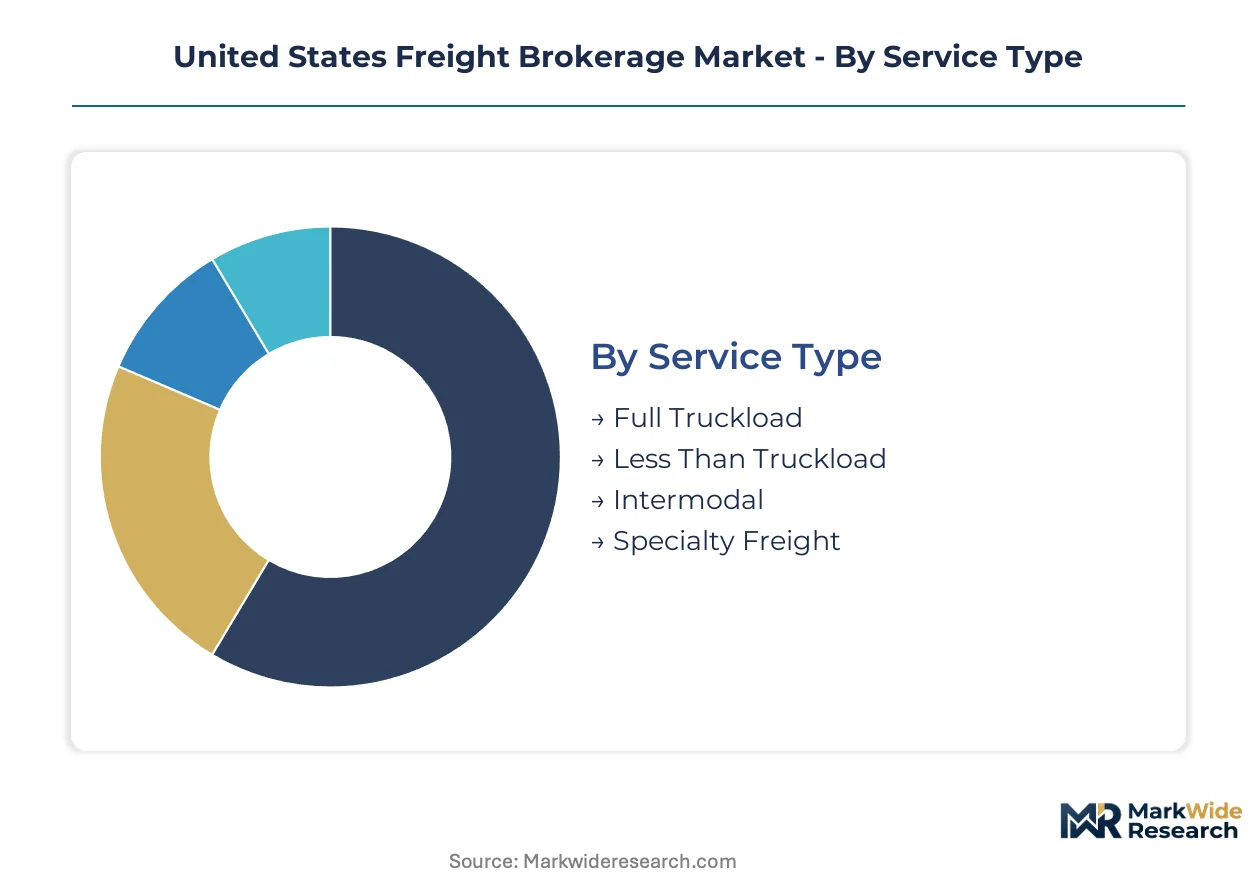
Freight brokerage segmentation reveals how service specialization, end-use concentration, and technology adoption create distinct competitive arenas. Each dimension carries unique regulatory burdens and margin structures that determine broker viability and investment priorities.
Service Type:
FMCSA broker authority and surety bond requirements apply uniformly across all service categories, though cargo insurance minimums escalate for hazardous materials and temperature-controlled shipments.
- Full Truckload:Single-shipper capacity contracts dominate transaction volume through predictable manufacturing and retail replenishment cycles. Texas, California, and Illinois corridors concentrate demand from automotive parts distributors and big-box retailers managing just-in-time inventory networks. Dry van and flatbed equipment types segment further by loading characteristics.
- Less Than Truckload:Consolidated shipments from multiple shippers require terminal infrastructure and line-haul coordination that pure brokers rarely control. E-commerce fulfillment networks in Southern California and New Jersey generate irregular volume spikes that strain traditional hub-and-spoke LTL capacity. This segment climbs fastest as shippers fragment orders across more frequent, smaller deliveries.
- Intermodal:Rail-road combinations on corridors exceeding seven hundred miles offer fuel efficiency advantages for manufacturing shippers.
- Specialty Freight:Temperature-controlled, oversized, and hazardous cargo commands premium spreads but requires specialized carrier qualification and cargo insurance verification.
Full Truckload sits at the top of the volume ranking, with Less Than Truckload climbing the fastest.
End User:
Shipper procurement sophistication varies dramatically, with enterprise retailers demanding API connectivity and predictive ETAs while smaller manufacturers accept phone-based dispatch relationships.
- Retail:Big-box and department store chains require dynamic capacity sourcing for seasonal surges and promotional inventory builds. Walmart and Target vendor compliance programs mandate specific electronic data interchange protocols and on-time delivery thresholds that filter broker eligibility.
- E-Commerce:Direct-to-consumer fulfillment networks generate irregular shipment volumes with compressed delivery windows. Amazon's logistics arm and Shopify merchants drive adoption of algorithmic freight matching across Texas and California corridors. This segment expands most quickly as last-mile injection points proliferate.
- Manufacturing:Automotive and industrial shippers prioritize reliability over spot-market savings to avoid production shutdown penalties.
- Wholesale:Distributor networks concentrate in Midwest distribution hubs with predictable lane density.
Retail commands the highest absolute brokerage spend, though E-Commerce demonstrates the steepest expansion trajectory.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics, with digital platforms compressing traditional agent-based sales models.
- Direct:Large shippers contract capacity through dedicated broker relationships bypassing intermediaries. Food and beverage manufacturers in the Midwest maintain preferred carrier lists with pre-negotiated lane rates and quarterly volume commitments.
- Brokers:Licensed intermediaries earning 10-20 percent spreads dominate spot-market transactions. Agent-based models at Total Quality Logistics and regional specialists sustain coverage across fragmented industrial freight lanes.
- Online Platforms:Digital freight matching automates load-carrier pairing and collapses information asymmetry.
- Third-Party Logistics:Integrated warehousing and transportation providers bundle brokerage with inventory management services.
Brokers retain the largest transaction share, while Online Platforms gain share fastest through small fleet onboarding.
Technology:
FMCSA electronic logging device mandates and broker transparency regulations force infrastructure investment that disadvantages technology-lagging operators.
- Tracking Systems:GPS and telematics integration provides real-time visibility into carrier location and hours-of-service compliance. Shippers in automotive and consumer packaged goods sectors treat predictive ETAs as non-negotiable procurement requirements.
- Freight Management Software:Transportation management systems centralize procurement, execution, and settlement workflows. Manufacturing verticals demand API connectivity to enterprise resource planning systems, filtering broker participation by technical capability.
- AI Optimization:Machine learning models forecast capacity tightness and dynamic lane pricing.
- Blockchain Solutions:Distributed ledger pilots target documentation automation and payment acceleration for small carriers.
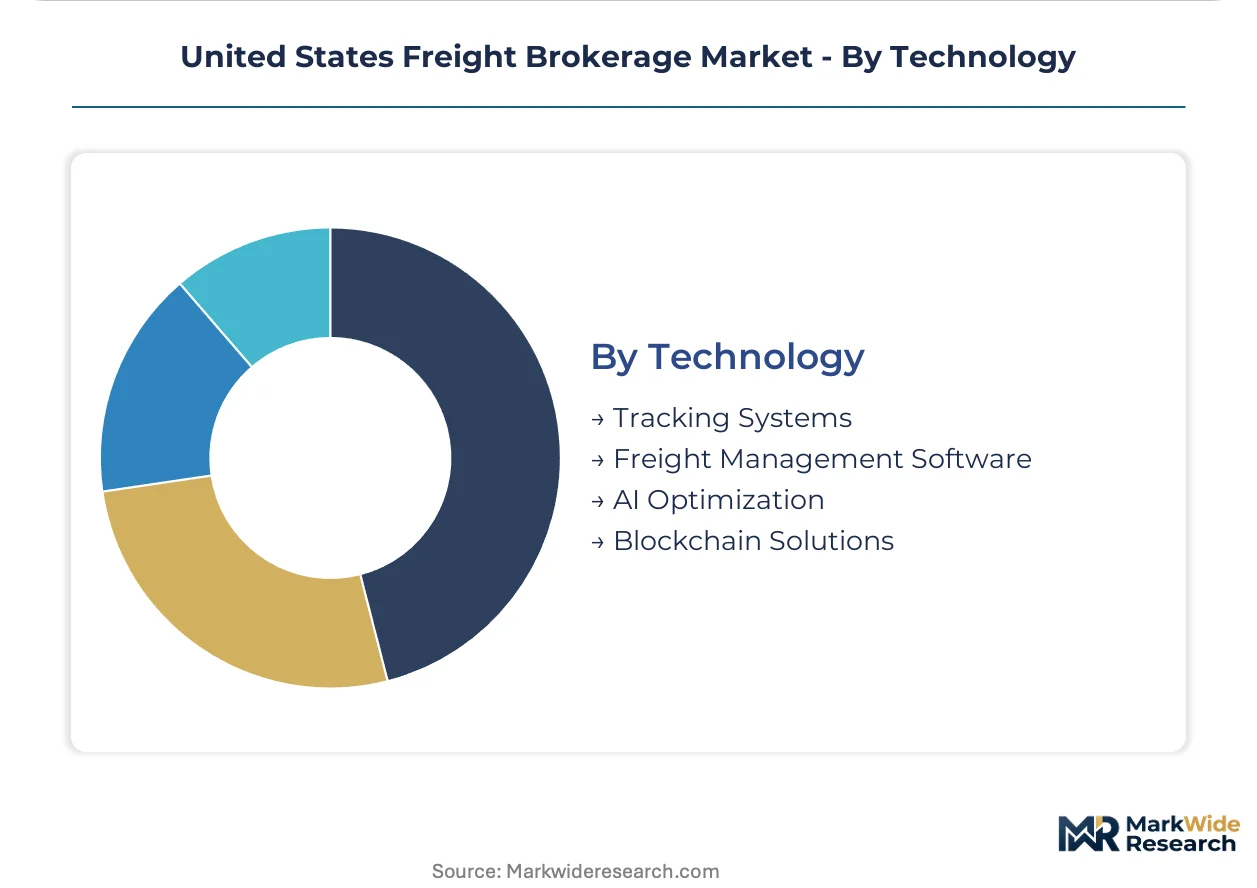
Tracking Systems sits at the top of deployment penetration, with AI Optimization climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth freight corridor anchors the United States freight brokerage market through its convergence of interstate highways, rail intermodal terminals, and e-commerce distribution centers serving Southwest and Midwest manufacturing networks.
Texas
Houston's petrochemical complexes and Dallas-Fort Worth's retail distribution hubs generate sustained full truckload demand across the I-35 and I-10 corridors. The Texas Department of Transportation's freight infrastructure investments prioritize I-35 corridor expansion to accommodate cross-border Mexico trade. Laredo and El Paso serve as primary gateway cities where brokers coordinate cross-border capacity with Mexican carriers.
California
The Ports of Los Angeles and Long Beach inject containerized freight into drayage and intermodal brokerage networks serving inland distribution centers. The California Air Resources Board's Advanced Clean Trucks regulation accelerates zero-emission fleet transitions that reshape carrier qualification requirements. The Inland Empire warehouse cluster concentrates broker activity for last-mile fulfillment serving Western states.
Illinois
Chicago's rail intermodal terminals position the state as the primary consolidation point for Midwest manufacturing shipments to East and West Coast markets. The Illinois Commerce Commission oversees rail rate disputes that indirectly shape broker pricing power on Chicago-origin intermodal lanes. Joliet and Rochelle host specialized cold-chain facilities serving pharmaceutical and food processing verticals.
Georgia
Atlanta's Hartsfield-Jackson cargo operations and Savannah's port expansion drive Southeast brokerage demand for automotive parts and retail imports. The Georgia Department of Transportation's freight and logistics plans prioritize I-75 and I-85 corridor capacity improvements. The Savannah port's deepening project attracts intermodal brokerage volume for Appalachian and Midwest reach.
Ohio
Columbus and Cincinnati distribution centers serve as Midwest fulfillment nodes for e-commerce networks requiring dynamic capacity sourcing. The Ohio Department of Transportation's smart mobility corridor initiatives test autonomous trucking applications that may reshape broker-carrier relationships. Toledo and Cleveland anchor automotive supply chain brokerage serving Detroit and Southern assembly plants.
United States Freight Brokerage Market Competitive Environment
Global majors compete with regional champions across technology platforms and agent-based coverage models, producing a tiered structure where scale-driven intermediaries face pressure from digital-native entrants. The market fragments across asset-light brokers, integrated 3PLs, and technology platforms. Three archetypes dominate: proprietary platform operators, agent-network specialists, and bundled transportation providers. Consolidation through strategic acquisitions and API-based shipper integration represent the primary competitive moves reshaping market share distribution.
Among the established platform operators, C.H. Robinson and Total Quality Logistics exemplify divergent scale strategies. C.H. Robinson anchors the technology-enabled tier through its Navisphere platform integration with large shipper ERP systems. Total Quality Logistics occupies the agent-intensive position, sustaining coverage density across fragmented industrial freight corridors. XPO Logistics represents the bundled-service archetype, combining less-than-truckload assets with brokerage capacity for mid-market accounts seeking single-source transportation procurement.
| Leading Market Players |
|---|
| C.H. Robinson |
| Total Quality Logistics |
| XPO Logistics |
| Echo Global Logistics |
| Landstar System |
| Hub Group |
| J.B. Hunt Transport Services |
| GlobalTranz |
| Arrive Logistics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up freight brokerage platforms anchor supply behavior through aggressive carrier acquisition spend while compressing pricing discipline across spot-market corridors. Their capital deployment patterns concentrate procurement technology investment in Texas and California freight lanes, reshaping margin structures for family-owned regional specialists competing on relationship-based dispatch.
Pricing Analysis
Input-cost pass-through from diesel fuel volatility and driver wage inflation shapes contract rate negotiations between shippers and brokers. Spot-market brokerage operates on per-unit transactional pricing with spreads compressing under algorithmic freight matching platforms. Price differentiation rests on cargo insurance minimums and FMCSA safety ratings, with enterprise retailers least sensitive to rate fluctuations and small manufacturers most responsive to fuel surcharge adjustments. Pricing pressure stems from digital freight platforms collapsing information asymmetry that historically sustained broker margins.
Supply Chain Analysis
Domestic-content mandates under the Federal Motor Carrier Safety Administration's broker surety bond requirements reshape carrier qualification sourcing toward US-based operators with verified authority. Supply concentrates among owner-operator networks across Texas, California, and Illinois, drawing from fragmented small fleet capacity rather than consolidated asset bases. Raw material dependencies include diesel fuel pricing, commercial auto insurance coverage, and ELD telematics infrastructure. Single-source vulnerability runs through concentrated drayage capacity at Los Angeles-Long Beach port complex. Distribution runs through digital freight matching platforms and agent-based sales networks serving distinct shipper scale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US freight brokerage constitutes a late-cycle quality story as e-commerce fulfillment networks shift procurement specifications toward real-time visibility and predictive ETAs as non-negotiable requirements.
For Market Incumbents: Extend platform API connectivity into shipper ERP systems to defend against disintermediation from centralized transportation management systems. Deepen vertical integration through captive insurance products and fuel advance services that justify margin spreads through service value rather than information control. For New Entrants and Emerging Players: Begin with mobile-first carrier acquisition targeting owner-operators with ten or fewer trucks currently underserved by legacy broker technology stacks. Focus geographic entry on Ohio and Georgia corridors where autonomous trucking pilot programs create partnership opportunities with self-driving fleet operators. For Investors and Strategic Acquirers: Valuations sit cheapest among agent-based regional specialists with dense industrial lane coverage but lagging technology infrastructure. Long-term viability across the analysis window favors platforms with demonstrated API integration capabilities and specialized compliance infrastructure for temperature-controlled freight. Watch FMCSA regulatory shifts on broker transparency enforcement as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform API Integration | Connects broker systems to shipper ERP networks at Walmart and Target, filtering participation by technical capability. |
| Specialized Carrier Acquisition | Builds cold-chain capacity for pharmaceutical distribution where temperature-controlled freight commands premium spreads. |
| Autonomous Fleet Partnership | Positions brokers as capacity aggregators for self-driving operators testing in Arizona and Texas corridors. |
| Insurance Product Bundling | Justifies margin spreads through cargo coverage and payment acceleration rather than information opacity. |
| Intermodal Rail Expansion | Captures fuel efficiency demand on corridors exceeding seven hundred miles through Chicago rail terminals. |
Study Parameters
Direct dialogue with freight brokerage operations executives, carrier procurement managers, shipper transportation directors, and FMCSA compliance officers grounded qualitative findings in operational reality. Secondary validation drew from FMCSA carrier authority databases, Surface Transportation Board rail rate filings, American Trucking Associations freight tonnage reports, and electronic logging device mandate implementation records. Bottom-up and top-down triangulation cross-checked segment-level capacity estimates against aggregate brokerage volume trends.
Bottom-up modeling aggregated carrier capacity by fleet size and equipment type across Texas, California, Illinois, Georgia, and Ohio corridors, while top-down analysis tracked shipper procurement spend by retail, e-commerce, manufacturing, and wholesale verticals. Segmentation dimensions included service type, end-use concentration, distribution channel, and technology adoption tier. CAGRs were derived from trend extrapolation of digital freight matching penetration rates and intermodal volume shifts, with forecast inputs incorporating ELD mandate compliance timelines and autonomous trucking pilot expansion patterns.
Several conditions sit outside the modeled scope, including sudden FMCSA regulatory reversals, catastrophic nuclear verdict litigation spikes, and autonomous trucking commercialization acceleration beyond pilot corridors. Forecasts reflect assumptions about carrier capacity retention and shipper procurement consolidation trajectories. A small set of named triggers warrants ongoing watch: broker surety bond requirement adjustments, diesel price volatility spikes, and platform-driven margin compression thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Big Data in Logistics Market