
 Asia-Pacific Cold Chain Logistics Market | 2026-2036
Asia-Pacific Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cold Chain Logistics Market Intelligence
Phase-change materials are rebalancing insulation economics in refrigerated transport, displacing conventional polyurethane foam in long-haul pharmaceutical lanes. DHL Supply Chain leverages its multi-temperature hub network across Singapore and Thailand to sustain pharmaceutical compliance leadership. Kerry Logistics Network Limited anchors perishable exports from Greater China through integrated warehousing and bonded cold storage. Nichirei Logistics Group dominates Japan's frozen food distribution with specialized deep-frozen infrastructure.
Asia-Pacific cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods, maintaining precise thermal parameters from minus 25 degrees Celsius for deep-frozen seafood to 2-8 degrees Celsius for vaccine distribution. The system relies on vapor-compression refrigeration, vacuum-insulated panels, and real-time telemetry to prevent thermal excursions across multimodal handoffs. Transportation services command the largest value pool due to fuel-intensive refrigerated trucking and intermodal reefer movements, while warehousing segments capture margin concentration in automated high-bay frozen storage near port gateways. IoT Solutions represent the fastest-expanding technology category as fleet operators deploy sensor networks for predictive maintenance and regulatory documentation.
Japan's METI enforces energy-efficiency standards for commercial refrigeration equipment, compelling warehouse operators to retrofit aging ammonia-based systems. India's FSSAI mandates end-to-end temperature documentation for frozen and chilled food imports, raising compliance barriers for informal logistics providers. China's SAMR implements GB standards for refrigerated vehicle construction and cold storage facility hygiene. Stakeholders must monitor diverging national certification requirements as cross-border e-commerce platforms expand fresh and frozen product assortments.
Market Dynamics
Phase-change materials and vacuum-insulated panels are compressing thermal excursion rates in pharmaceutical lanes, while METI efficiency mandates and FSSAI documentation rules force simultaneous capital deployment across Japan and India.
Growth Catalysts
- Biologics distribution expansion:Temperature-sensitive gene therapies and mRNA vaccines require minus 70 to minus 20 degrees Celsius corridors through Southeast Asia's pharmaceutical networks. Cold chain operators are building dedicated deep-frozen capacity in Singapore and Bangkok to capture this traffic.
- India's PLI scheme for food processing:The production-linked incentive program subsidizes integrated cold storage and refrigerated transport investments. Food processors in Maharashtra and Gujarat are consolidating fragmented village-level collection into hub-and-spoke networks.
- Phase-change material adoption:Salt-hydrate and paraffin-based PCMs are replacing mechanical refrigeration in last-mile vaccine delivery. These materials stabilize payloads for 72-96 hours without active cooling, enabling drone and motorcycle distribution to remote Indonesian islands.
Market Restraints
- Refrigerant input volatility:Ammonia and hydrofluorocarbon prices fluctuate with energy markets and F-Gas Regulation phase-down schedules. Japanese warehouse operators face stranded asset risk on aging ammonia systems that fail METI 2025 efficiency benchmarks.
- Specialized fleet concentration:Intermodal reefer container manufacturing concentrates in Chinese and South Korean shipyards. Lead times for pharmaceutical-grade reefers now exceed 14 months, constraining Southeast Asian pharmaceutical exporters.
- Last-mile thermal integrity gaps:Motorcycle and three-wheeler delivery lacks standardized insulated compartments. FSSAI documentation requirements expose informal operators to compliance violations across Indian urban corridors.
Strategic Opportunities
- Vietnam's underpenetrated seafood export infrastructure:The Mekong Delta lacks sufficient minus 25 degrees Celsius blast freezing capacity for pangasius and shrimp. Integrated operators can anchor export corridors through Ho Chi Minh City port.
- IoT-telemetry convergence with blockchain:Sensor networks generating immutable temperature records enable premium pricing for compliance-guaranteed lanes. Australian and Japanese pharmaceutical importers are mandating this documentation tier.
- Cross-border e-commerce fresh channels:Platforms connecting Chinese consumers to Australian beef and New Zealand dairy require bonded cold storage at Shanghai and Qingdao. Same-day delivery promises compress required inventory positioning.
Industry Challenges
- Refrigeration technician scarcity:Ammonia system specialists and cryogenic handlers command wage premiums exceeding 40% in Australian and Japanese markets. Training pipelines through vocational institutions lag fleet expansion timelines.
- Multi-temperature facility capex intensity:Automated high-bay frozen storage with simultaneous chilled, frozen, and deep-frozen zones requires 3-4x capital per pallet position versus ambient warehousing. Return thresholds deter regional operator participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cold Chain Logistics Market |
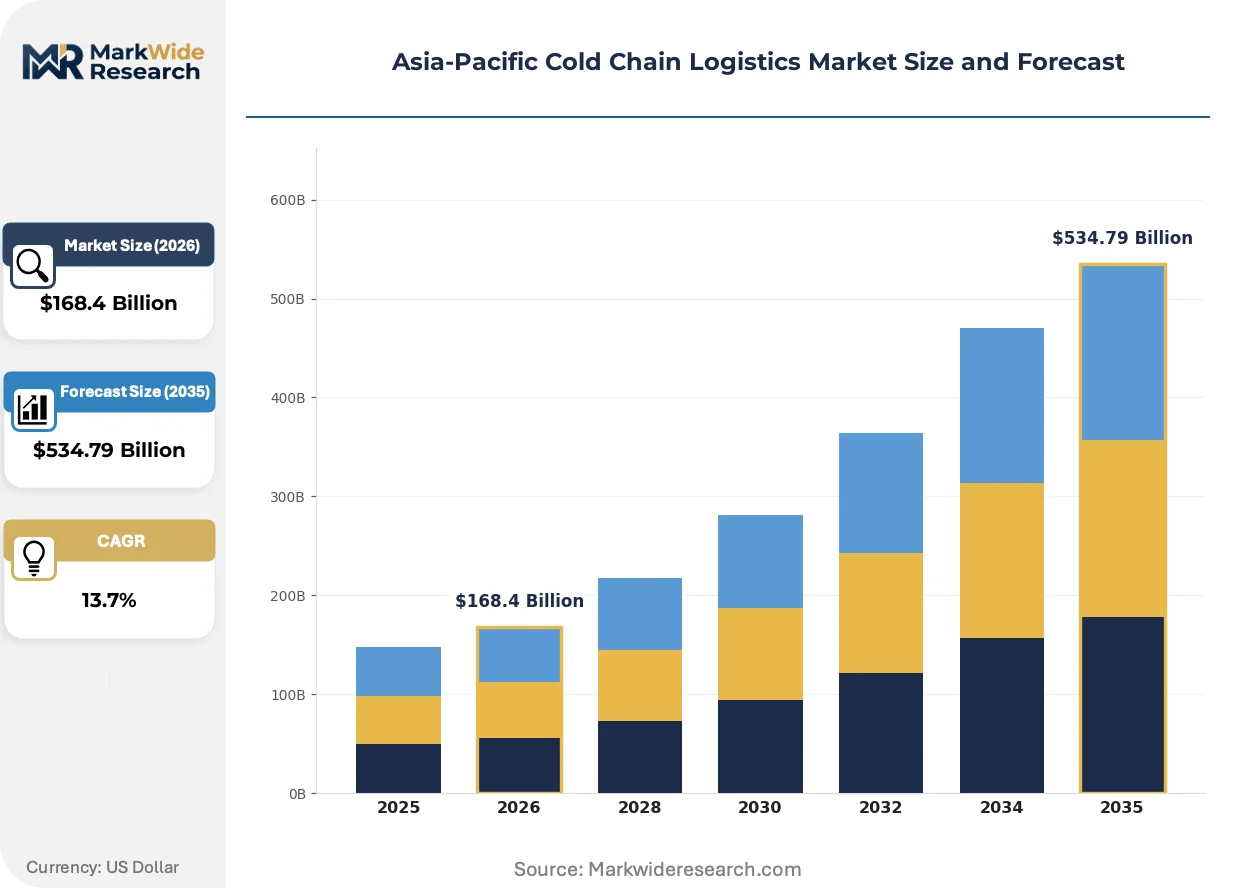
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $534.79 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Inventory Management Industry Vertical: Food & Beverage, Pharmaceuticals, Chemicals, Aerospace Temperature Range: Ambient, Chilled, Frozen, Deep Frozen Technology: Refrigerated Trucks, Temperature Monitoring, Insulated Containers, IoT Solutions |
| Companies Covered | DHL Supply Chain, Kuehne + Nagel, Nichirei Logistics Group, JWD Group, Yusen Logistics, Kerry Logistics Network Limited, S.F. Express, Nippon Express, Lineage Logistics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cold Chain Logistics Market Strategic Shifts & Innovations
Digital traceability infrastructure and passive thermal protection are compressing compliance costs while reshaping competitive positioning between integrated multinationals and specialized regional operators.
Vacuum-insulated panels utilizing fumed silica cores are overtaking polyurethane foam in pharmaceutical air freight containers. Korean and Japanese pharmaceutical exporters are adopting VIP-lined shippers for 120-hour lane stability. This material transition is overtaking conventional insulation economics on trans-Pacific routes, enabling direct ocean freight substitution for air cargo on non-urgent biologics.
China's SAMR implements revised GB standards for refrigerated vehicle construction and cold storage facility hygiene documentation. Warehouse operators in Jiangsu and Zhejiang provinces are retrofitting ammonia detection systems and automated temperature logging to satisfy inspection protocols. The pharmaceutical segment faces the steepest compliance burden, with SAMR auditors rejecting facilities lacking continuous digital telemetry.
Consolidated procurement of temperature-controlled logistics services is concentrating buyer power among Chinese e-commerce platforms and Australian supermarket chains. Long-term contracts with guaranteed capacity allocation are displacing spot-market engagement for frozen protein and dairy imports. This pattern is most visible in Shanghai's Yangshan port zone, where platform-controlled bonded cold storage now captures 60% of Australian beef import volume.
Asia-Pacific Cold Chain Logistics Market Segmentation
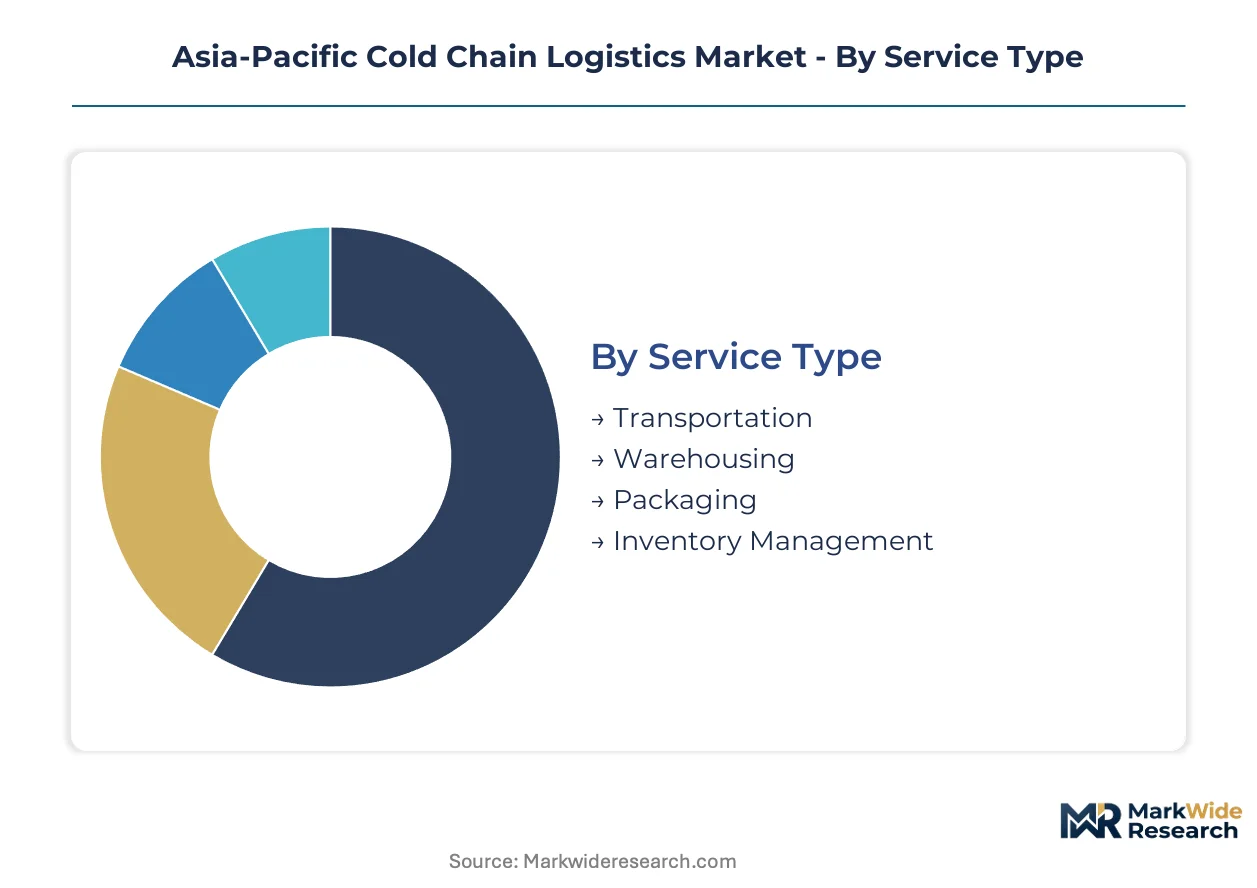
Temperature-controlled logistics demands diverge sharply across payload sensitivity, transit distance, and compliance burden. Service providers configure asset bases differently for pharmaceutical gene therapies versus frozen seafood exports, creating distinct margin pools within each segment cluster.
Service Type:
Cost tier separates integrated operators from specialized point-solution vendors across the Asia-Pacific corridor.
- Transportation:Fuel-intensive refrigerated trucking and intermodal reefer movements dominate value capture. Demand concentrates on China's eastern seaboard, where Shanghai and Qingdao anchor multi-modal frozen export corridors serving Australian beef and New Zealand dairy flows.
- Warehousing:Automated high-bay frozen storage near port gateways commands margin concentration through simultaneous chilled, frozen, and deep-frozen zone operation. Japanese METI efficiency mandates and India's FSSAI documentation rules force simultaneous capital deployment across compliance-heavy markets.
- Packaging:Vacuum-insulated panels and phase-change materials stabilize pharmaceutical payloads for 72-120 hours without active cooling. Salt-hydrate PCMs enable drone distribution to remote Indonesian islands.
- Inventory Management:Real-time telemetry integration with bonded cold storage tracks temperature excursions across handoffs. Cross-border e-commerce platforms mandate this capability for same-day delivery promises.
Volume sits with Transportation; growth tilts toward Warehousing.
Industry Vertical:
Application maturity determines whether buyers prioritize compliance certification or cost minimization.
- Food & Beverage:Frozen protein and dairy imports drive bonded cold storage demand at Shanghai's Yangshan port zone. India's PLI scheme for food processing subsidizes integrated village-to-hub collection networks in Maharashtra and Gujarat.
- Pharmaceuticals:Gene therapies and mRNA vaccines require minus 70 to minus 20 degrees Celsius corridors through Southeast Asia. Singapore and Bangkok operators are building dedicated deep-frozen capacity to capture this traffic.
- Chemicals:Temperature-sensitive industrial precursors demand continuous digital telemetry for regulatory documentation. SAMR auditors reject facilities lacking automated temperature logging.
- Aerospace:Specialized thermal protection for avionics components utilizes VIP-lined shippers on trans-Pacific routes. Korean and Japanese exporters are substituting ocean freight for air cargo on non-urgent biologics.
Food & Beverage holds installed base dominance; Pharmaceuticals shows the steepest expansion trajectory.
Temperature Range:
Customer technical specifications fragment equipment procurement and technician training requirements.
- Ambient:Standard climate-controlled storage for non-perishable pharmaceuticals and packaged goods. Minimal regulatory burden attracts informal logistics providers.
- Chilled:2-8 degrees Celsius corridors for vaccine distribution and fresh produce. FSSAI mandates end-to-end temperature documentation for Indian chilled food imports.
- Frozen:Minus 18 degrees Celsius standard for seafood and meat exports. Vietnam's Mekong Delta lacks sufficient blast freezing capacity for pangasius and shrimp.
- Deep Frozen:Minus 25 to minus 70 degrees Celsius for biologics and cryogenic materials. Ammonia system specialists command wage premiums exceeding 40% in Australian and Japanese markets.
Frozen commands throughput volume; Deep Frozen captures the fastest margin expansion.
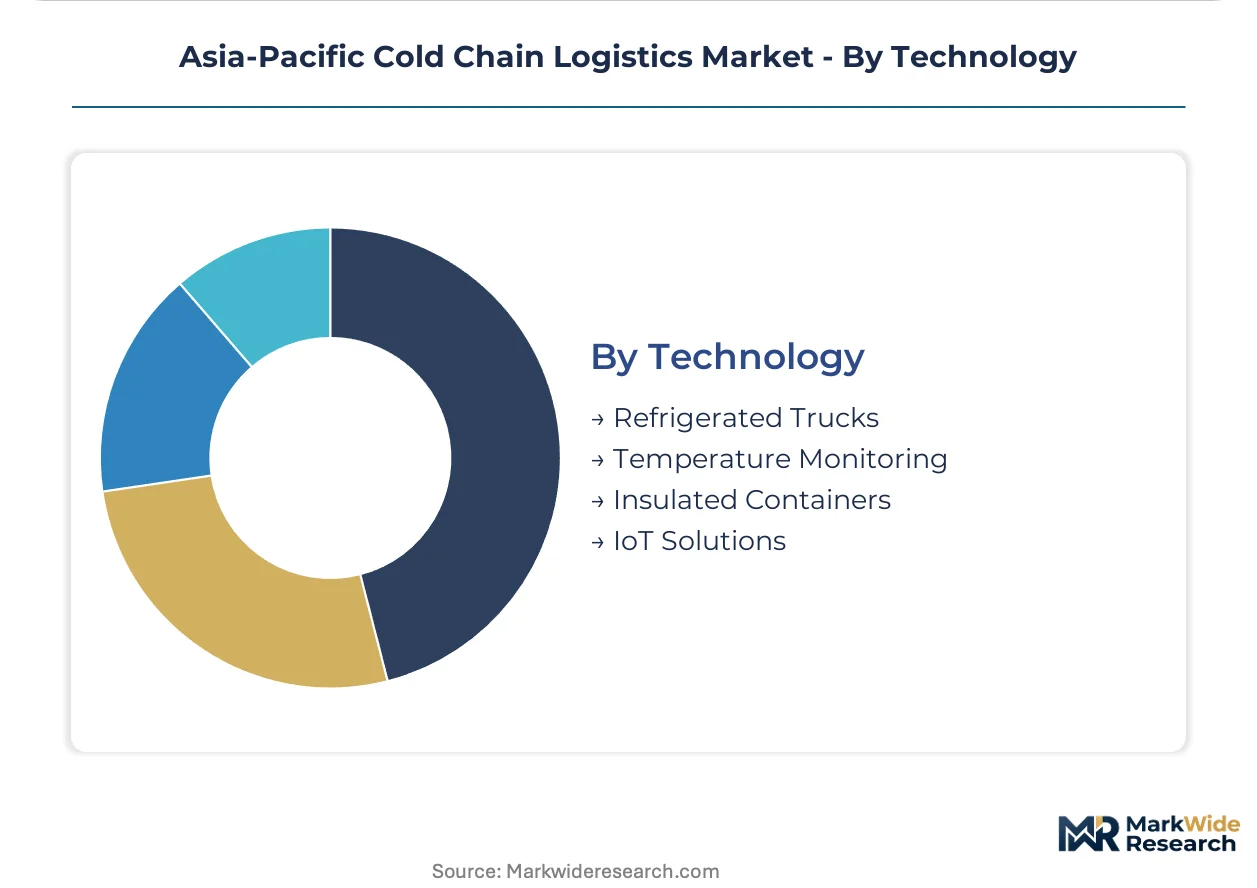
Technology:
Supply concentration in Chinese and South Korean manufacturing shapes equipment availability timelines.
- Refrigerated Trucks:Vapor-compression refrigeration dominates long-haul lanes. Lead times for pharmaceutical-grade reefers now exceed 14 months, constraining Southeast Asian pharmaceutical exporters.
- Temperature Monitoring:Sensor networks generate immutable temperature records for blockchain documentation. Australian and Japanese pharmaceutical importers mandate this tier for premium lane pricing.
- Insulated Containers:Fumed silica core VIPs displace polyurethane foam in pharmaceutical air freight. Korean exporters adopt these for 120-hour lane stability on trans-Pacific routes.
- IoT Solutions:Predictive maintenance algorithms and regulatory documentation automation represent the technology category expanding most quickly. Fleet operators deploy these networks across multimodal handoffs.
Refrigerated Trucks anchor capital deployment; IoT Solutions attracts the fastest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along China's eastern seaboard, where Shanghai and Qingdao anchor multi-modal frozen export corridors for Australian beef and New Zealand dairy flows. India's PLI scheme for food processing and Japan's METI efficiency mandates are tightening compliance requirements across the region. Pharmaceutical distribution networks across Southeast Asia are expanding refrigerated capacity to handle temperature-sensitive biologics.
China
Shanghai and Qingdao dominate frozen protein and dairy import flows through bonded cold storage at Yangshan port zone. SAMR implements revised GB standards for refrigerated vehicle construction and facility hygiene documentation, forcing Jiangsu and Zhejiang warehouse operators to retrofit ammonia detection systems. Cross-border e-commerce platforms connecting Chinese consumers to Australian beef require same-day delivery inventory positioning at these port gateways.
Japan
Deep-frozen infrastructure for seafood distribution commands specialized capital deployment across Kanto and Kansai industrial corridors. METI enforces energy-efficiency standards for commercial refrigeration equipment, compelling warehouse operators to address stranded asset risk on aging ammonia systems. Nichirei Logistics Group dominates frozen food distribution through dedicated deep-frozen infrastructure in these metropolitan zones.
India
Maharashtra and Gujarat food processors are consolidating fragmented village-level collection into hub-and-spoke networks under PLI scheme subsidies. FSSAI mandates end-to-end temperature documentation for frozen and chilled food imports, raising compliance barriers for informal logistics providers across Indian urban corridors. Village-to-hub collection networks are capturing agricultural output that previously degraded in ambient storage.
Singapore
Dedicated deep-frozen capacity for gene therapies and mRNA vaccines is expanding to serve Southeast Asian pharmaceutical networks. The national pharmaceutical regulator enforces continuous digital telemetry requirements for minus 70 to minus 20 degrees Celsius corridors. Multi-temperature hub infrastructure anchors regional pharmaceutical compliance leadership for temperature-sensitive biologics distribution.
Vietnam
The Mekong Delta lacks sufficient minus 25 degrees Celsius blast freezing capacity for pangasius and shrimp export processing. National food safety authorities are tightening documentation requirements for seafood export certification. Ho Chi Minh City port zones present anchoring opportunities for integrated operators building export corridors through underpenetrated seafood infrastructure.
Asia-Pacific Cold Chain Logistics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding pharmaceutical compliance lanes while regional operators capture fragmented food processing logistics. The market structures around three tiers: global networks with multi-temperature hub infrastructure, national champions with bonded cold storage specialization, and last-mile specialists deploying passive thermal protection. Strategic moves concentrate on M&A for geographic footprint expansion and technology licensing for IoT-telemetry convergence.
Within the integrated multinational tier, DHL Supply Chain and Kerry Logistics Network Limited exemplify hub-and-spoke network architectures spanning Singapore, Thailand, and Greater China. Nichirei Logistics Group occupies a position among deep-frozen specialists with concentrated Japanese market presence. These three entities represent divergent archetypes: global compliance leadership through multi-temperature infrastructure, perishable export anchoring through bonded warehousing integration, and national frozen distribution through specialized deep-frozen assets.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Kuehne + Nagel |
| Nichirei Logistics Group |
| JWD Group |
| Yusen Logistics |
| Kerry Logistics Network Limited |
| S.F. Express |
| Nippon Express |
| Lineage Logistics |
| Others |
Cost & Logistics Intelligence
Ammonia and hydrofluorocarbon price indices cascade through Asia-Pacific cold chain economics, compressing margins on aging Japanese warehouse systems while amplifying procurement premiums for pharmaceutical-grade reefer containers out of Chinese and South Korean shipyards. This input-cost volatility stratifies service pricing across compliance-heavy versus commodity lanes, with METI-mandated retrofit requirements and FSSAI documentation rules forcing simultaneous capital deployment that operators recover through tiered rate cards.
Pricing Analysis
Volume concentrates in frozen food transportation while margin pools in pharmaceutical warehousing with multi-temperature zone premiums. Three-tier pricing structure across premium compliance-guaranteed, standard certified, and economy ambient lanes separates Australian beef exporters demanding blockchain-telemetry documentation from Indian domestic chilled distributors. Cost compression in economy trucking intensifies because informal operators face FSSAI exclusion, while pharmaceutical buyers show lowest price sensitivity due to gene therapy payload irreplaceability.
Supply Chain Analysis
Refrigeration technician scarcity in Australian and Japanese markets constrains ammonia system maintenance capacity, forcing wage premiums that feed into service pricing. Manufacturing concentrates in China, South Korea, and Japan for vapor-compression equipment, vacuum-insulated panels, and cryogenic handling systems. Component dependencies span fumed silica cores, salt-hydrate phase-change materials, and hydrofluorocarbon refrigerants. Single-source vulnerability concentrates in pharmaceutical-grade reefer container production. Distribution runs through Shanghai and Qingdao port gateways for Australian and New Zealand protein flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cold chain logistics is becoming a vertical-integration race, with operators pursuing captive control over ammonia-system maintenance networks to offset technician scarcity premiums and secure compliance capacity.
For Market Incumbents: Cement multi-temperature hub dominance through backward integration into phase-change material production, insulating against Korean VIP supplier concentration. DHL Supply Chain and Kerry Logistics Network Limited anchor positions through Singapore-Thailand pharmaceutical corridors and Greater China bonded warehousing. Defend against emerging IoT-telemetry specialists by capturing cryogenic handler training pipelines before Australian and Japanese vocational institutions expand output. For New Entrants and Emerging Players: Enter via Vietnam's Mekong Delta seafood infrastructure gap, where pangasius and shrimp exporters lack minus 25 degrees Celsius blast freezing capacity near Ho Chi Minh City port. Target Indian village-to-hub collection networks under PLI scheme subsidies, consolidating fragmented Maharashtra and Gujarat agricultural flows. Deploy salt-hydrate PCM passive cooling for Indonesian island drone distribution as a regulatory-light beachhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated high-bay frozen storage specialists in Jiangsu and Zhejiang provinces, where SAMR compliance retrofit costs strain regional operators. Long-term viability hinges on pharmaceutical corridor positioning as gene therapy volumes expand. Watch ammonia price volatility and METI efficiency mandate deadlines as inflection indicators for stranded asset exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCM Production | Captive salt-hydrate supply secures 72-hour vaccine distribution stability for Indonesian last-mile networks. |
| Automated High-Bay Frozen Storage Buildout | Simultaneous chilled-frozen-deep-frozen zones capture pharmaceutical margin premiums at Shanghai Yangshan port. |
| Cryogenic Handler Training Pipeline Investment | Proprietary technician certification offsets 40% wage premiums in Australian and Japanese ammonia system markets. |
| IoT-Telemetry Blockchain Convergence | Immutable temperature records command premium pricing from Australian and Japanese pharmaceutical importers. |
| Vietnam Seafood Export Corridor Anchoring | Integrated blast freezing capacity at Ho Chi Minh City port captures underpenetrated pangasius and shrimp flows. |
Research Approach
Document review covered SAMR GB standards filings, METI efficiency mandate circulars, FSSAI documentation protocols, and PLI scheme administrative guidelines, complemented by interviews with cold chain operations directors, pharmaceutical logistics compliance officers, refrigerated transport fleet managers, bonded warehouse facility engineers, and ammonia system maintenance technicians. Secondary validation drew from customs trade data on reefer container flows, IEA cold storage energy consumption reports, and ASEAN pharmaceutical distribution regulatory updates. Bottom-up service provider revenue aggregation and top-down regional demand sizing were triangulated against capital expenditure disclosures from integrated logistics networks.
Segmentation outputs across service type, industry vertical, temperature range, and technology category were modeled over the projection horizon, with CAGRs derived from historical capacity installation rates and forward-looking regulatory compliance timelines. Inputs included pharmaceutical biologics pipeline expansion trajectories, India's PLI scheme subsidy disbursement schedules, and Japan's METI efficiency benchmark phase-in patterns for commercial refrigeration equipment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant price volatility spikes or METI mandate acceleration. Forecasts reflect documented assumptions on pharmaceutical volume growth, PLI scheme continuation, and regional regulatory harmonization progress. Material deviation in ammonia system retrofit completion rates or FSSAI enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Multicarrier Shipping Software Market