
 Chemical Tanker Shipping Market | 2026-2036
Chemical Tanker Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Tanker Shipping Market Analysis
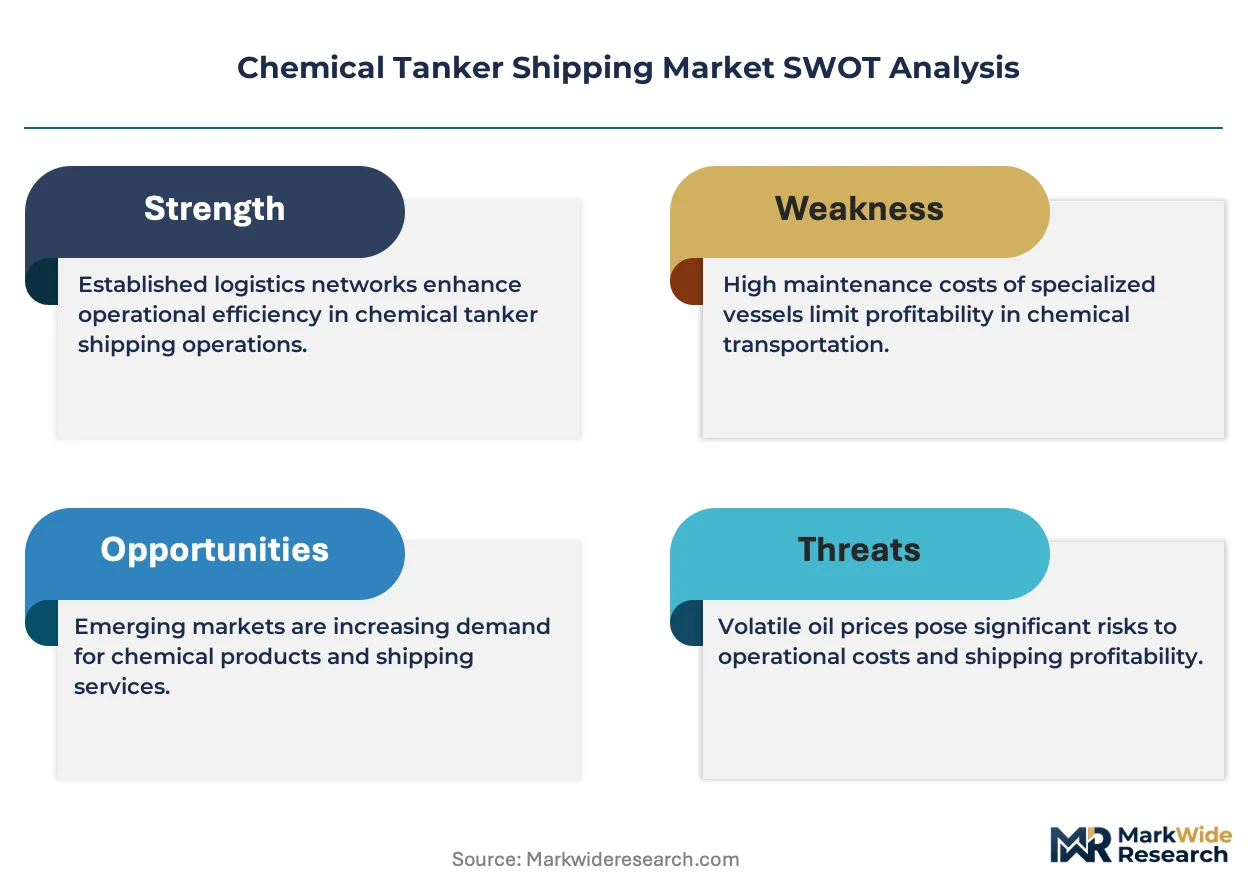
Digital cargo matching and real-time stowage optimization is reconfiguring voyage economics for parcel chemical trades. Stolt-Nielsen leverages its integrated terminal network to control tank cleaning and cargo flexibility across multiple trade lanes. Odfjell anchors its competitive position through deep specialization in stainless steel tankers serving high-purity chemical segments. MOL Chemical Tankers sustains scale advantages via its Asia-centric fleet deployment and long-term contract coverage with Japanese chemical producers.
Chemical tanker shipping involves the maritime transport of liquid chemicals in parcel or bulk configurations using vessels with segregated cargo tanks, typically constructed of stainless steel or epoxy-coated mild steel with multiple independent pumping systems. These ships handle cargoes with flash points ranging from below 60°C to elevated temperatures, requiring IMO Type II/III hull designs and dedicated tank atmospheres to prevent cross-contamination. Specialty chemicals command premium freight rates due to stringent purity requirements and smaller parcel sizes, while industrial chemicals generate volume-driven revenue through larger lot movements. Stainless steel tanks dominate the high-value cargo segment because they eliminate coating degradation risks, whereas coated tanks occupy the cost-sensitive industrial chemical trade where cargo compatibility is less restrictive.
The International Maritime Organization's MARPOL Annex II governs chemical cargo categorization and discharge standards, directly influencing tanker design specifications and cleaning protocol costs for operators. The EU's Monitoring, Reporting and Verification framework and FuelEU Maritime initiative impose escalating carbon intensity obligations on vessels calling at European ports, reshaping fleet renewal timelines and retrofit investment decisions. Classification societies including DNV and Lloyd's Register enforce structural and cargo containment standards that determine market access for aging tonnage. Stakeholders must weigh regulatory compliance capital requirements against charter rate recovery potential when evaluating fleet expansion or renewal commitments.
Market Dynamics
The chemical tanker shipping market is being fundamentally restructured by the International Maritime Organization's escalating carbon intensity mandates, which are compressing vessel lifecycles and forcing premature fleet renewal decisions across all major trade lanes.
Growth Catalysts
- FuelEU Maritime:The European Union's escalating carbon intensity obligations for vessels calling at Rotterdam, Antwerp, and Hamburg are accelerating demand for dual-fuel newbuilds with methanol-ready specifications.
- Specialty chemical demand:Pharmaceutical and agrochemical manufacturers in Switzerland and Singapore are expanding seaborne procurement of high-purity feedstocks requiring stainless steel tank segregation.
- Digital cargo matching:Real-time stowage optimization platforms are reducing ballast voyages and improving vessel utilization rates on the Singapore–Houston route.
Market Restraints
- Stainless steel supply concentration:Japanese and South Korean steel mills control premium-grade plate production for chemical tank construction, exposing shipyards to input cost volatility and delivery delays.
- MARPOL Annex II compliance friction:The IMO's revised cargo classification standards are extending certification timelines for existing tonnage and elevating tank cleaning protocol costs for operators serving multiple chemical categories.
- Pipeline substitution:New petrochemical complexes in Saudi Arabia and the UAE are deploying dedicated pipeline networks for short-haul movements, displacing coastal parcel tanker demand in the Middle East Gulf.
Strategic Opportunities
- India chemical cluster expansion:Dahej and Mundra are attracting specialty chemical investments that will generate new deep-sea export demand requiring IMO Type II parcel tonnage.
- Carbon capture feedstock transport:Emerging demand for liquid CO2 and amine solvent movements from capture facilities to storage sites is creating a new cargo category for modified chemical tankers.
- Green methanol bunkering infrastructure:Port authorities in Rotterdam and Singapore are developing methanol supply chains that will reward early-adopter vessel operators with preferential berthing and reduced port dues.
Industry Challenges
- Marine chemist certification scarcity:The specialized workforce required for tank atmosphere testing and cargo compatibility verification is concentrated in aging demographics across European maritime training institutes.
- Legacy cargo control system integration:Retrofitting existing parcel tankers with automated stowage monitoring and predictive maintenance sensors requires extended drydock periods that conflict with tight charter schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Tanker Shipping Market |
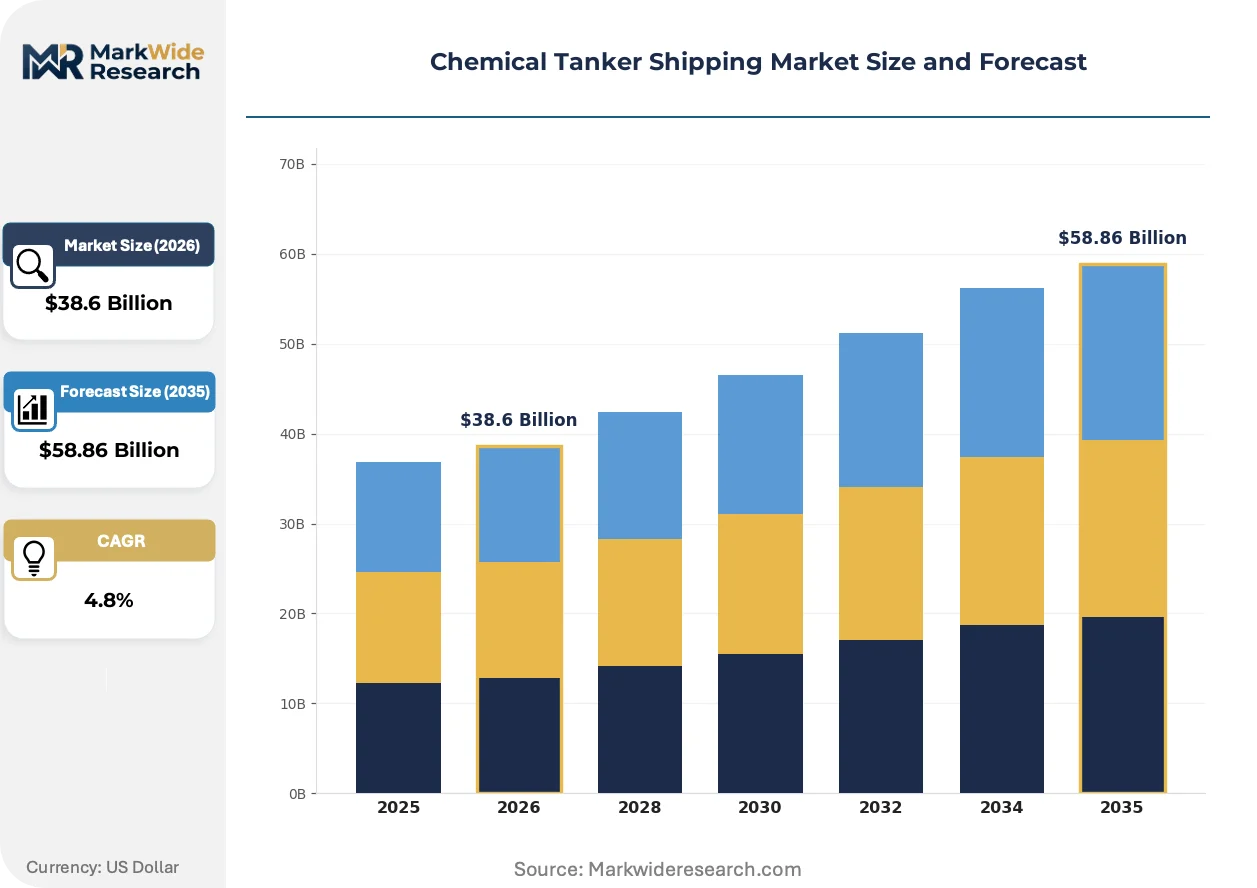
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feedstock, Specialty Chemicals, Industrial Chemicals, Liquid Gas Delivery Mode: Bulk Shipping, Container Shipping, Chartering, Scheduled Services End User: Chemical Manufacturers, Oil Refineries, Pharmaceutical Companies, Food & Beverage Industry Tank Type: Stainless Steel Tanks, Coated Tanks, Insulated Tanks, Rubber-lined Tanks |
| Companies Covered | Stolt-Nielsen, Odfjell, MOL Chemical Tankers, Navig8, Bahri, Nordic Tankers, Ardmore Shipping Corporation, Hafnia, Iino Kaiun Kaisha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Tanker Shipping Market Emerging Trajectories
Digital twin technology and alternative fuel propulsion systems are converging to redefine vessel economics, while regulatory pressure from multiple jurisdictions is compressing the viable lifecycle of conventional chemical tankers.
Digital twin platforms are virtualizing vessel performance monitoring by creating real-time simulations of hull stress, cargo temperature profiles, and engine efficiency. Stolt-Nielsen and Odfjell are deploying these systems across stainless steel fleets to optimize speed and fuel consumption on long-haul routes. This virtualization is compressing the competitive advantage of operators relying on manual voyage planning and static maintenance schedules.
The EU's FuelEU Maritime initiative is imposing binding carbon intensity reduction targets on vessels calling at European ports, with penalties escalating from 2025 through 2034. Shipowners serving Rotterdam and Antwerp are accelerating newbuild orders for methanol-capable dual-fuel engines to avoid cumulative compliance costs. The stainless steel parcel segment is most affected, as these high-value cargoes concentrate in European chemical clusters with the strictest enforcement mechanisms.
Charterers are consolidating procurement through integrated logistics platforms that unbundle freight contracting from terminal handling and tank cleaning services. Major chemical producers in Japan and Germany are migrating from annual contracts to spot-market fixture platforms with real-time rate transparency. This shift is most visible in the specialty chemical trade, where cargo confidentiality requirements previously favored long-term bilateral relationships with established operators.
Chemical Tanker Shipping Market Segmentation
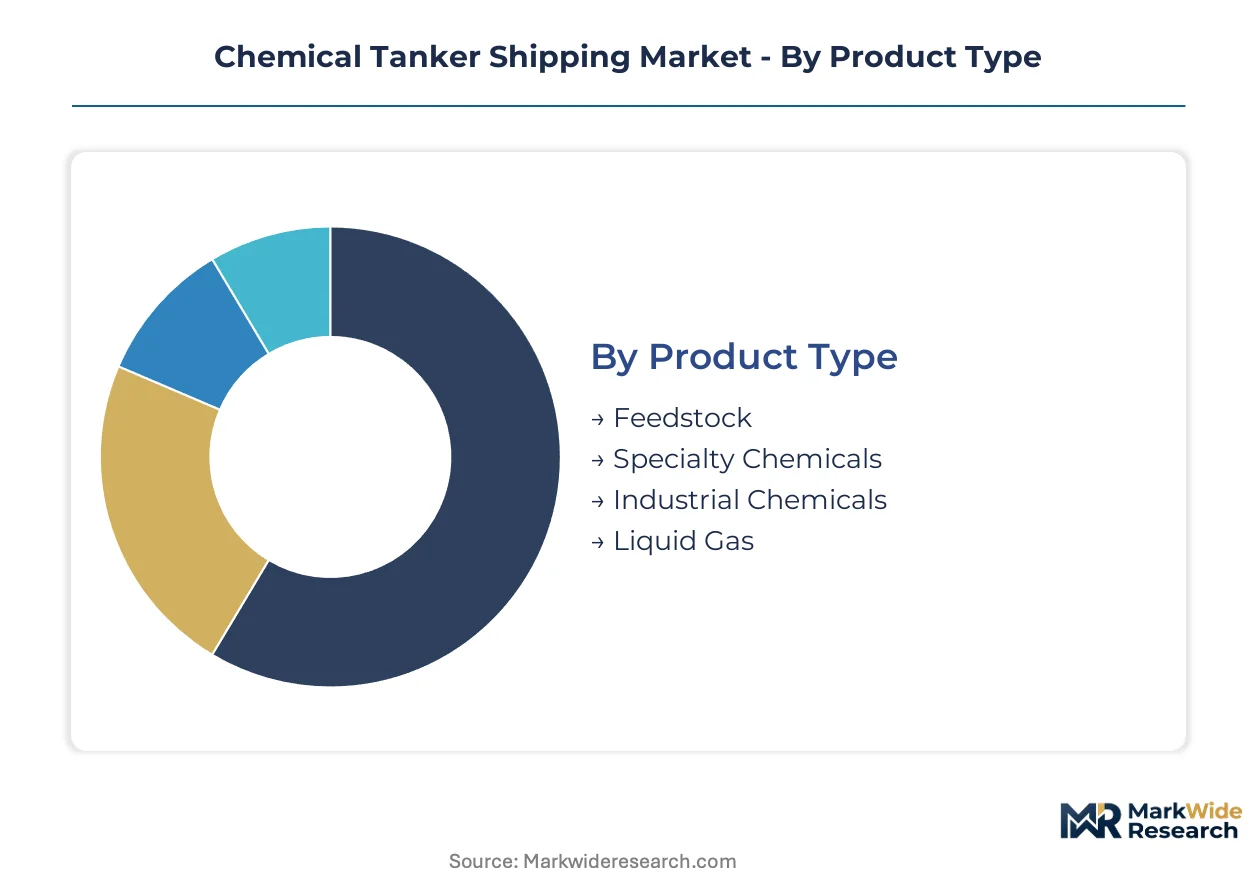
Chemical tanker shipping demands precise cargo segregation across highly differentiated vessel specifications. Segmentation reveals how cargo chemistry, delivery urgency, and purity requirements drive fleet specialization and charter rate stratification.
Product Type:
Cargo chemistry spans from commodity feedstocks to temperature-sensitive specialty formulations, each imposing distinct tank material and handling protocols.
- Feedstock:Crude oil derivatives and unprocessed petrochemical inputs move in large parcel sizes with minimal segregation requirements. Refinery demand in Rotterdam, Houston, and Singapore drives fixture volumes for these standardized movements.
- Specialty Chemicals:High-purity agrochemical and pharmaceutical intermediates command premium freight rates due to stringent contamination controls. Swiss and Japanese manufacturers are expanding seaborne procurement of these cargoes, requiring dedicated stainless steel tank segregation and intensive cleaning protocols between voyages.
- Industrial Chemicals:Sulfuric acid, caustic soda, and methanol move in cost-sensitive bulk configurations where coating compatibility matters more than absolute purity.
- Liquid Gas:Liquefied petroleum gas and petrochemical gases require pressurized or refrigerated containment systems distinct from atmospheric tank designs.
The dominant share belongs to Industrial Chemicals, while Specialty Chemicals is closing the gap fastest.
Delivery Mode:
Service configuration reflects the tension between asset utilization efficiency and cargo schedule reliability across trade lanes.
- Bulk Shipping:Full-vessel charters for large chemical producers seeking dedicated capacity on predictable routes. Dahej and Mundra exporters in India favor this mode for deep-sea movements to European chemical clusters.
- Container Shipping:ISO tank containers flexibly integrate with liner networks for smaller parcel sizes and multimodal distribution.
- Chartering:Spot-market fixtures dominate specialty chemical trades where cargo confidentiality and route flexibility outweigh schedule certainty.
- Scheduled Services:Fixed-rotation parcel tankers serving the Singapore–Rotterdam–Houston triangle with predictable berth windows and integrated tank cleaning.
Bulk Shipping captures the largest cargo volume, though Chartering is expanding most quickly as digital platforms compress fixture timelines.
End User:
Downstream industry requirements shape everything from tank certification grades to discharge window flexibility.
- Chemical Manufacturers:Integrated producers in Germany and Japan contract long-term parcel tonnage with stringent cargo compatibility documentation.
- Oil Refineries:Coastal facilities in Saudi Arabia and the UAE are displacing tanker demand through pipeline substitution for short-haul movements.
- Pharmaceutical Companies:Swiss and Singaporean manufacturers drive demand for high-purity stainless steel segregation with exhaustive chain-of-custody records.
- Food & Beverage Industry:Edible oils and flavoring extracts require dedicated tank certifications under national food safety regulators.
Chemical Manufacturers retain the dominant procurement volume, while Pharmaceutical Companies are gaining share fastest on purity-driven cargo expansion.
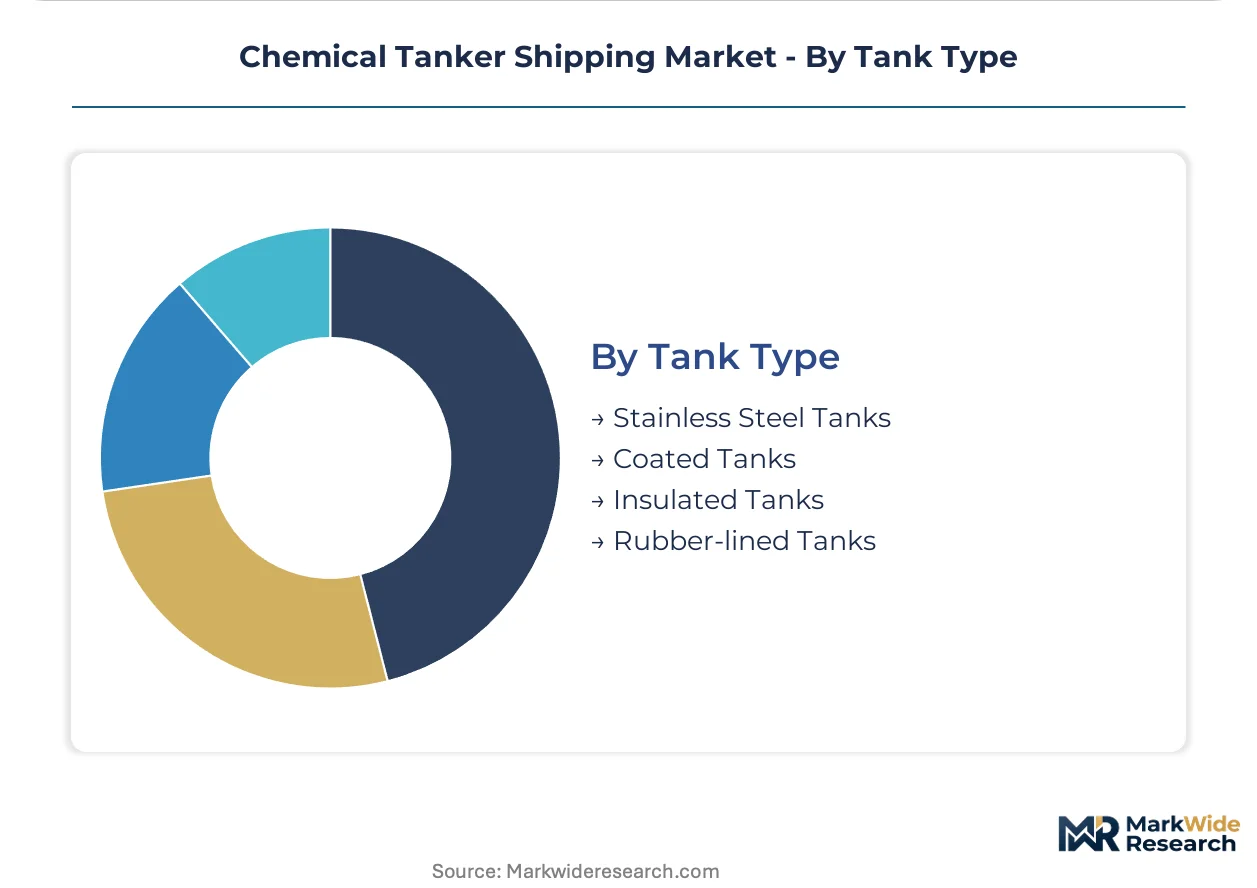
Tank Type:
Construction material selection locks in cargo compatibility ranges and determines vessel economic lifespans under corrosive chemical exposure.
- Stainless Steel Tanks:Austenitic grades eliminate coating degradation risks for high-purity cargoes. Japanese and South Korean steel mills control premium plate supply, exposing shipyards to input cost volatility.
- Coated Tanks:Epoxy and phenolic linings occupy cost-sensitive industrial chemical trades where cargo compatibility is less restrictive and vessel renewal cycles are shorter.
- Insulated Tanks:Thermal protection for temperature-sensitive cargoes including certain specialty chemicals and edible products.
- Rubber-lined Tanks:Acid-resistant linings for highly corrosive industrial chemicals where stainless steel would suffer pitting corrosion.
Coated Tanks comprise the largest installed base, while Stainless Steel Tanks are climbing the fastest on specialty chemical demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical manufacturers in Switzerland, Singapore, and Japan anchor seaborne procurement demand, driving fixture volumes along deep-sea routes connecting major chemical clusters.
United States
Houston anchors the Gulf Coast petrochemical complex with expanding deep-sea export capacity for specialty formulations. The EPA enforces vessel emission standards under the Clean Air Act that affect port calls along the Texas and Louisiana coasts. Dahej and Mundra exporters in India increasingly target US chemical clusters with IMO Type II parcel tonnage.
Germany
Integrated chemical producers in Ludwigshafen and Leverkusen contract long-term parcel capacity with stringent cargo compatibility documentation. The EU's FuelEU Maritime initiative imposes binding carbon intensity reduction targets on vessels calling at Hamburg and Antwerp. The Rhine-Ruhr chemical corridor generates substantial feeder demand connecting to Rotterdam deep-sea terminals.
Singapore
Pharmaceutical and agrochemical manufacturers expand seaborne procurement of high-purity feedstocks requiring stainless steel tank segregation. The Maritime and Port Authority of Singapore develops methanol bunkering infrastructure rewarding early-adopter vessel operators. Jurong Island chemical cluster drives intraregional parcel fixture volumes alongside deep-sea connections to Rotterdam and Houston.
Japan
METI oversees maritime energy transition policies affecting fleet renewal timelines for domestic chemical tanker operators. Japanese chemical producers sustain long-term contract coverage with Asia-centric fleet deployments. Osaka and Yokkaichi chemical clusters generate consistent demand for high-purity stainless steel parcel movements.
Netherlands
Rotterdam serves as Europe's primary chemical tanker hub with strict enforcement of EU Green Deal maritime provisions. The port authority prioritizes methanol-ready dual-fuel vessels with preferential berthing and reduced port dues. Antwerp-Rotterdam chemical cluster drives premium freight rates for stainless steel parcel tonnage serving Swiss and German manufacturers.
Chemical Tanker Shipping Market Vendor Landscape
Channel-controlling players compete with product-specialist players across differentiated vessel specifications and cargo-handling capabilities. The market structure consolidates around integrated terminal operators, stainless steel parcel specialists, and Asia-centric fleet deployers. Three strategic archetypes dominate: terminal-network controllers, high-purity cargo specialists, and scale-driven contract carriers. Competitive moves concentrate on methanol-ready newbuild ordering and digital cargo-matching platform deployment.
Among integrated terminal-network controllers, Stolt-Nielsen occupies a position exemplifying backward integration into tank cleaning and cargo flexibility management. Odfjell and MOL Chemical Tankers represent contrasting archetypes within specialized vessel deployment, with the former anchoring the stainless steel high-purity segment and the latter sitting within Asia-centric scale operations. These three operators collectively illustrate how geographic specialization and tank material focus stratify competitive positioning across trade lanes.
| Leading Market Players |
|---|
| Stolt-Nielsen |
| Odfjell |
| MOL Chemical Tankers |
| Navig8 |
| Bahri |
| Nordic Tankers |
| Ardmore Shipping Corporation |
| Hafnia |
| Iino Kaiun Kaisha |
| Others |
Supply Flow & Price Mechanics
The Singapore–Rotterdam–Houston corridor anchors freight cost dynamics, where stainless steel tank premiums concentrate among Japanese and South Korean shipyards while charterers in Switzerland and Germany absorb downstream price differentiation through long-term parcel contracts.
Pricing Analysis
Cost-plus contracts indexed to Baltic Exchange chemical tanker rates dominate fixture economics, with premium-mid-economy pricing differentiation separating stainless steel parcel tonnage from coated tank alternatives. Price differentiation hinges on IMO Type II/III certification grades and cargo compatibility documentation depth. Cost compression in industrial chemical trades is intensifying because MARPOL Annex II compliance extends tank cleaning cycles. Chemical manufacturers in Japan exhibit lowest price sensitivity due to purity requirements, while bulk feedstock buyers in India drive spot-market rate volatility.
Supply Chain Analysis
Shipyard capacity concentrates at Hyundai Heavy Industries, Samsung Heavy Industries, and Imabari Shipbuilding, which control methanol-ready dual-fuel newbuild slots through mid-decade. Raw material dependencies rest on austenitic stainless plate from Nippon Steel and POSCO, epoxy coating systems from AkzoNobel and Hempel, and specialized pumping equipment from German and Japanese suppliers. Single-source vulnerability in premium-grade steel plate exposes construction timelines to mill allocation decisions. Distribution runs through integrated terminal operators controlling tank cleaning and cargo flexibility across Rotterdam, Houston, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical tanker shipping functions as a service-attach opportunity where integrated tank cleaning and terminal handling revenue layers expand faster than base freight rates, rewarding operators with backward integration into port infrastructure.
For Market Incumbents: Insulate charter rate recovery by securing dedicated stainless steel newbuild slots at Korean and Japanese shipyards before FuelEU Maritime penalties escalate. Prioritize certification investment for MARPOL Annex II Type II hull designs to defend against emerging methanol-ready entrants targeting Rotterdam-Antwerp chemical clusters. Channel control through captive terminal networks in Houston and Singapore preserves cargo flexibility premiums.
For New Entrants and Emerging Players: Pursue carbon capture feedstock transport as a white-space cargo category, where modified chemical tankers face limited incumbent specialization. Target India chemical cluster expansion at Dahej and Mundra for IMO Type II parcel tonnage demand. Deploy digital cargo-matching platforms to compress fixture timelines against established operators reliant on annual contract coverage.
For Investors and Strategic Acquirers: Terminal-integrated parcel specialists with methanol-ready orderbooks represent the most defensible acquisition archetype for long-term viability across the energy transition window. Monitor green methanol bunkering infrastructure deployment at Rotterdam and Singapore as the critical inflection signal for fleet renewal economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Methanol-Ready Dual-Fuel Newbuild Ordering | FuelEU Maritime penalties at Rotterdam and Hamburg accelerate demand for alternative propulsion vessels. |
| Terminal Network Expansion | Stolt-Nielsen's integrated tank cleaning model demonstrates captive revenue attachment at chemical hubs. |
| Digital Cargo-Matching Platform Deployment | Real-time stowage optimization reduces ballast voyages on Singapore–Houston routes. |
| Carbon Capture Feedstock Transport Capability | Liquid CO2 and amine solvent movements from capture facilities create new cargo category demand. |
| Marine Chemist Workforce Development | Aging European training institute demographics threaten tank atmosphere certification capacity. |
Methodological Framework
The analysis maps specialty chemical parcel trades, industrial chemical bulk movements, and carbon capture feedstock transport, each validated through chartering managers, shipyard procurement officers, terminal operations directors, and chemical manufacturer logistics leads. Primary interviews with fleet deployment strategists at integrated operators combined with secondary validation from Lloyd's Register classification data, IMO MARPOL Annex II regulatory filings, and Baltic Exchange fixture records. Bottom-up vessel-by-vessel capacity assessment triangulates against top-down trade lane demand modeling.
Assumption sets held FuelEU Maritime enforcement intensity and stainless steel plate supply concentration fixed while varying specialty chemical demand growth and methanol bunkering infrastructure deployment across the projection horizon. Segmentation dimensions modeled include cargo chemistry grade, tank construction material, delivery mode configuration, and regional chemical cluster connectivity. CAGRs derive from trade lane fixture volume trajectories weighted by vessel age distribution and regulatory compliance cost burdens.
Macroeconomic conditions sit as an overlay; deviation in chemical manufacturing capital expenditure cycles and energy transition policy acceleration would shift the trajectory. Forecasts reflect documented assumptions regarding IMO regulatory timeline adherence and shipyard delivery schedule reliability. Quarterly review of methanol bunker price spreads and stainless steel plate order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market