
 Asia Pacific Event Logistics Market | 2026-2036
Asia Pacific Event Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Event Logistics Market Insights
Sustainable packaging materials are pivoting event logistics economics across Asia Pacific as venues and organizers confront waste reduction mandates. DP World leverages its port-centric infrastructure to control inbound freight flows for major exhibitions in Singapore and Dubai-Asia corridors. Nippon Express anchors high-precision equipment transport for Japan's concert and broadcast technology sectors. DHL Supply Chain differentiates through RFID-integrated warehousing networks spanning Australia, China, and Southeast Asia.
Asia Pacific event logistics encompasses the planning, coordination, and execution of time-critical material flows for temporary gatherings including trade shows, concerts, corporate conferences, and sporting fixtures, requiring specialized handling of audio-visual equipment, booth structures, and perishable promotional materials with turnaround windows often compressed to 48-72 hours. The service type dimension shows freight handling occupying the largest revenue pool due to cross-border complexity, while on-site management captures expanding margin as labor costs rise in Singapore and Sydney. End-user segmentation reveals corporate events and trade shows sustaining the deepest demand base, though concerts represent the fastest-growing category as K-pop and regional touring circuits multiply arena bookings across Seoul, Bangkok, and Manila.
Australia's chain of responsibility laws under the National Heavy Vehicle Regulator reshape carrier liability for event freight, while China's GB standards for temporary structures and Japan's METI energy efficiency codes constrain equipment choices in venue build-outs. India's BIS safety certifications for electrical and staging equipment create compliance thresholds for rental providers entering the market. Stakeholders must monitor how fragmented national regulations across ASEAN member states will consolidate or diverge as event tourism becomes an explicit economic development priority.
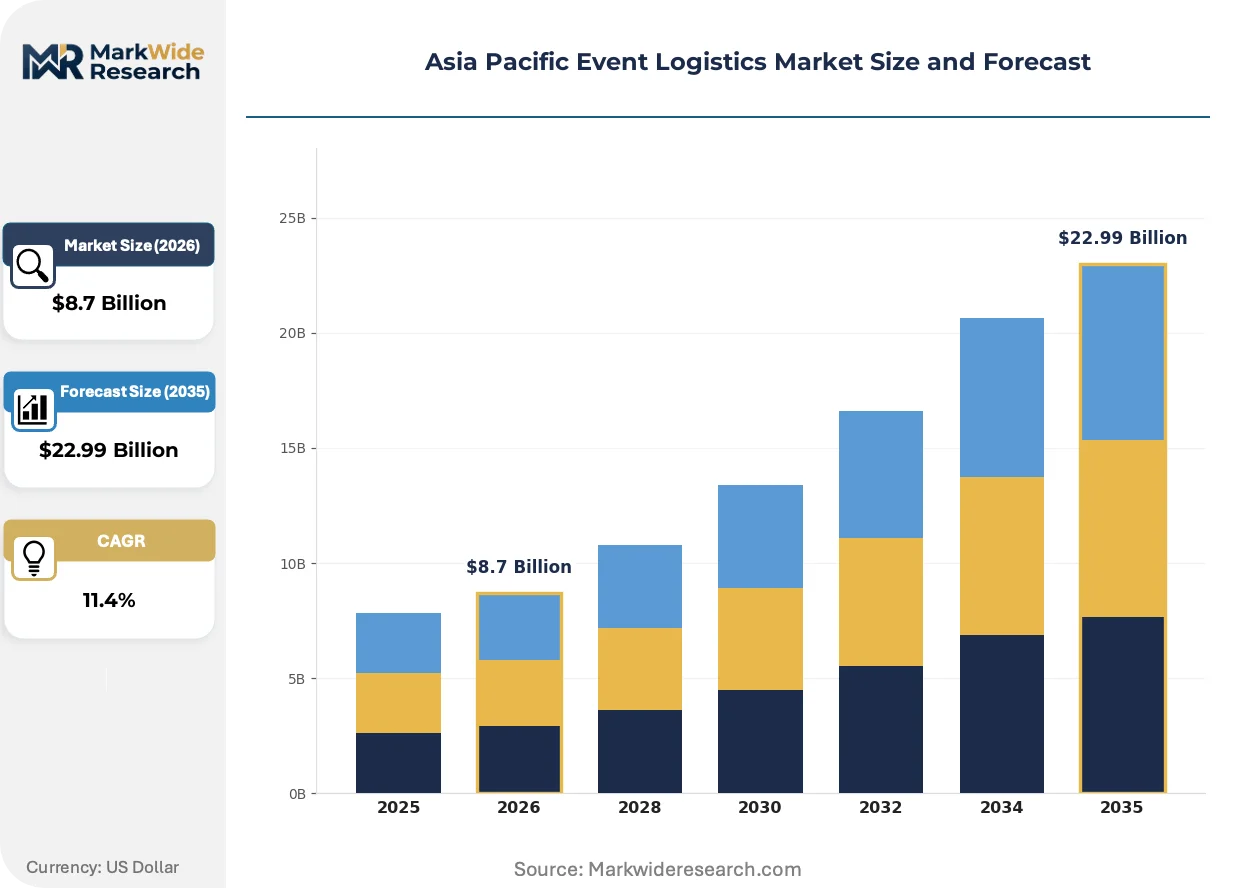
Market Dynamics
Sustainability mandates and compressed venue turnaround windows are restructuring Asia Pacific event logistics, forcing carriers to integrate carbon accounting into freight bids while deploying modular equipment fleets that collapse setup times from days to hours.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of carbon intensity benchmarks for temporary structures is compelling venue operators to specify low-emission freight partners in procurement tenders.
- Concert touring circuits:K-pop and regional music festivals are multiplying arena bookings across Seoul, Bangkok, and Manila, generating demand for high-velocity equipment repositioning between back-to-back dates.
- RFID-integrated warehousing:Real-time inventory tracking across Australia, China, and Southeast Asia is compressing material reconciliation windows from 48 hours to under 6 hours at major exhibition complexes.
Market Restraints
- Fuel cost volatility:Jet kerosene and marine diesel price swings directly erode margin on air and sea freight legs for time-critical booth materials.
- Port concentration risk:Singapore's dominance as a transshipment hub creates single-point vulnerability for exhibitions sourcing components from multiple ASEAN origins.
- Fragmented national regulations:Divergent BIS, GB, and METI certification requirements force logistics providers to maintain parallel compliance workflows across India, China, and Japan.
Strategic Opportunities
- Vietnam exhibition infrastructure:New convention centers in Ho Chi Minh City and Hanoi lack established logistics ecosystems, opening first-mover positioning for integrated freight-to-floor providers.
- Reusable modular systems:Aluminum frame and fabric display technologies that pack flat for 20+ reuse cycles align with tightening waste reduction mandates in Australian states.
- Cross-border e-commerce integration:Platforms connecting Chinese manufacturers to Southeast Asian event organizers are bypassing traditional distributor layers for promotional merchandise flows.
Industry Challenges
- Specialized technician scarcity:Certified riggers and broadcast equipment handlers command premium wages in Sydney and Singapore, constraining on-site crew scaling for simultaneous events.
- Legacy warehouse management systems:Older facilities across Indonesia and Philippines lack API connectivity for real-time inventory synchronization with client ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Event Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Handling, On-Site Management, Set-Up & Dismantling, Equipment Rental End User: Corporate Events, Trade Shows, Concerts, Sports Events Technology: RFID Tracking, Event Management Software, Virtual Platforms, Audio-Visual Equipment Delivery Model: In-House, Outsourced, Hybrid, Customized Solutions |
| Companies Covered | YTO Express, DP World, Nippon Express, CEVA Logistics, JAS Worldwide, DHL Supply Chain, Kuehne + Nagel International, DB Schenker, DSV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Event Logistics Market Trends and Innovations
Digital orchestration layers are displacing manual coordination protocols across Asia Pacific event logistics, compressing planning cycles while embedding compliance verification into automated workflows.
Blockchain-enabled documentation is unifying customs clearance, insurance verification, and chain-of-custody records into single-source data architectures. Major exhibition organizers in Singapore and Dubai-Asia corridors are mandating distributed-ledger bills of lading for high-value audio-visual equipment. This convergence is unifying previously siloed compliance checkpoints into continuous digital threads that reduce border detention incidents.
Japan's METI energy efficiency codes are constraining power distribution and temporary climate control equipment deployed in venue build-outs. Rental providers must now certify diesel generator alternatives and battery storage configurations against revised consumption benchmarks. Concert touring operators face equipment substitution costs as legacy lighting rigs fail new thermal performance thresholds.
Consolidated vendor relationships are displacing fragmented spot-buying for recurring corporate events. Procurement teams at technology and pharmaceutical firms are narrowing approved logistics panels to three to five integrated providers capable of spanning freight, on-site installation, and post-event reverse logistics. This concentration is most visible in Australia, where chain of responsibility laws under the National Heavy Vehicle Regulator elevate liability for carrier selection decisions.
Asia Pacific Event Logistics Market Segmentation
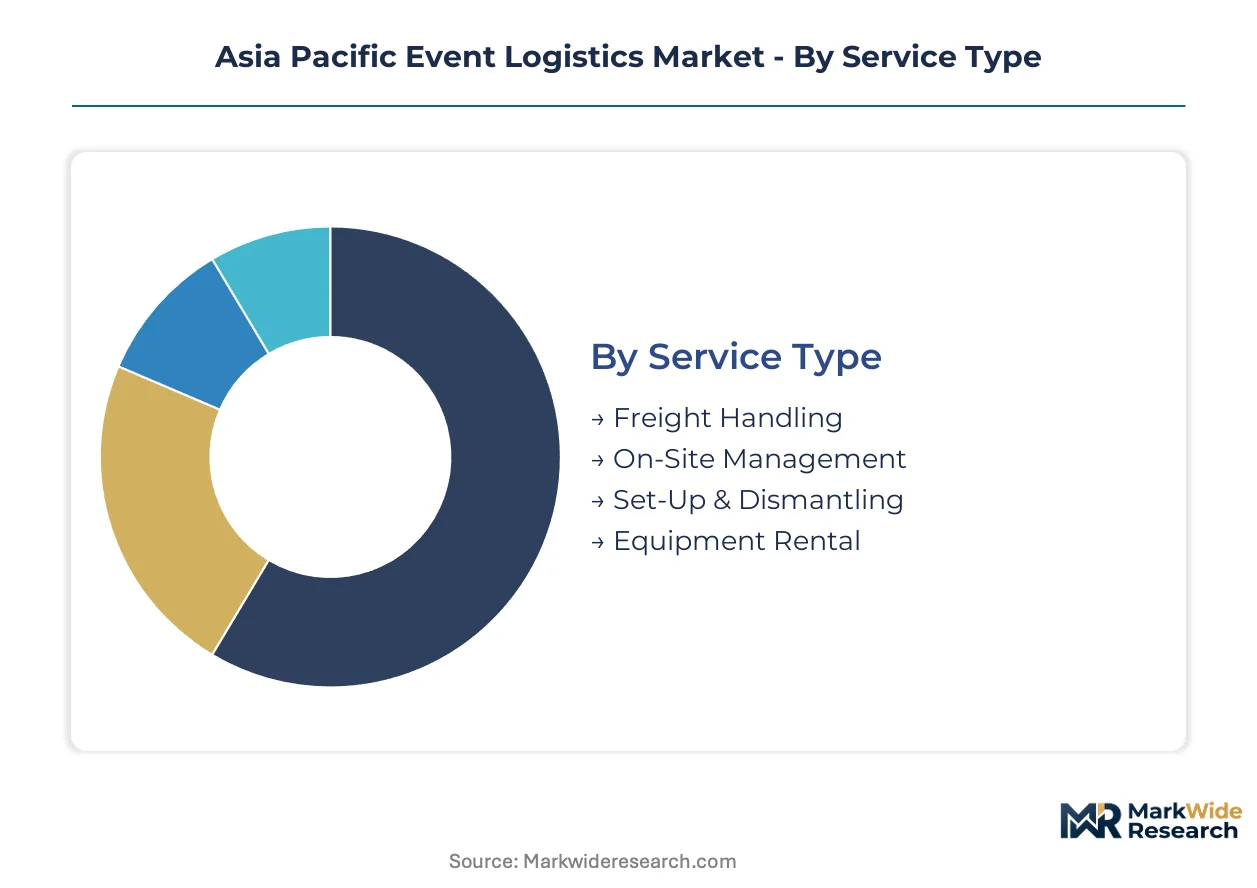
Asia Pacific event logistics operators configure service portfolios around certification burdens that vary sharply by equipment category and venue jurisdiction. Segmentation choices determine which GB, BIS, METI, or TGA compliance workflows a provider must maintain.
Service Type:
Freight handling and on-site management carry distinct certification obligations under China's MEE carbon intensity rules and Australia's chain of responsibility laws.
- Freight Handling:Cross-border consolidation of booth materials, audio-visual gear, and temporary structures demands bonded warehousing capabilities and customs brokerage licenses. China's dual carbon goals now require freight partners to document emission intensity per ton-kilometer for venue procurement tenders in Shanghai and Shenzhen.
- On-Site Management:Coordination of labor crews, material flow timing, and venue interface protocols. Singapore's compressed turnaround windows and rising technician wages push margin expansion here, though certified rigger scarcity in Sydney constrains simultaneous event scaling.
- Set-Up & Dismantling:Physical assembly of modular structures and technology rigs. India's BIS safety certifications for electrical and staging equipment create compliance thresholds for crews operating in Mumbai and Delhi exhibition complexes.
- Equipment Rental:Provision of display systems, lighting, and climate control assets. Japan's METI energy efficiency codes now constrain diesel generator and battery storage configurations, forcing rental fleets toward certified low-consumption alternatives.
Freight handling sits at the top of the volume ranking, with on-site management climbing the fastest.
End User:
End-user segments separate by event frequency, asset specificity, and the sustainability scrutiny applied by corporate procurement teams.
- Corporate Events:Recurring internal conferences and product launches with standardized booth requirements. Pharmaceutical and technology firms in Australia are consolidating approved logistics panels to three-to-five integrated providers capable of spanning freight through reverse logistics.
- Trade Shows:Multi-exhibitor temporary exhibitions with complex material coordination windows. Singapore's dominance as a transshipment hub concentrates sourcing from multiple ASEAN origins, creating single-point vulnerability for exhibition freight flows.
- Concerts:Touring music productions demanding high-velocity equipment repositioning. K-pop and regional festival circuits across Seoul, Bangkok, and Manila generate steepest expansion trajectory as arena bookings multiply.
- Sports Events:Single or periodic fixtures with broadcast infrastructure requirements. Temporary structure permits and crowd safety protocols vary across Australian states, fragmenting compliance preparation.
Corporate events anchor the revenue base, with concerts expanding most quickly.
Technology:
Technology deployment separates venues by digital maturity and the API connectivity of legacy warehouse management systems.
- RFID Tracking:Real-time inventory synchronization across Australia, China, and Southeast Asia. Material reconciliation windows compress from 48 hours to under 6 hours at major exhibition complexes with integrated tag infrastructure.
- Event Management Software:Digital orchestration platforms displacing manual coordination protocols. Older facilities across Indonesia and Philippines lack API connectivity for ERP synchronization, constraining adoption.
- Virtual Platforms:Hybrid event streaming and remote participation infrastructure. Post-pandemic retention in corporate segments sustains demand alongside physical logistics services.
- Audio-Visual Equipment:Broadcast and display technology subject to blockchain-enabled documentation mandates. Major exhibition organizers in Singapore and Dubai-Asia corridors now require distributed-ledger bills of lading for high-value gear.
RFID tracking leads technology investment volume, with event management software gaining share fastest.
Delivery Model:
Delivery model selection reflects internal capability depth and the liability exposure venues assign to external partners.
- In-House:Venue or organizer-operated logistics with captive crews and equipment fleets. Australia's National Heavy Vehicle Regulator elevates carrier selection liability, pushing some organizers toward direct control.
- Outsourced:Third-party provision of specialized freight, installation, or equipment services. Fragmented national regulations across India, China, and Japan force providers to maintain parallel compliance workflows.
- Hybrid:Split responsibility with core freight in-house and peak labor outsourced. Common in Vietnam where new convention centers in Ho Chi Minh City and Hanoi lack established logistics ecosystems.
- Customized Solutions:Bespoke integration across multiple service elements for recurring high-value events. Technology and pharmaceutical procurement teams favor concentrated vendor relationships over fragmented spot-buying.
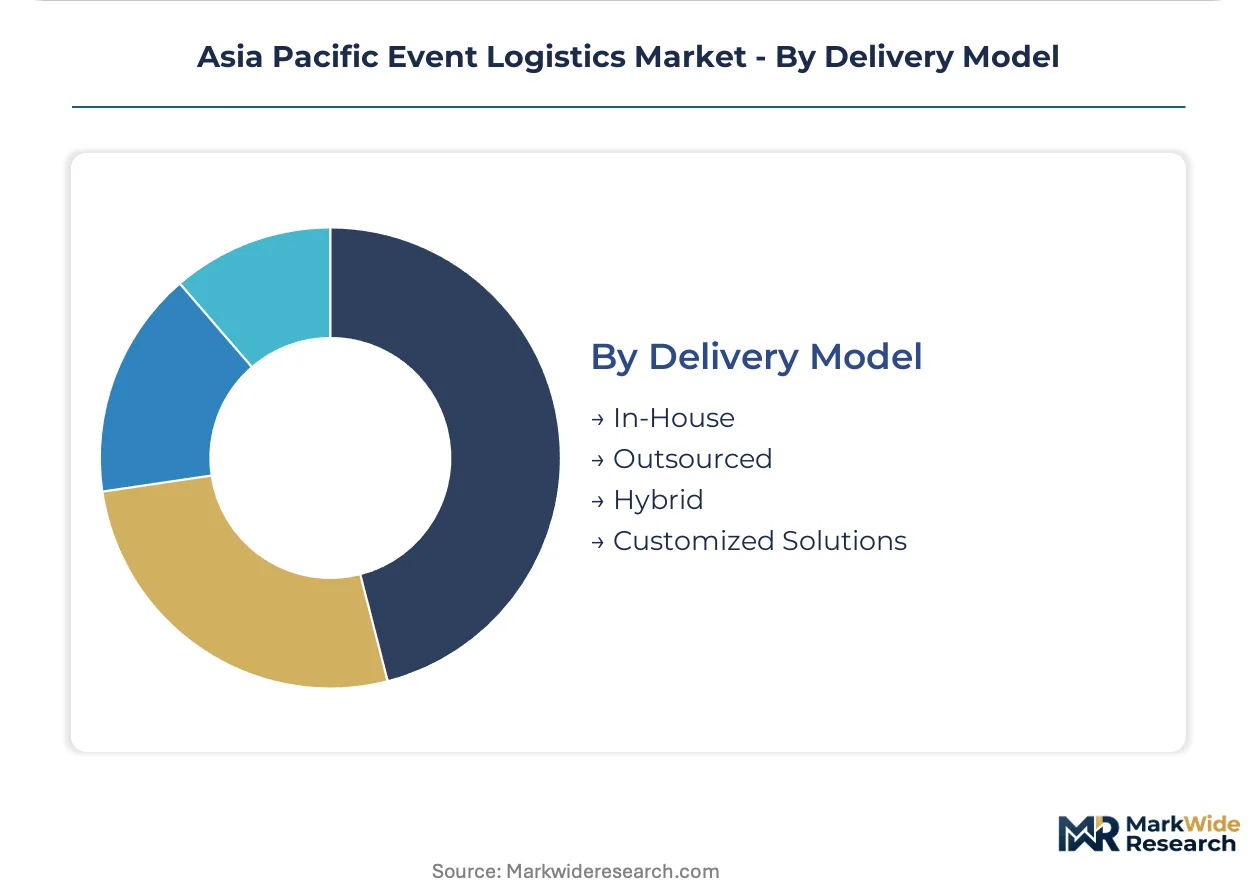
Outsourced delivery captures the largest transaction volume, with hybrid models climbing fastest as venues test capability buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's exhibition complexes anchor regional event logistics demand as compressed turnaround windows and sustainability mandates reshape service requirements across the Asia Pacific.
China
Shanghai and Shenzhen convention centers drive freight handling volume as venue procurement teams enforce MEE carbon intensity documentation per ton-kilometer. GB standards for temporary structures constrain equipment choices in venue build-outs, forcing logistics providers to certify modular display systems. The Yangtze River Delta cluster concentrates demand for low-emission freight partners serving pharmaceutical and technology sector conferences.
Japan
Tokyo and Osaka arena bookings for concert touring circuits generate demand for high-precision equipment transport and rapid repositioning between dates. METI energy efficiency codes now constrain diesel generator and battery storage configurations in rental fleets, elevating compliance costs for power distribution equipment. The Kanto region's broadcast technology sector anchors specialized handling requirements for audio-visual gear.
Australia
Sydney and Melbourne corporate events sustain recurring demand for integrated freight-to-floor providers capable of spanning logistics through reverse logistics. National Heavy Vehicle Regulator chain of responsibility laws elevate carrier selection liability, pushing procurement teams toward consolidated vendor panels. New South Wales and Victoria exhibition infrastructure commands premium technician wages for certified rigging crews.
Singapore
The city-state's transshipment dominance concentrates exhibition freight flows from multiple ASEAN origins, creating single-point vulnerability for complex material coordination. Rising labor costs and 48-hour venue turnaround windows expand margins for on-site management services. The Marina Bay and Changi exhibition clusters lack established logistics ecosystems, opening positioning opportunities for integrated providers.
India
Mumbai and Delhi exhibition complexes generate demand as BIS safety certifications for electrical and staging equipment create compliance thresholds for rental providers entering the market. Corporate event procurement teams fragment across spot-buying relationships, resisting the vendor consolidation visible in Australia. The Maharashtra and Delhi-NCR clusters concentrate pharmaceutical sector conference activity with standardized booth requirements.
Asia Pacific Event Logistics Market Competitive Landscape
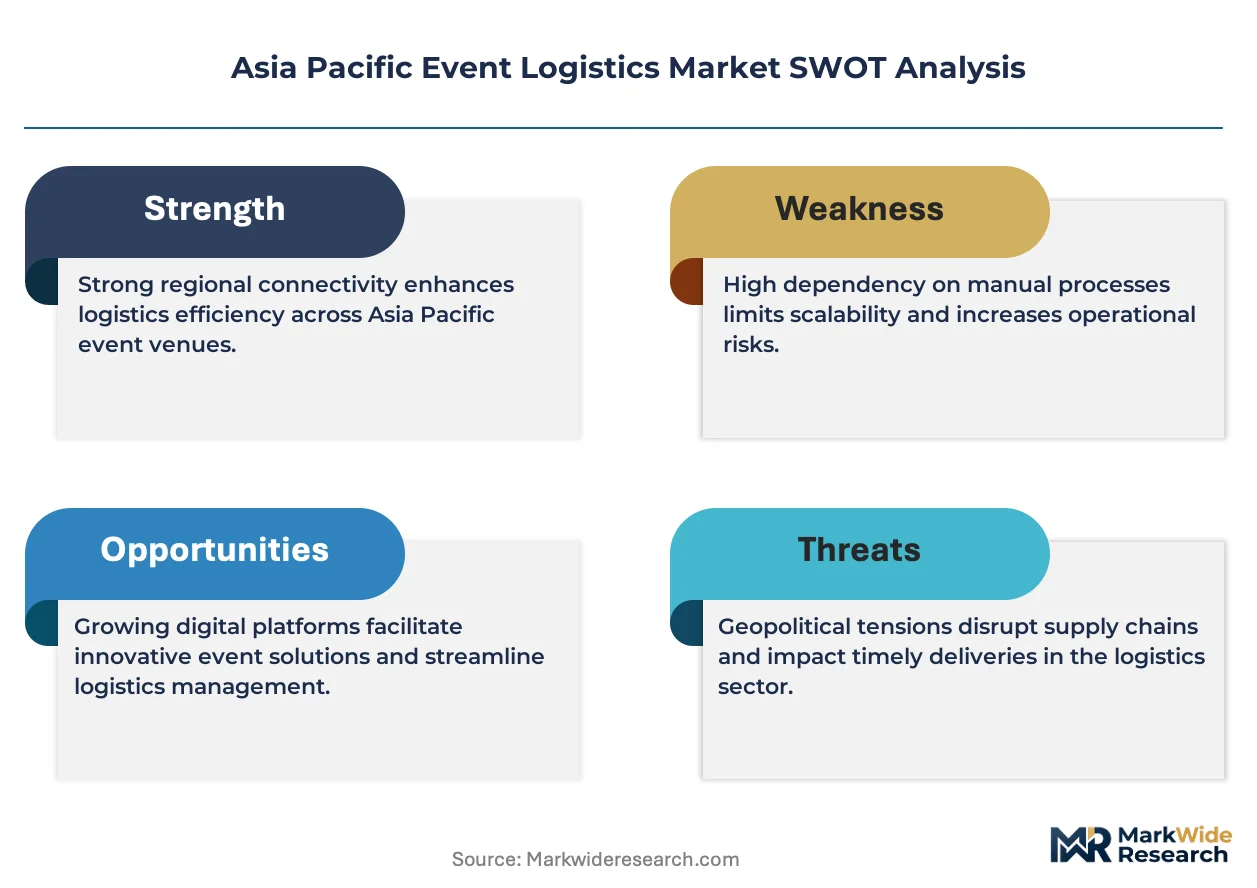
Global majors compete with regional champions across service integration depth, as consolidated vendor relationships displace fragmented spot-buying for recurring corporate events. The market structure tiers around port-centric infrastructure control, RFID-integrated warehousing networks, and high-precision equipment handling specialization. Three archetypes dominate: integrated freight-to-floor providers, port-centric exhibition specialists, and concert touring logistics operators. Competitive moves concentrate on strategic partnerships for venue ecosystem access and portfolio diversification into reusable modular systems.
Within the integrated logistics tier, DP World leverages port-centric infrastructure to control inbound freight flows, while DHL Supply Chain anchors RFID-integrated warehousing networks spanning Australia, China, and Southeast Asia. Nippon Express occupies a position exemplifying high-precision equipment transport specialization for Japan's concert and broadcast technology sectors. These three represent distinct competitive vectors: infrastructure control, digital orchestration, and vertical technical capability.
| Leading Market Players |
|---|
| YTO Express |
| DP World |
| Nippon Express |
| CEVA Logistics |
| JAS Worldwide |
| DHL Supply Chain |
| Kuehne + Nagel International |
| DB Schenker |
| DSV |
| Others |
Pricing and Supply Chain Analysis
Captive warehousing networks in Singapore and Shanghai anchor supply positions for Asia Pacific event logistics providers while simultaneously determining pricing power through bonded inventory control and customs clearance speed. Port-centric infrastructure investments by DP World and DHL Supply Chain create tiered service premiums that compress margins for asset-light competitors lacking similar upstream integration.
Pricing Analysis
Jet kerosene and marine diesel cost pass-throughs directly compress margins on air and sea freight legs for time-critical booth materials and audio-visual equipment. Project-based pricing dominates, with differentiation anchored in certification grade under China's MEE carbon intensity rules and Australia's National Heavy Vehicle Regulator compliance tiers. Cost compression in standard freight services is intensifying because fuel volatility erodes fixed-rate contract viability. Corporate event procurement teams exhibit lowest price sensitivity due to consolidated vendor panels, while concert touring operators face acute margin pressure from simultaneous multi-city equipment repositioning demands.
Supply Chain Analysis
Direct-to-venue channels handle hyperscale exhibition demand through Singapore's transshipment hub, which concentrates inbound flows from China, Vietnam, and Thailand manufacturing origins. Raw material dependencies center on aluminum frame systems, lithium battery storage configurations, and RFID tag infrastructure. Single-source vulnerability runs through Singapore's port dominance, where exhibition freight from multiple ASEAN origins converges before final-mile distribution. Distribution runs through hybrid models combining in-house core freight with peak labor outsourcing, particularly visible in Vietnam's emerging convention center markets lacking established logistics ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MEE carbon intensity enforcement and Japan's METI energy efficiency codes continuously elevate compliance investment thresholds for new entrants.
For Market Incumbents: Deploy RFID-integrated warehousing as the primary lever to compress material reconciliation windows and defend against modular equipment fleet competitors. Incumbents should deepen backward integration into reusable aluminum frame manufacturing to capture waste reduction mandate premiums in Australian states. Certified rigger scarcity in Sydney and Singapore threatens simultaneous event scaling capacity. For New Entrants and Emerging Players: Capture first-mover positioning in Vietnam's Ho Chi Minh City and Hanoi convention center corridors where established logistics ecosystems remain underdeveloped. The most penetrable segment spans integrated freight-to-floor services for pharmaceutical sector conferences with standardized booth requirements. A direct digital orchestration platform bypassing legacy warehouse management system limitations in Indonesia and Philippines offers viable go-to-market differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented national regulations across India, China, and Japan force parallel compliance workflow maintenance that mid-cap specialists cannot sustain. Long-term viability favors integrated providers spanning freight handling through on-site management with captive certification capabilities. The signal to monitor is vendor panel consolidation velocity among Australian technology and pharmaceutical procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Warehouse Integration | Compresses material reconciliation from 48 hours to under 6 hours at Singapore exhibition complexes. |
| Reusable Modular System Investment | Aligns aluminum frame fleets with Australian state waste reduction mandates for 20+ reuse cycles. |
| Vietnam Market Entry Partnership | Secures first-mover positioning in Ho Chi Minh City and Hanoi convention center corridors. |
| Carbon Certification Investment | Documents emission intensity per ton-kilometer for China's MEE venue procurement tenders. |
| Cross-Border E-Commerce Platform | Bypasses traditional distributor layers connecting Chinese manufacturers to Southeast Asian event organizers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics operations directors, venue procurement managers, certified rigging crew supervisors, and customs brokerage leads with secondary validation. Sources included Singapore Maritime and Port Authority trade flow data, China's MEE carbon intensity disclosure filings, Australian National Heavy Vehicle Regulator compliance records, and Japan METI energy efficiency certification databases. Bottom-up freight volume modeling and top-down market sizing triangulated across service type and end-user segmentation dimensions.
Comparable-period anchoring linked historical freight handling volumes and on-site management transaction counts to projected venue construction pipelines and concert touring circuit expansion schedules across the analysis window. Segmentation modeling incorporated service type, end-user category, technology deployment, and delivery model dimensions. CAGRs derived from logistic curve fitting to exhibition infrastructure investment cycles and regulatory compliance cost trajectories. Industry-specific inputs included K-pop touring circuit arena booking velocity and China's dual carbon goal enforcement timelines.
Underlying measurement precision varies by segment; freight handling volumes carry tighter precision than nascent virtual platform integration metrics. Forecasts reflect assumptions regarding sustained MEE carbon intensity enforcement, METI energy efficiency code stringency, and Australian chain of responsibility law expansion. Periodic stress-testing of base assumptions is recommended against fuel cost volatility and port concentration risk scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
UAE Contract Logistics Market