
 China Shipping Agency Services Market | 2026-2036
China Shipping Agency Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Shipping Agency Services Market Outlook
Digital documentation platforms are rebalancing cost structures across traditional paper-based agency workflows. COSCO SHIPPING Development Co., Ltd anchors its position through captive port relationships along China's eastern seaboard. Sinotrans Limited leverages inland waterway connectivity to sustain freight consolidation volumes. China Marine Shipping Agency Co., Ltd dominates military and state-cargo segments where clearance protocols demand specialized expertise.
Shipping agency services encompass the coordination of vessel port calls, encompassing customs declaration, cargo documentation, berth scheduling, and regulatory compliance on behalf of shipowners or charterers. These services operate through electronic data interchange systems that transmit manifest files, bill-of-lading records, and customs declarations between port authorities, terminals, and carriers in standardized formats. Cargo handling and customs brokerage command the largest service-type revenue pools, while vessel tracking grows fastest as real-time AIS integration becomes mandatory at major Chinese ports. Freight forwarders represent the most concentrated client-type segment, though direct shipping company contracts yield superior margin retention for agencies with dedicated liner agreements.
China's Ministry of Transport and MIIT enforce port data security standards that restrict foreign-platform access to vessel scheduling systems. SAMR oversight of freight-rate filing and anti-monopoly provisions shapes how agencies bundle services with forwarding affiliates. Stakeholders must monitor evolving GB standards for maritime blockchain interoperability, as compliance timelines will determine which agency networks capture integrated logistics contracts.
Market Dynamics
Port digitalization mandates from MIIT are compressing documentation timelines and forcing agency networks to consolidate fragmented service tiers into unified platforms.
Growth Catalysts
- Shandong agricultural containerization:Rising export volumes through Qingdao and Yantai terminals are pulling integrated agency bundles that combine customs brokerage with cold-chain documentation.
- GB standards for maritime blockchain:Compliance timelines under draft interoperability protocols are creating first-mover advantages for agencies with captive IT development resources.
- Yangtze River Delta port integration:Shanghai-Ningbo coordination is eliminating redundant agency layers and concentrating contract volumes with networks offering cross-port coverage.
Market Restraints
- Foreign-platform exclusion:MIIT data-security restrictions block international vessel-scheduling systems from direct port authority integration, fragmenting technology procurement.
- Shanghai-Ningbo duopoly risk:Cargo concentration across these two mega-ports creates exposure to localized labor actions or weather disruptions.
- Paper-to-digital transition costs:Legacy document retention requirements under Maritime Code revisions impose parallel workflow maintenance through 2027.
Strategic Opportunities
- Inland waterway digitization:Sinotrans-connected Yangtze tributary ports remain underserved by real-time AIS tracking, opening captive routes for early platform deployers.
- Military-civilian clearance specialization:State-cargo segments with restricted berth protocols offer premium-margin contracts insulated from price competition.
- Freight-rate bundling under SAMR review:Anti-monopoly oversight creates compliance-driven demand for transparent service unbundling that separates agency fees from forwarding margins.
Industry Challenges
- Maritime blockchain talent scarcity:GB standards development outpaces domestic training pipelines for smart-contract documentation specialists.
- Legacy EDI system integration:Port authority data formats vary across Tianjin, Guangzhou, and Xiamen, forcing costly middleware development for multi-port agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Shipping Agency Services Market |
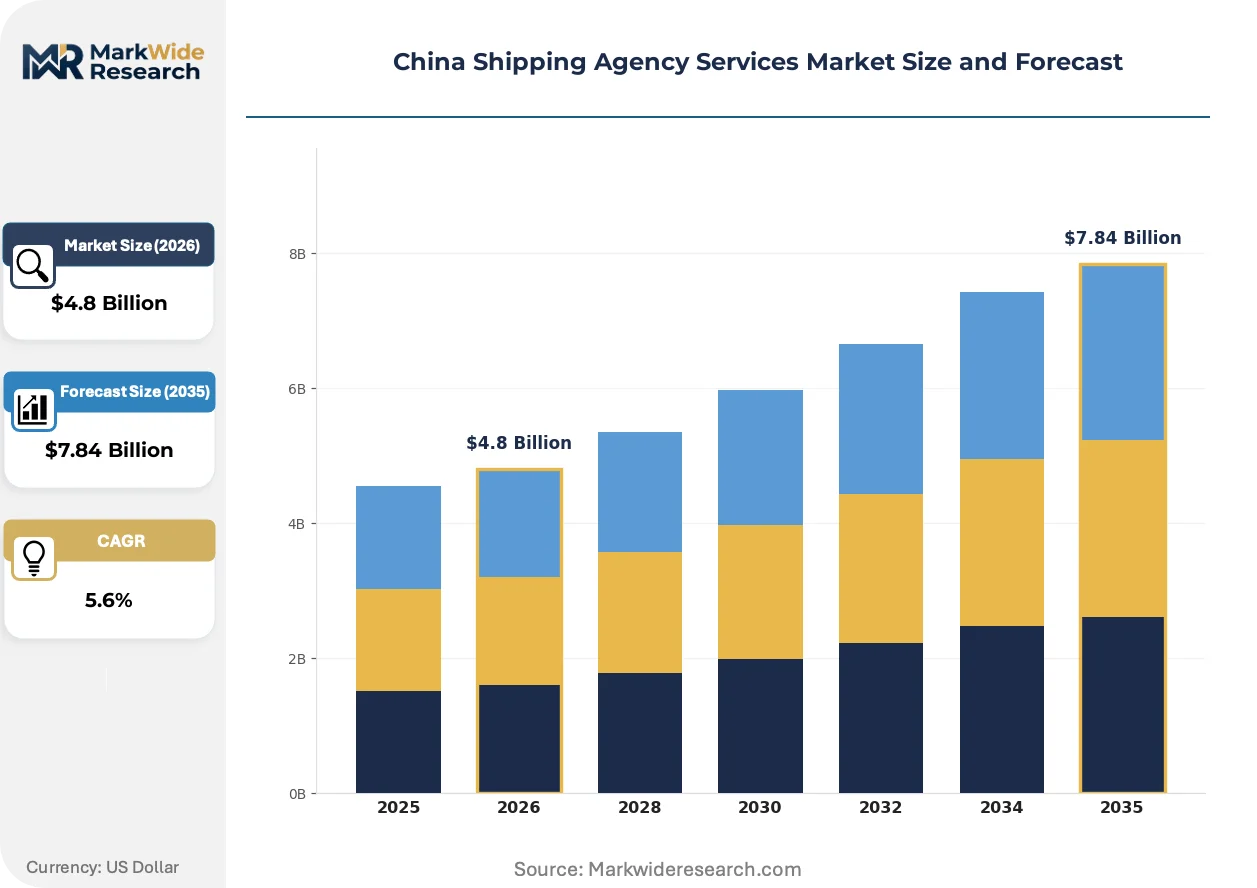
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port Clearance, Cargo Handling, Vessel Tracking, Customs Brokerage Client Type: Freight Forwarders, Shipping Companies, Importers, Exporters Operational Scale: Local, Regional, National, International Service Offering: Documentation, Freight Insurance, Risk Assessment, Consultancy |
| Companies Covered | China Marine Shipping Agency Co., Ltd, Shenzhen Fly International Logistics, SINO Shipping, Bansar, ET International Logistics, COSCO SHIPPING Development Co., Ltd, DDPCHAIN, Winsky Freight, Sinotrans Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Shipping Agency Services Market Strategic Shifts
Documentation automation and regulatory data-sharing mandates are collapsing the traditional sequential workflow between vessel arrival, customs clearance, and cargo release.
Electronic data interchange platforms with embedded customs-declaration modules are automating manifest transmission between carriers and port authorities. Freight forwarders in the Yangtze River Delta are adopting these systems fastest, driven by Shanghai-Ningbo integration timelines. This compression is eliminating 24-48 hour documentation buffers that previously sustained multi-agency handoffs.
MIIT port data-security standards are restricting foreign-platform access to vessel scheduling systems and mandating domestic server localization. The industrial consequence is a bifurcation between China-certified platforms and international systems, forcing multinational agencies to maintain parallel technology stacks. Container lines with direct Shanghai terminal contracts are absorbing compliance costs fastest, while smaller tramp operators face platform-access delays.
Direct carrier contracts are displacing freight-forwarder intermediation for documentation-heavy cargoes like refrigerated agricultural exports. Shandong-based exporters are consolidating vendor relationships with agencies offering captive customs-brokerage licenses, bypassing layered forwarding markups. This concentration is most visible in Qingdao's reefer terminal cluster, where integrated service bundles now capture documentation volumes previously fragmented across three to four vendors.
China Shipping Agency Services Market Segmentation
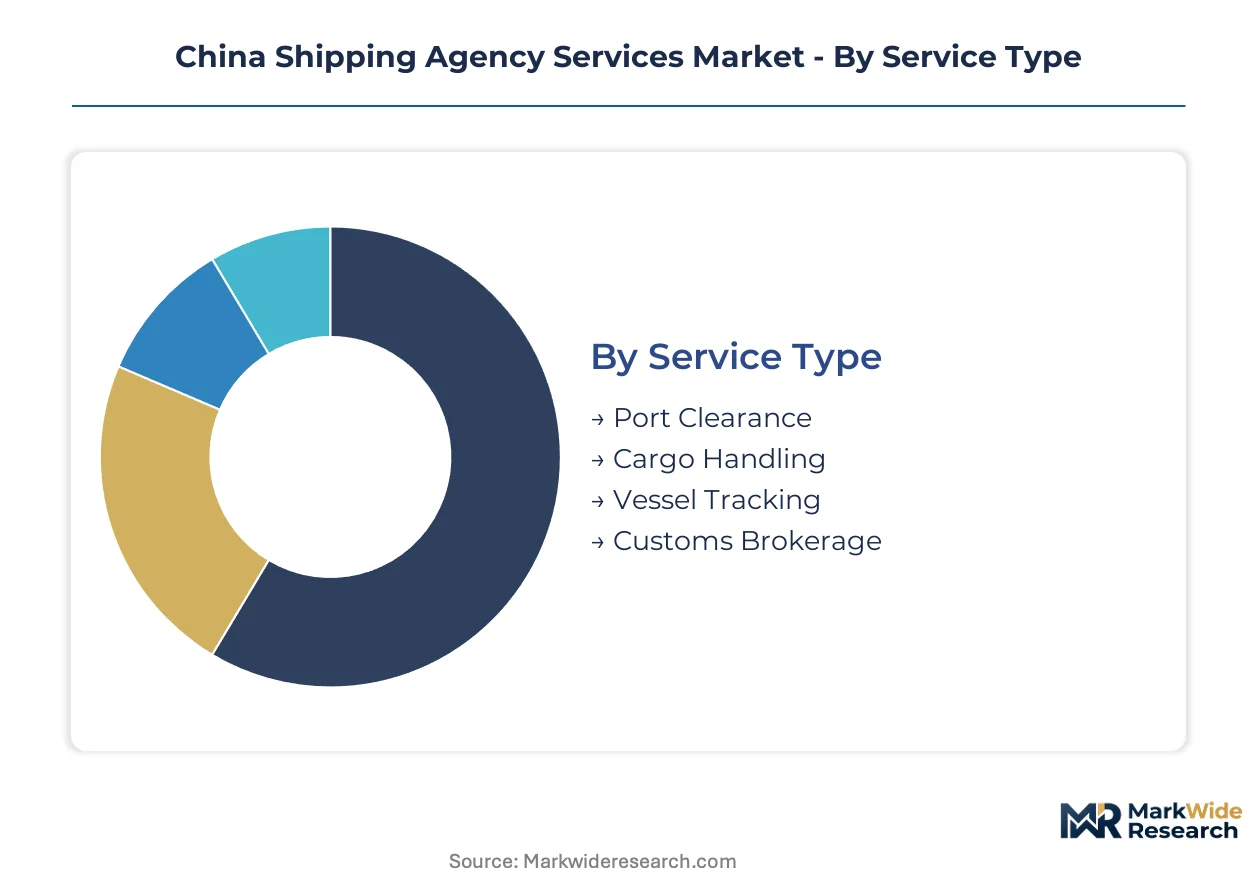
Service segmentation in China's shipping agency market determines contract structures and margin capture. MIIT digitalization mandates are compressing traditional service tiers into integrated bundles, reshaping how agencies position across operational categories.
Service Type:
Agencies upgrade legacy service portfolios to capture documentation automation contracts before GB blockchain standards finalize compliance windows.
- Port Clearance:Regulatory filing coordination with harbor authorities, pilotage scheduling, and quarantine documentation. Yangtze River Delta terminals concentrate demand as Shanghai-Ningbo integration eliminates redundant clearance layers between adjacent ports.
- Cargo Handling:Stevedoring supervision, tally services, and terminal liaison for container and breakbulk operations. Shandong agricultural exporters at Qingdao reefer terminals are consolidating handling contracts with integrated agency bundles that bundle cold-chain oversight.
- Vessel Tracking:Real-time AIS monitoring and berth-status transmission to carriers. MIIT mandates for domestic server localization accelerate platform procurement for this segment.
- Customs Brokerage:Declaration filing, duty calculation, and inspection coordination with customs authorities. Captive licensing requirements restrict market entry to established operators with SAMR-registered qualifications.
Cargo handling sits at the top of the volume ranking, with vessel tracking climbing the fastest.
Client Type:
Margin structures vary sharply by client procurement sophistication and contract centralization.
- Freight Forwarders:Intermediary clients purchasing agency services as bundled inputs for shipper contracts. Forwarder concentration in Yangtze River Delta clusters sustains volume but compresses pricing through competitive tendering.
- Shipping Companies:Direct carrier contracts with liner operators and tramp owners. COSCO SHIPPING Development and similar state carriers favor dedicated agency relationships with multi-port coverage guarantees.
- Importers:Domestic cargo owners requiring inbound clearance and terminal release coordination. Manufacturing clusters in Guangdong and Jiangsu provinces drive regional demand concentration.
- Exporters:Outbound shippers needing documentation for agricultural, electronics, and machinery cargoes. Shandong containerization expansion pulls integrated service adoption for reefer documentation.
Freight forwarders anchor contract volumes, though direct shipping company agreements yield superior margin retention.
Operational Scale:
Geographic coverage scope determines technology investment requirements and regulatory compliance burden.
- Local:Single-port operations serving Tianjin, Xiamen, or Dalian terminals. Local specialists retain niche positions in military-cargo segments with restricted berth protocols.
- Regional:Multi-port networks spanning provincial clusters like Shandong or Fujian. Regional operators face consolidation pressure from national networks offering cross-port pricing.
- National:Coverage across all major coastal and Yangtze inland ports. National scale requires parallel technology stacks to accommodate varying port authority EDI formats.
- International:Coordination with foreign agency networks for Chinese-flagged vessels abroad. MIIT data-security restrictions fragment international platform integration.
National-scale operations command the largest contract values, with regional networks expanding most quickly through port integration spillover.
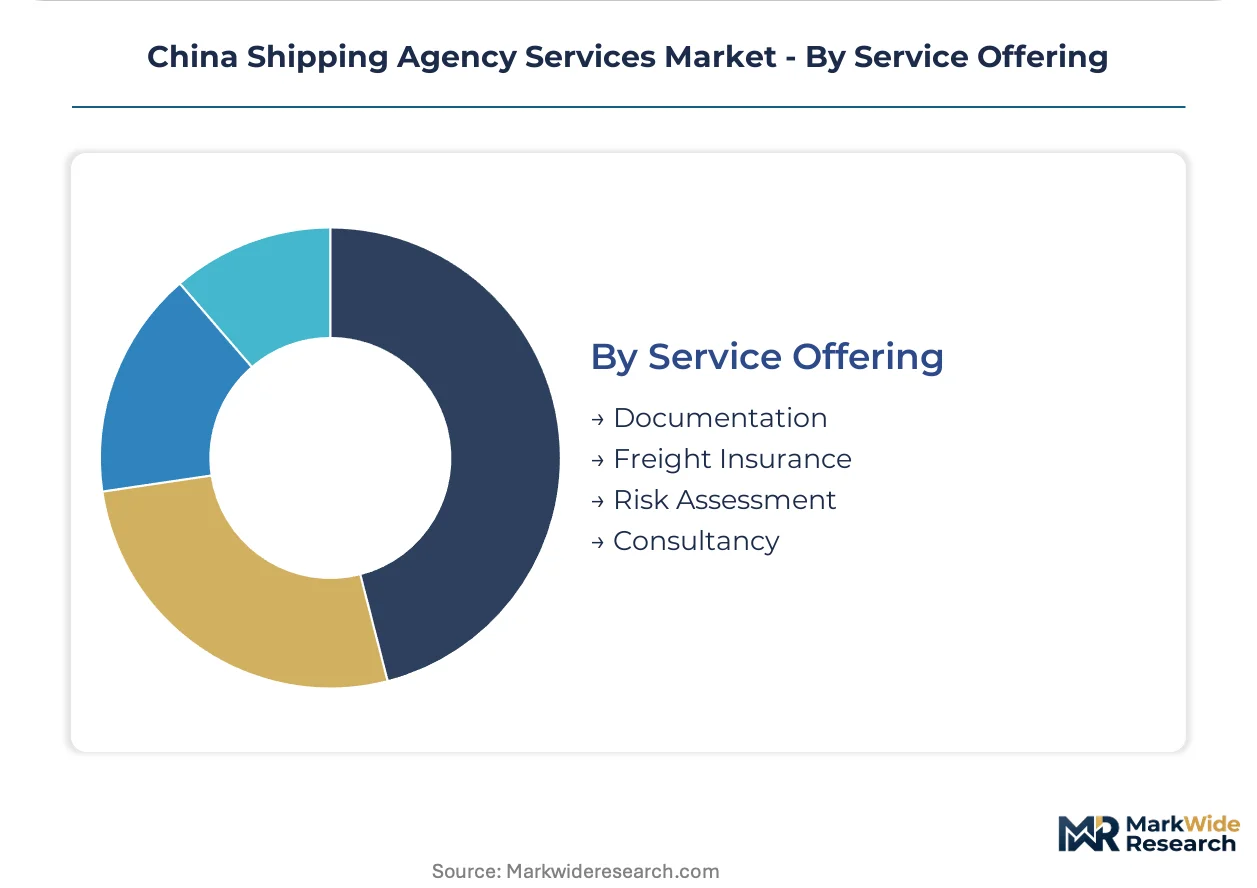
Service Offering:
Value-added offerings separate premium agency tiers from documentation-only competitors.
- Documentation:Core manifest preparation, bill-of-lading processing, and certificate issuance. Automation platforms are collapsing 24-48 hour processing buffers that previously sustained manual workflows.
- Freight Insurance:Marine cargo policy placement and claims coordination. SAMR oversight of rate filing creates compliance-driven demand for transparent insurance unbundling.
- Risk Assessment:Port congestion forecasting, weather routing advice, and regulatory change monitoring. Specialist expertise concentrates in agencies serving state-cargo segments.
- Consultancy:Supply chain optimization and customs strategy advisory. Consultancy margins expand where agencies combine operational data with regulatory interpretation capabilities.
Documentation generates the highest transaction volumes, while consultancy offerings gain share fastest as shippers seek compliance navigation support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta port integration is reshaping agency service procurement patterns across China's coastal provinces. MIIT digitalization mandates and Maritime Code revisions are compressing documentation timelines and forcing network consolidation. Regional demand concentrates where agricultural containerization, electronics manufacturing, and state-cargo segments overlap.
Shandong Peninsula
Qingdao and Yantai terminals are pulling integrated agency bundles for refrigerated agricultural exports. Maritime Code revisions impose parallel paper-digital workflow requirements through 2027. Cold-chain documentation specialists are consolidating vendor relationships at Qingdao's reefer terminal cluster.
Beijing-Tianjin-Hebei
Tianjin Port's breakbulk and container operations sustain demand for customs brokerage with captive licensing. SAMR oversight of freight-rate filing shapes how agencies bundle services with forwarding affiliates. State-cargo segments with restricted berth protocols command premium-margin contracts in this northern hub.
Pearl River Delta
Guangzhou and Shenzhen terminals drive inbound clearance coordination for manufacturing clusters in Guangdong Province. MIIT data-security standards restrict foreign-platform access to vessel scheduling systems. Electronics exporters are consolidating documentation volumes with agencies offering multi-port coverage guarantees.
Fujian Coastal
Xiamen Port's varying EDI data formats force costly middleware development for multi-port agency networks. GB standards for maritime blockchain interoperability are creating first-mover advantages for IT-resourced operators. Regional specialists face consolidation pressure from national networks offering cross-port pricing.
Western China
Inland waterway connectivity through Yangtze tributaries remains underserved by real-time AIS tracking platforms. Sinotrans-linked routes offer captive opportunities for early digital deployers. Chongqing's river-sea intermodal hub is digitizing manifest transmission between carriers and port authorities.
China Shipping Agency Services Market Competitive Environment
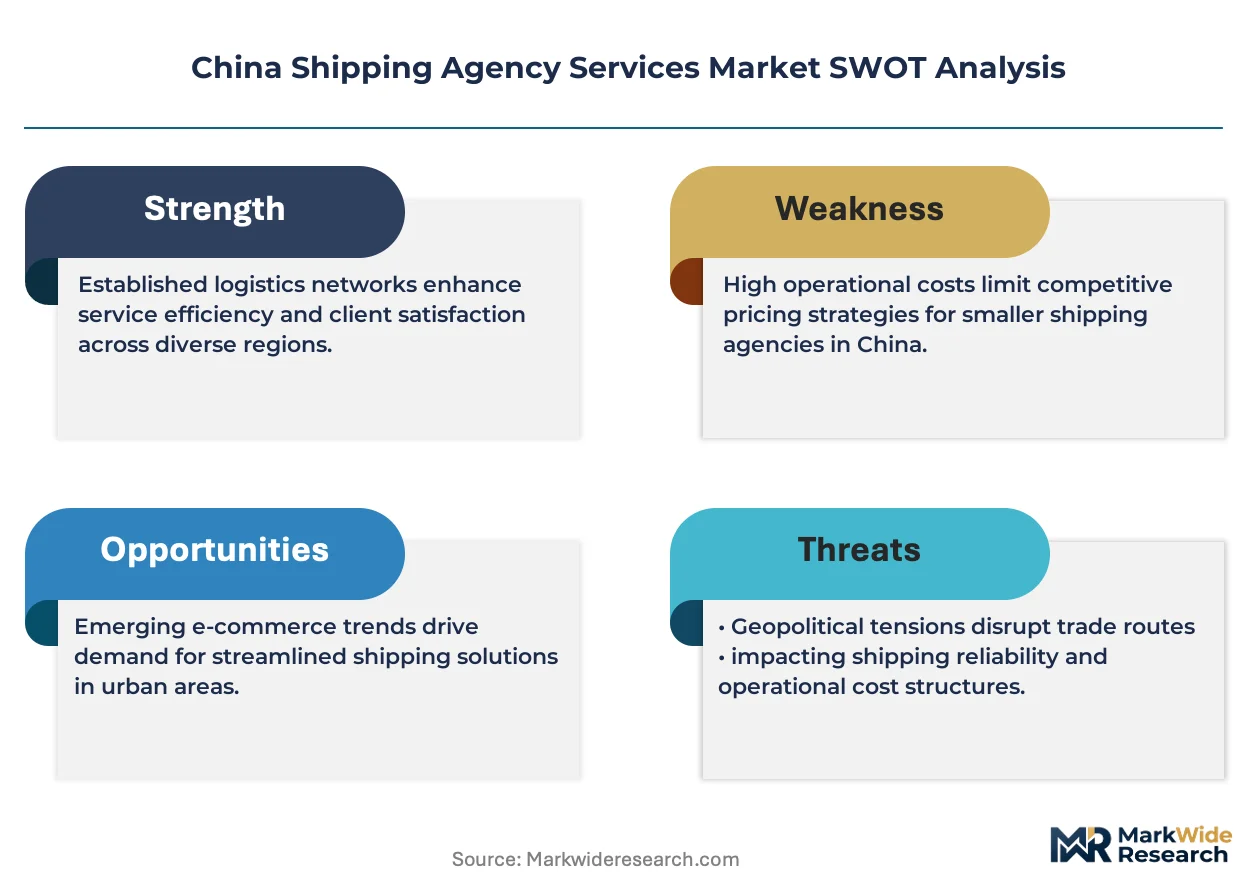
Network consolidation dominates the current landscape as port integration eliminates redundant agency layers between adjacent terminals. The vendor base spans state-affiliated maritime groups, regional logistics integrators, and digital-native platform operators. Three archetypes define competitive positioning: captive port-relationship specialists, inland waterway connectivity providers, and military-cargo clearance experts. M&A activity and proprietary platform development represent the dominant competitive vectors as GB blockchain compliance windows narrow.
Among state-affiliated maritime service providers, COSCO SHIPPING Development Co., Ltd and China Marine Shipping Agency Co., Ltd occupy positions reflecting captive infrastructure access and specialized clearance expertise. Sinotrans Limited exemplifies the inland waterway connectivity archetype through its Yangtze tributary network. These entities represent how regulatory data-localization requirements and state-cargo protocols create defensive market positions against price-competitive challengers.
| Leading Market Players |
|---|
| China Marine Shipping Agency Co., Ltd |
| Shenzhen Fly International Logistics |
| SINO Shipping |
| Bansar |
| ET International Logistics |
| COSCO SHIPPING Development Co., Ltd |
| DDPCHAIN |
| Winsky Freight |
| Sinotrans Limited |
| Others |
Value Chain & Pricing Dynamics
Port digitalization mandates from MIIT are compressing documentation timelines while simultaneously reshaping cost economics and supply concentration. The shift from paper-based workflows to electronic data interchange platforms eliminates redundant agency layers, concentrating contract volumes with operators capable of absorbing upfront platform investments.
Pricing Analysis
Input-cost pass-through from proprietary IT platform development and domestic server localization requirements is reshaping margin structures across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates national-scale operators with captive port relationships from regional specialists and local document-only agencies. Pricing pressure stems from freight forwarder consolidation in Yangtze River Delta clusters, where competitive tendering compresses markups. Smaller tramp operators exhibit highest price sensitivity due to fragmented cargo volumes, while state carriers with direct terminal contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Workforce availability for maritime blockchain smart-contract specialists concentrates in Shanghai, Beijing, and Shenzhen, creating geographic bottlenecks for platform development talent. The supply chain draws from domestic IT infrastructure providers, port authority EDI system vendors, and SAMR-registered customs brokerage qualification trainers. Single-source vulnerability runs through MIIT-certified platform providers, where foreign-system exclusion fragments technology procurement alternatives. Distribution runs through direct carrier contracts and freight forwarder intermediary networks, with the former capturing superior margin retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's shipping agency services market functions as a geographic-arbitrage play between Yangtze River Delta cost compression and Shandong Peninsula premium-margin agricultural documentation. MIIT data-localization requirements impose compliance burdens on foreign-platform operators that domestic IT-resourced agencies bypass entirely.
For Market Incumbents: Deepen captive port relationships along China's eastern seaboard to defend against national-network consolidation pressure. Invest in proprietary maritime blockchain development ahead of GB standards finalization to secure first-mover compliance advantages. Absorb cold-chain documentation specialization costs at Qingdao reefer terminals before agricultural containerization volumes peak. For New Entrants and Emerging Players: GB standards for maritime blockchain interoperability in China opens a window for IT-native platform operators to capture documentation automation contracts from legacy EDI-dependent incumbents. Target inland waterway digitization along Yangtze tributaries where Sinotrans-connected routes remain underserved by real-time AIS tracking. Lead with transparent service unbundling that separates agency fees from forwarding margins under SAMR anti-monopoly review. For Investors and Strategic Acquirers: Valuations sit cheapest among regional multi-port networks facing consolidation pressure from national operators with cross-port pricing power. Five-to-ten year viability hinges on captive IT development resources and military-civilian clearance licensing moats. Watch GB blockchain compliance timeline acceleration as the inflection signal determining which agency networks capture integrated logistics contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Platform Development | MIIT-certified domestic systems bypass foreign-platform exclusion mandates at major ports. |
| Cold-Chain Documentation Specialization | Shandong agricultural exporters consolidate vendor relationships with integrated service bundles. |
| Inland Waterway Digitization | Sinotrans-linked Yangtze tributary routes offer captive growth for early AIS deployers. |
| Military-Civilian Clearance Licensing | State-cargo segments with restricted berth protocols command premium-margin contracts. |
| Cross-Port Network Consolidation | Shanghai-Ningbo integration eliminates redundant agency layers between adjacent terminals. |
Study Parameters
Coverage spans China's coastal provinces and Yangtze River inland waterway corridors, with primary inputs from each regional cluster. Primary interviews with port authority operations directors, customs brokerage license holders, freight forwarder procurement leads, and maritime IT platform developers combined with secondary validation from MIIT policy circulars, SAMR regulatory filings, and port authority EDI system documentation. Bottom-up service-type volume estimates and top-down market size triangulation anchored the analytical framework.
Rate-of-change decomposition across the projection horizon separated volume growth drivers from price-mix effects. Segmentation dimensions modeled include service type, client procurement sophistication, operational geographic coverage, and value-added offering tier. CAGRs derived from trend extrapolation of port call volumes, documentation automation adoption curves, and regulatory compliance timeline impacts. Shandong agricultural containerization expansion and Yangtze River Delta port integration spillover served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT data-security standard acceleration or Maritime Code revision delays. Forecasts reflect assumptions regarding GB blockchain interoperability implementation timelines and SAMR anti-monopoly enforcement intensity. Material deviation in Shanghai-Ningbo labor action frequency or cold-chain documentation talent availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market