
 Middle East and Africa Freight & Logistics Market | 2026-2036
Middle East and Africa Freight & Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Freight & Logistics Market Insights
Truck driver availability across the GCC is rotating toward certified operators capable of managing IoT-enabled fleet systems, tightening labor supply for conventional haulage. DHL leverages its Dubai South hub infrastructure to dominate pharmaceutical cold chain corridors into East Africa. Aramex sustains last-mile density through franchise partner networks in secondary Egyptian and Nigerian cities. Gulf Agency Company (GAC) anchors project cargo capabilities serving offshore energy installations across the Red Sea basin.
Freight and logistics encompasses the physical movement, storage, and coordination of goods through multimodal networks operating across temperature-controlled, bulk, containerized, and project-specific parameters, with fleet telematics and warehouse management systems governing real-time inventory visibility and route optimization. The primary commercial purpose centers on reducing dwell time between production and consumption nodes while minimizing inventory carrying costs for shippers. Transportation mode selection shows sea freight commanding intercontinental volume while road networks capture intra-regional distribution, with air freight occupying premium perishable and emergency shipment segments. End user concentration in e-commerce is restructuring warehousing requirements toward micro-fulfillment centers and same-day delivery radii, while manufacturing accounts retain demand for synchronized inbound supply chains serving just-in-line assembly plants.
UAE's General Civil Aviation Authority and Saudi Arabia's Transport General Authority coordinate cross-border permit regimes for autonomous trucking trials, while South Africa's National Regulator for Compulsory Specifications enforces vehicle safety standards affecting fleet replacement cycles. Egypt's customs modernization directives and Nigeria's port automation mandates are reshaping clearance timelines and bonded storage requirements. Stakeholders must monitor how Gulf standardization bodies align autonomous vehicle protocols with existing road safety frameworks before committing capital to unmanned fleet deployment.
Market Dynamics
Fleet telematics integration across the Jeddah-Riyadh-Dubai corridor is compressing dwell times and forcing asset-light operators toward technology partnerships or exit. This concentration dynamic is redrawing competitive boundaries around data capabilities rather than vehicle ownership alone.
Growth Catalysts
- UAE Autonomous Vehicle Testing Regulations:Dubai South's regulatory sandbox permits unmanned truck trials on designated freight corridors, accelerating validation timelines for sensor fusion systems before commercial deployment.
- Pharmaceutical Cold Chain Expansion:Temperature-controlled warehousing investments along the Red Sea basin are creating dedicated lanes for biologics distribution into East African markets with limited existing infrastructure.
- E-commerce Fulfillment Networks:Same-day delivery radii from micro-fulfillment centers in secondary Egyptian and Nigerian cities are generating demand for bonded last-mile density.
Market Restraints
- Fleet Modernization Capex Burden:Euro VI and equivalent emission standards across Saudi Arabia and UAE are forcing premature replacement cycles for conventional diesel tractors before depreciation recovery.
- Certified Driver Supply Concentration:IoT-enabled fleet systems require operators with combined commercial licenses and telemetry certification, creating a bottleneck distinct from conventional haulage labor pools.
- Cross-Border Permit Fragmentation:GCC corridor movements face inconsistent documentation requirements between Saudi Arabia's Transport General Authority and UAE's General Civil Aviation Authority jurisdictions.
Strategic Opportunities
- Secondary City Franchise Networks:Last-mile density partnerships in Port Harcourt, Alexandria, and Dar es Salaam remain underpenetrated relative to primary metro corridors.
- Project Cargo Energy Corridors:Offshore installation decommissioning and renewable construction across the Red Sea basin is generating specialized heavy-lift requirements beyond standard containerized capacity.
- Customs Modernization Tailwinds:Egypt's port automation mandates and Nigeria's single-window clearance reforms are compressing bonded storage dwell times for compliant operators.
Industry Challenges
- Telematics Integration Complexity:Legacy warehouse management systems in established GCC logistics zones require middleware development to synchronize with real-time fleet visibility platforms.
- Autonomous Protocol Standardization Delays:Gulf standardization bodies have yet to align sensor redundancy requirements with existing road safety frameworks, freezing capital commitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Freight & Logistics Market |
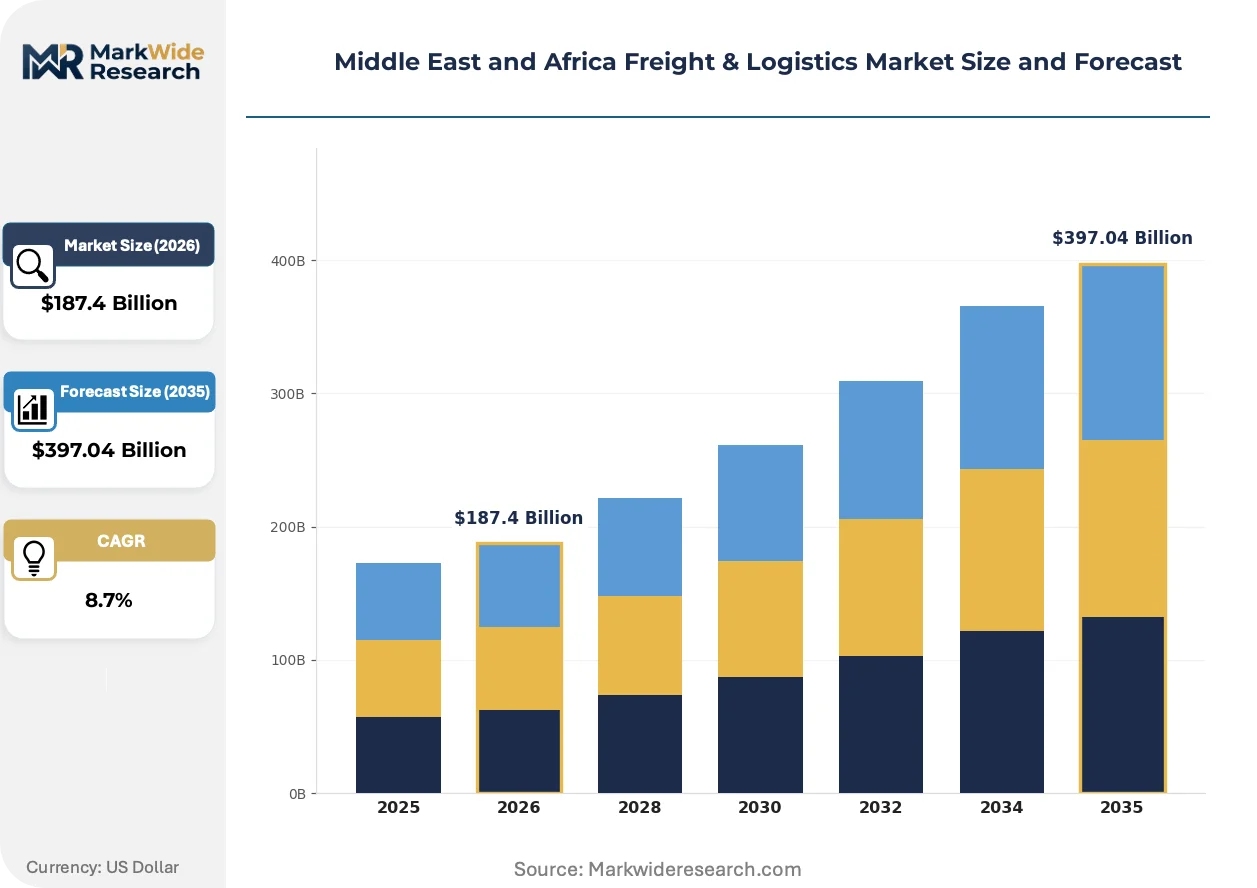
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Supply Chain Management End User: E-commerce, Manufacturing, Retail, Automotive Technology: Artificial Intelligence, Blockchain, Internet of Things, Automation Transportation Mode: Road, Air, Sea, Rail |
| Companies Covered | DHL, Aramex, Gulf Agency Company (GAC), RAK Logistics, Al-Futtaim Logistics, Agility Logistics, Kuehne + Nagel, Ceva Logistics, Almajdouie Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Freight & Logistics Market Trends and Innovations
Digital freight matching platforms are compressing broker margins and shifting pricing power toward shippers with predictable volume profiles. This disintermediation is accelerating consolidation among asset-based carriers with proprietary data infrastructure.
Edge computing nodes embedded in refrigerated containers are miniaturizing temperature monitoring from centralized warehouse systems to individual shipment units. Pharmaceutical distributors across the UAE and Saudi Arabia are adopting these devices for lane qualification documentation. Real-time cold chain verification is miniaturizing compliance costs and enabling direct-to-pharmacy distribution models previously requiring intermediary quality checkpoints.
Saudi Arabia's logistics zone licensing reforms are eliminating foreign ownership restrictions in bonded facilities, triggering facility upgrades near Jeddah Islamic Port. The Transport General Authority's streamlined permitting is compressing operational setup timelines from 18 months to under 9 months for qualified applicants. European and Asian 3PLs are responding through joint ventures with local license holders rather than greenfield development.
Shippers in the GCC are consolidating procurement around integrated service contracts bundling warehousing, line-haul, and last-mile execution. This bundling is displacing point-solution tenders and favoring operators with owned assets across all three legs. Manufacturing accounts serving just-in-line assembly plants in Dubai Industrial City and Jeddah's King Abdullah Economic City are driving this consolidation most visibly.
Middle East and Africa Freight & Logistics Market Segmentation
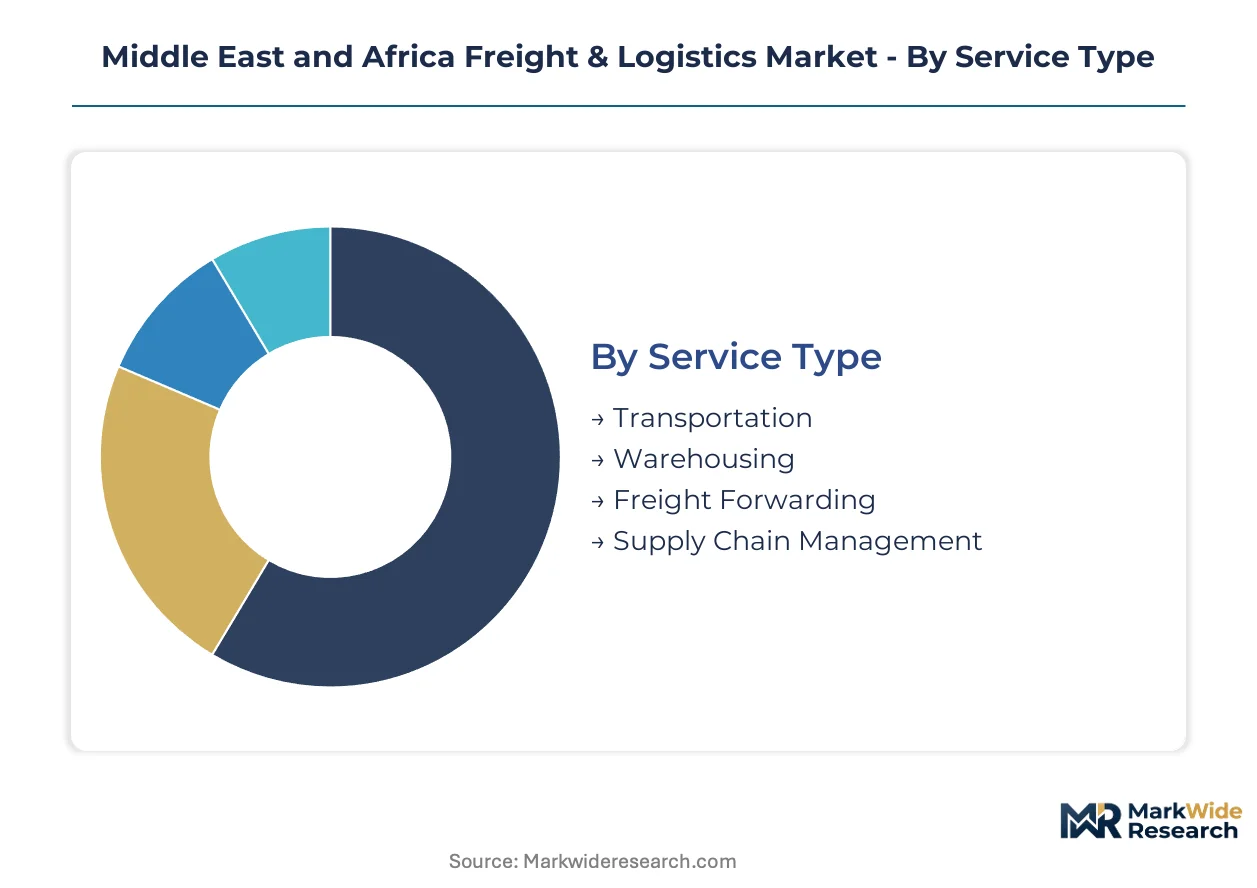
Segmentation reveals how fleet telematics and bonded warehousing investments are concentrating capital across distinct service layers. Understanding substitution pressures between modes and technologies guides resource allocation in the Jeddah-Riyadh-Dubai corridor.
Service Type:
Substitution pressure runs strongest against standalone warehousing as integrated contracts bundle storage with line-haul execution.
- Transportation:Road and air modes dominate intra-regional distribution with real-time fleet tracking now baseline for contract renewal. Demand clusters in the Jeddah-Riyadh-Dubai triangle where port capacity upgrades require synchronized drayage capacity.
- Warehousing:Bonded facilities near Jeddah Islamic Port and Dubai South are upgrading to temperature-controlled specifications for pharmaceutical corridors. Euro VI emission standards are accelerating automation investments to reduce labor dependency.
- Freight Forwarding:Digital platforms are compressing traditional broker margins across Egyptian and Nigerian customs corridors.
- Supply Chain Management:Manufacturing accounts in King Abdullah Economic City are driving demand for synchronized inbound supply chains.
Transportation retains volume leadership; Supply Chain Management holds the steepest expansion curve.
End User:
Cost tier differentiation separates premium cold chain requirements from standardized parcel movements.
- E-commerce:Same-day delivery radii from micro-fulfillment centers in secondary Egyptian and Nigerian cities are restructuring last-mile asset deployment. Franchise partner networks sustain density where owned fleet economics fail.
- Manufacturing:Just-in-line assembly plants in Dubai Industrial City require synchronized inbound supply chains with minimal inventory buffers. IoT-enabled fleet systems govern supplier coordination.
- Retail:Seasonal volume spikes concentrate procurement around integrated service contracts bundling warehousing and distribution.
- Automotive:Project cargo capabilities serve knock-down kit assembly operations with specialized handling requirements.
E-commerce retains volume leadership; Manufacturing holds the steepest expansion curve.
Technology:
Application maturity varies sharply between proven tracking systems and experimental autonomous protocols.
- Artificial Intelligence:Route optimization algorithms are compressing dwell times across the GCC corridor. Dubai South's regulatory sandbox permits unmanned truck trials validating sensor fusion systems.
- Blockchain:Documentation verification pilots are reducing customs clearance friction at Egyptian and Nigerian ports.
- Internet of Things:Edge computing nodes embedded in refrigerated containers enable real-time cold chain verification for pharmaceutical distribution. Temperature monitoring miniaturizes from centralized warehouse systems to individual shipment units.
- Automation:Autonomous protocol standardization delays are freezing capital commitment timelines until Gulf bodies align sensor redundancy requirements with existing road safety frameworks.
Internet of Things retains volume leadership; Artificial Intelligence holds the steepest expansion curve.
Transportation Mode:
Geographic concentration in the Red Sea basin favors multimodal coordination over single-mode dominance.
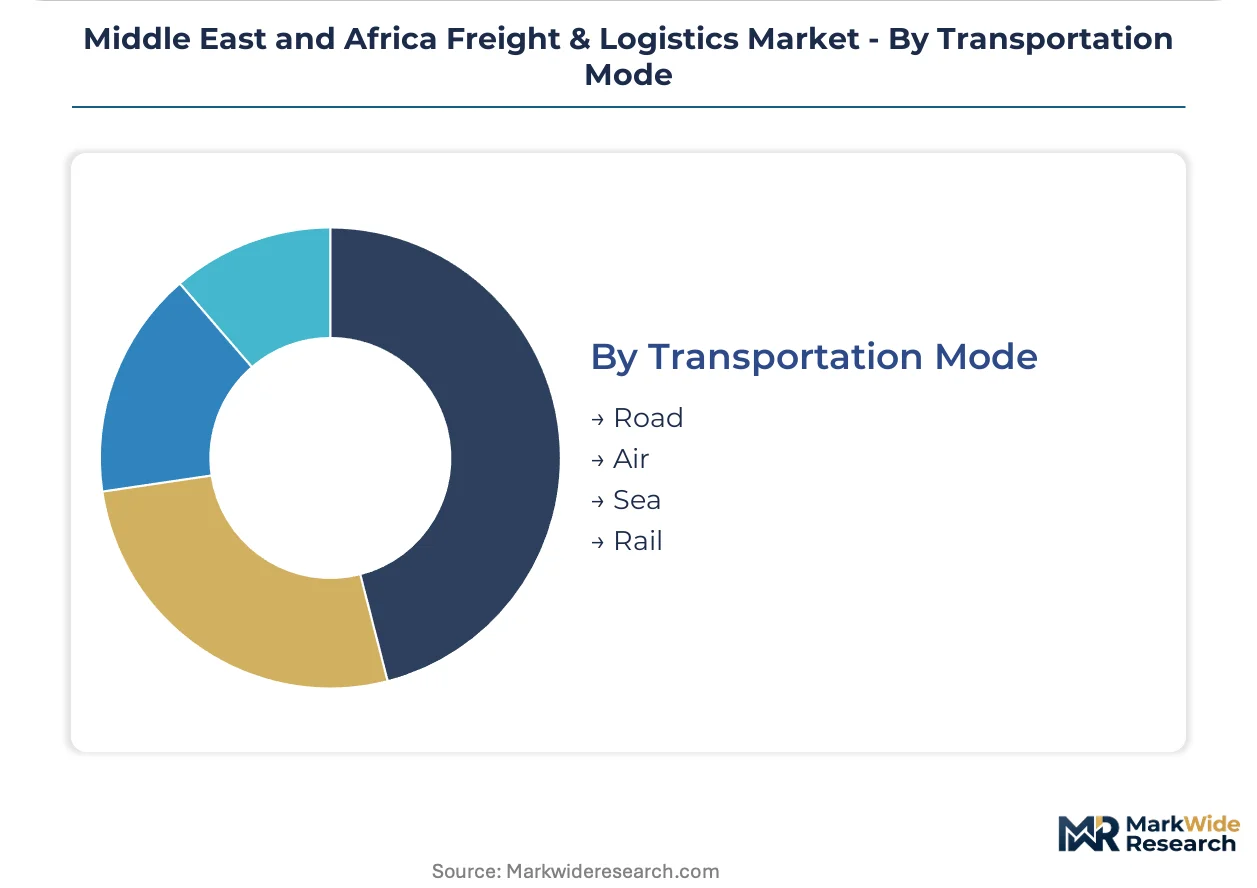
- Road:Intra-regional distribution captures volume across the Jeddah-Riyadh-Dubai corridor with fleet telematics integration now competitive baseline. Certified operator shortages are tightening labor supply for conventional haulage.
- Air:Premium perishable and emergency shipments occupy this segment with pharmaceutical cold chain expansion creating dedicated lanes into East African markets. Dubai South hub infrastructure anchors intercontinental connectivity.
- Sea:Intercontinental volume concentration requires synchronized drayage and bonded warehousing near Jeddah Islamic Port.
- Rail:Limited network coverage restricts deployment to specific mineral and bulk commodity corridors.
Road retains volume leadership; Air holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE's General Civil Aviation Authority anchors regulatory coordination for autonomous freight trials across the Gulf Cooperation Council corridor. Transport authorities in Saudi Arabia and Egypt are synchronizing customs modernization timelines. Nigeria's port automation mandates are compressing clearance dwell times for bonded operators.
United Arab Emirates
Dubai South's pharmaceutical cold chain infrastructure and Jebel Ali Port capacity upgrades drive bonded warehousing demand. The General Civil Aviation Authority permits unmanned truck trials on designated freight corridors. Micro-fulfillment centers in Dubai Industrial City are restructuring last-mile asset deployment for e-commerce fulfillment.
Saudi Arabia
Logistics zone licensing reforms and King Abdullah Economic City's just-in-line assembly plants concentrate synchronized inbound supply chain demand. The Transport General Authority streamlined permitting compresses operational setup timelines. Jeddah Islamic Port bonded facilities are upgrading to temperature-controlled specifications for Red Sea basin distribution.
Egypt
Port automation mandates and Alexandria's secondary city franchise networks generate last-mile density opportunities. The country's customs modernization directives reshape clearance timelines and bonded storage requirements. Cairo's manufacturing corridors are driving demand for integrated service contracts bundling warehousing and distribution.
Nigeria
Single-window clearance reforms and Lagos port infrastructure investments accelerate bonded storage turnover. The country's port automation mandates compress dwell times for compliant operators. Secondary cities including Port Harcourt sustain franchise partner network expansion where owned fleet economics fail.
South Africa
The National Regulator for Compulsory Specifications enforces vehicle safety standards affecting fleet replacement cycles. Cape Town and Durban corridors concentrate intermodal coordination for mineral and bulk commodity movements. Mining logistics demand and automotive knock-down kit assembly operations drive specialized handling requirements.
Middle East and Africa Freight & Logistics Market Competitive Landscape
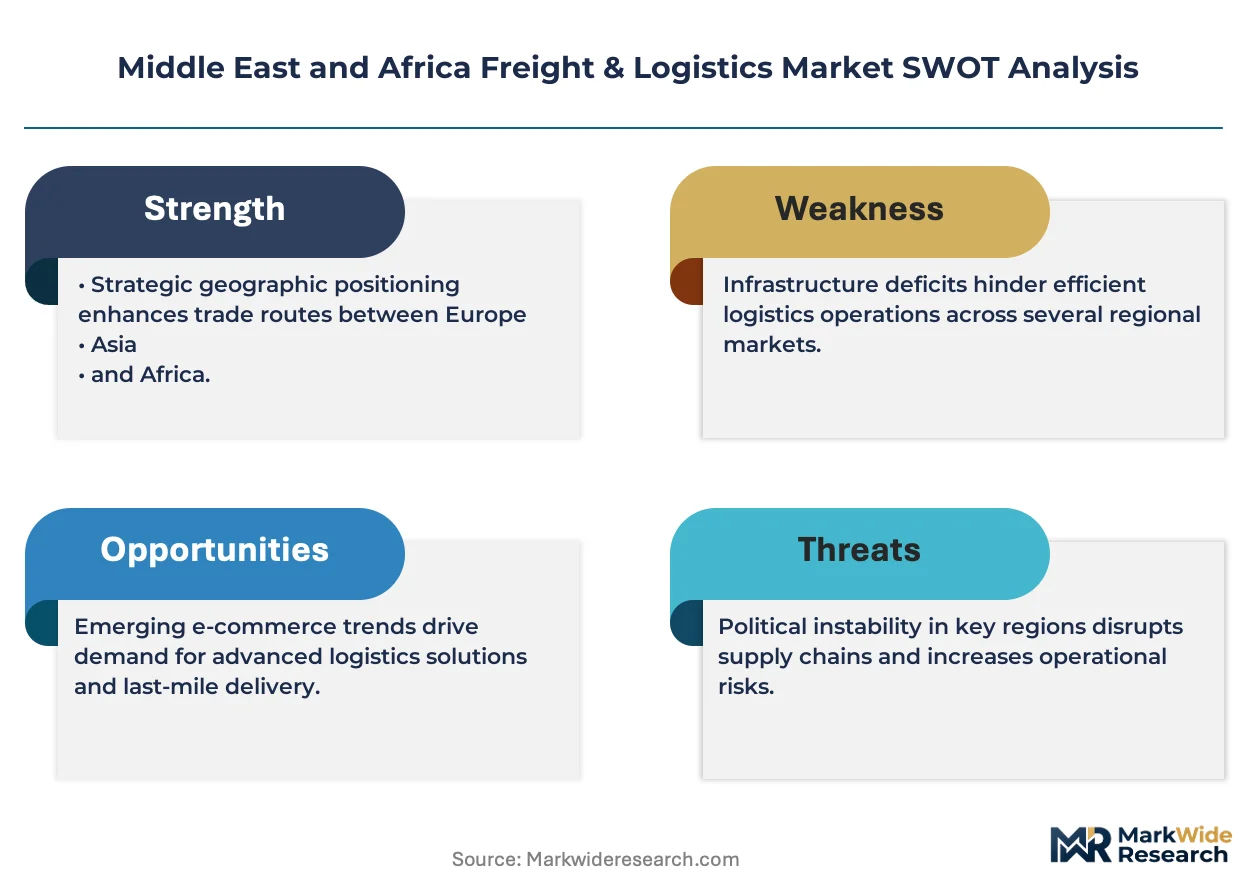
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa freight and logistics market. Asset-heavy operators with owned warehousing, line-haul, and last-mile capabilities command bundled procurement contracts from manufacturing accounts. Strategic archetypes include integrated end-to-end providers, cold chain specialists, and franchise-network last-mile operators. Competitive moves concentrate on technology partnerships for telematics integration and joint ventures to navigate foreign ownership restrictions in bonded facilities.
Within the integrated provider tier, DHL leverages Dubai South hub infrastructure to anchor pharmaceutical cold chain corridors into East Africa. Aramex sustains last-mile density through franchise partner networks in secondary Egyptian and Nigerian cities. Gulf Agency Company occupies a position serving project cargo capabilities for offshore energy installations across the Red Sea basin.
| Leading Market Players |
|---|
| DHL |
| Aramex |
| Gulf Agency Company (GAC) |
| RAK Logistics |
| Al-Futtaim Logistics |
| Agility Logistics |
| Kuehne + Nagel |
| Ceva Logistics |
| Almajdouie Group |
| Others |
Pricing and Supply Chain Analysis
Jeddah Islamic Port's container throughput scale and Dubai South's bonded warehousing density create fixed-cost leverage that compresses price floors for regional operators while elevating barriers for asset-light entrants. This concentration dynamic ties freight rates directly to port capacity utilization and customs clearance efficiency across the GCC corridor.
Pricing Analysis
Freight rate spreads between Jeddah-Riyadh and Dubai-Abu Dhabi corridors reflect diesel cost differentials and bonded facility availability rather than pure distance metrics. Contract-based long-term offtake agreements dominate pharmaceutical cold chain logistics, while spot-market pricing governs conventional containerized movements. Price differentiation separates ISO-certified temperature-controlled operators from standard haulage providers, with certification premiums widening as Euro VI compliance costs accelerate fleet turnover. Cost compression in conventional road freight is intensifying because digital freight matching platforms are disintermediating traditional brokers and shifting pricing power toward high-volume shippers with predictable demand profiles. Manufacturing accounts serving just-in-line assembly plants exhibit lowest price sensitivity due to inventory carrying cost exposure, while secondary city e-commerce fulfillment networks face acute margin pressure from same-day delivery service level requirements.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability fluctuations on Asia-Gulf trade lanes are elevating inbound logistics costs for bonded warehousing operators dependent on synchronized drayage capacity. Geographic supply concentration centers on the UAE, Saudi Arabia, and Egypt as the primary logistics infrastructure hubs, with secondary distribution nodes emerging in Nigeria and South Africa. The regional supply chain draws from European tractor manufacturers, Asian container equipment suppliers, and domestic fuel refining capacity. Single-source vulnerability runs through sensor fusion system suppliers for autonomous trucking trials, where Gulf standardization delays have frozen validation timelines. Distribution runs through hub-and-spoke configurations anchored by Dubai South and Jeddah Islamic Port, with last-mile fragmentation into franchise partner networks for secondary city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight and logistics across the Middle East and Africa sits in early-cycle expansion as autonomous vehicle testing regulations and pharmaceutical cold chain investments create first-mover advantages in corridor infrastructure. E-commerce fulfillment density and bonded warehousing automation represent underpenetrated layers with substantial runway ahead.
For Market Incumbents: Compound data infrastructure advantages by integrating proprietary telematics platforms with warehouse management systems serving manufacturing accounts in King Abdullah Economic City. Deepen vertical integration through controlled-temperature facility ownership near Jeddah Islamic Port before foreign ownership restrictions fully dissolve. Defensive positioning requires pre-emptive certification investment in IoT-enabled fleet systems as the Transport General Authority tightens operator qualification requirements.
For New Entrants and Emerging Players: Telemetry certification fast-tracks through Dubai South's regulatory sandbox offer accelerated market entry for autonomous trucking technology providers. Secondary Egyptian and Nigerian cities present the most penetrable white-space for franchise-network last-mile density, where Aramex's partner model has demonstrated scalability without owned fleet capital intensity. A go-to-market angle anchored by pharmaceutical cold chain compliance documentation can bypass established carrier relationships in East African distribution corridors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy operators with integrated warehousing, line-haul, and last-mile capabilities over point-solution specialists facing bundling pressure. Long-term viability across the analysis window hinges on proprietary data infrastructure and bonded facility ownership in the Jeddah-Riyadh-Dubai triangle. Acquisition targets should display cross-border permit coordination capabilities and sensor fusion validation progress. The signal to watch is Gulf standardization body alignment on autonomous vehicle protocols, which would unlock frozen capital commitment timelines and validate sensor redundancy investment theses.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Vehicle Certification | Dubai South regulatory sandbox validation accelerates commercial deployment timelines for sensor fusion systems. |
| Temperature-Controlled Facility Upgrade | Jeddah Islamic Port bonded warehousing investments capture pharmaceutical cold chain corridor expansion into East Africa. |
| Franchise Network Expansion | Port Harcourt and Alexandria last-mile density partnerships replicate Aramex's secondary city penetration model. |
| Telematics Platform Integration | Real-time fleet visibility synchronization with warehouse management systems compresses dwell times for manufacturing accounts. |
| Cross-Border Permit Harmonization | Transport General Authority and General Civil Aviation Authority coordination reduces documentation friction for GCC corridor movements. |
Research Methodology
A spread of perspectives from fleet operations directors, bonded warehouse managers, pharmaceutical distribution executives, customs modernization officers, and autonomous vehicle testing coordinators converged on the working assumptions underpinning this analysis. Primary field engagement combined structured interviews with secondary validation against Transport General Authority regulatory filings, Dubai South infrastructure disclosures, Egyptian port automation directives, Nigerian single-window clearance documentation, and GCC trade statistics. Bottom-up segmentation modeling triangulated against top-down corridor capacity assessments.
Segmentation dimensions modeled include service type, end-user industry, technology application, and transportation mode, with geographic clustering across the Jeddah-Riyadh-Dubai corridor receiving specific analytical weight. CAGRs were derived from capacity utilization trajectories, fleet modernization cycle timing, and bonded warehousing absorption rates throughout the forecast period. Industry-specific forecast inputs incorporated Euro VI compliance cost curves and pharmaceutical cold chain lane qualification timelines.
Underlying assumptions cover autonomous protocol standardization progress, certified operator supply elasticity, and customs modernization implementation pace, with deviation risk concentrated in regulatory coordination delays between Saudi Arabia and UAE transport authorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
United States Contract Logistics Market