
 Brazil Freight and Logistics Market | 2026-2036
Brazil Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Freight and Logistics Market Outlook
Aftermarket service revenue is tilting from pure transport margins toward integrated warehousing and customs brokerage bundles. JSL SA leverages its captive fleet and terminal network to dominate Brazil's road-heavy corridors. Rumo Logística anchors intermodal rail flows between agricultural interiors and Atlantic ports. DSV competes through specialized cold-chain and project-cargo capabilities for industrial clients.
Brazil freight and logistics encompasses the physical movement, storage, and documentation of goods across road, rail, air, and maritime modes, with cargo handling specifications varying by commodity density, perishability, and customs classification. Its primary purpose is bridging geographic production-consumption gaps while complying with federal transit and foreign-trade regulations. Transportation services absorb the dominant value share given Brazil's continental road dependency, while freight forwarding margins expand fastest as customs complexity rises for e-commerce and manufactured imports. Warehousing investment clusters around São Paulo state and Paraná distribution corridors where inventory velocity determines facility returns.
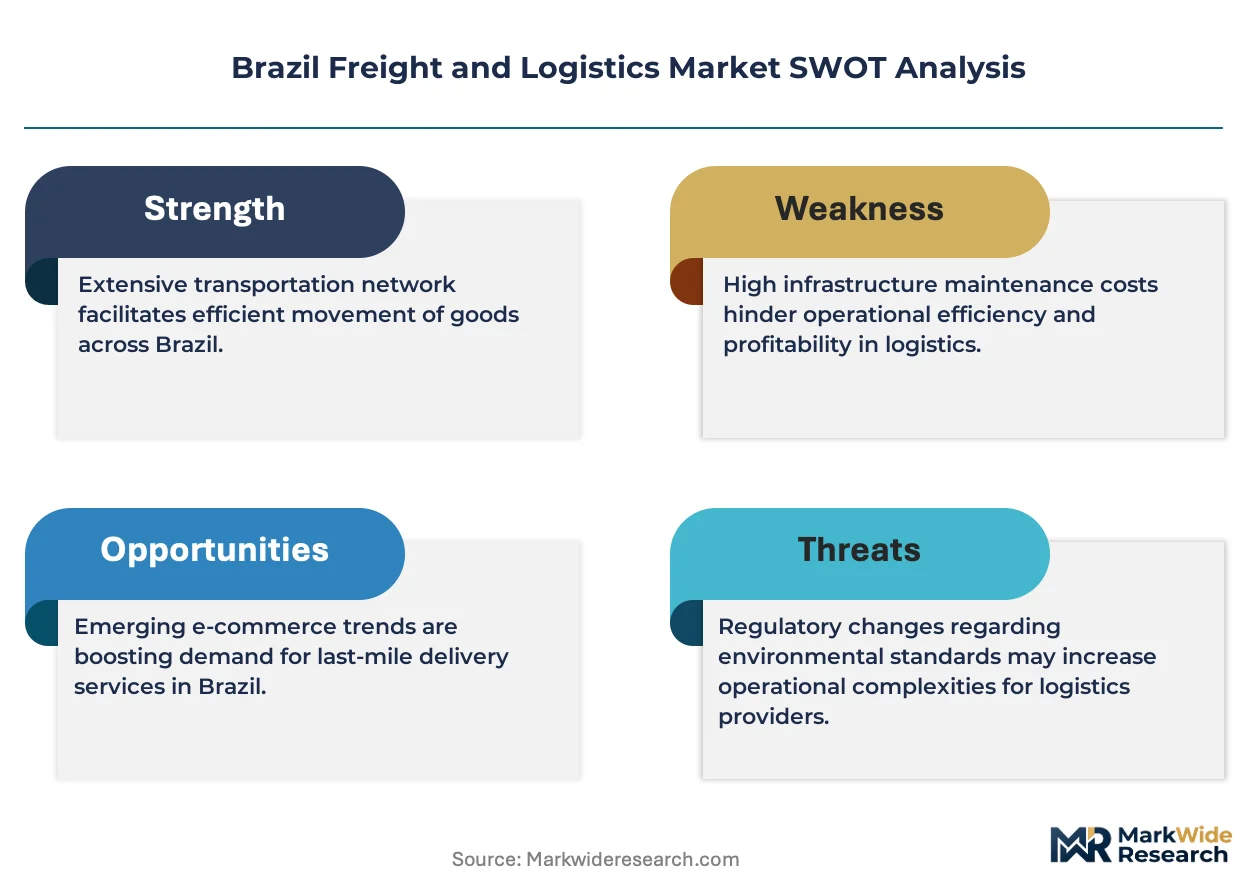
ANTT governs road freight tariffs and concession contracts, while Receita Federal administers customs clearance protocols that directly shape forwarding service demand. ANVISA and MAPA impose sanitary inspection requirements on agricultural and pharmaceutical cargo, creating compliance-driven specialization among logistics providers. Stakeholders must monitor how federal infrastructure auction schedules and green-fuel mandates for heavy vehicles reshape fleet investment decisions and modal competitive balance.
Market Dynamics
ANTT's digital permit systems and tariff recalibration are compressing carrier margins while forcing consolidation among small fleet operators across Mato Grosso and São Paulo corridors.
Growth Catalysts
- Soybean export corridors:Agribusiness volume from Mato Grosso's interior to Santos port anchors long-haul freight demand. Terminal investment at Rondonópolis and Lucas do Rio Verde locks in modal share for road-rail interchanges.
- ANTT regulatory modernization:Automated freight permits and transparent tariff benchmarking reduce administrative friction for cross-state carriers. Digital documentation cuts transit delays at state border checkpoints.
- E-commerce fulfillment velocity:São Paulo's last-mile density requirements pull warehousing investment toward Guarulhos and Campinas distribution clusters. Same-day delivery promises compress inventory positioning decisions.
Market Restraints
- Diesel price volatility:Petrobras pricing policy exposes road-dependent carriers to input cost swings that cannot be fully passed through contracted tariffs. Fleet operators absorb margin compression during price spike periods.
- Rail network concentration:Rumo Logística's control over Mato Grosso-Atlantic grain corridors limits shipper bargaining power on bulk agricultural flows. Alternative routing options remain undeveloped for interior origin points.
- Driver qualification scarcity:Federal licensing requirements and demographic shifts constrain available heavy-vehicle operators. Training pipeline gaps extend recruitment timelines for expanding fleets.
Strategic Opportunities
- Paraná distribution corridor expansion:Curitiba and Londrina warehousing clusters offer lower land costs than saturated São Paulo markets for e-commerce fulfillment nodes. Highway connectivity to Porto de Paranaguá adds maritime export optionality.
- Green-fuel fleet mandates:Federal biodiesel blending requirements and prospective hydrogen pilot programs create early-mover advantages for carriers with retrofit capabilities. ANTT concession contracts increasingly weight environmental performance.
- Cross-border Mercosur integration:Simplified customs protocols with Argentina and Paraguay open integrated logistics contracts for manufactured goods flows. São Paulo-based forwarders capture value from documentation bundling.
Industry Challenges
- Toll system fragmentation:State-level concession contracts create inconsistent pricing and payment systems across Brazil's federal highway network. Fleet operators manage multiple transponder technologies and billing cycles.
- Warehousing automation capex:E-commerce velocity requirements demand robotics and WMS investment that mid-sized 3PLs struggle to finance. Labor cost arbitrage in secondary markets delays automation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Freight and Logistics Market |
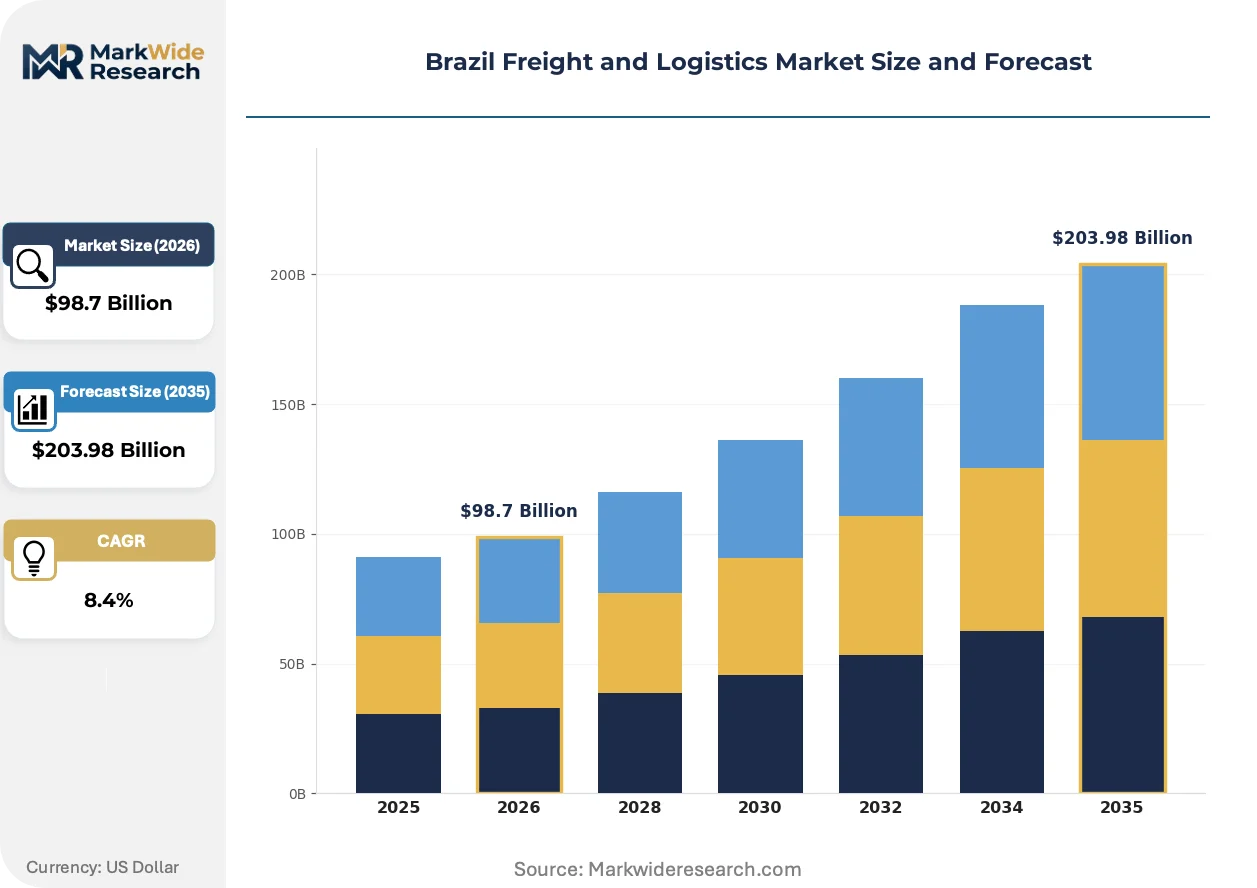
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Delivery Mode: Road, Rail, Air, Sea Customer Type: Retailers, Manufacturers, Wholesalers, E-commerce Technology: TMS, WMS, RFID, IoT |
| Companies Covered | JSL SA, DSV, A.P. Moller - Maersk, Allog Group, Nippon Express, DHL Group, Kuehne + Nagel, Rumo Logística, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Freight and Logistics Market Strategic Shifts
Digital freight matching and automated warehouse systems are compressing traditional brokerage margins while elevating data analytics capabilities among surviving logistics providers.
Telematics platforms is hybridizing fleet management with predictive maintenance algorithms and real-time cargo monitoring. Large agribusiness shippers in Mato Grosso now mandate IoT-enabled trailers for high-value soybean and corn movements. This convergence is collapsing the information gap between carriers and cargo owners, forcing traditional brokers toward specialized customs and compliance services.
ANTT's updated freight tariff reference tables now incorporate fuel cost indices and regional congestion adjustments on a quarterly basis. Carriers operating under federal concession contracts must demonstrate cost structure alignment with these benchmarks. Road transport segments serving São Paulo industrial zones face the steepest compliance documentation requirements.
Shippers are consolidating vendor relationships around integrated service providers offering warehousing, customs brokerage, and dedicated fleet capacity under single contracts. Manufacturing exporters in Paraná and Santa Catarina increasingly reject pure transport quotes in favor of inventory-managed solutions. This bundling preference is most pronounced among automotive parts suppliers serving Mercosur assembly plants.
Brazil Freight and Logistics Market Segmentation
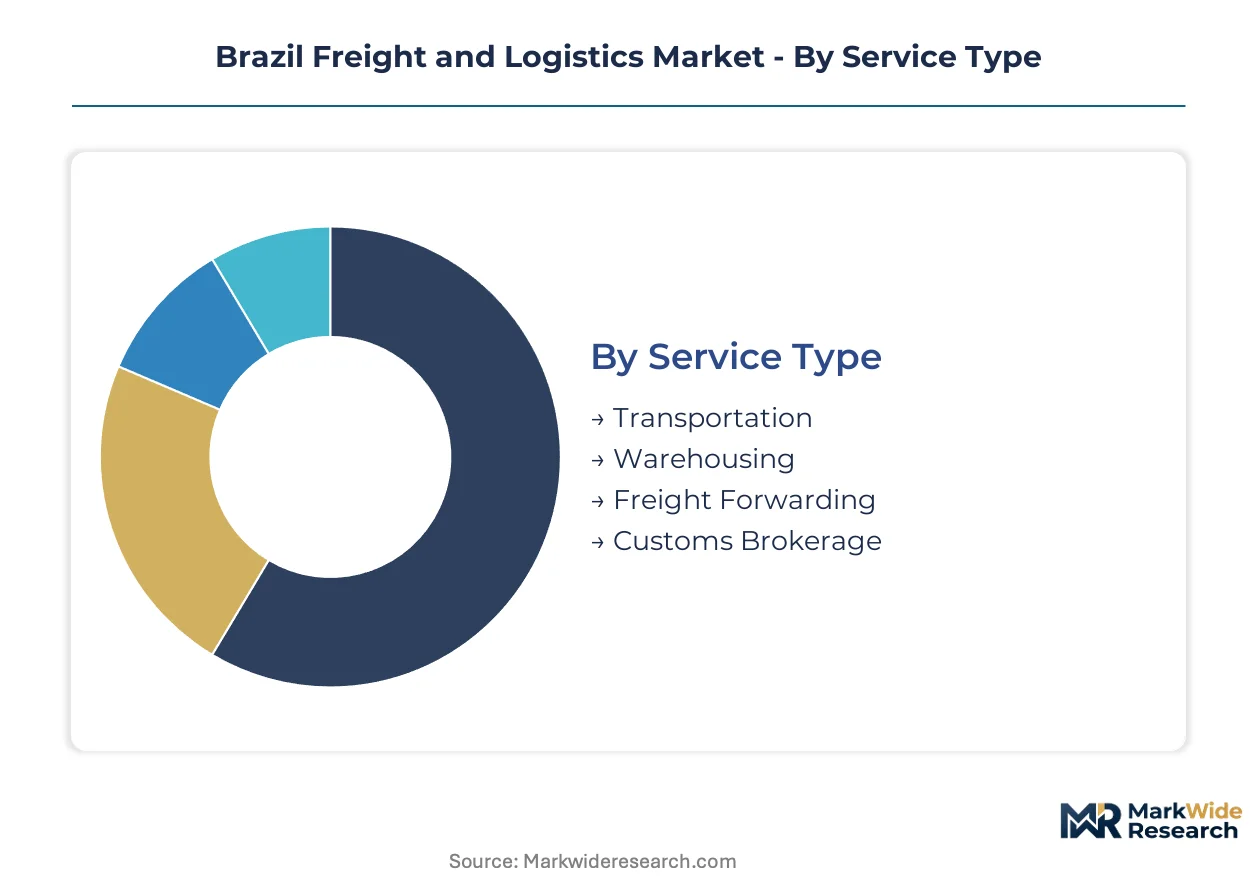
Service bundling intensity varies sharply across Brazil's logistics segments. Transportation providers face the steepest margin compression from fuel volatility, while warehousing and forwarding segments capture value from customs complexity and inventory velocity demands.
Service Type:
After-sales service obligations differ materially across service types, with transportation requiring minimal ongoing support while integrated forwarding contracts demand continuous compliance monitoring.
- Transportation:Physical cargo movement via owned or contracted fleet assets across road-dominant corridors. São Paulo industrial zones and Mato Grosso agribusiness corridors absorb the highest contract volumes. Petrobras diesel pricing policy directly compresses carrier margins during cost spike periods.
- Warehousing:Climate-controlled and ambient storage facilities with inventory management systems. Guarulhos and Campinas clusters concentrate demand from e-commerce fulfillment requirements. Same-day delivery promises force inventory positioning closer to consumption endpoints.
- Freight Forwarding:Documentation and customs clearance coordination for international cargo movements. Receita Federal protocol complexity drives specialization among São Paulo-based providers. E-commerce import volumes expand forwarding service demand fastest.
- Customs Brokerage:Regulatory compliance and tariff classification services for cross-border trade. ANVISA and MAPA sanitary inspections add specialized requirements for agricultural and pharmaceutical cargo. Mercosur integration simplifies some documentation flows while creating new compliance layers.
Transportation holds the largest share; momentum sits with Freight Forwarding.
Delivery Mode:
Modal selection hinges on cargo density, perishability, and corridor infrastructure maturity rather than pure cost optimization.
- Road:Dominant mode for Brazil's continental distances with flexible routing capabilities. ANTT's digital permit systems reduce administrative friction for interstate carriers. Driver qualification scarcity constrains fleet expansion timelines.
- Rail:Bulk agricultural movements between Mato Grosso interior and Atlantic ports. Rumo Logística's corridor concentration limits shipper bargaining power on grain flows. Terminal investment at Rondonópolis locks in modal share for intermodal interchanges.
- Air:High-value, time-sensitive cargo serving pharmaceutical and electronics supply chains. Guarulhos International Airport anchors domestic air freight distribution. Cold-chain requirements elevate handling specifications for perishable exports.
- Sea:Containerized and bulk maritime movements through Santos and Paranaguá ports. Port infrastructure congestion creates inventory buffer requirements for shippers. Deep-water terminal investments aim to capture post-Panamax vessel calls.
Road maintains volume leadership; rail expansion is climbing the fastest.
Customer Type:
Procurement sophistication varies across customer segments, with e-commerce operators demanding real-time visibility that manufacturers often bypass.
- Retailers:Store replenishment and distribution center operations with seasonal volume spikes. São Paulo metropolitan density supports frequent delivery schedules. Inventory turnover metrics determine logistics provider selection.
- Manufacturers:Raw material inbound and finished goods outbound flows with contract stability. Automotive parts suppliers in Paraná and Santa Catarina favor integrated service bundles. Mercosur assembly plant requirements shape cross-border logistics contracts.
- Wholesalers:Consolidated distribution to fragmented downstream customers. Secondary city coverage requirements extend delivery network complexity. Credit terms and collection risk influence carrier selection criteria.
- E-commerce:Direct-to-consumer fulfillment with last-mile density requirements. Curitiba and Londrina warehousing clusters offer land cost advantages over saturated São Paulo markets. Returns processing capabilities differentiate logistics providers.
Manufacturers command the largest contract values; e-commerce is gaining share fastest.
Technology:
Technology deployment separates integrated providers from commodity transport operators, with data analytics capabilities becoming competitive differentiators.
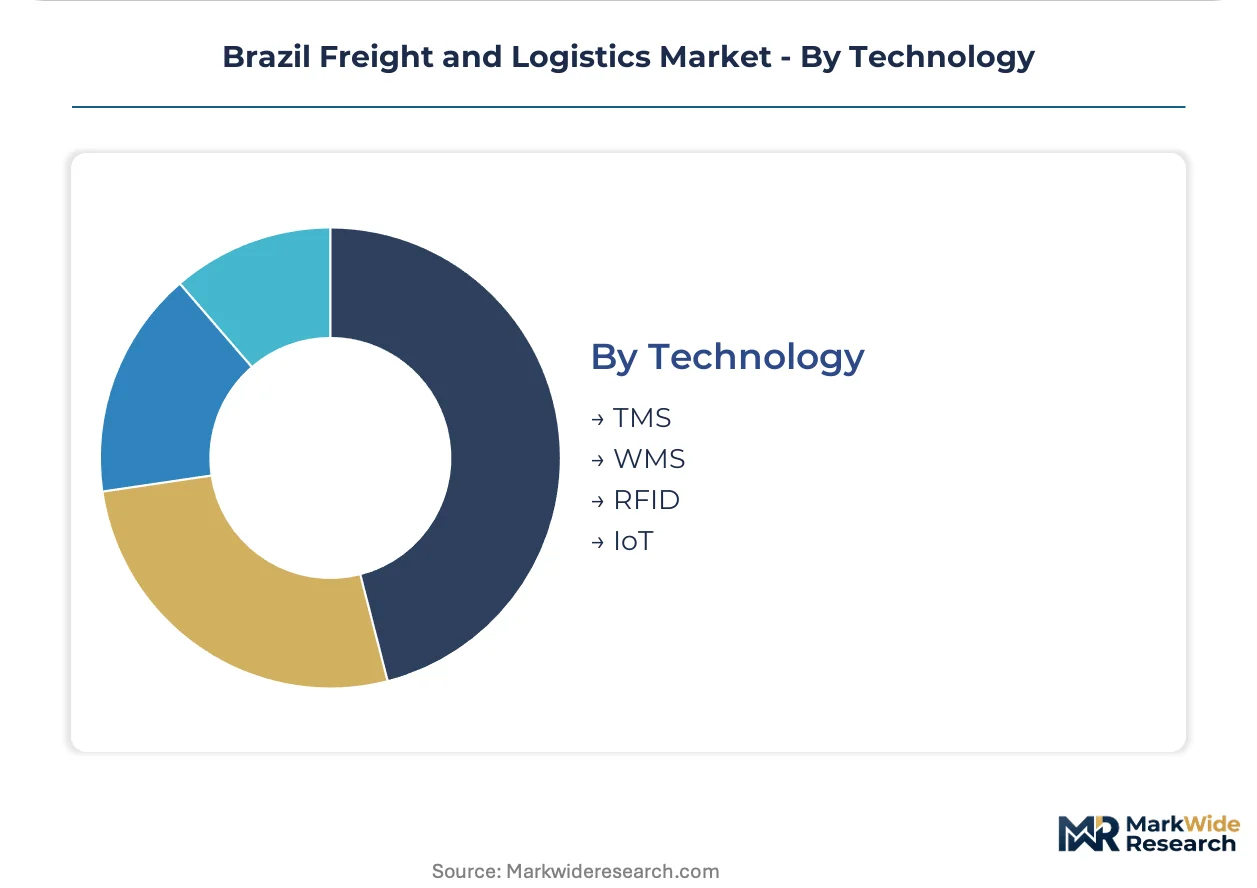
- TMS:Transportation management systems optimizing route planning and carrier selection. ANTT's quarterly tariff benchmarks feed into TMS cost modeling. Large agribusiness shippers mandate platform integration for contract eligibility.
- WMS:Warehouse management systems coordinating inventory positioning and order fulfillment. Robotics integration demands capital investment that mid-sized 3PLs struggle to finance. Labor cost arbitrage in secondary markets delays automation adoption.
- RFID:Radio-frequency identification for cargo tracking and inventory accuracy. Port terminal operators deploy RFID for container yard management. Implementation costs limit adoption among small fleet operators.
- IoT:Sensor-enabled cargo monitoring for temperature, humidity, and location verification. Mato Grosso soybean exporters now require IoT-enabled trailers for high-value movements. Telematics convergence collapses information gaps between carriers and cargo owners.
TMS captures the broadest deployment; IoT is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Brazilian logistics corridors, with agribusiness shippers in Mato Grosso negotiating aggressively on bulk grain rates while São Paulo industrial buyers prioritize reliability over marginal cost savings.
São Paulo
Southeastern manufacturing and e-commerce fulfillment dominate freight demand. ANTT's digital permit systems reduce interstate transit friction for carriers serving the Santos port corridor. Guarulhos and Campinas warehouse clusters absorb the highest logistics investment as inventory positioning tightens.
Minas Gerais
Iron ore and steel shipments anchor heavy-haul road and rail volumes. Federal mining concession regulations shape carrier contract stability for bulk mineral movements. The Belo Horizonte industrial ring concentrates steel distribution and automotive parts logistics.
Paraná
Curitiba and Londrina distribution clusters offer land cost advantages over saturated São Paulo markets. MAPA sanitary inspection requirements govern agricultural export flows through Porto de Paranaguá. E-commerce fulfillment nodes are expanding fastest in this secondary corridor.
Rio Grande do Sul
Soybean and meat export volumes drive port logistics demand at Rio Grande. ANVISA pharmaceutical regulations elevate cold-chain requirements for vaccine distribution from Porto Alegre. Manufacturing exporters favor integrated service bundles for Mercosur cross-border flows.
Mato Grosso
Interior agricultural origins face the steepest freight cost pressure due to distance from Atlantic ports. Rumo Logística's rail corridor concentration limits shipper routing alternatives for grain movements. Rondonópolis terminal investment locks in intermodal share for soybean exports.
Brazil Freight and Logistics Market Competitive Environment
Road-dominant integrators and intermodal rail specialists split the market along cargo density lines. Consolidation pressure concentrates among mid-sized fleet operators facing ANTT margin compression. Three archetypes dominate: captive-fleet road haulers, rail-anchored bulk movers, and global forwarders with customs specialization. Carriers defend position through M&A absorption of distressed fleets and concession contract renewals weighted toward environmental performance.
Within the domestic integrated tier, JSL SA and Rumo Logística exemplify contrasting modal strategies. JSL SA represents the road-heavy archetype with terminal network density across southeastern corridors. Rumo Logística occupies the intermodal position anchoring agricultural bulk flows between interior origins and Atlantic ports. Among global forwarders, DSV and DHL Group sit within the specialized customs and cold-chain service tier, competing on documentation bundling rather than pure transport rates.
| Leading Market Players |
|---|
| JSL SA |
| DSV |
| A.P. Moller - Maersk |
| Allog Group |
| Nippon Express |
| DHL Group |
| Kuehne + Nagel |
| Rumo Logística |
| FedEx |
| Others |
Value Chain & Pricing Dynamics
Petrobras diesel pricing concentration anchors carrier margin volatility across Brazil's road-dominant corridors, shifting profit pools toward integrated warehousing and customs brokerage bundles that absorb fuel cost fluctuations through long-term contracts.
Pricing Analysis
After-sales service revenue from maintenance contracts and extended warranty bundles drives lifetime value for fleet operators facing ANTT's quarterly tariff recalibration. Three-tier pricing structure across premium, standard, and economy levels segments carriers by fleet age, telematics integration, and compliance documentation depth. Price differentiation hinges on ANTT concession contract tier and IoT-enabled cargo monitoring certification. Pricing pressure stems from Petrobras diesel cost spikes that cannot be fully passed through to contracted agribusiness shippers. Small fleet operators in Mato Grosso show highest price sensitivity; São Paulo industrial buyers prioritize reliability over marginal savings.
Supply Chain Analysis
Tariff exposure between Brazil and Mercosur partners Argentina and Paraguay dominates cross-border forwarding complexity, elevating documentation bundling premiums for São Paulo-based providers. Diesel refining capacity concentrates in Brazil's southeastern industrial corridor, with biodiesel blending mandates drawing from domestic soybean processing. Fleet assets and terminal infrastructure rest on Chinese chassis imports and European telematics systems. Single-source vulnerability sits with Rumo Logística's rail corridor control over Mato Grosso-Atlantic grain flows. Distribution runs through Santos port anchoring maritime exports, with Rondonópolis intermodal terminals feeding interior agricultural origins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's freight and logistics market operates as a substitution defense against digital freight platforms disintermediating traditional brokerage margins through automated matching algorithms.
For Market Incumbents: Pre-empt digital freight platform encroachment by captive integration of warehousing assets with customs brokerage capabilities in Guarulhos and Campinas clusters. Acquire distressed mid-sized fleets facing ANTT margin compression to consolidate terminal network density. Vertical integration into biodiesel supply chains hedges Petrobras pricing volatility for concession contract renewals. For New Entrants and Emerging Players: Establish a beachhead in Curitiba and Londrina e-commerce fulfillment nodes where land cost arbitrage supports same-day delivery infrastructure. Target pharmaceutical cold-chain specialization under ANVISA regulations as the most penetrable premium segment. Deploy IoT-enabled trailer assets as the go-to-market differentiator for Mato Grosso agribusiness contracts. For Investors and Strategic Acquirers: Capital is best deployed toward integrated 3PLs with ANTT concession contract renewals weighted toward environmental performance metrics. Long-term viability over the next decade hinges on green-fuel retrofit capabilities and intermodal terminal control. Monitor ANTT infrastructure auction schedules as the inflection signal for fleet investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Terminal Investment | Rondonópolis and Lucas do Rio Verde facilities lock in grain corridor modal share against pure road competition. |
| Green-Fuel Fleet Retrofit | Biodiesel blending compliance and hydrogen pilot participation secure ANTT concession contract renewal advantages. |
| Customs Brokerage Integration | Receita Federal documentation bundling captures value from e-commerce import volume expansion in São Paulo. |
| Telematics Platform Deployment | IoT-enabled cargo monitoring meets Mato Grosso agribusiness shipper mandates for high-value soybean movements. |
| Warehousing Automation | Robotics and WMS investment in Guarulhos clusters compresses inventory positioning for same-day delivery promises. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, ANTT regulatory affairs leads, agribusiness logistics procurement managers, and e-commerce fulfillment planners. Secondary validation drew from ANTT freight tariff reference tables, Receita Federal customs clearance protocols, Petrobras pricing policy disclosures, and port authority throughput statistics. Bottom-up carrier revenue modeling and top-down corridor volume estimates were triangulated to anchor segmentation splits.
Calibration against historical ANTT permit issuance data and Santos port container movements informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type bundling intensity, modal selection by cargo density, customer procurement sophistication, and technology deployment tier. CAGRs were derived from corridor-specific volume growth trajectories and tariff adjustment elasticities. Forecast inputs incorporated federal infrastructure auction schedules and green-fuel mandate implementation pacing.
Stress conditions across Petrobras diesel pricing bands, ANTT regulatory enforcement intensity, and Mercosur customs integration progress were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about concession contract renewal rates and intermodal terminal investment completion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market