
 Asia-Pacific Shipping Agency Services Market | 2026-2036
Asia-Pacific Shipping Agency Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Shipping Agency Services Market Outlook
Vietnam's container terminal expansion is tilting regional agency demand southward from legacy northeast Asian hubs. Sinotrans leverages its state-backed logistics network to dominate inland-to-port connectivity across China's manufacturing belts. Bansar sustains competitive positioning through specialized perishables handling in Southeast Asian trade lanes. Falcon Freight anchors its portfolio on digital customs platforms that reduce dwell times at India's major gateways.
Shipping agency services coordinate vessel port calls, cargo documentation, and regulatory compliance between carriers and terminal operators, typically managing berth scheduling, pilotage arrangements, and customs filings through integrated software platforms. The primary commercial purpose centers on minimizing vessel turnaround time and ensuring uninterrupted cargo flow through complex multi-jurisdictional supply chains. Port agency commands the deepest margin pools where vessel traffic density justifies dedicated on-site representation, while freight forwarding segments exhibit the fastest structural growth as shippers consolidate vendor relationships. Cargo handling services face margin compression from terminal automation, though customs clearance retains pricing power where regulatory complexity demands specialized expertise.
China's SAMR enforces port service pricing transparency under GB standards, while India's DGFT mandates electronic filing protocols that reshape agency technology investments. The EU AI Act's algorithmic accountability requirements extend to automated routing systems on Asia-Europe corridors, forcing compliance upgrades. Japan's METI pushes maritime digitalization through standardized data exchange frameworks. Stakeholders must monitor how Indonesia's pending port authority restructuring affects licensing access for foreign agency partnerships.
Market Dynamics
Containerized trade corridors from Vietnam's manufacturing belts are rerouting agency demand southward, compressing traditional northeast Asian hub dominance while Indonesia's transshipment expansion captures diverted volumes from congested legacy gateways.
Growth Catalysts
- GB Standards for Port Digitalization:China's SAMR mandates transparent service pricing and electronic data exchange, forcing agency technology upgrades that reduce documentation friction and accelerate vessel turnaround times.
- Containerized Manufacturing Export Surge:Vietnam's electronics and textile production corridors are generating dedicated agency demand for integrated inland-to-port coordination services.
- EU AI Act Extraterritorial Pressure:Algorithmic accountability requirements on Asia-Europe trade lanes compel shipping agencies to retrofit automated routing systems with compliance documentation layers.
Market Restraints
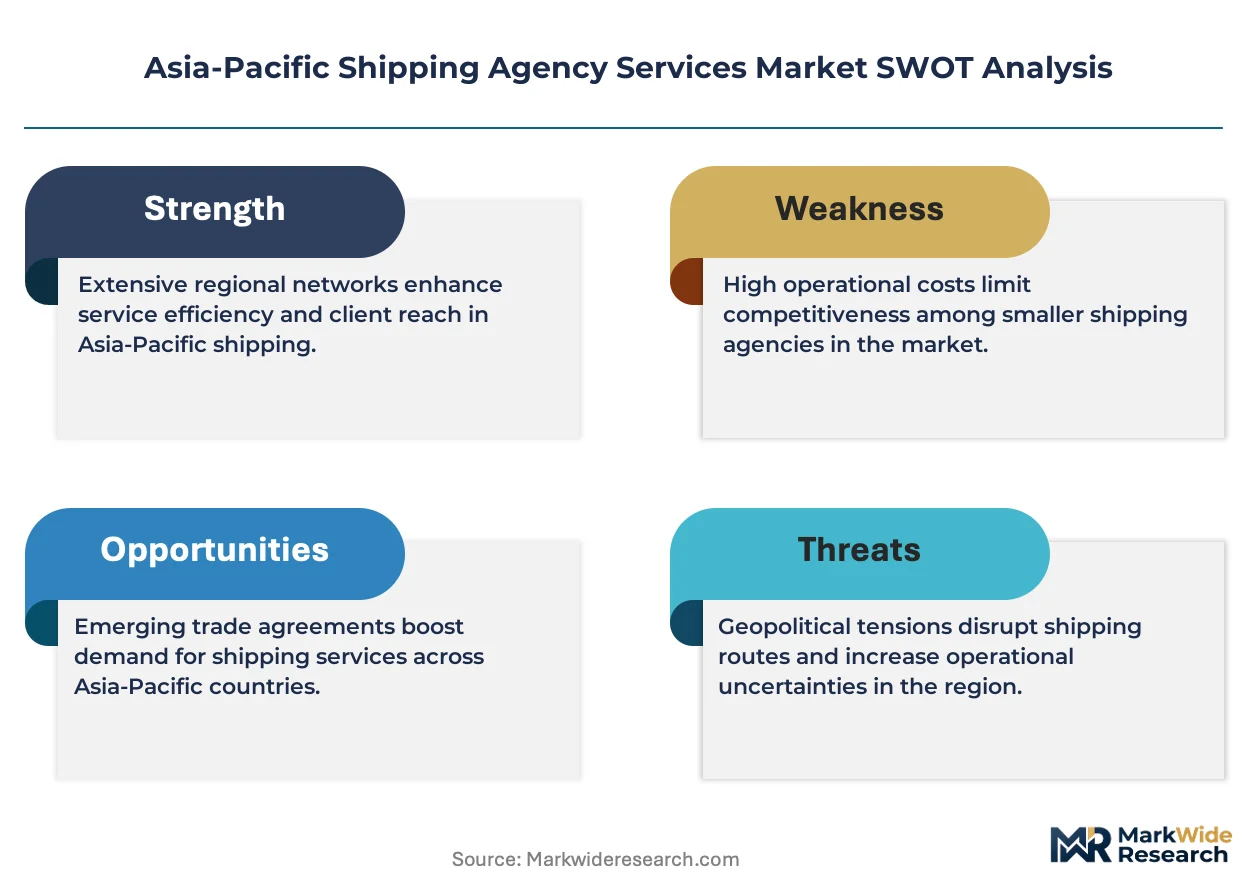
- Terminal Automation Compression:Automated cargo handling systems at Singapore and Shanghai ports are squeezing margins for traditional stevedoring-linked agency services.
- Regulatory Fragmentation Costs:Divergent electronic filing protocols between India's DGFT and China's SAMR force redundant platform investments for cross-border operators.
- Legacy System Integration Debt:Proprietary port community systems in Japan and South Korea resist API standardization, inflating IT expenditure for multi-jurisdiction agency networks.
Strategic Opportunities
- Indonesia Transshipment Hub Expansion:Pending port authority restructuring at Batam and Belawan creates first-mover licensing access for foreign agency partnerships.
- Perishables Corridor Specialization:Temperature-controlled pharmaceutical and agricultural exports from Thailand and the Philippines demand dedicated cold-chain agency expertise.
- METI Standardized Data Exchange:Japan's maritime digitalization framework offers compliant agencies preferential access to automated customs pre-clearance channels.
Industry Challenges
- Maritime Cybersecurity Certification:IMO 2021 cybersecurity guidelines require expensive crew training and system hardening that smaller agency networks struggle to fund.
- Interoperable Platform Integration:India's PCS 1x and China's single window systems use incompatible data standards, fragmenting workflow automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Shipping Agency Services Market |
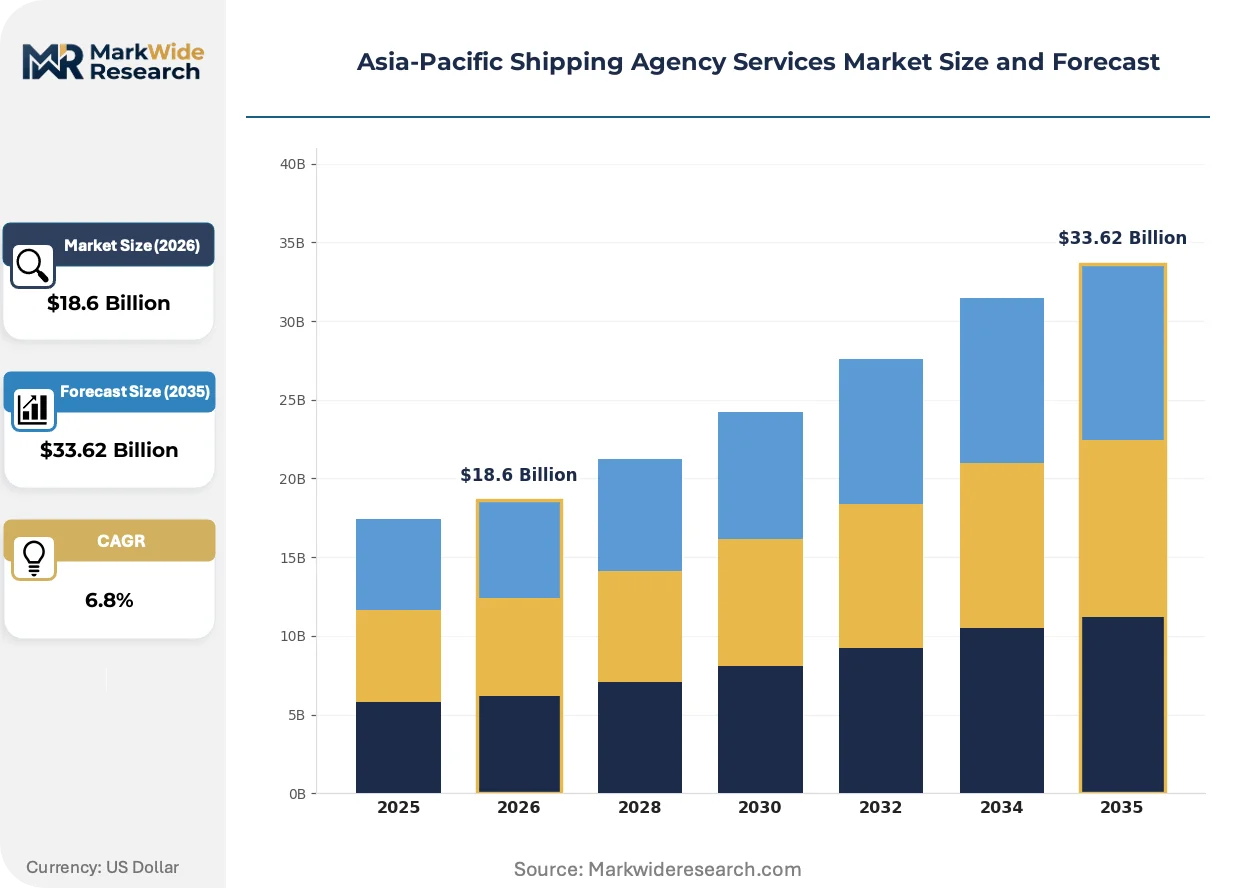
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port Agency, Cargo Handling, Customs Clearance, Freight Forwarding Client Type: Shipping Lines, Importers, Exporters, Freight Forwarders Operation Size: Small Scale, Medium Scale, Large Scale, International End User: Manufacturers, Retailers, Logistics Companies, Fisheries |
| Companies Covered | Falcon Freight, Bansar, Sinotrans, International Clearing & Shipping Agency (India) Pvt. Ltd., Legend Shipping Agency, Batam Shipping Agency, Albatross Shipping Agencies, Intermodal Shipping Inc., HS Lanka, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Shipping Agency Services Market Strategic Shifts
Digital twin architectures and blockchain-anchored documentation are compressing traditional agency workflows, while regulatory pressure from Brussels and Beijing forces algorithmic transparency into automated routing decisions.
Cloud-based port community systems are virtualizing berth scheduling and pilotage coordination through centralized platforms. Mid-sized carriers in Southeast Asia are adopting these systems fastest, leapfrogging legacy EDI investments. The technology is virtualizing on-site representation requirements, allowing remote agencies to capture port call management contracts previously held by physically present competitors.
China's GB standards for port service pricing transparency are mandating real-time rate disclosure and eliminating opaque surcharge structures. Industrial consequence includes margin compression for agencies reliant on documentation fee arbitrage. Port agency segments in Shanghai and Ningbo are responding by unbundling services into discrete, priced components to demonstrate compliance.
Shipper consolidation of vendor relationships is compressing the agency selection cycle from annual to quarterly reviews. Freight forwarding segments face the strongest disruption as beneficial cargo owners demand integrated door-to-door accountability. This pattern is most visible in Vietnam-to-Europe corridors where manufacturers now specify single-contract liability across inland, ocean, and customs segments.
Asia-Pacific Shipping Agency Services Market Segmentation
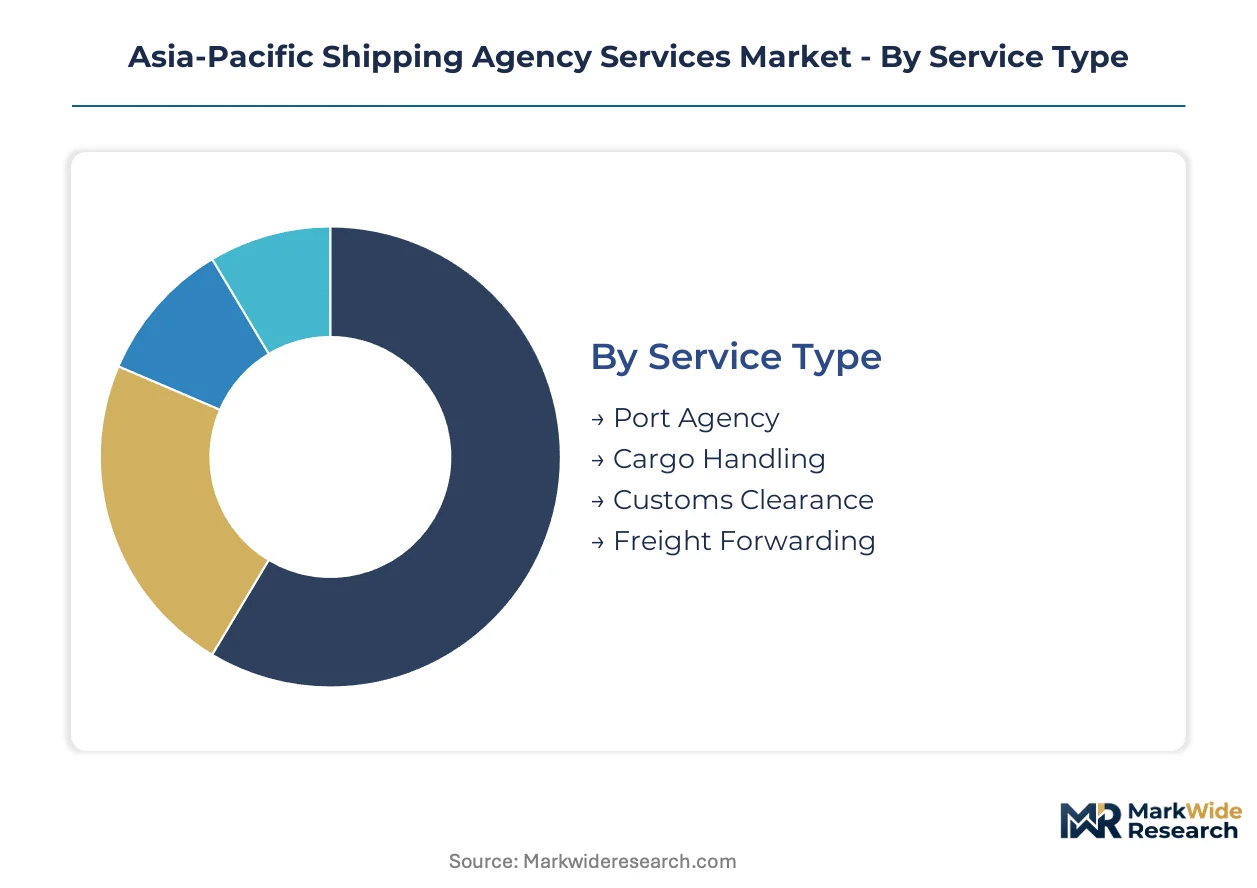
Shipping agency services fragment across operational dimensions that determine margin structure and technology investment requirements. Service type delineates core competency requirements, while client type shapes contractual risk profiles and working capital intensity.
Service Type:
Mature segments anchor revenue stability while emerging specializations capture technology-driven margin expansion.
- Port Agency:Vessel port call coordination encompassing berth scheduling, pilotage arrangements, and husbandry services. Demand concentrates at Shanghai and Singapore where vessel traffic density justifies dedicated on-site representation, though terminal automation compresses traditional stevedoring-linked margins.
- Freight Forwarding:Integrated door-to-door logistics coordination spanning inland transport, ocean carriage, and customs brokerage. Vietnamese electronics manufacturers are consolidating vendor relationships and demanding single-contract liability across multimodal segments, accelerating agency selection cycles from annual to quarterly reviews.
- Cargo Handling:Physical stevedoring and terminal coordination services. Automated systems at Singapore and Shanghai ports squeeze margins for labor-intensive operations.
- Customs Clearance:Regulatory documentation and duty optimization services. India's DGFT electronic filing mandates and China's SAMR transparency standards force redundant platform investments.
Port Agency retains volume leadership; Freight Forwarding holds the steepest expansion curve.
Client Type:
Contract scale and liability concentration vary sharply across buyer categories, with direct carrier relationships commanding premium positioning.
- Shipping Lines:Direct vessel operating carriers requiring comprehensive port representation across multiple jurisdictions. China's state-backed logistics networks dominate inland-to-port connectivity for manufacturing belt corridors.
- Freight Forwarders:Non-vessel operating intermediaries outsourcing specialized port agency functions. Demand clusters in Indonesia's transshipment hubs as volumes reroute from congested northeast Asian gateways.
- Importers:Beneficial cargo owners seeking customs efficiency and dwell time reduction. India's major gateways show strongest technology adoption for digital customs platforms.
- Exporters:Origin-side shippers requiring documentation and compliance support. Thailand and Philippines cold-chain pharmaceutical exports demand temperature-controlled agency expertise.
Shipping Lines generate the deepest revenue pools; Freight Forwarders are gaining share fastest through vendor consolidation mandates.
Operation Size:
Scale determines technology amortization capacity and multi-jurisdiction licensing reach.
- Large Scale:Multi-port networks with proprietary technology platforms and dedicated regulatory compliance teams. METI standardized data exchange frameworks in Japan offer compliant operators preferential automated customs pre-clearance access.
- International:Cross-border operators managing Asia-Europe corridor compliance. EU AI Act algorithmic accountability requirements compel retrofitting of automated routing systems with documentation layers.
- Medium Scale:Regional specialists with concentrated geographic presence. Vietnam's manufacturing corridor expansion creates dedicated demand for integrated inland coordination.
- Small Scale:Single-port or limited-route operators. IMO 2021 cybersecurity guidelines strain funding capacity for crew training and system hardening.
Large Scale operations dominate cross-border contract capture; International scope climbs the fastest as shippers consolidate vendor relationships.
End User:
Industry-specific cargo characteristics dictate service customization requirements and margin differentiation.
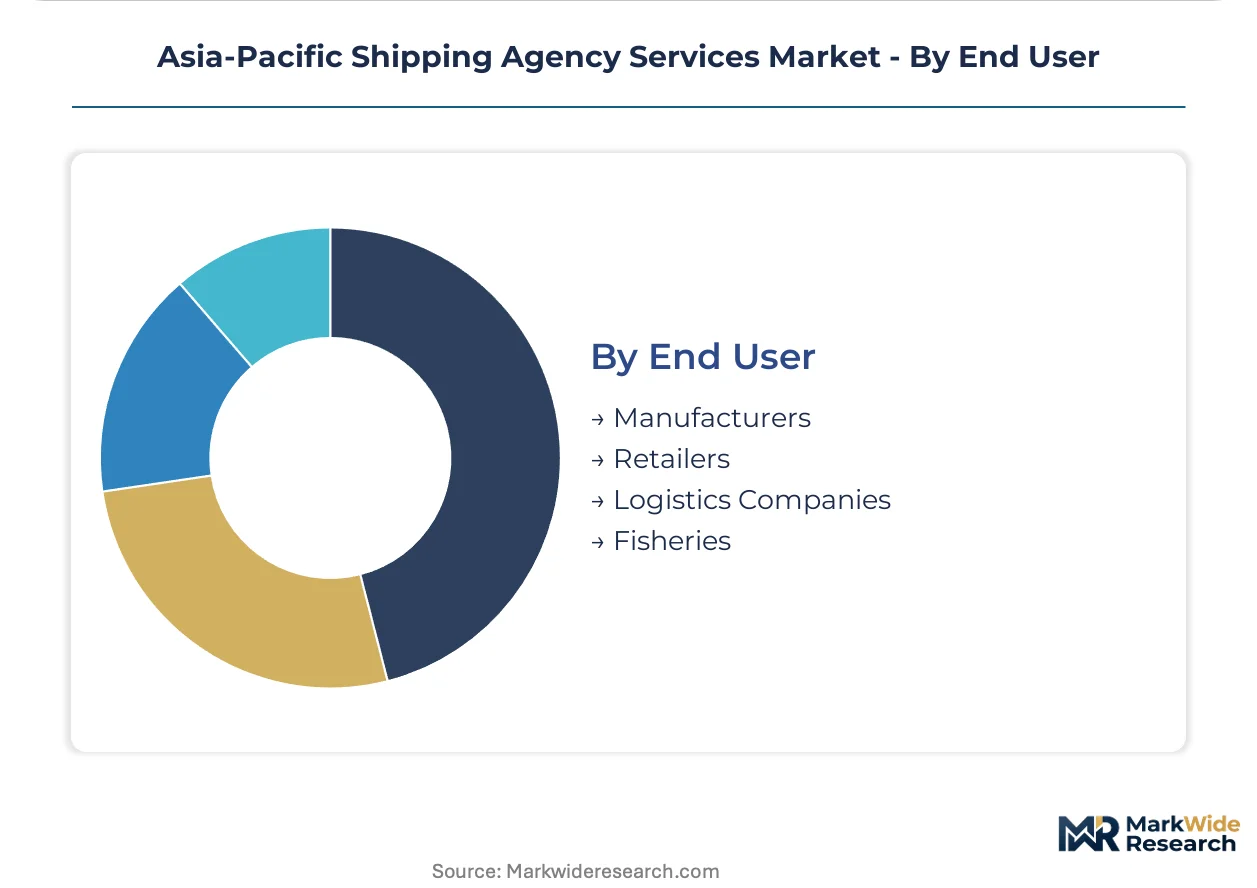
- Manufacturers:Electronics and automotive producers with just-in-time supply chain requirements. Vietnam's textile and electronics production corridors generate dedicated agency demand for time-definite inland-to-port coordination.
- Logistics Companies:Third-party operators seeking outsourced port agency functions. Indonesia's pending port authority restructuring at Batam and Belawan creates first-mover licensing opportunities.
- Retailers:Seasonal volume shippers with container consolidation needs. E-commerce fulfillment networks reshape traditional agency scheduling patterns.
- Fisheries:Perishable commodity exporters requiring cold-chain documentation and rapid customs clearance. Temperature-controlled pharmaceutical corridors from Thailand demand specialized expertise.
Manufacturers anchor volume concentration; Logistics Companies show the steepest trajectory as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agency service demand concentrates in manufacturing belt corridors and transshipment hubs across five national markets. Each jurisdiction presents distinct regulatory frameworks and infrastructure development trajectories that reshape competitive positioning for port representation services.
China
SAMR's GB standards for port service pricing transparency mandate real-time rate disclosure across Shanghai and Ningbo terminals. State-backed logistics networks dominate inland-to-port connectivity for manufacturing belt corridors. Yangtze River Delta container throughput justifies dedicated on-site agency representation despite terminal automation compressing traditional margins.
Vietnam
Electronics and textile production corridors generate dedicated demand for integrated inland-to-port coordination services. Container terminal expansion at Cai Mep and Lach Huyen accelerates vessel call frequency requiring specialized husbandry support. Manufacturing belt logistics reshape agency selection cycles as shippers consolidate vendor relationships across multimodal segments.
Indonesia
Transshipment expansion at Batam and Belawan captures diverted volumes from congested northeast Asian gateways. Pending port authority restructuring creates first-mover licensing access for foreign agency partnerships. Archipelago geography demands specialized inter-island coordination capabilities distinct from continental hub operations.
India
DGFT electronic filing protocols reshape technology investments for customs clearance segments. Digital customs platforms at Mumbai and Chennai reduce dwell times through automated pre-clearance channels. Pharmaceutical and agricultural export corridors demand temperature-controlled documentation expertise from agency operators.
Japan
METI standardized data exchange frameworks offer compliant agencies preferential automated customs pre-clearance access. Maritime digitalization mandates reshape interoperability requirements for multi-jurisdiction operators. Kanto and Kansai industrial clusters maintain specialized agency demand for precision-timed automotive component logistics.
Asia-Pacific Shipping Agency Services Market Competitive Environment
State-affiliated networks and specialized independents split the market across divergent capability requirements. Consolidation pressure concentrates in freight forwarding segments where shipper vendor consolidation accelerates contract turnover. Three archetypes dominate: integrated state-backed logistics platforms, perishables-specialized regional operators, and digital-first customs clearance specialists. Competitive moves center on technology licensing for compliance automation and strategic port authority partnerships for licensing access.
Among China-based operators, Sinotrans anchors the state-backed archetype through its nationwide inland connectivity infrastructure. Specialized Southeast Asian players occupy distinct positioning: Bansar exemplifies perishables corridor expertise, while Falcon Freight represents digital customs platform specialization. These three operators illustrate how geographic origin and service focus determine competitive differentiation in fragmented agency markets.
| Leading Market Players |
|---|
| Falcon Freight |
| Bansar |
| Sinotrans |
| International Clearing & Shipping Agency (India) Pvt. Ltd. |
| Legend Shipping Agency |
| Batam Shipping Agency |
| Albatross Shipping Agencies |
| Intermodal Shipping Inc. |
| HS Lanka |
| Others |
Value Chain & Pricing Dynamics
China's state-backed logistics infrastructure concentration along the Yangtze River Delta manufacturing belt concentrates margin capture with operators possessing dedicated inland-to-port coordination capabilities. SAMR's GB standards for service pricing transparency eliminate documentation fee arbitrage that previously subsidized smaller agency networks.
Pricing Analysis
China's SAMR mandates for port service pricing transparency dictate the pricing tier structure across Shanghai and Ningbo terminals. Three-tier pricing structure across premium, standard, and economy levels segments buyers by vessel call frequency and contract duration. Price differentiation rests on certification grade under METI data exchange frameworks and volume scale commitments. Cost compression in standard-tier port agency services is intensifying because terminal automation eliminates labor-intensive stevedoring markups. E-commerce retailers exhibit highest price sensitivity due to seasonal volume volatility, while automotive manufacturers accept premium positioning for just-in-time reliability guarantees.
Supply Chain Analysis
Tariff exposure between Vietnam and the European Union dominates supply chain risk calculations for electronics and textile exporters rerouting through Indonesia's transshipment hubs. Geographic supply concentration centers on China, Vietnam, and Indonesia for manufacturing belt corridors and gateway port infrastructure. Raw material dependencies include container equipment availability, specialized cold-chain reefer units, and customs clearance software licenses. Single-source vulnerability characterizes proprietary port community systems in Japan and South Korea that resist API standardization. Distribution runs through hub-and-spoke networks anchored at Singapore, Shanghai, and emerging Batam-Belawan transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beneficial cargo owner consolidation of vendor relationships from annual to quarterly review cycles has shifted bargaining power decisively toward buyers demanding integrated door-to-door accountability.
For Market Incumbents: Build regulatory compliance moats through METI-standardized data exchange certification and EU AI Act algorithmic accountability documentation. Integrate backward into proprietary customs clearance platforms at India's DGFT-mandated electronic filing gateways. Defend against digital-first entrants by capturing exclusive licensing access at Indonesia's pending port authority restructuring. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's electronics manufacturing corridor expansion where integrated inland-to-port coordination demand outstrips established agency capacity. Target perishables specialization in Thailand-Philippines pharmaceutical cold-chain corridors as the most penetrable segment. Pursue white-label technology licensing to mid-sized carriers adopting cloud-based port community systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed freight forwarding networks consolidating across Southeast Asian manufacturing belts. Five-to-ten year viability hinges on technology amortization capacity for multi-jurisdiction compliance platforms. Monitor Indonesia's port authority restructuring timeline as the critical inflection signal for licensing access valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for Compliance Automation | EU AI Act documentation layers retrofit automated routing systems across Asia-Europe corridors. |
| Strategic Port Authority Partnership | Exclusive licensing at Batam and Belawan captures diverted transshipment volumes from congested northeast Asian gateways. |
| Perishables Corridor Specialization | Temperature-controlled pharmaceutical expertise from Thailand anchors margin differentiation in cold-chain agency services. |
| Digital Customs Platform Integration | DGFT electronic filing compliance at Mumbai and Chennai reduces dwell times through automated pre-clearance channels. |
| Multi-Jurisdiction Certification Investment | METI standardized data exchange frameworks unlock preferential access to Japan's automated customs channels. |
Study Parameters
Operator-level perspectives from port agency managers, freight forwarding executives, customs clearance specialists, and terminal operations directors anchored the qualitative base. Primary interviews combined with secondary validation from Lloyd's List port throughput databases, UNCTAD maritime transport statistics, and national port authority regulatory filings. Bottom-up vessel call frequency modeling and top-down regional trade flow analysis enabled triangulation across the analysis window.
Scenario-bracketing around containerized trade growth assumptions and regulatory implementation timelines shaped the analytical framework. Segmentation dimensions modeled encompass service type, client category, operation scale, and end-user industry vertical. CAGRs were derived through regression analysis against historical port throughput correlations and forward trade corridor projections. Vietnam manufacturing belt expansion rates and Indonesia transshipment diversion coefficients served as industry-specific forecast inputs.
Stress conditions across terminal automation adoption curves, regulatory compliance cost inflation, and cybersecurity certification requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR enforcement intensity and METI framework adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Rail Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
First and Last Mile Delivery Market