
 France Parcel Market | 2026-2036
France Parcel Market Size, Share, and Industry Trends Forecast 2026-2036
France Parcel Market Insights
Recycled corrugated fiberboard is replacing virgin cardboard in parcel packaging and is realigning cost structures across the France parcel sector. Chronopost dominates express delivery networks through its dense last-mile infrastructure. DPD leverages automated sorting hubs to sustain operational speed in high-volume corridors. La Poste Group anchors universal service obligations while competing in premium segments through Colissimo.
France parcel services encompass the collection, sorting, transport, and last-mile distribution of packaged goods, typically involving items weighing under 30 kilograms with tracking capabilities through barcode or RFID systems, serving commercial and consumer exchange. Express delivery leads service type revenue due to premium pricing on time-definite shipments, while same-day delivery represents the fastest-expanding segment as quick-commerce platforms proliferate in dense urban zones. Automated lockers within the delivery channel dimension are capturing margin pools by reducing failed delivery costs and consolidating drop-off density in residential districts.
France's parcel operators navigate oversight from DGCCRF on consumer protection, ADEME on environmental compliance for packaging and fleet emissions, and EU Green Deal mandates on carbon reduction trajectories. These frameworks shape demand by penalizing single-use plastics and rewarding electric vehicle adoption in urban delivery zones. Stakeholders must monitor regulatory tightening on delivery zone access restrictions and packaging recyclability thresholds as compliance costs restructure competitive economics.
Market Dynamics
EU Green Deal mandates are forcing logistics operators toward electric fleet conversion and recycled packaging compliance, restructuring cost bases and competitive positioning across French parcel networks.
Growth Catalysts
- E-commerce proliferation:Quick-commerce platforms are multiplying same-day delivery demand in dense urban zones like Paris, Lyon, and Marseille. This channel expansion pulls volume through automated sorting infrastructure.
- EU Green Deal carbon trajectories:Regulatory penalties on single-use plastics and rewards for electric vehicle adoption in urban delivery zones are accelerating fleet modernization investments.
- Automated locker density:Residential district consolidation through smart locker networks is reducing failed delivery costs and capturing margin pools in last-mile economics.
Market Restraints
- Electric vehicle capex burden:Battery-powered van procurement and charging infrastructure deployment strain operator balance sheets before fuel savings materialize.
- Recycled fiberboard supply concentration:Virgin cardboard substitution depends on limited European corrugated recycling capacity, creating input cost volatility.
- Paris metropolitan logistics corridor saturation:Delivery zone access restrictions and warehouse land scarcity concentrate competition in a narrow geographic band.
Strategic Opportunities
- Underpenetrated secondary cities:Automated locker deployment in Toulouse, Nantes, and Strasbourg offers first-mover density advantages before competitor saturation.
- RFID-barcode convergence:Hybrid tracking systems combining radio-frequency identification with legacy barcode infrastructure enable real-time parcel visibility without full network replacement.
- ADEME packaging incentives:Environmental compliance subsidies for recyclable threshold achievement create cost offsets for early recyclability adopters.
Industry Challenges
- Electric vehicle technician scarcity:Fleet maintenance skill gaps in high-voltage systems and battery diagnostics constrain rollout velocity.
- Legacy sorting system integration:Automated hub upgrades must interface with existing Chronopost and DPD infrastructure without service interruption.
- DGCCRF consumer protection compliance:Delivery time guarantee enforcement and damage liability frameworks require operational redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Parcel Market |
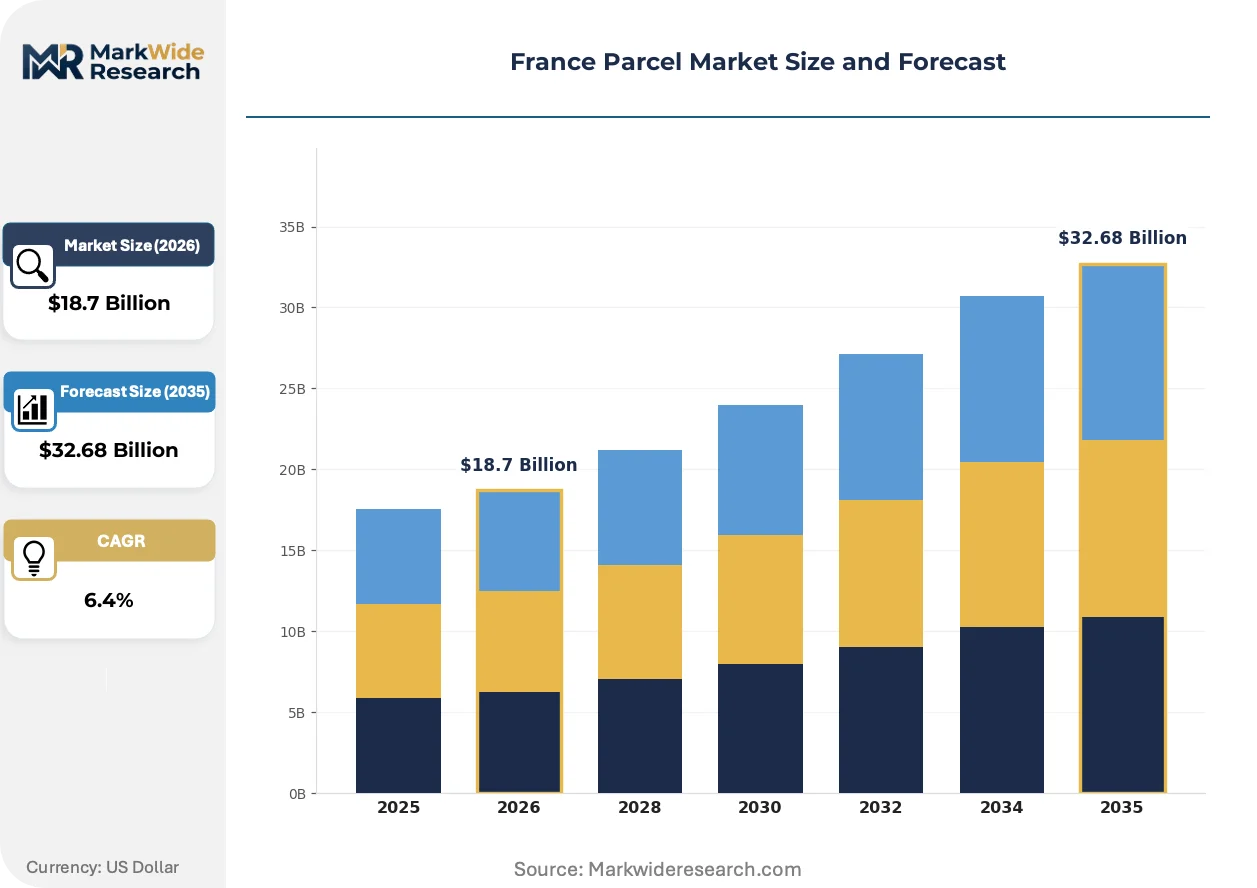
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, International Shipping End User: Retailers, E-commerce Platforms, SMEs, Individuals Packaging Type: Boxed, Palletized, Envelopes, Custom Packaging Delivery Channel: Direct Shipping, Third-Party Logistics, Pick-Up Points, Automated Lockers |
| Companies Covered | Chronopost, DPD, La Poste Group, UPS, FedEx, Colissimo, DHL Group, Colis Privé, Mondial Relay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Parcel Market Trends and Innovations
Parcel networks are converging around automation, sustainability compliance, and urban consolidation models that compress delivery economics while expanding service coverage.
Electric last-mile fleets are expanding into French urban delivery corridors as operators respond to EU Green Deal emission reduction mandates. Chronopost and DPD are deploying battery-powered vans across Paris, Lyon, and Bordeaux metropolitan zones at accelerating pace. This technology is expanding into suburban and intercity routes as charging infrastructure density permits range extension beyond core urban perimeters.
ADEME packaging recyclability thresholds are tightening material specifications for parcel operators serving French consumer markets. Single-use plastic penalties and recycled content minimums are restructuring supplier relationships toward corrugated fiberboard specialists. Express delivery services face the steepest compliance costs due to premium packaging expectations, forcing operational redesign toward reusable container systems.
Quick-commerce platforms are compressing delivery time expectations from next-day to same-hour windows in dense residential districts. Traditional express carriers are losing volume to specialized urban logistics providers operating micro-fulfillment nodes. This behavioral shift concentrates most intensely in Paris intra-muros and Lyon Presqu'île, where population density supports unit economics for sub-60-minute fulfillment.
France Parcel Market Segmentation
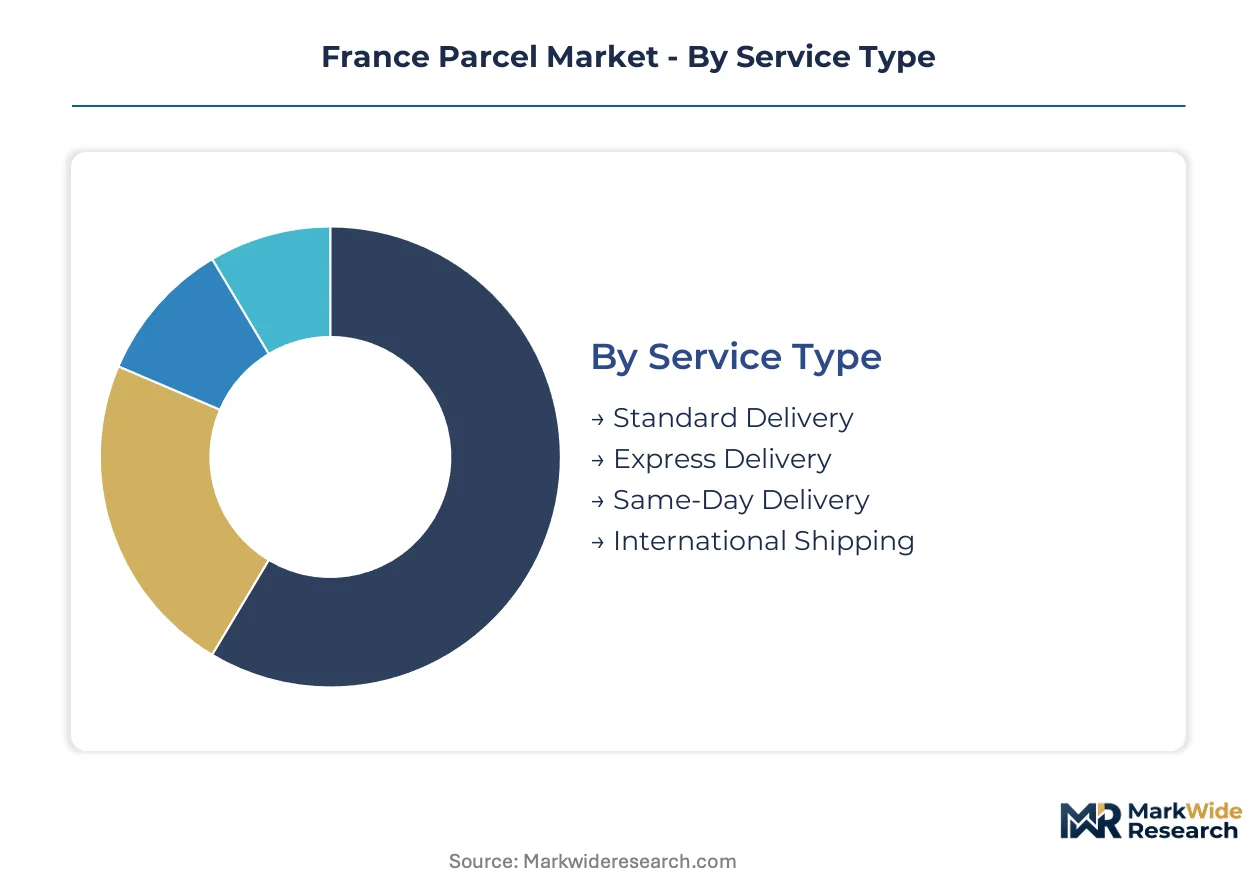
Segmentation in the France parcel market reveals how service differentiation, customer scale, and last-mile infrastructure shape operator economics. Understanding these dimensions exposes where margin pools concentrate and where competitive intensity is restructuring.
Service Type:
Speed expectations and pricing power separate buyers across service tiers, with premium time-definite options commanding structural advantages.
- Standard Delivery:Economy-focused shipments with 2-5 day transit windows dominate volume flows through La Poste Group's Colissimo network. Retailers and marketplace sellers absorb this cost tier to preserve margin on low-value goods.
- Express Delivery:Time-definite next-day service carries premium pricing through Chronopost's dense last-mile infrastructure. Paris metropolitan corridors generate the densest demand concentration as financial services and luxury goods shippers prioritize reliability over cost.
- Same-Day Delivery:Sub-60-minute fulfillment windows expanding through quick-commerce micro-fulfillment nodes in Lyon Presqu'île and Marseille.
- International Shipping:Cross-border parcel flows connecting French e-commerce platforms to EU single market destinations.
Volume sits with Standard Delivery; growth tilts toward Same-Day Delivery.
End User:
Scale and shipping frequency determine service configuration, with large-volume accounts extracting customized terms unavailable to sporadic shippers.
- E-commerce Platforms:High-frequency shippers operating automated sorting integrations and API-connected label generation. Quick-commerce specialists in Paris intra-muros are compressing delivery windows to same-hour fulfillment.
- Retailers:Omnichannel operators blending store fulfillment with direct-to-consumer parcel injection. Electronics and apparel categories drive the steepest express adoption as return-rate sensitivity elevates service reliability requirements.
- SMEs:Mid-scale shippers lacking dedicated logistics infrastructure, dependent on third-party platform integrations.
- Individuals:Sporadic C2C shippers utilizing retail access points and postal counters.
Parcel density clusters with E-commerce Platforms; margin expansion tracks toward Retailers.
Packaging Type:
Dimensional weight pricing and ADEME recyclability thresholds are restructuring material specifications across shipper categories.
- Boxed:Corrugated fiberboard containers replacing virgin cardboard under EU Green Deal packaging mandates. Express carriers face steepest compliance costs as premium service expectations resist material downgrades.
- Envelopes:Lightweight document and soft-goods pouches dominating intercity letter-class flows. Financial services and legal sectors in Paris maintain concentrated demand for tamper-evident envelope specifications.
- Palletized:Bulk parcel consolidation for B2B corridor movements between distribution centers.
- Custom Packaging:Branded unboxing experiences for luxury and subscription commerce.
Shipment volume aggregates in Boxed; sustainability-driven substitution is accelerating fastest in Custom Packaging.
Delivery Channel:
Last-mile density and failed-delivery cost absorption separate channel economics, with automated infrastructure capturing margin from manual attempts.
- Automated Lockers:Smart consolidation points reducing failed delivery costs in residential districts. DPD and Chronopost are deploying density in Toulouse and Nantes ahead of competitor saturation.
- Third-Party Logistics:Outsourced fulfillment and last-mile execution for e-commerce platforms lacking captive infrastructure. Specialized urban logistics providers are displacing traditional express carriers in sub-60-minute delivery windows.
- Direct Shipping:Carrier-operated last-mile without intermediary consolidation.
- Pick-Up Points:Retail-accessible collection counters in convenience and grocery networks.
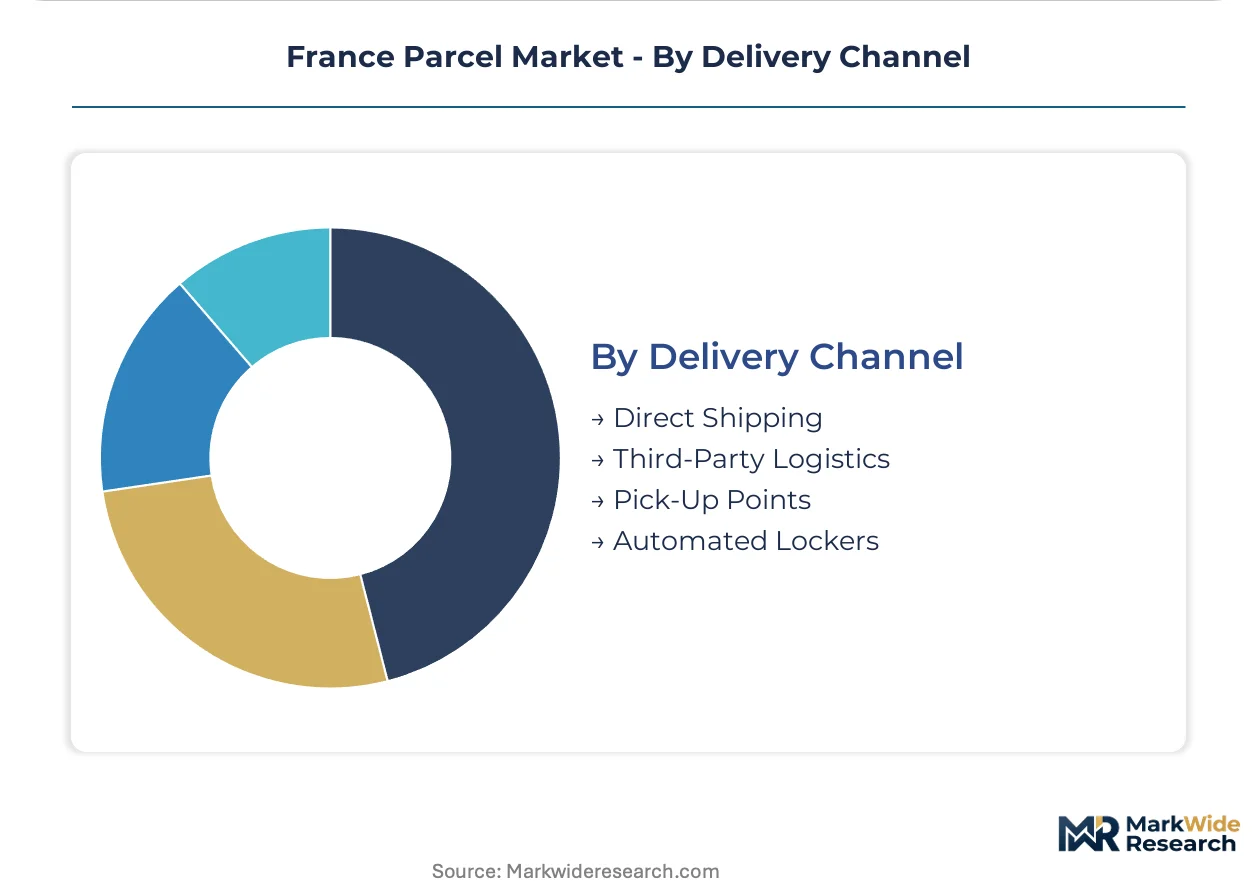
Network coverage concentrates in Third-Party Logistics; capital efficiency is improving fastest through Automated Lockers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parcel demand concentrates in the Paris metropolitan corridor, where logistics infrastructure density and e-commerce penetration create volume gravity. Secondary urban clusters in Lyon and Marseille are emerging as growth poles through quick-commerce expansion. Regional disparities in automated locker deployment and electric fleet penetration are restructuring competitive access across French territory.
Île-de-France
Paris intra-muros and the Petite Couronne generate the densest parcel flows through financial services and luxury goods corridors. DGCCRF delivery guarantee enforcement is strictest here, elevating service reliability requirements. Chronopost and DPD operate automated sorting hubs in Bobigny and Roissy-Charles de Gaulle logistics zones to capture same-day demand.
Auvergne-Rhône-Alpes
Lyon Presqu'île and Grenoble technology clusters pull express volume from electronics and pharmaceutical shippers. ADEME regional subsidies for electric commercial vehicles accelerate fleet conversion in the metropolitan area. Micro-fulfillment nodes in Villeurbanne and Saint-Étienne are expanding same-hour delivery coverage for quick-commerce platforms.
Provence-Alpes-Côte d'Azur
Marseille port logistics and Nice tourism commerce create mixed B2B and B2C parcel density. EU Green Deal emission zone restrictions in Marseille center push operators toward electric last-mile fleets. Aix-en-Provence and Toulon are receiving automated locker investments ahead of competitor saturation in these midsize urban markets.
Hauts-de-France
Lille metropolitan cross-border e-commerce flows connect French platforms to Belgian and Dutch consumer markets. The region's warehouse land availability near the A1 motorway corridor attracts distribution center investments from national carriers. Calais and Dunkirk port logistics create palletized consolidation demand for B2B parcel movements.
Nouvelle-Aquitaine
Bordeaux wine commerce and aerospace supply chains generate specialized express requirements with temperature-control and security specifications. ADEME packaging recyclability incentives support corrugated fiberboard substitution in the region's premium goods export channels. Automated locker deployment in Bordeaux Métropole lags Paris and Lyon, creating first-mover opportunities for network expansion.
France Parcel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated postal operators and independent express carriers dividing the French parcel landscape. La Poste Group anchors universal service through Colissimo while Chronopost captures premium express margins. Three strategic archetypes dominate: state-affiliated postal networks, multinational integrators, and specialized urban logistics providers. Competitive moves center on automated hub expansion and electric fleet conversion rather than price warfare.
Within the state-affiliated tier, La Poste Group and Chronopost occupy positions that combine regulatory privilege with commercial agility. Among multinational integrators, DPD and DHL Group exemplify the automated infrastructure archetype through dense sorting investments. These named entities represent how competitive positioning in French parcel markets depends on balancing regulatory compliance with service velocity.
| Leading Market Players |
|---|
| Chronopost |
| DPD |
| La Poste Group |
| UPS |
| FedEx |
| Colissimo |
| DHL Group |
| Colis Privé |
| Mondial Relay |
| Others |
Pricing and Supply Chain Analysis
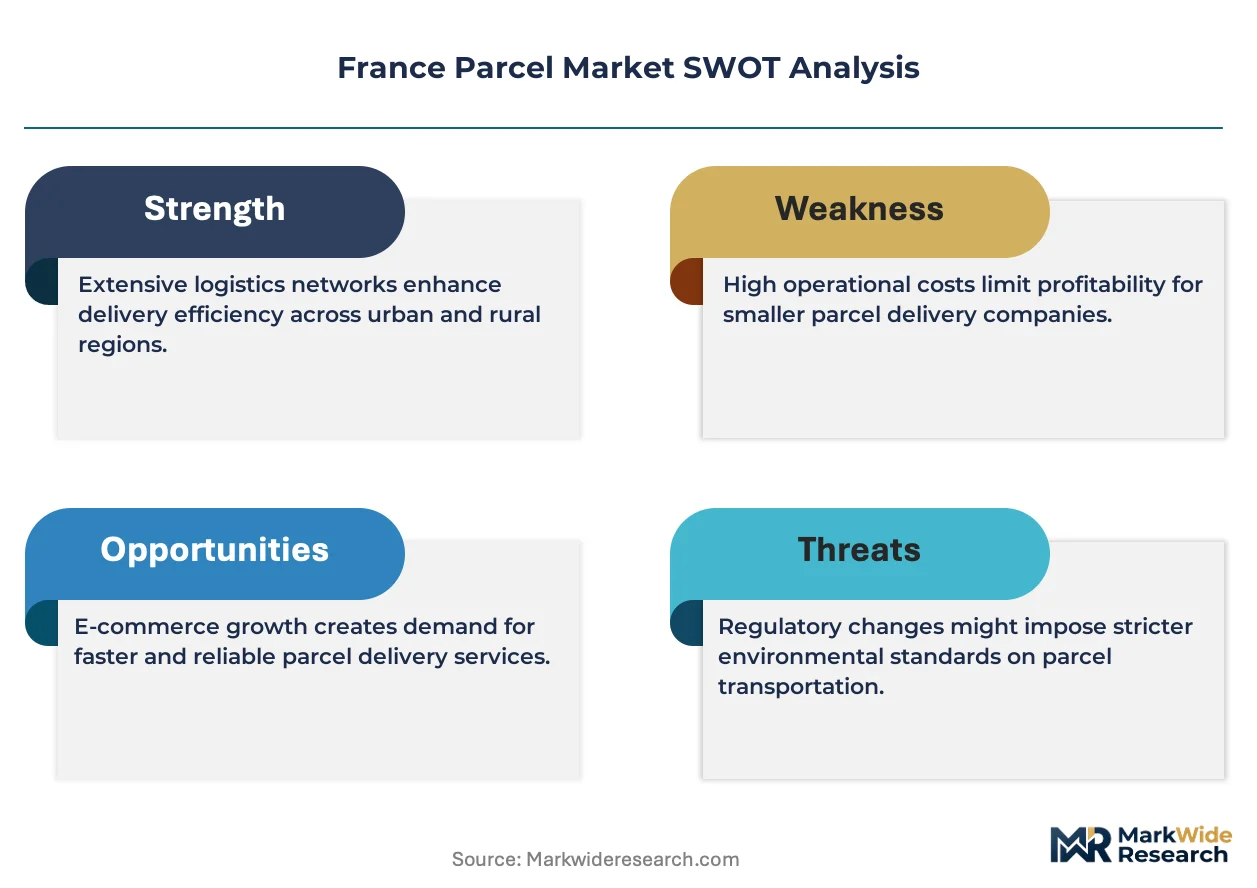
Express-standard-economy service tier divergence in French parcel markets manifests through divergent fuel surcharge pass-through mechanics and sorting infrastructure intensity, with premium Chronopost services commanding dedicated hub capacity while Colissimo standard volumes flow through shared postal networks. This bifurcation concentrates pricing power with time-definite specialists and compresses margins in economy segments where La Poste Group bears universal service obligations.
Pricing Analysis
Volume aggregates with standard delivery while margin concentrates in express tiers. Three-tier pricing structure across premium, standard, and economy levels reflects transit time guarantees, with Chronopost next-day services extracting fuel-adjusted premiums and Colissimo economy rates absorbing regulatory cross-subsidy burdens. Price differentiation hinges on delivery window certainty and last-mile density, with quick-commerce platforms least sensitive to cost and SME sporadic shippers most responsive to access point discounts. Pricing pressure stems from electric fleet conversion capex and recycled fiberboard input volatility.
Supply Chain Analysis
Corrugated fiberboard supply rests on German and Belgian recycling capacity, with virgin cardboard substitution constrained by European pulping infrastructure. Electric van procurement draws from French and German OEM assembly, while battery cell production centers on South Korean and Chinese suppliers. Single-source vulnerability concentrates in high-voltage technician training pipelines. Distribution runs through automated sorting hubs in Île-de-France and Auvergne-Rhône-Alpes, with last-mile execution fragmenting between carrier-operated fleets and third-party locker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's parcel sector is consolidating around compliance-heavy infrastructure investments, with EU Green Deal mandates and ADEME packaging thresholds forcing subscale operators toward exit or acquisition.
For Market Incumbents: Anticipate quick-commerce platform disintermediation by securing micro-fulfillment node partnerships in Lyon and Marseille before specialized urban logistics providers lock out traditional express carriers. Reinforce electric fleet density through ADEME subsidy capture and technician apprenticeship pipelines. Prioritize automated locker first-mover deployment in Toulouse and Nantes to preempt DPD saturation. For New Entrants and Emerging Players: The premium-economy price-point gap in secondary city same-day delivery offers white-space entry before Chronopost and DPD extend automated locker networks. Target Bordeaux Métropole and Strasbourg with locker-only infrastructure avoiding hub capex. Pursue SME-focused API integrations with recycled packaging compliance bundled as differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with automated locker network operators given ADEME subsidy flow-through and failed-delivery cost capture. Long-term viability favors assets with electric fleet conversion completion and DGCCRF compliance infrastructure. Watch electric vehicle technician certification velocity as inflection signal for rollout scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | ADEME subsidies offset battery procurement costs while DGCCRF emission zone access guarantees route coverage. |
| Automated Locker Density Expansion | DPD and Chronopost deployments in Toulouse and Nantes reduce failed delivery costs before competitor saturation. |
| Recycled Fiberboard Compliance | EU Green Deal packaging thresholds restructure supplier relationships toward corrugated specialists with virgin substitution capacity. |
| Micro-Fulfillment Node Partnerships | Quick-commerce platform alliances in Lyon Presqu'île defend volume against specialized urban logistics displacement. |
| Technician Apprenticeship Pipelines | High-voltage battery diagnostics training alleviates maintenance skill gaps constraining electric van rollout velocity. |
Research Methodology
EU customs data, ADEME environmental compliance filings, and La Poste Group universal service reports formed the secondary backbone, supplemented by carrier fleet disclosure statements and automated locker deployment records. Primary interviews with parcel operations directors, e-commerce logistics procurement managers, last-mile infrastructure planners, and DGCCRF regulatory compliance officers validated volume assumptions and pricing mechanics. Bottom-up parcel flow modeling triangulated against top-down e-commerce penetration projections.
Bottom-up segment sizing across service type, end user, packaging format, and delivery channel dimensions combined with top-down GDP-e-commerce elasticity checks. CAGRs derived from segment-level volume trajectories and pricing trend extrapolation across the analysis window. Electric vehicle adoption curves, ADEME subsidy phase-out schedules, and recycled fiberboard supply constraints fed industry-specific forecast inputs.
Underlying measurement precision varies by segment; express delivery and automated locker channels carry tighter precision than SME individual shipping due to carrier disclosure granularity. Forecasts reflect documented assumptions on e-commerce growth persistence and regulatory compliance cost pass-through. Electric fleet conversion delays, recycled material supply disruptions, and DGCCRF enforcement intensity shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market