
 Systemic Scleroderma Treatment Market | 2026-2036
Systemic Scleroderma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Scleroderma Treatment Market Intelligence
The systemic scleroderma treatment landscape is pivoting between premium biologics and conventional immunosuppressants as payers tighten reimbursement criteria for high-cost therapies. Bristol-Myers Squibb Company leverages its immunology portfolio to sustain leadership in T-cell modulation approaches. Boehringer Ingelheim International GmbH anchors its position through deep R&D investment in antifibrotic mechanisms. F. Hoffmann-La Roche Ltd differentiates via precision biomarker strategies that target interstitial lung disease subsets.
Systemic scleroderma treatment encompasses pharmaceutical interventions targeting autoimmune dysregulation, vascular pathology, and tissue fibrosis in diffuse and limited cutaneous subsets; primary formulations include small-molecule immunosuppressants, monoclonal antibodies, and vasodilator compounds administered via oral, intravenous, or subcutaneous routes to halt disease progression and manage organ-specific complications. Immunosuppressants occupy the largest revenue pool due to entrenched prescriber habits in rheumatology practice, while antifibrotic agents represent the fastest-expanding category as nintedanib and similar compounds gain traction in interstitial lung disease indications. Intravenous administration commands premium pricing and hospital pharmacy dependence, whereas subcutaneous delivery is gaining share through home-care penetration and patient convenience preferences.
The FDA orphan drug program and EMA's priority medicines scheme jointly shape clinical trial incentives and accelerated review pathways for novel scleroderma therapies, directly influencing pipeline investment decisions by developers. REACH compliance and MDR requirements in Europe impose stringent purity and traceability standards on active pharmaceutical ingredients, raising manufacturing barriers for generic entrants. Stakeholders must monitor evolving payer evidence requirements for fibrosis-specific endpoints as health technology assessment bodies recalibrate value frameworks for rare disease treatments.
Market Dynamics
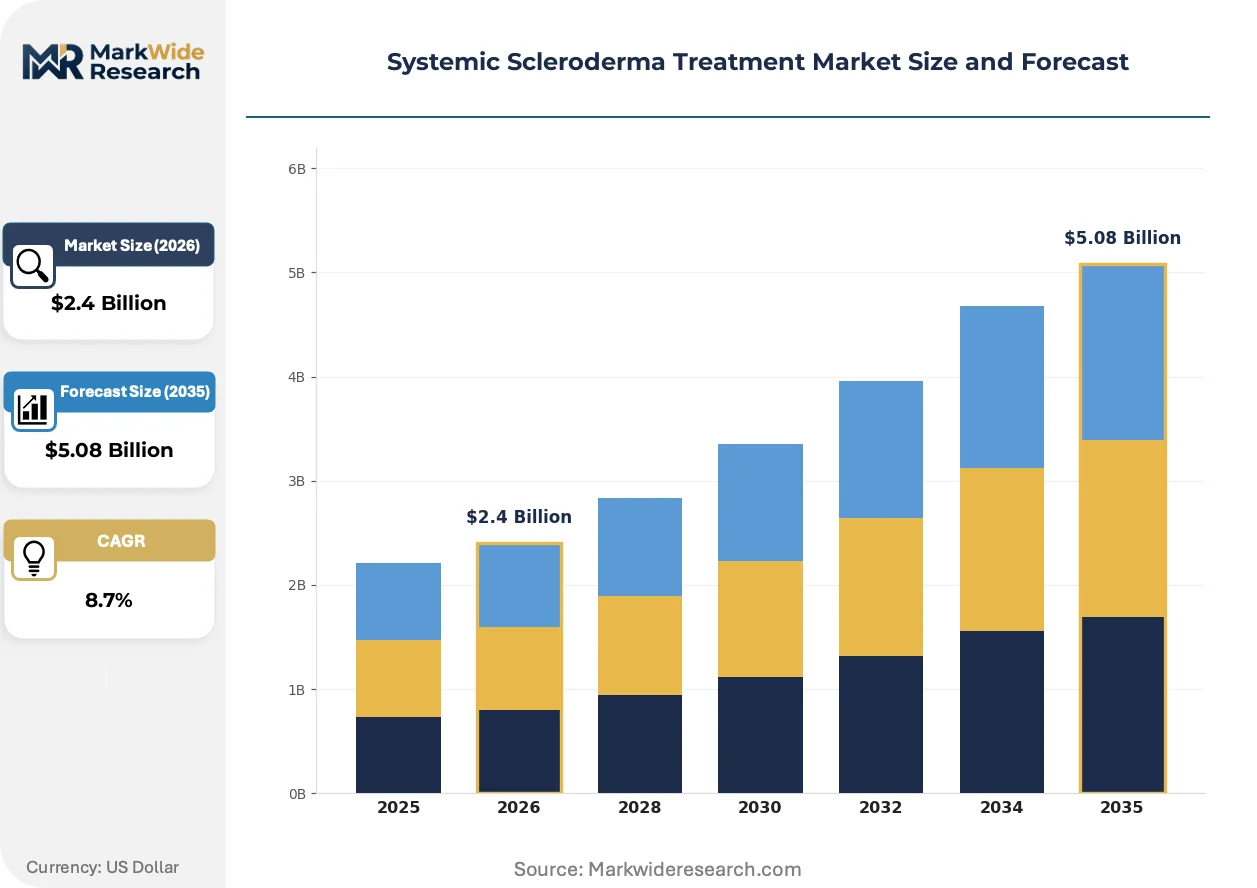
The systemic scleroderma treatment market pivots on tightening payer reimbursement criteria for premium biologics, forcing developers to demonstrate fibrosis-specific clinical endpoints that justify cost differentials against entrenched immunosuppressant standards.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan drug designation pathway accelerates novel therapy approvals by granting tax credits and market exclusivity extensions, drawing venture capital toward rare disease pipelines.
- Interstitial lung disease expansion:Antifibrotic agents targeting ILD complications in diffuse cutaneous subsets are capturing expanded label indications, broadening addressable patient populations beyond skin-limited presentations.
- Specialty clinic infrastructure:Dedicated rheumatology centers in the United States, Germany, and Japan are building integrated care pathways that streamline biologic administration and patient monitoring.
Market Restraints
- Biologic manufacturing concentration:Contract manufacturing for monoclonal antibodies concentrates among a handful of European and North American CDMOs, creating single-source vulnerability for pipeline candidates.
- Health technology assessment barriers:England's NICE and Germany's IQWiG impose stringent cost-effectiveness thresholds that frequently reject premium scleroderma therapies without mortality endpoint data.
- Small-molecule substitution pressure:Generic mycophenolate mofetil and methotrexate formulations erode pricing power for novel entrants in first-line maintenance settings.
Strategic Opportunities
- Japan's aging patient base:The country's rising diffuse cutaneous prevalence among elderly populations creates demand for home-administered subcutaneous formulations that reduce hospital dependency.
- Biomarker-guided precision dosing:Integration of IL-6 and TGF-β signaling assays with therapeutic algorithms enables personalized biologic selection, differentiating specialty clinic offerings.
- EMA's priority medicines scheme:Accelerated assessment pathways for antifibrotic candidates with orphan status compress development timelines and reduce regulatory capital requirements.
Industry Challenges
- Specialized trial design expertise:The scarcity of biostatisticians experienced in rare disease adaptive trial protocols delays study initiation and inflates CRO procurement costs.
- Legacy immunosuppressant entrenchment:Rheumatology prescriber habits rooted in decades of cyclophosphamide and mycophenolate use create formidable switching friction for biologic newcomers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Scleroderma Treatment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Corticosteroids, Antifibrotic Agents, Vasodilators Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | Bristol-Myers Squibb Company, Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Pfizer Inc., Eli Lilly and Company, Bayer AG, Novartis AG, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Scleroderma Treatment Market Strategic Shifts & Innovations
Precision biomarker integration and administration route innovation are compressing competitive differentiation windows, while regulatory frameworks recalibrate value demonstration requirements across major pharmaceutical markets.
Targeted T-cell modulation therapies are consolidating their position as the dominant mechanistic class in late-stage pipelines. Specialty clinics in Germany and the United States are adopting these agents at accelerating cadence for patients with refractory diffuse cutaneous progression. This consolidation is compressing development investment into narrowly defined immunologic pathways, crowding out exploratory fibroblast-directed approaches.
REACH compliance and MDR requirements in Europe are imposing stringent purity and traceability standards on active pharmaceutical ingredients used in parenteral formulations. These regulations are elevating manufacturing barriers for generic entrants and contract producers without dedicated rare disease capabilities. Antifibrotic biologics with complex glycosylation patterns face the steepest compliance cost escalations, favoring established European manufacturers with integrated quality systems.
Patient-administered subcutaneous delivery is displacing hospital-based intravenous infusion as the preferred route for maintenance biologic therapy. Home-care nursing networks in Japan and the United States are expanding capacity to support this transition, reducing treatment center burden. This channel shift is most visible in limited cutaneous populations with stable disease trajectories, where convenience and reduced infection exposure outweigh the premium pricing of IV formulations.
Systemic Scleroderma Treatment Market Segmentation
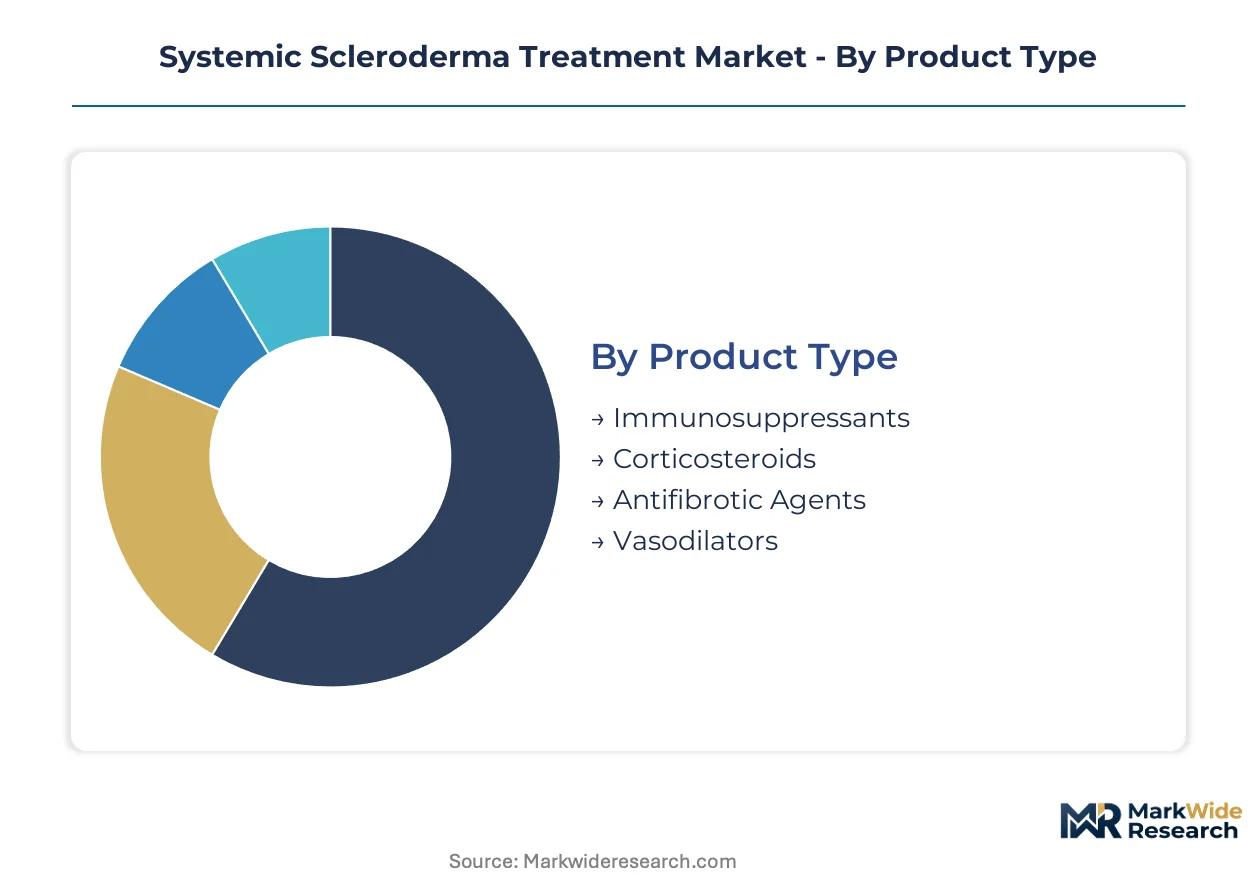
Systemic scleroderma treatment segmentation reveals distinct procurement patterns across therapeutic categories, with payer reimbursement tiers and administration logistics shaping channel preferences. Understanding these divides enables targeted positioning for biologic entrants against entrenched immunosuppressant standards.
Product Type:
Prescriber familiarity with mechanism of action and payer coverage tiers differentiate therapeutic selection across diffuse and limited cutaneous patient populations.
- Immunosuppressants:Small-molecule agents including mycophenolate mofetil and cyclophosphamide modulate lymphocyte proliferation through nucleotide synthesis inhibition. Rheumatology practices in the United States and Germany maintain heavy reliance on these compounds for first-line maintenance, though IQWiG cost-effectiveness reviews in Germany increasingly challenge reimbursement for non-biologic alternatives without mortality data.
- Antifibrotic Agents:Kinase inhibitors and related compounds target TGF-β signaling and collagen deposition in interstitial lung disease complications. Specialty clinics in Japan are expanding nintanib prescriptions for elderly diffuse cutaneous patients with progressive fibrosis, driven by PMDA orphan drug incentives and home-care administration protocols.
- Corticosteroids:Glucocorticoid formulations provide acute symptom relief but carry limited disease-modifying efficacy; tapering protocols dominate maintenance planning.
- Vasodilators:Calcium channel blockers and prostacyclin analogs address Raynaud's phenomenon and digital ulcer prevention in limited cutaneous subsets.
Immunosuppressants lead volumes today; antifibrotic agents are gaining share fastest.
Administration Route:
Site-of-care economics and patient mobility constraints determine route selection, with hospital capacity pressures accelerating shifts toward ambulatory alternatives.
- Intravenous:Hospital-based infusion of monoclonal antibodies and cyclophosphamide requires specialized nursing infrastructure and carries premium pricing tied to facility fees. United States academic medical centers maintain dominant IV volumes for rituximab and tocilizumab in refractory cases.
- Subcutaneous:Patient-administered biologics reduce treatment center burden and infection exposure. Home-care networks in Japan are expanding subcutaneous capacity for elderly diffuse cutaneous patients, supported by METI telehealth reimbursement frameworks.
- Oral:Small-molecule immunosuppressants and corticosteroids dominate maintenance therapy through pharmacy dispensing.
- Topical:Limited to localized symptom management in limited cutaneous presentations with minimal systemic penetration.
Intravenous administration retains revenue concentration; subcutaneous delivery is climbing the fastest.
End User:
Clinical complexity thresholds and reimbursement authorization requirements concentrate high-cost biologic prescribing in institutional settings with integrated care pathways.
- Specialty Clinics:Dedicated rheumatology centers in Germany and the United States coordinate biologic administration, biomarker monitoring, and multidisciplinary organ-specific care. These sites capture disproportionate antifibrotic agent volumes through streamlined prior authorization processes.
- Hospitals:Academic medical centers manage acute exacerbations, IV induction protocols, and interstitial lung disease complications requiring pulmonology co-management.
- Home Care:Nursing services support subcutaneous maintenance in stable limited cutaneous patients.
- Research Institutions:Clinical trial sites drive pipeline exposure for novel T-cell modulators and fibroblast-directed therapies.
Specialty clinics lead volumes today; home care is expanding most quickly.
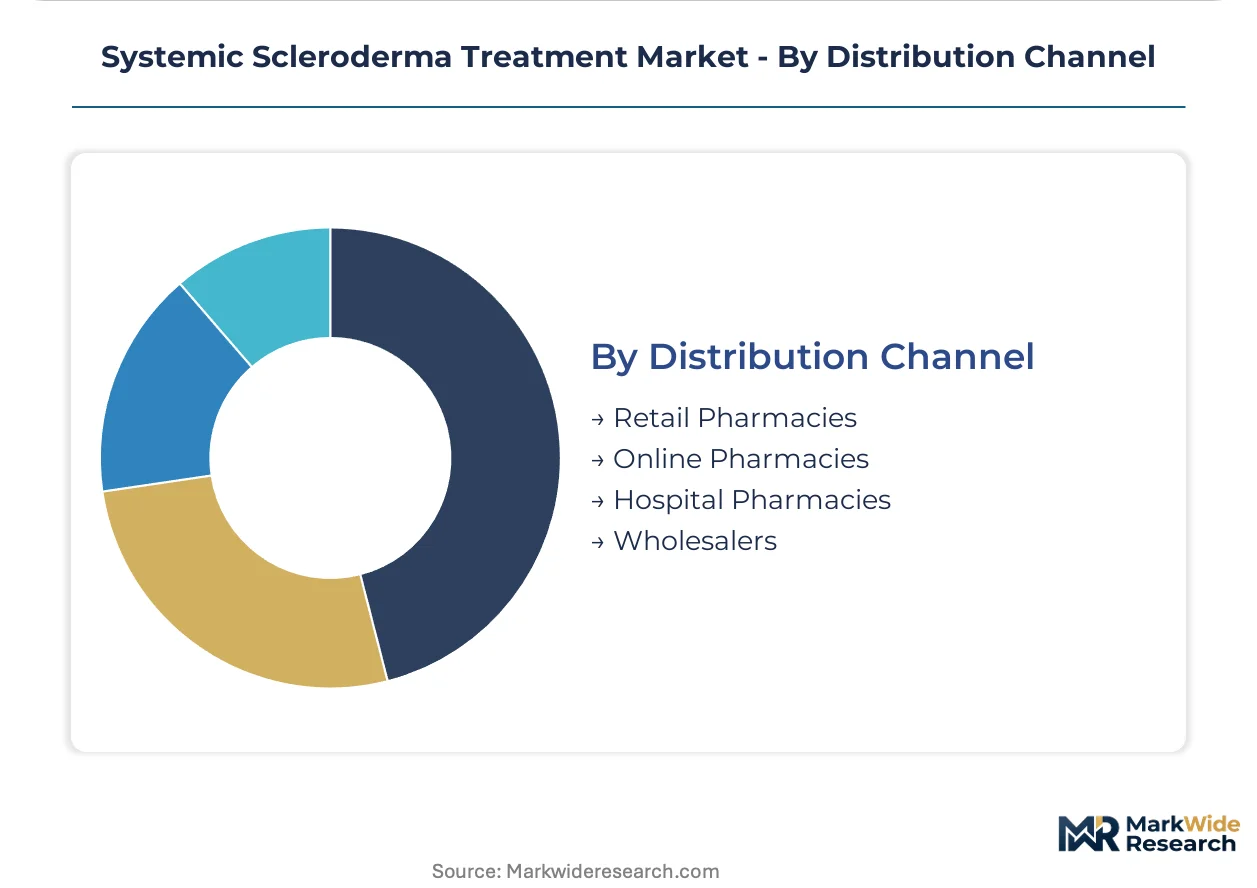
Distribution Channel:
Product temperature requirements, patient assistance program integration, and payer specialty pharmacy mandates fragment channel access for parenteral formulations.
- Hospital Pharmacies:Captures IV biologics and acute-care immunosuppressants through 340B pricing and integrated EHR procurement in United States health systems.
- Retail Pharmacies:Dominates oral generic immunosuppressants and corticosteroids with established prior authorization workflows.
- Online Pharmacies:Emerging for maintenance refills in limited cutaneous populations with stable dosing.
- Wholesalers:Provides cold-chain distribution infrastructure for temperature-sensitive monoclonal antibodies to hospital and specialty clinic customers.
Hospital pharmacies lead volumes today; online pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatology specialists cluster in the United States, Germany, and Japan, anchoring clinical trial networks and biologic adoption curves for systemic scleroderma therapies.
United States
Academic medical centers in Boston and New York drive rituximab and tocilizumab prescribing for refractory diffuse cutaneous cases. The FDA orphan drug designation pathway accelerates novel therapy approvals through tax credits and extended market exclusivity. Specialty clinics in the Mayo Clinic network streamline prior authorization for antifibrotic agents.
Germany
IQWiG cost-effectiveness reviews increasingly challenge reimbursement for non-biologic alternatives lacking mortality endpoint data. REACH compliance and MDR requirements impose stringent purity standards on active pharmaceutical ingredients. Rheumatology centers in Munich and Berlin coordinate integrated care pathways for interstitial lung disease complications.
Japan
PMDA orphan drug incentives and METI telehealth reimbursement frameworks expand home-care administration of subcutaneous formulations for elderly diffuse cutaneous patients. The aging patient base creates demand for nursing-supported maintenance therapy outside hospital settings. Tokyo and Osaka academic hospitals anchor biomarker-guided precision dosing protocols.
United Kingdom
NICE cost-effectiveness thresholds frequently reject premium scleroderma therapies without robust mortality data, compressing market access for novel entrants. The NHS England specialized commissioning framework concentrates biologic prescribing in designated rheumatology centers. London and Manchester hospital networks lead adaptive trial protocol design for rare disease indications.
Switzerland
Swissmedic accelerated assessment pathways for antifibrotic candidates with orphan status reduce regulatory capital requirements for developers. Basel and Zurich host concentrated pharmaceutical R&D infrastructure supporting fibrosis-specific endpoint validation. The country's precision medicine initiatives enable integration of IL-6 and TGF-β signaling assays with therapeutic algorithms.
Systemic Scleroderma Treatment Market Key Industry Players
Top-tier vendors anchor immunomodulation and antifibrotic development, while mid-cap specialists concentrate on biomarker-guided precision platforms. The market structure reflects consolidation around T-cell modulation expertise and antifibrotic kinase inhibition. Three archetypes dominate: large-cap immunology portfolio holders, targeted fibrosis developers, and precision biomarker integrators. Competitive moves center on orphan drug exclusivity extensions and specialty clinic partnership networks.
Within the large-cap immunology tier, Bristol-Myers Squibb Company and F. Hoffmann-La Roche Ltd occupy positions representing T-cell modulation and precision biomarker strategies respectively. Boehringer Ingelheim International GmbH exemplifies the targeted fibrosis development archetype through its R&D concentration in antifibrotic mechanisms. These three entities collectively represent the dominant competitive vectors shaping prescriber access and payer negotiation dynamics across the United States, Germany, and Japan.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Eli Lilly and Company |
| Bayer AG |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Others |
Cost & Logistics Intelligence
Payer consolidation around specialty pharmacy mandates in the United States and Germany is forcing biologic manufacturers to absorb facility fee markups into list prices, compressing net margins and accelerating subcutaneous formulation investment to bypass hospital pharmacy gatekeepers.
Pricing Analysis
Facility-bundled versus unbundled service splits dominate systemic scleroderma therapy pricing, with hospital-based IV infusions commanding premium facility fees while subcutaneous alternatives compete on patient out-of-pocket minimization. Price differentiation rests on orphan drug exclusivity status and biomarker-guided patient selection protocols, with FDA-designated therapies capturing substantial brand premiums over generic immunosuppressants. Pricing pressure stems from IQWiG and NICE cost-effectiveness thresholds that demand mortality endpoint data for premium reimbursement, forcing developers to discount in European markets. Large academic medical centers in the United States exhibit lowest price sensitivity due to 340B pricing advantages, while German statutory health insurers demonstrate highest sensitivity through rigid reference pricing mechanisms.
Supply Chain Analysis
Freight cost escalation for temperature-controlled monoclonal antibody distribution is reshaping regional sourcing strategies, with European and North American contract manufacturers gaining preference over Asian CDMOs for pipeline candidates targeting orphan indications. Active pharmaceutical ingredient supply concentrates in Switzerland, Germany, and the United States, where REACH and MDR compliance capabilities are pre-installed. Manufacturing draws from recombinant protein expression systems, specialized glycosylation equipment, and single-use bioreactor technologies. Single-source vulnerability pervades fill-finish capacity for parenteral formulations, with regulatory restriction risk elevating as FDA inspection backlogs delay site approvals. Distribution runs through integrated wholesaler-specialty pharmacy networks in the United States and direct-to-hospital contracts in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The systemic scleroderma treatment market functions as a regulatory compounder, where FDA orphan drug designation accelerations and EMA priority medicines pathways cumulatively expand addressable revenue pools for developers with established rare disease infrastructure.
For Market Incumbents: Cement leadership through captive biologics manufacturing capacity in Basel and Boston corridor sites, insulating against CDMO concentration risk while securing supply continuity for tocilizumab-class therapies. Deepen biomarker assay integration with specialty clinic networks to create switching friction against rituximab biosimilar entrants. Prioritize EMA rapporteur engagement for antifibrotic label expansions ahead of competitor filings. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Japanese home-care administration creates immediate white-space opportunity for subcutaneous formulations with simplified cold-chain requirements. Target elderly diffuse cutaneous populations in Osaka and Nagoya metropolitan zones where hospital capacity constraints are most acute. Pursue METI telehealth reimbursement alignment as the primary go-to-market angle, leveraging existing nursing network infrastructure rather than building de novo. For Investors and Strategic Acquirers: Asymmetric upside sits with precision biomarker platform developers possessing IL-6 and TGF-β signaling assay capabilities that enable companion diagnostic positioning. Long-term viability across the analysis window favors entities with integrated diagnostic-therapeutic offerings rather than standalone biologic assets. Monitor PMDA orphan drug designation velocity as the inflection indicator for Japanese market access trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and exclusivity extensions accelerate capital recovery for rare disease pipelines. |
| Subcutaneous Formulation Development | Home-care administration protocols in Japan reduce hospital pharmacy dependence and facility fee burdens. |
| Biomarker Assay Integration | IL-6 signaling companion diagnostics differentiate specialty clinic offerings against immunosuppressant standards. |
| EMA Priority Medicines Engagement | Accelerated assessment pathways compress regulatory capital requirements for antifibrotic candidates. |
| Specialty Clinic Partnership Networks | Integrated care pathways in German rheumatology centers streamline prior authorization for biologic therapies. |
Research Approach
Multiple input streams — regulatory filing databases, clinical trial registries, and payer policy documentation — were reconciled with primary interviews spanning drug development executives, regulatory affairs leads, formulary directors at United States academic medical centers, and hospital procurement managers in German rheumatology networks. Secondary validation drew from FDA orphan drug designation records, EMA priority medicines submissions, ClinicalTrials.gov protocol entries, and IQWiG benefit assessment reports. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Historical approval trajectories for T-cell modulators and antifibrotic agents were cross-referenced against panel input from payer access specialists regarding evolving reimbursement criteria across the projection horizon. Segmentation dimensions modeled encompassed therapeutic category, administration route, end-user setting, and regional regulatory cluster. CAGRs were derived from weighted scenario analysis incorporating pipeline probability-adjusted revenue flows and patient share evolution assumptions. Forecast inputs included biomarker adoption curves and specialty clinic infrastructure buildout rates.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous biologic delivery would alter the outlook if home-care nursing capacity expansion lags patient demand. Forecasts reflect assumptions regarding orphan drug incentive continuity and payer evidence requirement stability. A model refresh is warranted upon material change in FDA accelerated approval policy or EMA benefit assessment methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market