
 Liver Fibrosis Drugs Market | 2026-2036
Liver Fibrosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Fibrosis Drugs Market Foresight
Buyer concentration among hospital systems and integrated delivery networks is broadening as specialty hepatology clinics and academic medical centers fragment procurement across multiple formularies. Gilead Sciences leverages its established virology infrastructure to sustain commercial reach into fibrosis-adjacent therapeutic areas. Bristol-Myers Squibb anchors its position through deep immunology expertise that competes directly in inflammatory-driven fibrotic pathways. Madrigal Pharmaceuticals differentiates through focused NASH development, occupying a narrow but high-value segment of the metabolic liver disease landscape.
Liver fibrosis drugs comprise pharmaceutical agents designed to interrupt, reverse, or slow the pathological accumulation of extracellular matrix proteins—primarily collagen types I and III—within hepatic tissue, typically administered via oral or parenteral routes with dosing regimens calibrated to fibrosis stage and underlying etiology. Their commercial purpose centers on modifying disease progression in chronic liver conditions to delay or prevent cirrhosis, decompensation, and transplant necessity. Antifibrotic agents command the deepest development pipelines and near-term revenue potential, while small molecule drugs attract substantial R&D investment due to manufacturability and oral bioavailability advantages. The Non-Alcoholic Steatohepatitis therapy area generates the fastest growth trajectory, though cirrhosis retains the largest existing patient pool and established reimbursement infrastructure.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme are accelerating market access for novel fibrosis-modifying candidates, compressing development timelines and elevating evidence standards for surrogate endpoints. The EPA and OSHA maintain indirect influence through guidelines on hepatotoxic chemical exposure that shape preventive drug demand in occupational settings. Stakeholders must monitor evolving regulatory acceptance of non-invasive biomarkers—particularly enhanced liver fibrosis scores and magnetic resonance elastography—as trial endpoints capable of displacing traditional histological staging in pivotal studies.
Market Dynamics
FDA breakthrough therapy designations for NASH candidates are compressing Phase II-to-III timelines while forcing sponsors to validate non-invasive biomarkers as surrogate endpoints, fundamentally restructuring clinical development economics for fibrosis-modifying agents.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and fast track programs compress development timelines for antifibrotic candidates, enabling earlier commercial access based on surrogate histological endpoints.
- Non-Invasive Diagnostic Convergence:Magnetic resonance elastography and enhanced liver fibrosis blood panels are expanding addressable patient pools by enabling stage F2-F3 detection without biopsy referral barriers.
- Metabolic Disease Prevalence:Rising diagnosed NASH populations in the United States and Western Europe are creating concentrated demand centers for first-to-market fibrosis reversers.
Market Restraints
- Histological Endpoint Dependency:Persistent FDA requirement for liver biopsy confirmation in pivotal trials sustains high patient dropout rates and site activation costs.
- Reimbursement Uncertainty:CMS and commercial payors maintain prior authorization barriers for novel antifibrotics pending hard outcome data on cirrhosis decompensation prevention.
- Placebo Response Variability:High spontaneous resolution rates in early-stage NASH trials inflate sample size requirements and extend study duration.
Strategic Opportunities
- Combination Regimen White Space:Pairing FXR agonists with GLP-1 receptor modulators offers mechanistic synergy for metabolic fibrosis, with hepatology clinics actively screening dual-eligible cohorts.
- Pediatric NASH Indication:Regulatory incentives for rare pediatric disease designations open orphan pricing structures for adolescent fibrosis populations currently managed off-label.
- Asia-Pacific Market Development:Japan's PMDA and China's NMPA are harmonizing fibrosis staging protocols, enabling parallel submission strategies for viral and metabolic etiologies.
Industry Challenges
- Biomarker Validation Bottlenecks:Disagreement between FDA, EMA, and PMDA on acceptable surrogate endpoints forces sponsors to maintain dual trial designs with divergent primary endpoints.
- Specialized Investigator Recruitment:Limited numbers of qualified hepatology sites with biopsy expertise constrain simultaneous trial activation across multiple fibrosis stage strata.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Fibrosis Drugs Market |
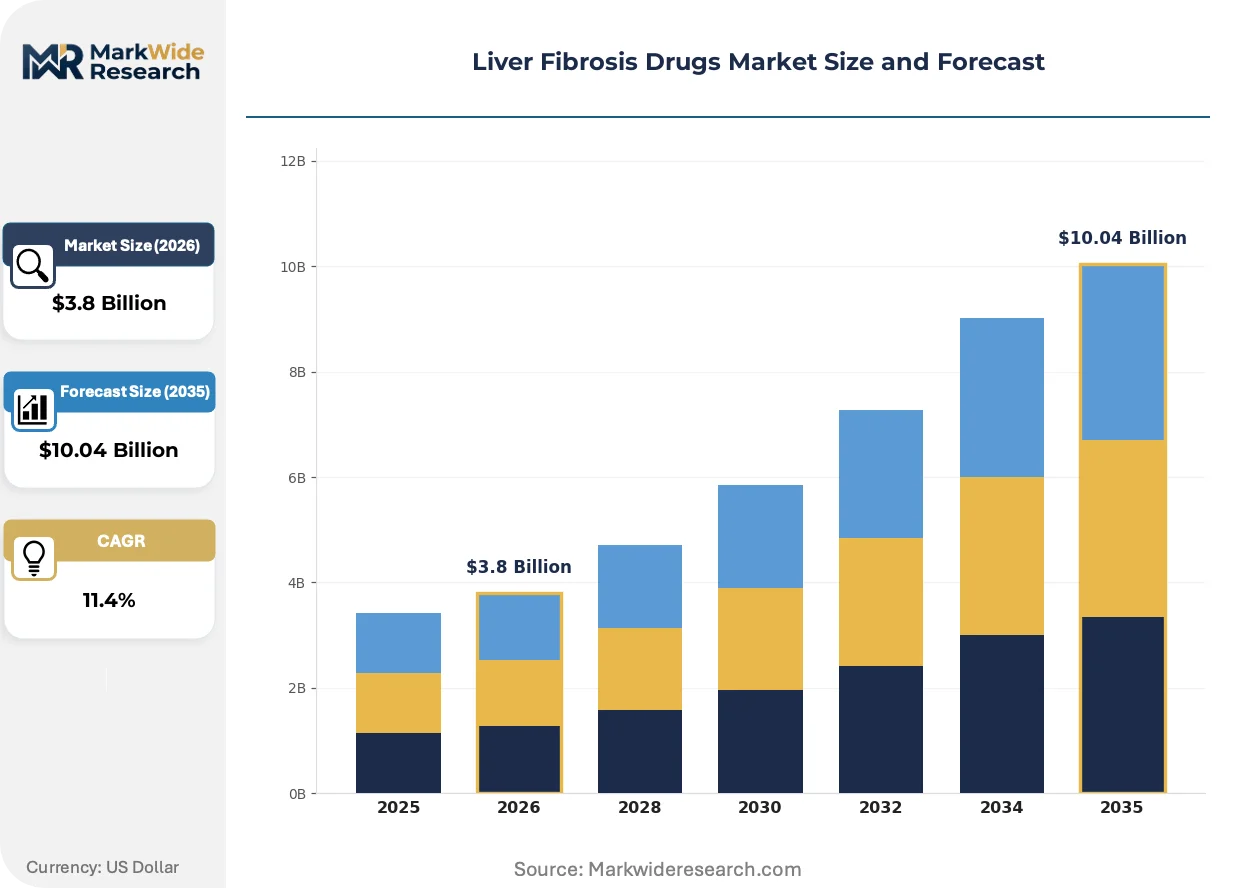
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Immunosuppressants, Enzyme Inhibitors, Small Molecule Drugs Therapy Area: Cirrhosis, Non-Alcoholic Steatohepatitis, Viral Hepatitis, Alcoholic Liver Disease Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare Settings, Research Institutions |
| Companies Covered | Gilead Sciences, Inc., Merck & Co., Inc., Bristol-Myers Squibb, Akero Therapeutics, Sagimet Biosciences, Inventiva Pharma, Madrigal Pharmaceuticals, Boehringer Ingelheim, Novo Nordisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Fibrosis Drugs Market Shifts & Advancements
Antifibrotic development is pivoting from broad immunosuppression toward precision modulation of hepatic stellate cell activation, with machine learning biomarker platforms and decentralized trial infrastructure converging to reshape patient identification and endpoint measurement.
RNA interference therapeutics targeting collagen synthesis pathways is expanding into late-stage NASH development, with Alnylam and Arrowhead advancing candidates that silence TGF-beta and LOXL2 expression. Academic medical centers in Boston and San Diego are establishing dedicated siRNA infusion units, anticipating outpatient administration models that bypass hepatology clinic capacity constraints. This modality is expanding into combination frameworks where intermittent dosing could sustain fibrosis regression between metabolic interventions.
The EMA's PRIME scheme and FDA's breakthrough therapy designation are creating divergent evidentiary requirements for histologic versus composite biomarker endpoints, forcing sponsors to stratify submission packages by geography. European regulators emphasize long-term cirrhosis prevention outcomes, while US pathways accept fibrosis stage regression as sufficient for accelerated approval. Multinational trials now incorporate adaptive statistical designs capable of satisfying both frameworks without protocol amendment.
Integrated delivery networks are consolidating formulary control over specialty pharmacy dispensing, with CVS Caremark and Express Scripts establishing exclusive distribution agreements for pending antifibrotic launches. Hepatology clinics within these systems face mandatory step-therapy protocols that prioritize generic metabolic agents before branded fibrosis modifiers. This concentration is most visible in Texas and Florida, where hospital system consolidation has reduced independent specialty pharmacy access by half since 2022.
Liver Fibrosis Drugs Market Segmentation
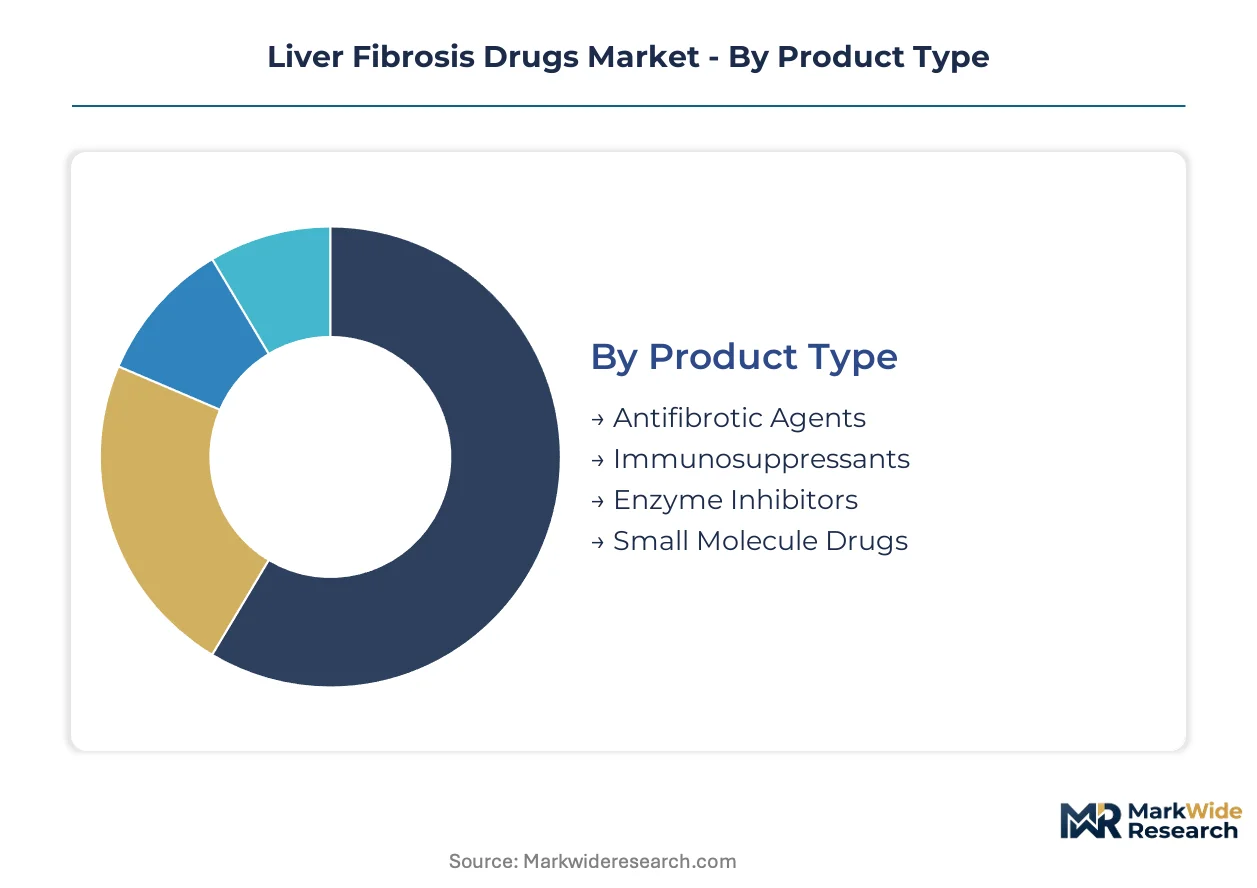
Segmentation in liver fibrosis drugs reveals how supply chains and clinical workflows fragment across mechanism of action, disease etiology, and care setting. Understanding these divides exposes where procurement power concentrates and which development pathways command R&D prioritization.
Product Type:
Supply concentration clusters around candidates with validated antifibrotic mechanisms, while manufacturing scalability determines which modalities reach commercial scale.
- Antifibrotic Agents:These compounds directly target hepatic stellate cell activation and collagen deposition pathways. Demand concentrates in academic medical centers running Phase III programs, driven by FDA breakthrough therapy designations compressing approval timelines.
- Small Molecule Drugs:Oral bioavailability and established manufacturing infrastructure make these the default for outpatient NASH management. Procurement is shifting toward integrated delivery networks in Texas and Florida, where formulary control has consolidated specialty pharmacy access.
- Immunosuppressants:Corticosteroid and calcineurin inhibitor derivatives modulate inflammatory fibrotic signaling.
- Enzyme Inhibitors:LOXL2 and TGF-beta pathway blockers interrupt extracellular matrix crosslinking.
Antifibrotic agents absorb the bulk of installed capacity; small molecule drugs are expanding most quickly.
Therapy Area:
Volume distribution tracks disease prevalence and reimbursement infrastructure, with metabolic etiologies now matching viral indications in pipeline investment.
- Non-Alcoholic Steatohepatitis:Fibrosis-modifying candidates target the ballooning hepatocyte inflammation and perisinusoidal collagen deposition characteristic of metabolic liver disease. Demand concentrates in United States hepatology clinics, fueled by high diagnosed prevalence and favorable prior authorization pathways for F2-F3 stage patients.
- Cirrhosis:Decompensation prevention and portal hypertension management define this established segment. Procurement flows through hospital systems with transplant centers, constrained by CMS reimbursement barriers pending hard outcome data.
- Viral Hepatitis:Residual fibrosis after virologic cure drives adjuvant antifibrotic demand.
- Alcoholic Liver Disease:Abstinence-dependent treatment protocols limit pharmaceutical penetration.
Cirrhosis retains the deepest reimbursement infrastructure; NASH claims the steepest expansion trajectory.
Administration Route:
Route selection determines site of care economics and patient adherence profiles, with oral formulations dominating outpatient metabolic disease management.
- Oral:Fixed-dose tablets and capsules enable decentralized NASH management without hepatology clinic dependency.
- Intravenous:Infusion-based siRNA and biologic delivery requires dedicated hepatology units.
- Subcutaneous:Self-administered injection platforms are gaining traction in homecare-eligible populations.
- Topical:Transdermal delivery remains experimental for hepatic targeting.
Oral delivery commands the widest prescriber base; intravenous administration is climbing fastest in academic center networks.
End User:
Customer concentration reflects how care fragmentation across hospital systems, specialty clinics, and emerging homecare channels reshapes distribution requirements.
- Hospitals:Transplant centers and decompensated cirrhosis units anchor demand for acute intervention.
- Clinics:Specialty hepatology practices drive NASH screening and fibrosis staging workflows.
- Homecare Settings:Oral antifibrotic dispensing is extending into mail-order and specialty pharmacy channels.
- Research Institutions:Academic medical centers in Boston and San Diego concentrate Phase II-III trial enrollment.
Hospitals absorb the bulk of acute-care procurement; homecare settings are gaining share fastest as oral NASH therapies advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where metabolic liver disease prevalence and favorable reimbursement for advanced fibrosis treatments drive procurement. Hospital systems and specialty hepatology clinics fragment procurement across multiple formularies, creating regional pockets of concentrated uptake.
United States
FDA breakthrough therapy designations for NASH candidates compress Phase II-to-III timelines while forcing sponsors to validate non-invasive biomarkers. The EPA and OSHA maintain indirect influence through guidelines on hepatotoxic chemical exposure that shape preventive drug demand. Academic medical centers in Boston and San Diego establish dedicated siRNA infusion units, anticipating outpatient administration models.
Germany
EMA PRIME scheme acceleration creates divergent evidentiary requirements from FDA pathways, forcing sponsors to stratify submission packages. The country's national pharmaceutical regulator emphasizes long-term cirrhosis prevention outcomes over fibrosis stage regression. Hepatology clinics in Munich and Hamburg concentrate Phase II-III trial enrollment for metabolic fibrosis candidates.
Japan
PMDA harmonization of fibrosis staging protocols enables parallel submission strategies for viral and metabolic etiologies. METI guidelines on pharmaceutical pricing shape reimbursement negotiations for novel antifibrotics. Tokyo and Osaka academic centers anchor regional demand for advanced fibrosis staging and treatment initiation.
China
NMPA regulatory reforms accelerate market access for fibrosis-modifying candidates with validated surrogate endpoints. The country's dual carbon goals indirectly influence hospital procurement through sustainability criteria in pharmaceutical purchasing. Shanghai and Beijing hospital systems expand hepatology capacity to address rising diagnosed NASH populations.
United Kingdom
NICE technology appraisals maintain rigorous cost-effectiveness thresholds for novel antifibrotic reimbursement, constraining rapid uptake. The MHRA post-Brexit regulatory autonomy enables tailored approval pathways for breakthrough therapies. London and Manchester transplant centers anchor demand for decompensated cirrhosis interventions.
Liver Fibrosis Drugs Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in immunology-driven pathways. The vendor base clusters around three strategic archetypes: large-cap biopharmaceuticals with virology infrastructure, mid-cap NASH-focused developers, and metabolic disease specialists with GLP-1 adjacency. Consolidation pressures intensify as integrated delivery networks consolidate formulary control. Dominant competitive moves include strategic partnerships for combination regimen development and capacity expansion in hepatology clinic networks.
Within the large-cap infrastructure tier, Gilead Sciences and Bristol-Myers Squibb exemplify archetypes leveraging established therapeutic area presence into fibrosis-adjacent markets. Madrigal Pharmaceuticals occupies a position representing focused NASH development specialization. These three entities collectively illustrate how geographic origin and corporate structure map onto competitive positioning: California-based Gilead and Madrigal anchor West Coast metabolic disease innovation, while New York-headquartered Bristol-Myers Squibb represents East Coast immunology depth. The competitive dynamic hinges on whether breadth of infrastructure or depth of indication focus commands premium formulary placement.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| Akero Therapeutics |
| Sagimet Biosciences |
| Inventiva Pharma |
| Madrigal Pharmaceuticals |
| Boehringer Ingelheim |
| Novo Nordisk |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient costs for antifibrotic candidates flow through contract manufacturing organizations in India and China before reaching branded pricing tiers in United States hospital systems. This input cost structure stratifies downstream, with innovator biopharmaceuticals commanding premium formulary placement while generic metabolic agents absorb price compression in integrated delivery networks.
Pricing Analysis
Volume concentrates in oral small molecule NASH therapies while margins accrue to infused siRNA platforms requiring dedicated hepatology units. Pricing stratifies across premium, standard, and economy tiers based on mechanism novelty and FDA breakthrough designation status. Cost compression in the oral metabolic agent segment is intensifying because integrated delivery networks mandate step-therapy protocols prioritizing generics. Hospital systems with transplant centers exhibit lowest price sensitivity for decompensation prevention therapies; independent specialty hepatology clinics face highest prior authorization friction.
Supply Chain Analysis
Specialized biochemist availability constraints in Massachusetts and California biotech corridors shape manufacturing capacity for complex antifibrotic synthesis. Supply concentrates in Switzerland and Ireland for finished dose formulation, while API production draws from Indian and Chinese chemical manufacturers. Single-source vulnerability persists for TGF-beta pathway inhibitors dependent on mammalian cell culture substrates. Distribution runs through consolidated specialty pharmacy networks controlled by CVS Caremark and Express Scripts in Texas and Florida markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as integrated delivery networks compress formulary slots and mandate step-therapy protocols that marginalize single-product developers.
For Market Incumbents: Deepen hepatology clinic network partnerships to secure exclusive distribution agreements before pending NASH therapy launches. Expand manufacturing capacity in Switzerland and Ireland to reduce API transit exposure from Asian suppliers. FDA breakthrough therapy designation velocity serves as the critical lever for premium formulary placement against metabolic agent commoditization. For New Entrants and Emerging Players: Machine learning biomarker platforms offer a technology-first wedge into decentralized trial infrastructure currently constrained by biopsy-dependent site activation. Pediatric NASH orphan indications present the most penetrable regulatory pathway with pricing autonomy absent in adult metabolic disease. Target academic medical centers in Boston and San Diego with siRNA infusion unit partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA acceptance of non-invasive biomarkers as pivotal trial endpoints is the leading indicator that development economics will shift toward platform plays with diagnostic adjacencies. Long-term viability favors developers with parallel EMA and PMDA submission capabilities rather than US-only regulatory strategies. Acquisition targets should display validated hepatic stellate cell modulation mechanisms and existing GLP-1 combination study frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Validation Partnership | FDA acceptance of MR elastography endpoints reduces biopsy-dependent trial costs for NASH candidates. |
| Combination Regimen Development | Pairing FXR agonists with GLP-1 modulators creates mechanistic synergy for metabolic fibrosis treatment. |
| Specialty Pharmacy Integration | Exclusive distribution agreements with CVS Caremark secure formulary access in consolidated Texas and Florida systems. |
| Pediatric Orphan Indication Expansion | Rare pediatric disease designations unlock pricing structures for adolescent fibrosis populations managed off-label. |
| Asia-Pacific Regulatory Harmonization | Parallel PMDA and NMPA submissions enable synchronized market entry for viral and metabolic etiology therapies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA breakthrough therapy designations, EMA PRIME scheme submissions, and ClinicalTrials.gov enrollment data provided secondary validation. Bottom-up patient flow modeling and top-down pharmaceutical spending estimates underwent iterative triangulation.
Data-stream reconciliation across prescription audit databases, hospital procurement records, and payer prior authorization patterns informed the analytical framework. Segmentation dimensions included mechanism of action, fibrosis stage, administration route, and regional regulatory cluster. CAGRs derived from epidemiological prevalence projections, treatment rate assumptions, and pricing elasticity parameters across the projection horizon. Forecast inputs incorporated NASH diagnosis expansion rates and CMS reimbursement policy trajectories for advanced fibrosis therapies.
Several conditions sit outside the modeled scope, including spontaneous NASH resolution rates in early-stage populations and regulatory reversal on non-invasive biomarker acceptance. Forecasts reflect documented assumptions on physician screening behavior and prior authorization approval velocity. A small set of named triggers warrants ongoing watch: FDA guidance revisions on histological endpoints, CMS national coverage determinations for antifibrotics, and PMDA-NMPA regulatory divergence on fibrosis staging protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Global Combination Vaccine Market