
 Veterinary Intravenous (IV) Solutions Market | 2026-2036
Veterinary Intravenous (IV) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Intravenous (IV) Solutions Market Analytics
North America is rewriting capacity dynamics for veterinary IV solutions as domestic manufacturers expand sterile fill-finish operations. B. Braun Melsungen AG leverages its hospital-grade manufacturing infrastructure to supply both human and veterinary channels. Fresenius Kabi AG anchors European production while extending distribution into North American veterinary clinics. Zoetis Inc. specializes in species-specific formulations that differentiate its portfolio from generic fluid suppliers.
Veterinary intravenous solutions are sterile, pyrogen-free aqueous preparations containing electrolytes, glucose, or colloids, manufactured via aseptic processing in ISO Class 5 environments and terminally sterilized to guarantee endotoxin levels below veterinary pharmacopeial limits; these products restore circulating volume, correct acid-base disturbances, and provide parenteral nutritional substrates in critically ill animals. Crystalloid solutions dominate procedural volume due to their low cost and broad compatibility across species, while colloid segments command premium positioning in hemorrhagic shock management where oncotic pressure restoration proves clinically decisive. Bag packaging leads in hospital settings for gravity-flow administration, though pre-filled syringes are gaining traction in emergency veterinary protocols requiring rapid bolus delivery.
FDA Center for Veterinary Medicine enforces Current Good Manufacturing Practice for finished pharmaceuticals, compelling sterile injectable facilities to maintain environmental monitoring and batch release documentation that elevates compliance costs for market entrants. The USDA Animal and Plant Health Inspection Service coordinates with state veterinary boards to track adverse events linked to fluid therapy products, creating feedback loops that inform label revisions and contraindication updates. Stakeholders must monitor evolving pharmacovigilance integration between human and veterinary regulatory frameworks, as convergence trends in sterile manufacturing standards reshape facility investment requirements and outsourcing decisions across the supply base.
Market Dynamics
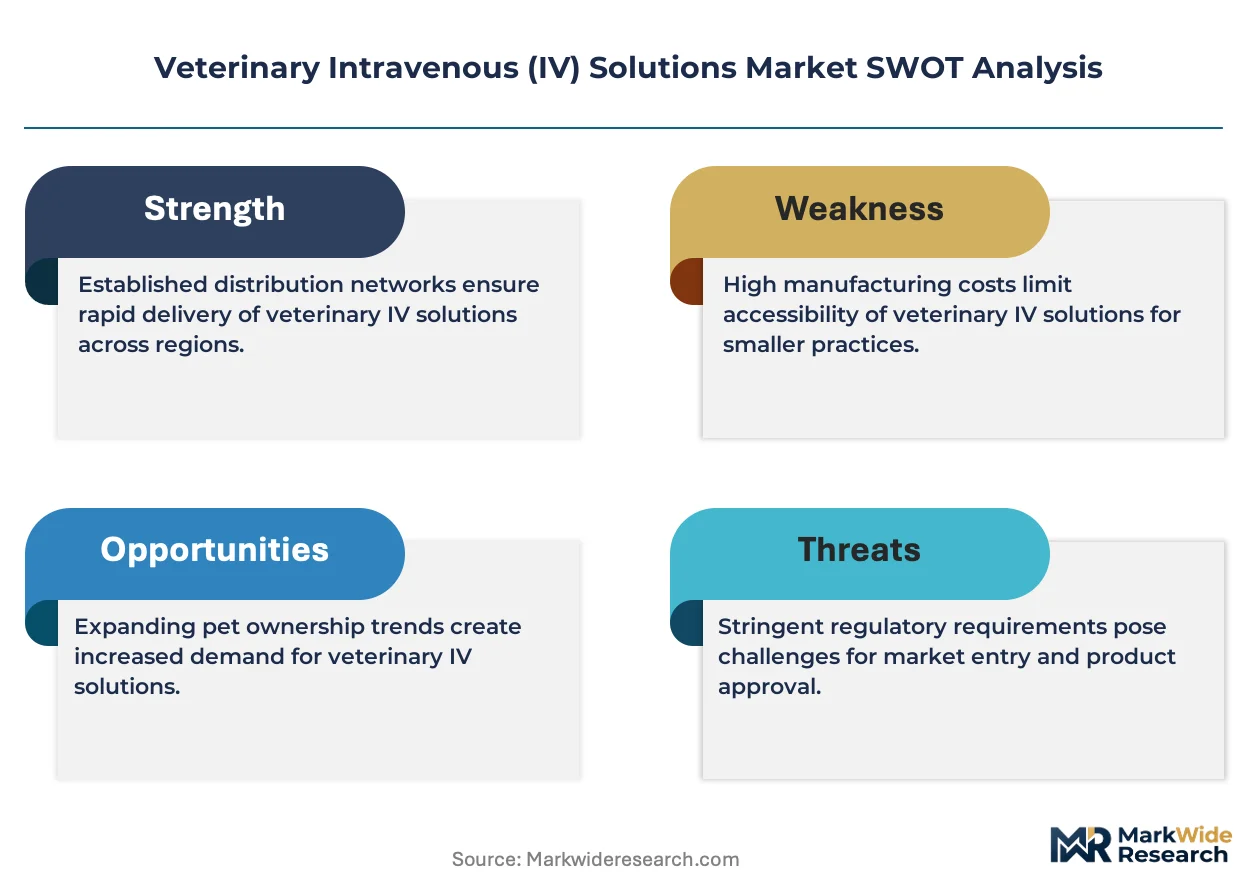
FDA Center for Veterinary Medicine's tightened Current Good Manufacturing Practice enforcement for sterile injectables is compressing supplier margins while elevating facility investment thresholds for new market entrants.
Growth Catalysts
- USDA pharmacovigilance integration:State veterinary boards now feed adverse event data into centralized tracking systems, accelerating label updates and expanding legitimate use cases for fluid therapy products.
- Companion animal critical care expansion:Specialty referral hospitals in the United States are standardizing perioperative fluid protocols, creating procedural pull-through for balanced crystalloid and colloid formulations.
- Aseptic processing automation:Closed-system filling technologies are reducing contamination risk in ISO Class 5 environments, enabling longer production runs and improved batch consistency for sterile solutions.
Market Restraints
- Pyrogen-free water scarcity:Pharmaceutical-grade water purification capacity concentrates among legacy manufacturers, creating input bottlenecks for new sterile fill-finish entrants.
- Terminal sterilization capex:Steam-autoclave and irradiation infrastructure requires eight-figure facility investments, freezing out regional compounders from commercial-scale veterinary production.
- Colloid substitution pressure:Synthetic hydroxyethyl starches face clinical scrutiny in human medicine, dampening veterinary adoption despite distinct species pharmacokinetics.
Strategic Opportunities
- Pre-filled syringe emergency protocols:Veterinary trauma centers are piloting ready-to-administer bolus formats, bypassing gravity-flow setup delays in hemorrhagic shock cases.
- USDA APHIS export harmonization:Mutual recognition agreements with Health Canada and TGA Australia are streamlining cross-border registration for sterile injectable manufacturers.
- Species-specific electrolyte profiling:Formulations calibrated to feline, equine, and exotic metabolic parameters command premium positioning against generic lactated Ringer's solutions.
Industry Challenges
- Qualified personnel scarcity:Aseptic operators with combined GMP and veterinary pharmacology expertise command salary premiums that inflate per-unit labor costs.
- Environmental monitoring compliance:Continuous viable and non-viable particle surveillance generates terabytes of batch release documentation, straining quality assurance bandwidth.
- Legacy ERP integration:Track-and-trace serialization mandates require retrofitting decades-old manufacturing execution systems with real-time data capture capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Intravenous (IV) Solutions Market |
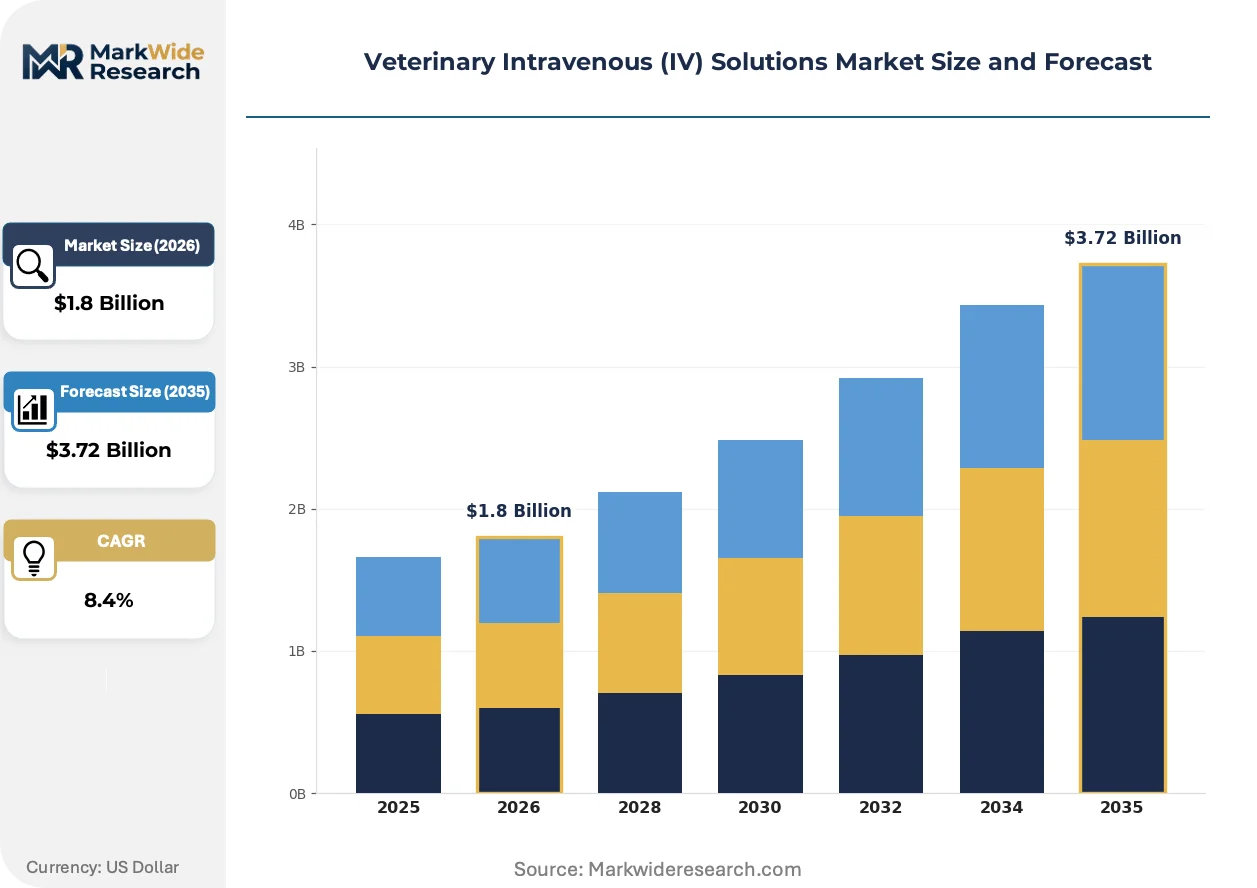
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalloids, Colloids, Hypertonic Saline, Dextrose Solutions End User: Animal Hospitals, Veterinary Clinics, Research Laboratories, Pet Shelters Application: Fluid Replacement, Electrolyte Balance, Nutritional Support, Resuscitation Packaging Type: Vials, Bags, Bottles, Pre-filled Syringes |
| Companies Covered | Elanco Animal Health Incorporated, B. Braun Melsungen AG, Zoetis Inc., Dechra Pharmaceuticals PLC, Virbac SA, Merck & Co. Inc., Fresenius Kabi AG, Vetoquinol SA, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Intravenous (IV) Solutions Market Evolving Landscape
Fluid therapy administration is fragmenting across delivery modalities as emergency veterinary protocols demand speed incompatible with traditional gravity-flow bag systems.
Closed-system transfer devices for sterile solution handling are hybridizing aseptic technique with point-of-care efficiency. Emergency and critical care specialists in university teaching hospitals are adopting these devices for rapid fluid resuscitation. The technology is hybridizing infection control protocols with workflow compression, collapsing the time between pharmacy dispensing and patient administration.
EMA's revised Guidelines on Sterile Manufacture are mandating enhanced barrier isolation systems for all new aseptic processing lines. European veterinary solution manufacturers face facility retrofit timelines measured in years rather than months. Smaller national markets with limited domestic fill-finish capacity are consolidating procurement around distributors with validated cold-chain logistics.
Consolidated buying groups representing multi-site specialty hospital networks are unbundling fluid therapy purchasing from equipment and service contracts. Independent veterinary practices are losing volume leverage as these groups centralize procurement through sole-source distribution agreements. The shift is most pronounced in the United States, where corporate practice ownership has concentrated demand among three national buying cooperatives.
Veterinary Intravenous (IV) Solutions Market Segmentation
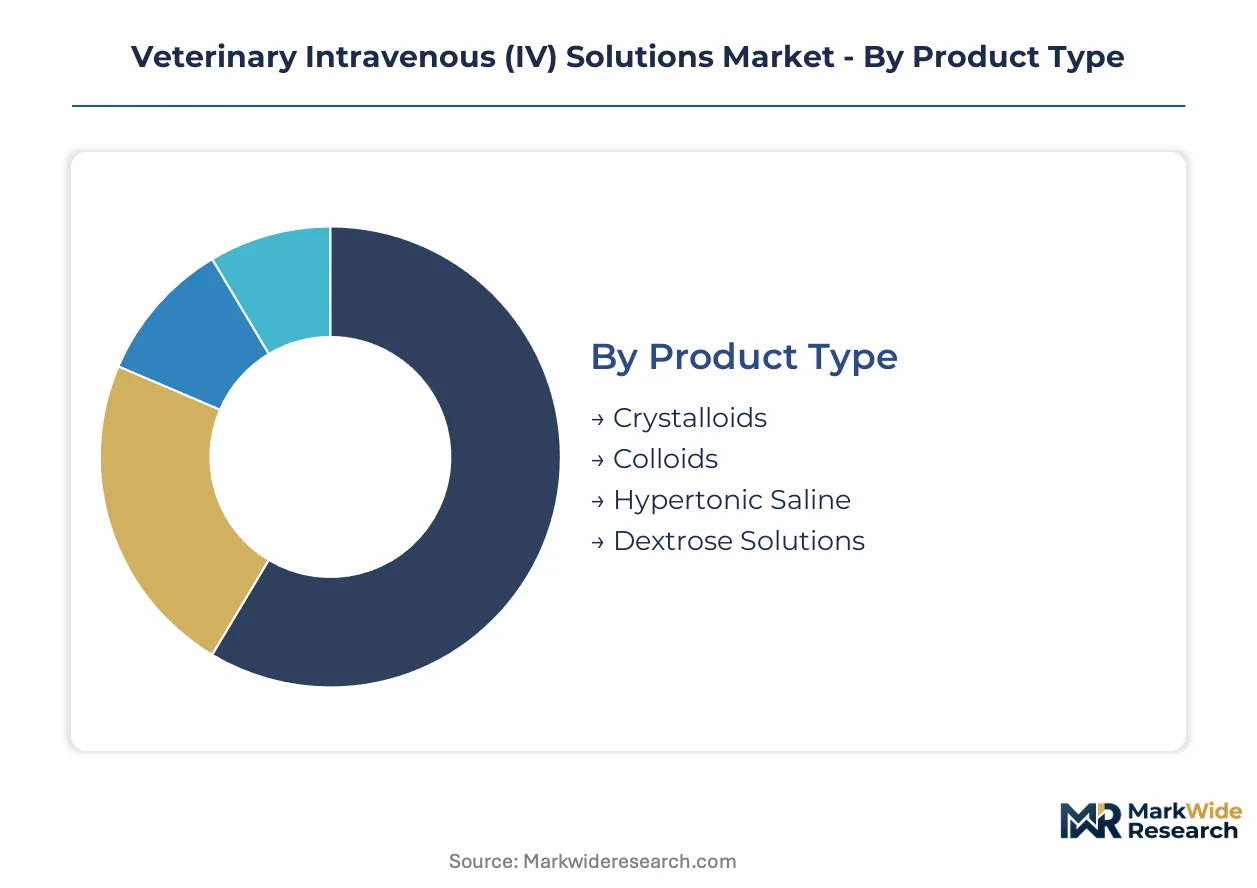
Veterinary IV solution purchasing patterns fragment sharply across clinical settings, with after-sales service intensity varying from emergency 24/7 support for specialty hospitals to minimal technical assistance for research bulk buyers. Product selection criteria diverge by end-use sophistication, driving manufacturers to tier their formulation portfolios and field service capabilities accordingly.
Product Type:
After-sales service intensity peaks with colloid formulations requiring clinical training support, while crystalloid commoditization pushes manufacturers toward volume logistics rather than technical field presence.
- Crystalloids:These electrolyte-based aqueous solutions—lactated Ringer's, normal saline, and balanced isotonic formulations—dominate procedural volume due to broad species compatibility and gravity-flow administration simplicity. Demand concentrates in high-throughput companion animal hospitals across the United States, where perioperative fluid protocols standardize around low-cost, high-turnover bag formats that minimize pharmacy labor.
- Colloids:Synthetic hydroxyethyl starches and natural albumin preparations restore oncotic pressure in hemorrhagic shock through high molecular weight plasma expansion. Specialty referral hospitals in North America command premium positioning here, though clinical scrutiny of human safety data dampens veterinary adoption velocity despite distinct species pharmacokinetics.
- Hypertonic Saline:Concentrated sodium chloride solutions enable rapid small-volume resuscitation in field emergency settings where transport weight constraints apply.
- Dextrose Solutions:Parenteral glucose preparations support hypoglycemic crisis management and nutritional substrate delivery in neonatal and critical care cases.
Crystalloids hold the largest share; momentum sits with colloids as trauma center capabilities expand.
End User:
Customer sophistication tiers separate institutional procurement discipline from individual practice purchasing patterns, reshaping distribution channel economics.
- Animal Hospitals:Multi-specialty institutions with 24-hour emergency services maintain the most complex fluid therapy protocols, requiring formulary breadth from crystalloid maintenance to colloid resuscitation and parenteral nutrition. These facilities in the United States drive premium solution consumption through standardized perioperative and critical care pathways.
- Veterinary Clinics:General practice settings concentrate procedural volume in routine surgery and outpatient illness management, favoring economical crystalloid bag formats over advanced colloid or syringe-based emergency products.
- Research Laboratories:Controlled study environments demand batch-traceable, endotoxin-certified solutions with documentation packages supporting GLP compliance and protocol reproducibility.
- Pet Shelters:High-volume, resource-constrained operations prioritize lowest-unit-cost fluid options for basic dehydration and supportive care in population health management.
Animal hospitals generate the highest revenue per account; veterinary clinics represent the deepest volume pool.
Application:
Clinical indication severity determines formulation complexity and administration urgency, segmenting demand by therapeutic intensity rather than species alone.
- Fluid Replacement:Volume restoration for dehydration, hemorrhage, or surgical losses constitutes the foundational use case across all practice types, with crystalloid selection driven by acid-base status and electrolyte deficit profiling.
- Electrolyte Balance:Correcting sodium, potassium, chloride, and calcium disturbances requires precise formulation matching to metabolic panel results, particularly in feline patients with unique renal handling characteristics.
- Nutritional Support:Parenteral glucose and amino acid solutions sustain patients with gastrointestinal dysfunction or post-operative ileus, demanding pharmacy compounding integration or pre-mixed specialty bags.
- Resuscitation:Emergency shock reversal protocols favor rapid bolus delivery formats, with pre-filled syringes gaining traction in trauma centers for hemorrhagic and septic shock management.
Fluid replacement anchors volume; resuscitation applications are climbing fastest as emergency specialty credentialing expands.
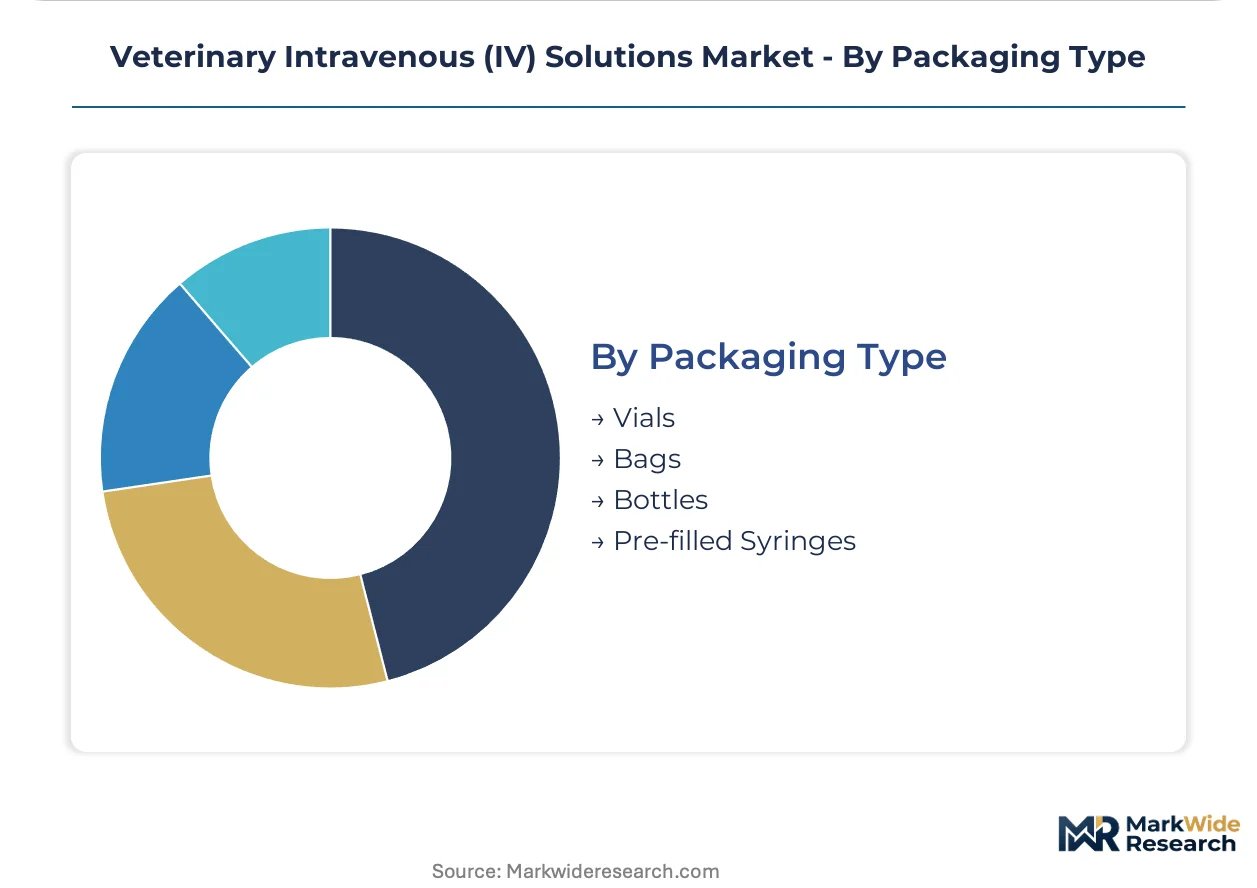
Packaging Type:
Administration workflow constraints and contamination risk tolerance shape container selection, with point-of-care speed requirements disrupting traditional pharmacy-centric distribution.
- Bags:Flexible plastic containers for gravity-flow infusion dominate hospital pharmacy inventories, offering cost efficiency and compatibility with standard IV administration sets across extended dwell times.
- Pre-filled Syringes:Ready-to-administer bolus formats compress time-to-treatment in emergency protocols, with veterinary trauma centers piloting these devices for hemorrhagic shock resuscitation where seconds alter survival curves.
- Vials:Multi-dose glass containers support pharmacy compounding and research aliquoting with preserved sterility across multiple withdrawals.
- Bottles:Larger-volume rigid containers serve bulk fluid needs in shelter and agricultural settings where single-patient precision matters less than cost minimization.
Bags maintain institutional dominance; pre-filled syringes are gaining share fastest in emergency specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine regulations on sterile injectable manufacturing have concentrated premium production capacity in the United States, while EMA guidelines reshape European facility investments and Asian markets develop domestic fill-finish capabilities.
United States
Specialty referral hospitals in metropolitan corridors drive consumption of balanced crystalloid and colloid formulations for perioperative and critical care protocols. FDA enforcement of Current Good Manufacturing Practice elevates compliance costs for sterile fill-finish operations, compressing margins for domestic manufacturers. The Research Triangle Park cluster in North Carolina anchors contract manufacturing organizations serving both human and veterinary sterile injectable markets.
Germany
EMA's revised Guidelines on Sterile Manufacture mandate enhanced barrier isolation systems for new aseptic processing lines, extending facility retrofit timelines. B. Braun Melsungen AG leverages hospital-grade manufacturing infrastructure to supply veterinary channels alongside human healthcare. The Melsungen industrial corridor concentrates legacy sterile fill-finish capacity with integrated pharmaceutical-grade water purification systems.
China
NMPA oversight of veterinary drug manufacturing is converging toward international GMP standards, compelling domestic producers to upgrade environmental monitoring and batch documentation systems. Provincial veterinary medicine regulators in Jiangsu and Zhejiang provinces coordinate facility inspections with centralized pharmacovigilance reporting. The Yangtze River Delta cluster is attracting contract manufacturing investment for sterile injectable export production.
United Kingdom
Veterinary specialty hospitals in Greater London and the Southeast standardize fluid therapy protocols for emergency and critical care cases, creating procedural demand for premium solution formats. The Veterinary Medicines Directorate aligns batch release documentation requirements with EMA frameworks post-Brexit, maintaining market access continuity. Cambridge-Oxford corridor research institutions drive demand for GLP-compliant, batch-traceable solutions in preclinical studies.
Japan
PMDA pharmacovigilance integration with agricultural ministry oversight creates dual regulatory pathways for veterinary sterile injectables. Metropolitan Tokyo and Osaka veterinary medical centers pilot pre-filled syringe formats for emergency trauma protocols. The Kansai industrial belt maintains concentrated aseptic processing capacity serving both domestic consumption and Asia-Pacific export markets.
Veterinary Intravenous (IV) Solutions Market Competitive Landscape
Diversified healthcare conglomerates and veterinary-specialized pharmaceutical companies split the market between scale-driven manufacturing and species-specific formulation expertise. The vendor base concentrates around three strategic archetypes: human-healthcare sterile injectable manufacturers extending into veterinary channels, dedicated animal health companies with species-calibrated portfolios, and diversified pharmaceutical conglomerates leveraging cross-divisional manufacturing assets. Dominant competitive moves include sterile fill-finish capacity expansion in ISO Class 5 environments and strategic partnerships with specialty veterinary distribution networks.
Within the human-healthcare extension archetype, B. Braun Melsungen AG and Fresenius Kabi AG occupy positions anchored by hospital-grade manufacturing infrastructure that serves dual-channel markets. Zoetis Inc. exemplifies the veterinary-specialized tier, representing species-specific formulation differentiation against generic fluid suppliers. These three entities illustrate how competitive positioning stratifies between scale-driven sterile manufacturing and targeted clinical application expertise.
| Leading Market Players |
|---|
| Elanco Animal Health Incorporated |
| B. Braun Melsungen AG |
| Zoetis Inc. |
| Dechra Pharmaceuticals PLC |
| Virbac SA |
| Merck & Co. Inc. |
| Fresenius Kabi AG |
| Vetoquinol SA |
| Baxter International Inc. |
| Others |
Value Network & Pricing Analysis
The Research Triangle Park cluster in North Carolina concentrates sterile fill-finish capacity for veterinary IV solutions, translating upstream manufacturing dominance into pricing leverage for domestic suppliers serving specialty referral hospitals. FDA enforcement of Current Good Manufacturing Practice elevates compliance costs that filter downstream as premium positioning for batch-certified products.
Pricing Analysis
Geographic price spreads between North American and Asian-sourced veterinary IV solutions reflect differential regulatory compliance burdens and cold-chain logistics costs. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service intensity, with colloid formulations commanding substantial premiums over crystalloid commodities. Cost compression in economy-tier crystalloid bags is intensifying because consolidated buying groups centralize procurement through sole-source distribution agreements. Independent veterinary practices exhibit highest price sensitivity, while multi-specialty animal hospitals prioritize formulary breadth over unit cost.
Supply Chain Analysis
Pharmaceutical-grade water purification feedstock draws from concentrated capacity in the United States, Germany, and Japan, where legacy manufacturers maintain integrated sterile processing infrastructure. Sodium chloride, glucose, and hydroxyethyl starch raw materials hinge on chemical processing clusters with established veterinary pharmacopeial certification. Single-source vulnerability concentrates in pyrogen-free water systems, where regional compounders lack terminal sterilization capability. Distribution runs through specialty veterinary distributors with validated cold-chain logistics, bypassing general medical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as companion animal critical care expansion drives procedural pull-through for premium fluid therapy protocols.
For Market Incumbents: Pre-empt colloid substitution pressure by accelerating species-specific electrolyte profiling investments that differentiate portfolios from generic lactated Ringer's suppliers. Consolidate sterile fill-finish capacity in ISO Class 5 environments to capture volume leverage from corporate practice ownership concentration. Channel control through exclusive distribution partnerships with national buying cooperatives represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in pre-filled syringe emergency protocols, where veterinary trauma centers pilot ready-to-administer bolus formats bypassing gravity-flow setup delays. Target research laboratories with GLP-compliant, batch-traceable solutions supporting protocol reproducibility requirements underserved by commodity suppliers. Go-to-market execution should emphasize documentation packages and endotoxin certification rather than price competition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance cost escalation compresses margins for sub-scale manufacturers and rewards integrated sterile processing assets. Acquisition targets should display captive pharmaceutical-grade water purification, validated aseptic processing lines, and established veterinary pharmacovigilance reporting infrastructure. The signal to watch is USDA APHIS mutual recognition agreement progress with Health Canada and TGA Australia, which would unlock cross-border registration economies for positioned suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Fill-Finish Capacity Expansion | ISO Class 5 environment investments capture volume from FDA compliance-driven supplier consolidation. |
| Species-Specific Formulation Development | Feline, equine, and exotic metabolic calibrations command premium positioning against generic solutions. |
| Pre-Filled Syringe Format Launch | Ready-to-administer bolus designs compress time-to-treatment in hemorrhagic shock protocols. |
| Backward Integration into Water Purification | Captive pyrogen-free water systems eliminate input bottlenecks constraining new market entrants. |
| Specialty Distribution Partnership | Exclusive agreements with national buying cooperatives secure volume leverage from corporate practice consolidation. |
Research Methodology
A spread of perspectives from sterile manufacturing executives, veterinary critical care specialists, GPO contracts managers, and regulatory affairs leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA Center for Veterinary Medicine filings, USDA APHIS pharmacovigilance databases, EMA sterile manufacture guidelines, and hospital procurement contract disclosures. Bottom-up facility capacity modeling and top-down demand segmentation triangulated volume estimates across the projection horizon.
Demand-supply-balance framing anchored the analytical approach, with crystalloid versus colloid product mix, companion animal versus livestock end-use splits, and bag versus pre-filled syringe packaging formats serving as core segmentation dimensions. CAGRs derived from trajectory fitting to historical procedural volume data, adjusted for specialty hospital credentialing expansion and aseptic processing automation adoption curves. Forecast inputs incorporated FDA enforcement intensity indices and corporate practice ownership concentration metrics.
Macroeconomic conditions sit as an overlay; deviation in veterinary service expenditure sensitivity, pet insurance penetration rates, or sterile manufacturing input costs would shift the trajectory. Cross-checking against American Animal Hospital Association procedural survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Light Therapy Devices Market
Veterinary
Veterinary Tables Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Consumables Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Global Animal Vaccine Market
Veterinary
Global Animal Model Market
Veterinary
Bovine Collagen Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Global Veterinary Telehealth Market