
 Japan Insulin Infusion Pump Market | 2026-2036
Japan Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Insulin Infusion Pump Market Insights
Certified diabetes educator shortages across Japan's prefectural health systems is redrawing competitive positioning for pump manufacturers. Medtronic plc leverages its long-standing reimbursement relationships with Japan's universal health coverage framework. Insulet Corporation anchors its growth strategy through Omnipod's tubeless design, which resonates with Japan's aging patient demographic seeking discretion. Tandem Diabetes Care, Inc. competes by emphasizing its Control-IQ algorithm integration with Dexcom continuous glucose monitors.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin subcutaneously through a cannula at basal rates and bolus doses calibrated to carbohydrate intake and blood glucose levels. These systems incorporate microprocessor-controlled piston or peristaltic drive mechanisms with accuracy thresholds typically within 5% of programmed delivery, serving the therapeutic purpose of glycemic management for insulin-dependent diabetes patients. Traditional pumps retain dominant installed base across Japanese hospital procurement channels, while patch pumps represent the fastest-growing form factor as patients migrate toward disposable, tube-free systems that eliminate daily set-change routines. Closed-loop technology commands the highest margin pool within the technology dimension, though Bluetooth-enabled pumps currently occupy the broadest reimbursement-accessible segment.
Japan's PMDA enforces rigorous electrical safety and software validation standards under the Pharmaceutical and Medical Device Act, extending approval timelines but ensuring clinical reliability benchmarks that foreign entrants must satisfy. METI's medical device industry strategy promotes domestic manufacturing of advanced diabetes technologies, creating preferential procurement pathways for companies establishing Japanese production facilities. JIS standards for electromagnetic compatibility constrain design architectures, particularly for wireless communication modules in connected pump ecosystems. Stakeholders must monitor PMDA's evolving software-as-a-medical-device guidance, which will determine whether algorithm updates require full re-approval or streamlined notification pathways.
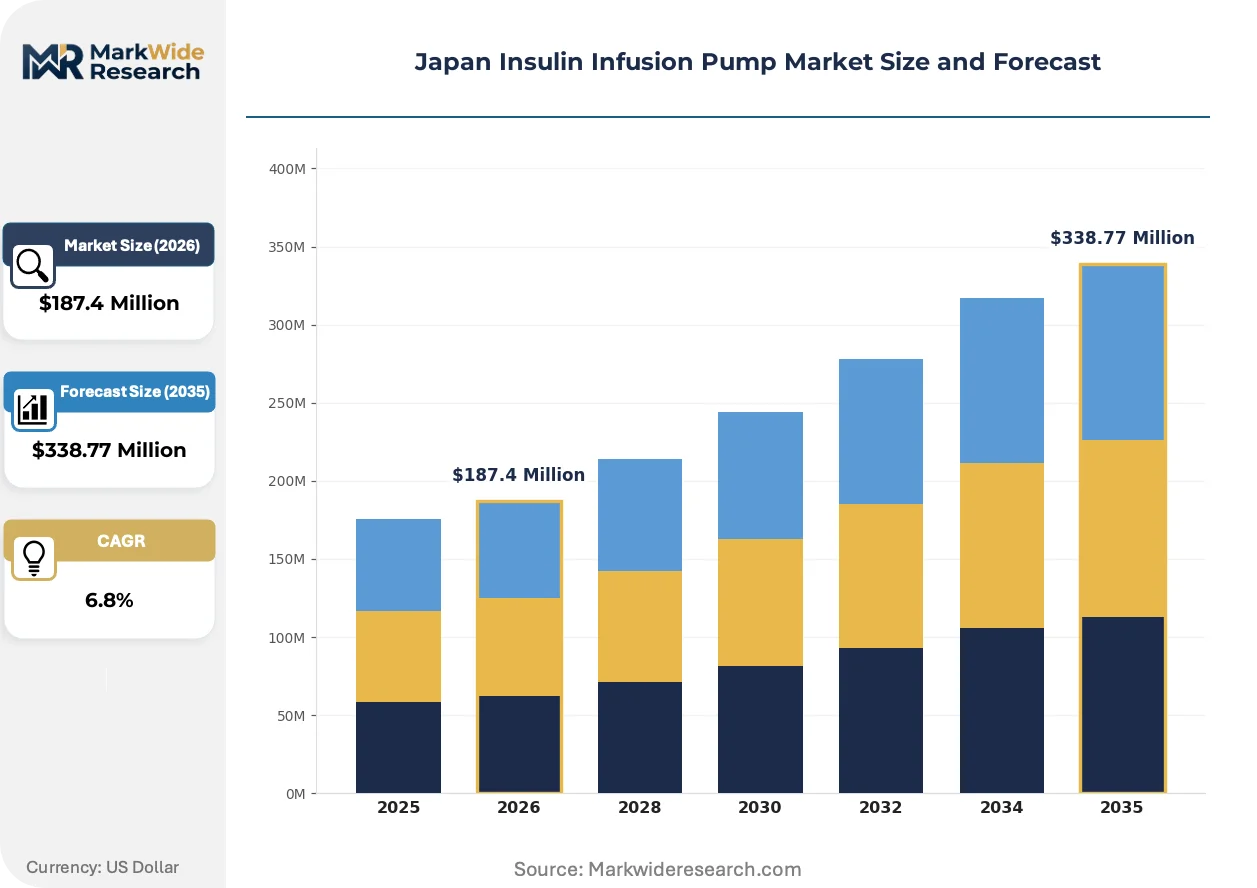
Market Dynamics
PMDA's compressed approval pathway for closed-loop artificial pancreas systems is redrawing competitive entry timelines while METI's domestic manufacturing incentives reshape supply-side investment patterns across Japan's prefectural hospital networks.
Growth Catalysts
- Tubeless patch pump technology:Disposable form factors eliminate daily set-change routines for elderly Type 1 patients managing therapy at home.
- METI medical device industry strategy:Preferential procurement pathways reward manufacturers establishing Japanese production facilities with faster hospital access.
- Homecare reimbursement expansion:Japan's universal health coverage framework now covers continuous subcutaneous insulin infusion for outpatient settings.
Market Restraints
- Certified diabetes educator scarcity:Prefectural health systems face acute shortages of trained personnel to support pump initiation and troubleshooting.
- PMDA software validation requirements:Rigorous electrical safety and electromagnetic compatibility testing under JIS standards extends development timelines.
- Closed-loop system complexity:Algorithm integration with continuous glucose monitors demands specialized technical support infrastructure.
Strategic Opportunities
- Osaka specialty diabetes clinics:Concentrated patient volumes in Kansai region's referral centers create bundled service contract potential.
- Bluetooth-enabled pump connectivity:Wireless data transmission to smartphone applications enables remote monitoring revenue streams.
- Software-as-a-medical-device guidance evolution:Streamlined notification pathways for algorithm updates would reduce regulatory maintenance burdens.
Industry Challenges
- Integration complexity with legacy hospital IT:Electronic health record compatibility varies across Tokyo metropolitan networks.
- Algorithm update re-approval uncertainty:PMDA has not clarified whether machine learning model improvements trigger full resubmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Insulin Infusion Pump Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pumps, Patch Pumps, Insulin Pens, Smart Pumps Form Factor: Wearable, Handheld, Portable, Integrated Systems End User: Hospitals, Clinics, Homecare, Telehealth Providers Technology: Bluetooth, USB-C, Wireless, Closed-Loop Systems |
| Companies Covered | Medtronic plc, Insulet Corporation, Roche Diabetes Care Japan Co., Ltd., Tandem Diabetes Care, Inc., Ypsomed AG, SOOIL Development Co., Ltd., Nipro Corporation, Terumo Corporation, Abbott Japan LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Insulin Infusion Pump Market Trends and Innovations
Closed-loop automation and disposable form factors are compressing traditional pump architectures while regulatory clarity around software updates determines competitive velocity for algorithm-driven systems.
Automated insulin delivery systems integrating Control-IQ algorithms with Dexcom continuous glucose monitors are displacing conventional open-loop pumps in tertiary hospital procurement channels. Endocrinology departments at Tokyo's metropolitan networks are prioritizing these configurations for newly diagnosed Type 1 patients. The technology is displacing manual bolus calculation workflows and reducing hypoglycemic event rates in real-world settings.
PMDA's evolving guidance on software-as-a-medical-device classifications will determine whether closed-loop algorithm updates require full re-approval or streamlined notification pathways. Manufacturers face uncertainty around regulatory maintenance costs for machine learning model improvements. The ambiguity most affects Bluetooth-enabled pump ecosystems where over-the-air updates are technically feasible but legally undefined.
Hospital procurement committees are consolidating vendor relationships around single-source service contracts that bundle device supply with educator training and remote monitoring support. Tokyo's metropolitan networks are leading this consolidation, replacing fragmented device-only purchasing. The shift pressures smaller prefectural hospitals to align with dominant supplier ecosystems or absorb higher total cost of ownership.
Japan Insulin Infusion Pump Market Segmentation
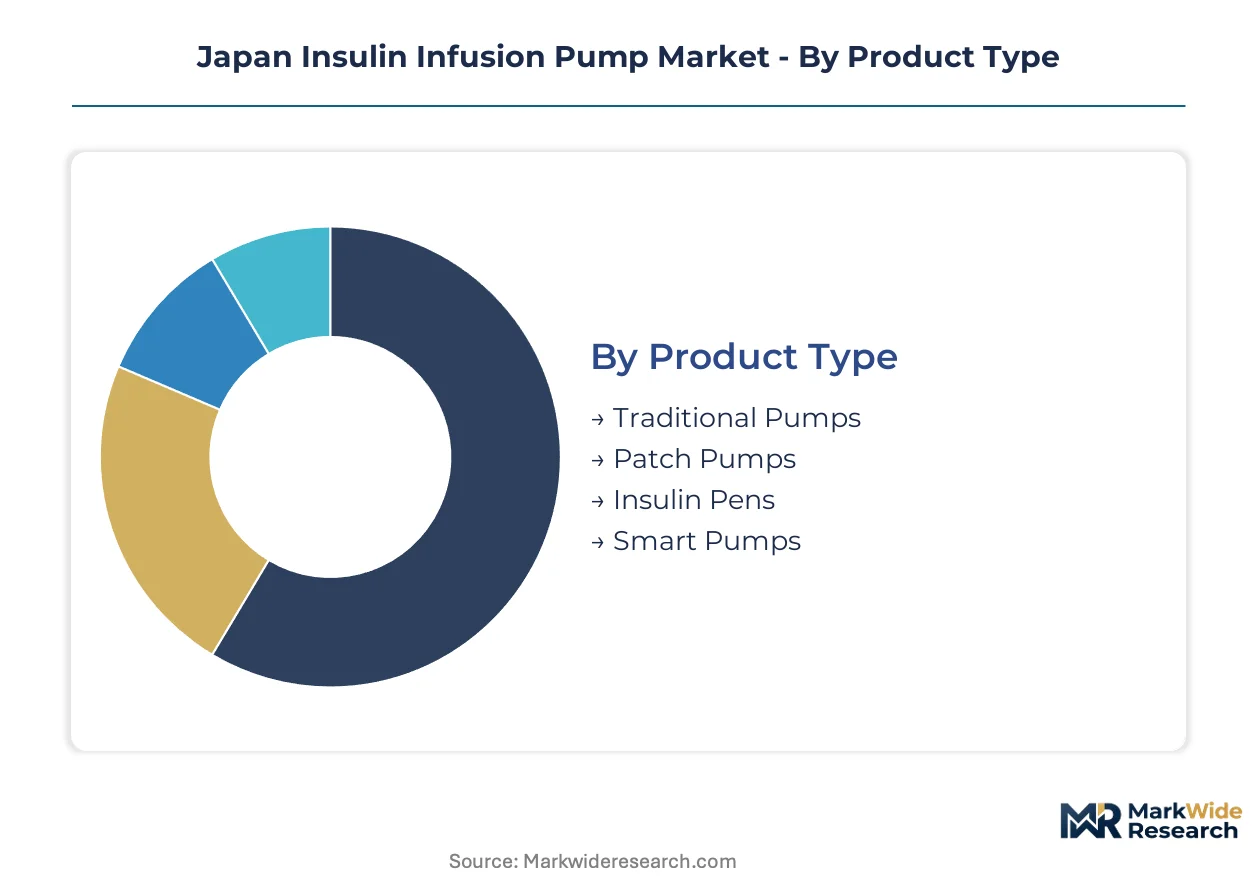
Segmentation in Japan's insulin infusion pump market reveals distinct procurement pathways across hospital networks, homecare channels, and emerging telehealth platforms. Each dimension exposes different margin structures, regulatory requirements, and patient demographic alignments that manufacturers must navigate.
Product Type:
Traditional pumps flow through Tokyo's metropolitan hospital procurement committees, while patch pumps and disposable systems concentrate in Osaka's specialty diabetes clinics and direct-to-patient homecare channels.
- Traditional Pumps:Microprocessor-controlled piston or peristaltic drive mechanisms deliver basal rates and bolus doses with accuracy thresholds within 5% of programmed delivery. Demand concentrates in Tokyo's metropolitan hospital networks where endocrinology departments prioritize reliability for newly diagnosed Type 1 patients.
- Patch Pumps:Tubeless disposable form factors eliminate daily set-change routines through adhesive-mounted cannula systems. Osaka's specialty diabetes clinics and elderly homecare patients in Kansai region drive adoption for discretion and simplified therapy management.
- Insulin Pens:Manual injection devices for multiple daily injection regimens serve as pump alternatives or backup systems.
- Smart Pumps:Connected devices with smartphone integration and data logging capabilities target tech-enabled patient segments.
Traditional pumps dominate installed base across hospital procurement channels. Patch pumps represent where expansion concentrates among Japan's aging Type 1 demographic seeking home-based therapy.
Form Factor:
Cost tier stratification separates premium integrated systems from economy handheld alternatives, with wearable configurations commanding reimbursement premiums under Japan's universal health coverage framework.
- Wearable:Body-adhered devices with extended wear durations of 2-3 days reduce interruption to daily activities. Tokyo's working-age Type 1 patients and active elderly populations in metropolitan prefectures prioritize form factor discretion.
- Handheld:Compact devices requiring manual carrying and interaction serve budget-conscious segments and backup therapy scenarios.
- Portable:Belt-clipped or pocket-carried pumps with tubing connections retain presence in hospital-based continuous subcutaneous insulin infusion protocols.
- Integrated Systems:Closed-loop configurations combining pump, continuous glucose monitor, and algorithm controller in unified hardware. PMDA's compressed approval pathway for artificial pancreas systems accelerates hospital procurement of these premium-tier systems.
Wearable configurations gain share fastest among outpatient homecare expansions. Integrated systems capture margin concentration despite narrower reimbursement access.
End User:
Customer type determines service bundling requirements, with hospitals demanding educator training contracts and homecare channels prioritizing remote monitoring infrastructure.
- Hospitals:Tertiary care centers and metropolitan networks require comprehensive service contracts bundling device supply with certified diabetes educator training. Tokyo's prefectural hospital systems consolidate vendor relationships around single-source agreements.
- Clinics:Specialty diabetes centers in Osaka and regional referral hubs concentrate patient volumes for pump initiation and algorithm optimization.
- Homecare:Outpatient settings now qualify for continuous subcutaneous insulin infusion reimbursement under universal health coverage expansion.
- Telehealth Providers:Remote monitoring platforms integrating pump data transmission with virtual endocrinology consultations.
Hospitals anchor device revenue through bundled procurement. Homecare is where volume expansion accelerates following reimbursement policy shifts.
Technology:
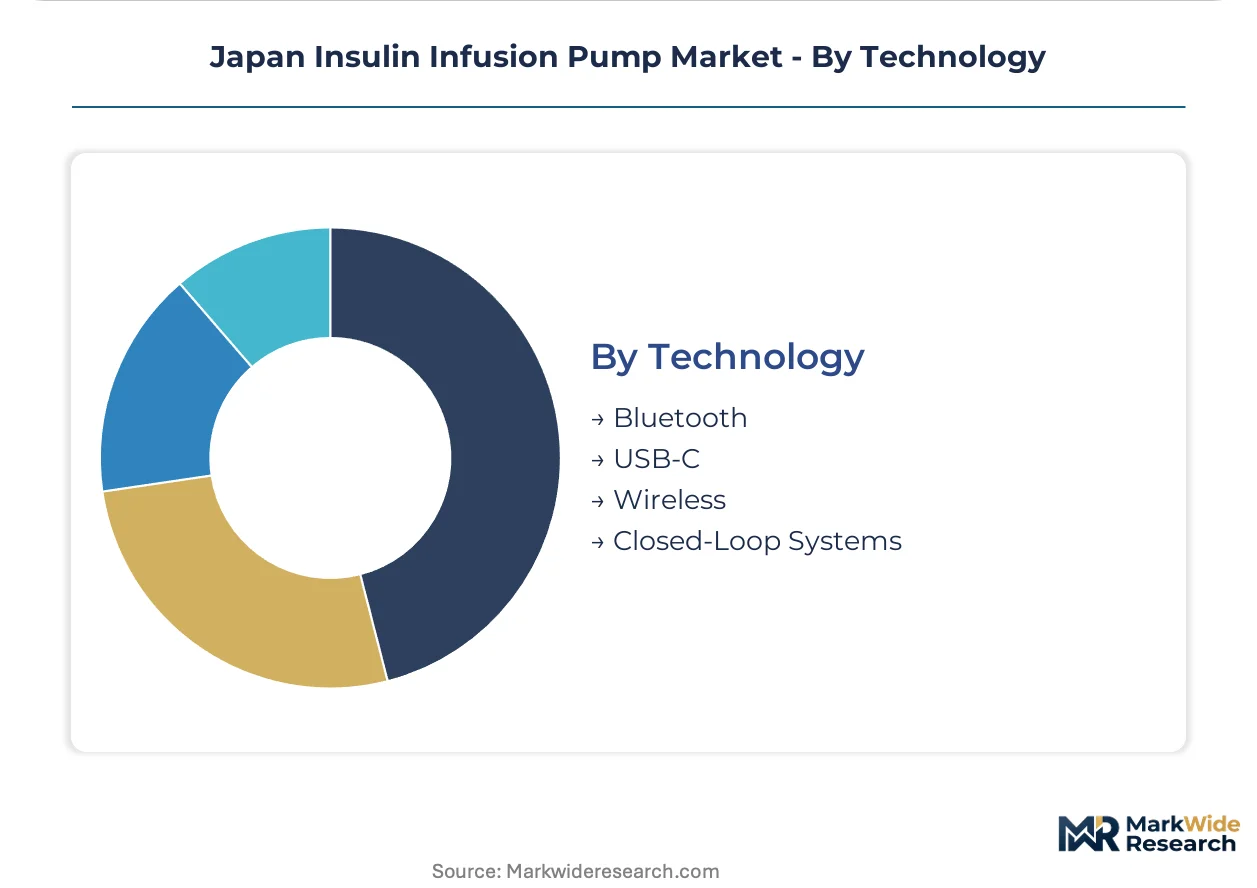
Maturity stage separates established connectivity protocols from emerging closed-loop automation, with Bluetooth-enabled systems occupying the broadest reimbursement-accessible segment while algorithm-driven platforms await regulatory clarity.
- Bluetooth:Wireless data transmission to smartphone applications enables remote monitoring and caregiver oversight. PMDA's software-as-a-medical-device guidance uncertainty constrains over-the-air update capabilities despite technical feasibility.
- USB-C:Wired connectivity for data download and charging retains utility in hospital IT environments with restricted wireless protocols.
- Wireless:Proprietary radio frequency protocols for pump-to-monitor communication in closed-loop ecosystems.
- Closed-Loop Systems:Automated insulin delivery integrating continuous glucose monitor data with predictive algorithms for basal rate adjustment. METI's domestic manufacturing incentives favor companies establishing Japanese production facilities for these advanced systems.
Bluetooth-enabled pumps dominate current installed base through reimbursement accessibility. Closed-loop systems concentrate expansion potential pending PMDA algorithm update pathway clarification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's insulin infusion pump consumption patterns diverge sharply from Western markets, with homecare channels absorbing volume growth while hospital procurement concentrates in metropolitan tertiary centers rather than distributed community settings.
Kanto/Tokyo
Tokyo's metropolitan hospital networks anchor institutional pump procurement through consolidated vendor relationships bundling device supply with educator training. PMDA's compressed approval pathway for closed-loop artificial pancreas systems accelerates adoption at Keio University Hospital and St. Luke's International Hospital. The concentration of endocrinology departments in Tokyo's 23 wards creates single-source service contract dominance.
Kansai/Osaka
Osaka's specialty diabetes clinics drive patch pump adoption among elderly Type 1 patients seeking discretion in homecare settings. METI's medical device industry strategy rewards manufacturers establishing Japanese production facilities with preferential procurement access to Kansai region referral centers. Osaka University Hospital and affiliated clinics concentrate algorithm optimization services for closed-loop system initiations.
Chubu/Nagoya
Nagoya's manufacturing corridor supplies precision components for pump drive mechanisms to domestic and foreign device makers. Aichi Prefecture's industrial cluster hosts contract manufacturers serving PMDA-compliant production requirements. Nagoya University Hospital participates in clinical validation trials for Bluetooth-enabled pump connectivity systems.
Kyushu
Fukuoka's emerging medical device hub attracts regional headquarters for pump manufacturers seeking proximity to Southeast Asian export markets. Kumamoto and Kagoshima prefectures face acute certified diabetes educator shortages that constrain pump initiation capacity. Local health systems rely on telehealth bridges to Tokyo and Osaka specialists for troubleshooting support.
Hokkaido
Hokkaido's dispersed rural population creates unique last-mile distribution challenges for pump supply and consumables replenishment. Sapporo Medical University anchors northern Japan's tertiary diabetes care, drawing patients from remote prefectures for pump initiation. Cold climate conditions influence wearable device battery performance and adhesive reliability in winter months.
Japan Insulin Infusion Pump Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's insulin infusion pump market, with reimbursement relationships and regulatory navigation capabilities separating the tiers. Hospital procurement committees consolidate vendor relationships around bundled service contracts that combine device supply with educator training infrastructure. Two strategic archetypes dominate: multinational device manufacturers leveraging global algorithm portfolios, and domestic distributors with deep prefectural health system relationships. Competitive moves center on METI domestic manufacturing qualification and PMDA closed-loop approval pathway navigation.
Among multinational manufacturers, Medtronic plc and Insulet Corporation exemplify contrasting market entry strategies, with the former anchoring institutional procurement through long-standing reimbursement relationships and the latter targeting homecare expansion through tubeless form factors. Tandem Diabetes Care, Inc. occupies a position emphasizing algorithm integration with continuous glucose monitoring ecosystems. Domestic players including Terumo Corporation and Nipro Corporation represent the specialist tier, leveraging manufacturing proximity and JIS standards compliance for hospital procurement access.
| Leading Market Players |
|---|
| Medtronic plc |
| Insulet Corporation |
| Roche Diabetes Care Japan Co., Ltd. |
| Tandem Diabetes Care, Inc. |
| Ypsomed AG |
| SOOIL Development Co., Ltd. |
| Nipro Corporation |
| Terumo Corporation |
| Abbott Japan LLC |
| Others |
Pricing and Supply Chain Analysis
Seventy-five-day PMDA software validation timelines compress inventory turns for pump manufacturers while concentrating pricing power among established players with pre-cleared algorithm portfolios. Japan's universal health coverage reimbursement bands amplify this dynamic by rewarding domestic production with faster hospital procurement access.
Pricing Analysis
Long-term bundled service contracts dominate Tokyo metropolitan hospital procurement, replacing fragmented device-only purchasing with single-source agreements spanning educator training and remote monitoring support. Pricing stratifies across premium closed-loop systems, standard Bluetooth-enabled pumps, and economy-tier traditional devices based on algorithm sophistication and METI domestic manufacturing qualification status. Cost compression in standard-tier pumps intensifies as patch pump alternatives gain homecare reimbursement share. Prefectural hospitals exhibit highest price sensitivity due to educator shortage-driven service bundling requirements, while tertiary centers prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Japan and Switzerland anchor precision drive mechanism fabrication for piston and peristaltic pump architectures, with Aichi Prefecture's Nagoya corridor hosting contract manufacturers for PMDA-compliant electromechanical assembly. Supply draws from Malaysian rubber component suppliers for cannula and tubing systems, plus Taiwanese semiconductor foundries for microprocessor and Bluetooth module fabrication. Single-source vulnerability concentrates in algorithm software licensing from US-based continuous glucose monitor ecosystems. Distribution runs through authorized medical device distributors with prefectural health system relationships, bypassing direct hospital sales for regulatory compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's insulin infusion pump market enters a cyclical recovery phase as PMDA's compressed closed-loop approval pathway unlocks hospital procurement cycles previously deferred by regulatory uncertainty.
For Market Incumbents: Consolidate vendor relationships through exclusive educator training contracts that lock out competitors from Tokyo metropolitan network procurement committees. Acquire certified diabetes educator capacity in Kyushu and Hokkaido where acute shortages constrain pump initiation rates. Vertical integration into Aichi Prefecture manufacturing secures METI preferential procurement qualification against foreign entrants lacking domestic production. For New Entrants and Emerging Players: Lead with patch pump form factors targeting Osaka specialty diabetes clinics and Kansai region elderly homecare patients where tubeless discretion commands premium positioning. Target telehealth provider partnerships for remote monitoring revenue streams in prefectures facing educator scarcity. Pursue software-as-a-medical-device pre-certification with PMDA to enable over-the-air algorithm update capabilities before regulatory guidance solidifies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking diabetes portfolio rationalization, particularly Japanese manufacturers with dormant pump divisions and established JIS compliance infrastructure. Long-term viability hinges on closed-loop algorithm ownership rather than hardware commoditization. Watch PMDA's machine learning model update pathway ruling as the critical inflection signal determining regulatory maintenance cost structures for algorithm-driven systems.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Closed-Loop Pre-Certification | Accelerates hospital procurement timelines at Keio University Hospital and St. Luke's International Hospital. |
| Domestic Manufacturing Footprint | Unlocks METI preferential access to Osaka University Hospital and Kansai region referral networks. |
| Certified Diabetes Educator Network | Resolves acute personnel shortages constraining pump initiation in Kyushu and Hokkaido prefectures. |
| Bluetooth Ecosystem Integration | Enables remote monitoring revenue streams pending PMDA software-as-a-medical-device guidance clarification. |
| Patch Pump Form Factor Development | Captures elderly homecare expansion under universal health coverage reimbursement expansion. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with endocrinology department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers; and secondary validation against PMDA device registration databases, METI medical device industry strategy documents, Japan's universal health coverage reimbursement schedules, and hospital procurement records from Tokyo and Osaka metropolitan networks. Bottom-up pump shipment estimates triangulated against top-down universal health coverage claims data for continuous subcutaneous insulin infusion.
Across the projection horizon, the analytical framework modeled volume and value outputs through product type, form factor, end user channel, and technology maturity stage dimensions. CAGRs derived from regression analysis against historical reimbursement expansion patterns and PMDA approval velocity trends. Forecast inputs incorporated closed-loop algorithm adoption curves, certified diabetes educator supply constraints, and METI domestic manufacturing incentive uptake rates.
The analysis sits within stated boundaries; outcomes outside sustained PMDA regulatory clarity on software update pathways, stable universal health coverage reimbursement bands, or resolved educator shortage trajectories would require recalibration. Recalibration cycles align with material shifts in PMDA guidance releases, METI policy revisions, and prefectural health system workforce data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market