
 Scleroderma Treatment Market | 2026-2036
Scleroderma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Scleroderma Treatment Market Outlook
Specialty clinics is bifurcating demand away from general hospital rheumatology departments as patient volumes shift toward centers with dedicated scleroderma programs. Bristol-Myers Squibb Company anchors its position through deep R&D investment in immunomodulatory pathways. Boehringer Ingelheim International GmbH specializes in antifibrotic mechanisms for interstitial lung disease comorbidities. F. Hoffmann-La Roche Ltd dominates the biologics segment with established intravenous infusion protocols and specialist channel control.
Scleroderma treatment encompasses pharmaceutical and biological interventions targeting fibrosis, vascular dysfunction, and immune dysregulation in systemic and localized forms, with biologics typically requiring cold-chain distribution and precise dosing regimens. The primary purpose centers on halting disease progression, managing organ involvement, and improving quality of life in patients with limited and diffuse cutaneous subsets. Immunosuppressants occupy the largest revenue pool due to their first-line status in systemic sclerosis management, while biologics represent the fastest-expanding category driven by precision-targeted mechanisms. Injectable delivery modes command premium positioning relative to oral generics, reflecting administration complexity and specialist oversight requirements.
The FDA orphan drug framework shapes development economics through tax credits and market exclusivity provisions, while EMA parallel pathways influence European trial design and reimbursement negotiations. ISO 14155 standards govern clinical investigation quality for interventional studies across multiple jurisdictions, directly affecting trial costs and timeline feasibility. Stakeholders must monitor evolving biosimilar entry timelines and payer prior-authorization stringency as determinants of portfolio prioritization and geographic market sequencing.
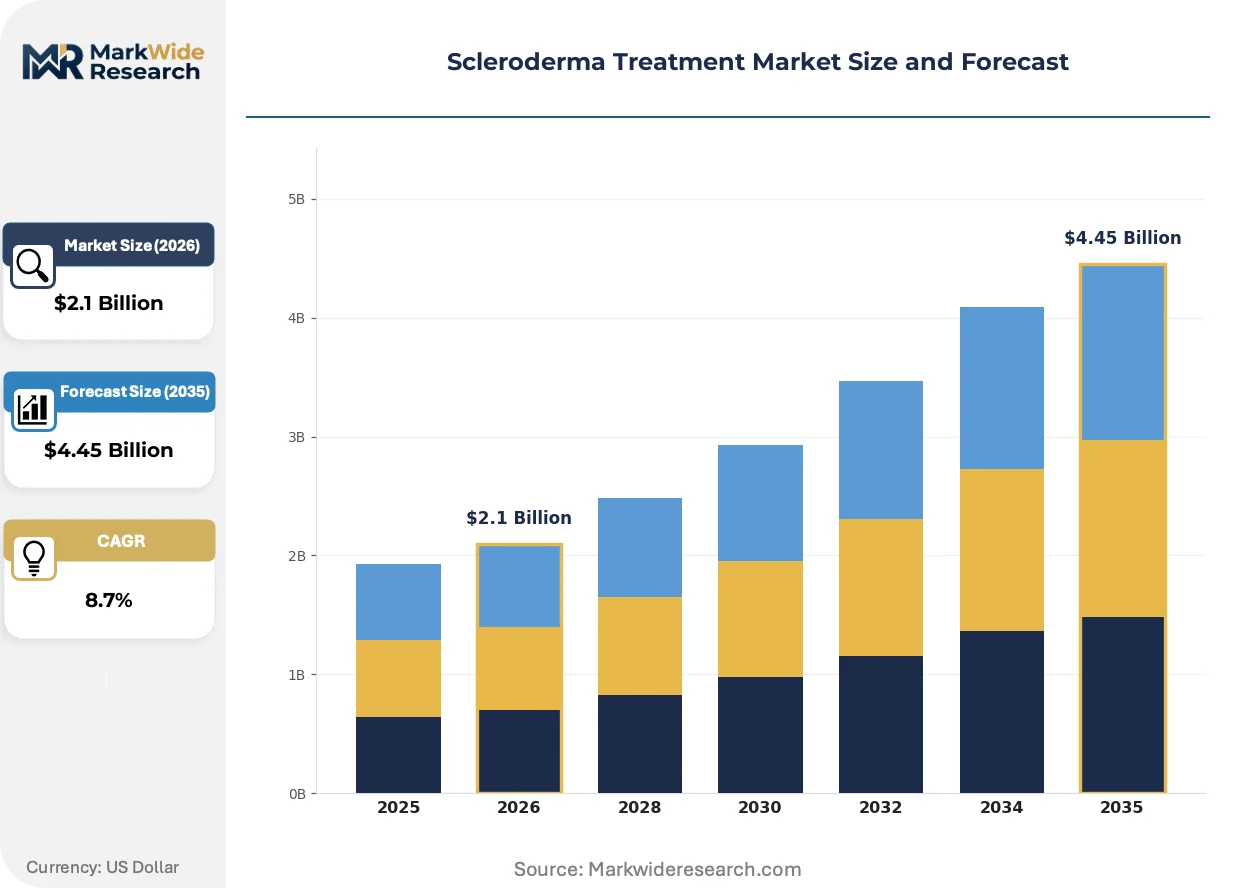
Market Dynamics
FDA orphan drug exclusivity provisions are compressing development timelines for systemic sclerosis biologics while simultaneously concentrating commercialization expertise among manufacturers with established cold-chain infrastructure and specialist channel relationships.
Growth Catalysts
- EMA parallel assessment pathways:European regulators accelerate conditional approval timelines for rare disease therapies, enabling synchronized US-EU launch strategies that reduce commercialization lag for novel immunomodulators.
- Specialty clinic expansion:Dedicated autoimmune centers in the United States are building scleroderma-specific infusion capabilities and patient registries that streamline biologic administration and outcomes tracking.
- Interstitial lung disease comorbidity protocols:Pulmonology-rheumatology integrated care models are expanding addressable patient pools by capturing systemic sclerosis patients earlier in disease progression through routine screening mandates.
Market Restraints
- Biologic cold-chain distribution costs:Temperature-controlled logistics for monoclonal antibodies impose infrastructure requirements that limit pharmacy participation and concentrate dispensing through hospital outpatient departments.
- Payer prior-authorization stringency:US commercial insurers and Medicare Advantage plans impose step-therapy requirements that delay biologic initiation until immunosuppressant failure, compressing effective treatment windows.
- Specialist workforce concentration:Board-certified rheumatologists with scleroderma expertise cluster in academic medical centers, creating access barriers in rural and secondary metropolitan markets.
Strategic Opportunities
- Telemedicine-enabled rural outreach:Virtual consultation platforms connect community rheumatologists with academic specialists for case review, extending biologic eligibility assessment to underserved US counties.
- Biosimilar entry preparation:Manufacturers with established intravenous infusion protocols can capture share from reference biologics as FDA approves follow-on therapies for autoimmune indications.
- Patient advocacy foundation partnerships:Scleroderma Foundation and similar organizations provide disease education infrastructure that reduces diagnostic delays and accelerates specialist referral pathways.
Industry Challenges
- Clinical trial recruitment bottlenecks:Limited systemic sclerosis prevalence requires multi-site international enrollment, complicating ISO 14155 compliance and protocol harmonization across jurisdictions.
- Biomarker validation delays:Absence of surrogate endpoints accepted by FDA and EMA forces reliance on hard clinical outcomes, extending pivotal study duration and increasing development risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scleroderma Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Corticosteroids, Antifibrotic Agents, Biologics Application: Cutaneous Scleroderma, Systemic Sclerosis, Organ Involvement, Raynaud's Phenomenon End User: Hospitals, Specialty Clinics, Research Institutions, Homecare Settings Delivery Mode: Oral, Injectable, Intravenous, Topical |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Boehringer Ingelheim International GmbH, Bayer AG, Sanofi, Corbus Pharmaceuticals Holdings, Inc., Pfizer Inc., GSK plc, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scleroderma Treatment Market Strategic Shifts
Precision immunology platforms are fragmenting the historical dominance of broad immunosuppressants, while regulatory acceleration mechanisms and patient-centric care models compress commercialization timelines and reshape site-of-care economics.
JAK inhibitors and tyrosine kinase inhibitors are fragmenting first-line treatment algorithms previously dominated by methotrexate and mycophenolate mofetil. Academic medical centers in the United States are adopting these oral alternatives for early diffuse cutaneous disease, enabling home administration that reduces infusion center dependency and shifts pharmacy benefit management complexity toward oral specialty drug tiers.
FDA's orphan drug tax credit provisions and seven-year market exclusivity are reshaping portfolio prioritization decisions for rare disease divisions. Manufacturers are front-loading systemic sclerosis programs to capture these incentives, accelerating IND filings and compressing Phase I-to-Phase II transitions. European sponsors simultaneously leverage EMA's PRIME designation to align regulatory strategies across Atlantic markets.
Site-of-care migration is compressing hospital outpatient department dominance as specialty pharmacies gain accreditation for biologic administration. United States payers are steering stable patients toward ambulatory infusion centers with lower facility fees, particularly in Medicare Advantage networks where total cost of care contracts incentivize care setting optimization.
Scleroderma Treatment Market Segmentation
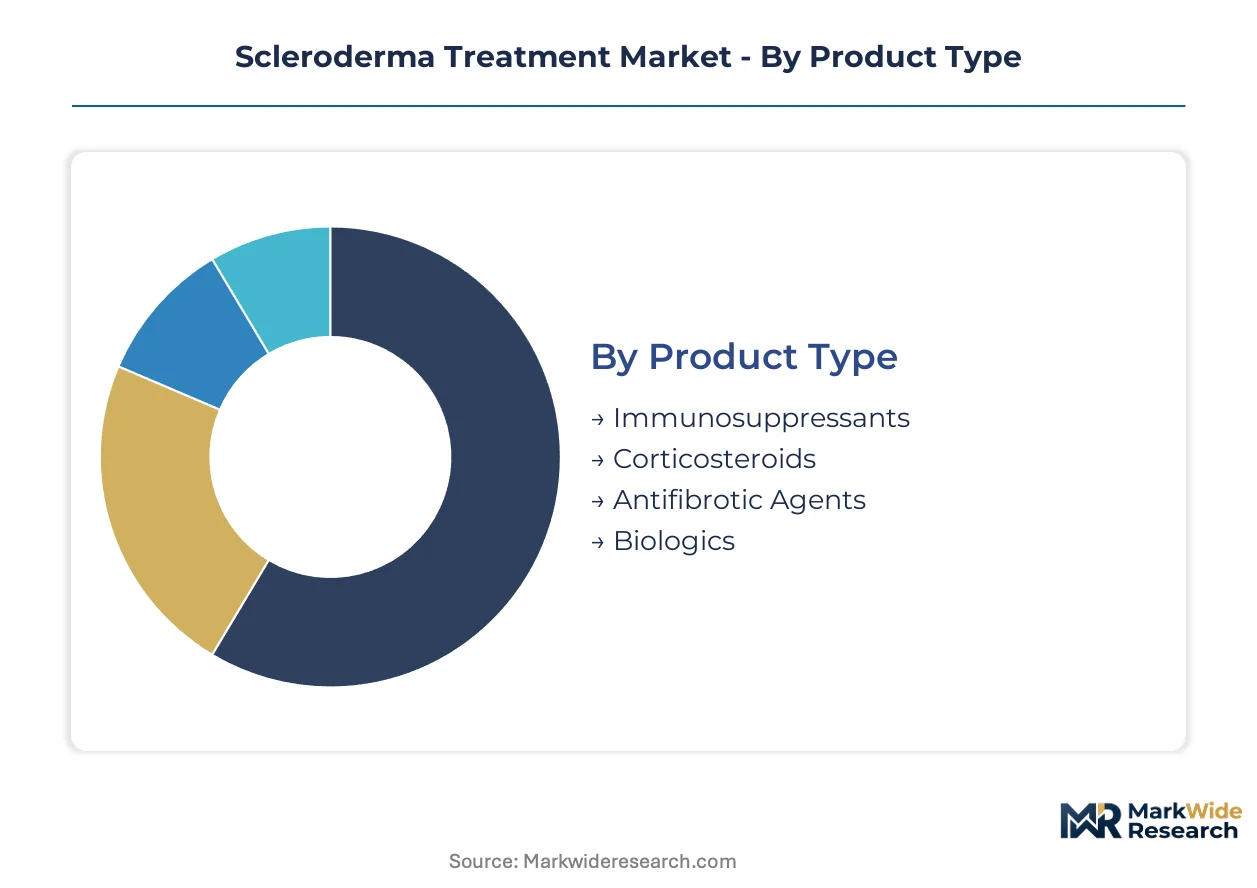
Scleroderma treatment markets fragment across therapeutic mechanism, disease manifestation, and site-of-care economics. Understanding these divisions reveals where biologic substitution pressures concentrate and which channels capture premium pricing.
Product Type:
Antifibrotic agents face the most acute substitution pressure from emerging tyrosine kinase inhibitors, while biologics confront biosimilar entry timelines that reshape manufacturer investment horizons.
- Immunosuppressants:Methotrexate and mycophenolate mofetil remain first-line systemic therapy, with demand anchored in United States academic medical centers where step-therapy protocols mandate trial before biologic escalation. Payer prior-authorization stringency reinforces their volume position despite slower onset.
- Biologics:Monoclonal antibodies targeting IL-6 and B-cell pathways command infusion-center premiums and require cold-chain infrastructure. United States specialty clinics build registries around these agents, capturing patients with diffuse cutaneous progression.
- Antifibrotic Agents:Nintedanib and pirfenidone address interstitial lung disease comorbidities.
- Corticosteroids:Prednisone bridges acute flares in localized and early systemic disease.
Immunosuppressants anchor the volume base while biologics gain share at the steepest rate.
Application:
Cost tier stratification separates diagnostic-stage interventions from chronic management, with organ involvement protocols commanding the highest per-patient spend due to multi-specialty coordination requirements.
- Systemic Sclerosis:Diffuse and limited cutaneous subsets drive biologic eligibility and infusion center utilization. United States pulmonology-rheumatology integrated screening protocols expand addressable pools by capturing interstitial lung disease early.
- Organ Involvement:Renal crisis and pulmonary hypertension require ICU-capable sites with continuous monitoring. Academic medical centers concentrate this demand through dedicated scleroderma programs.
- Cutaneous Scleroderma:Localized morphea and linear scleroderma respond to topical and phototherapy.
- Raynaud's Phenomenon:Calcium channel blockers and vasodilators address vascular dysfunction.
Systemic sclerosis generates the highest revenue per patient while organ involvement applications expand most quickly through screening mandate adoption.
End User:
Customer type concentration reflects site-of-care economics, with specialty clinics capturing stable biologic patients from hospital outpatient departments through lower facility fees and dedicated disease expertise.
- Specialty Clinics:Dedicated autoimmune centers build infusion capabilities and patient registries that streamline biologic administration. United States Medicare Advantage networks steer stable patients toward these settings under total cost of care contracts.
- Hospitals:Academic medical centers retain complex cases requiring multi-organ coordination and ICU escalation. Board-certified rheumatologist concentration reinforces their dominance in diagnostic workup and clinical trial access.
- Homecare Settings:Subcutaneous biologic self-administration expands through specialty pharmacy networks.
- Research Institutions:Phase II and III trial sites concentrate in FDA and EMA jurisdictions.
Hospitals retain the most complex cases while specialty clinics capture volume fastest through site-of-care migration incentives.
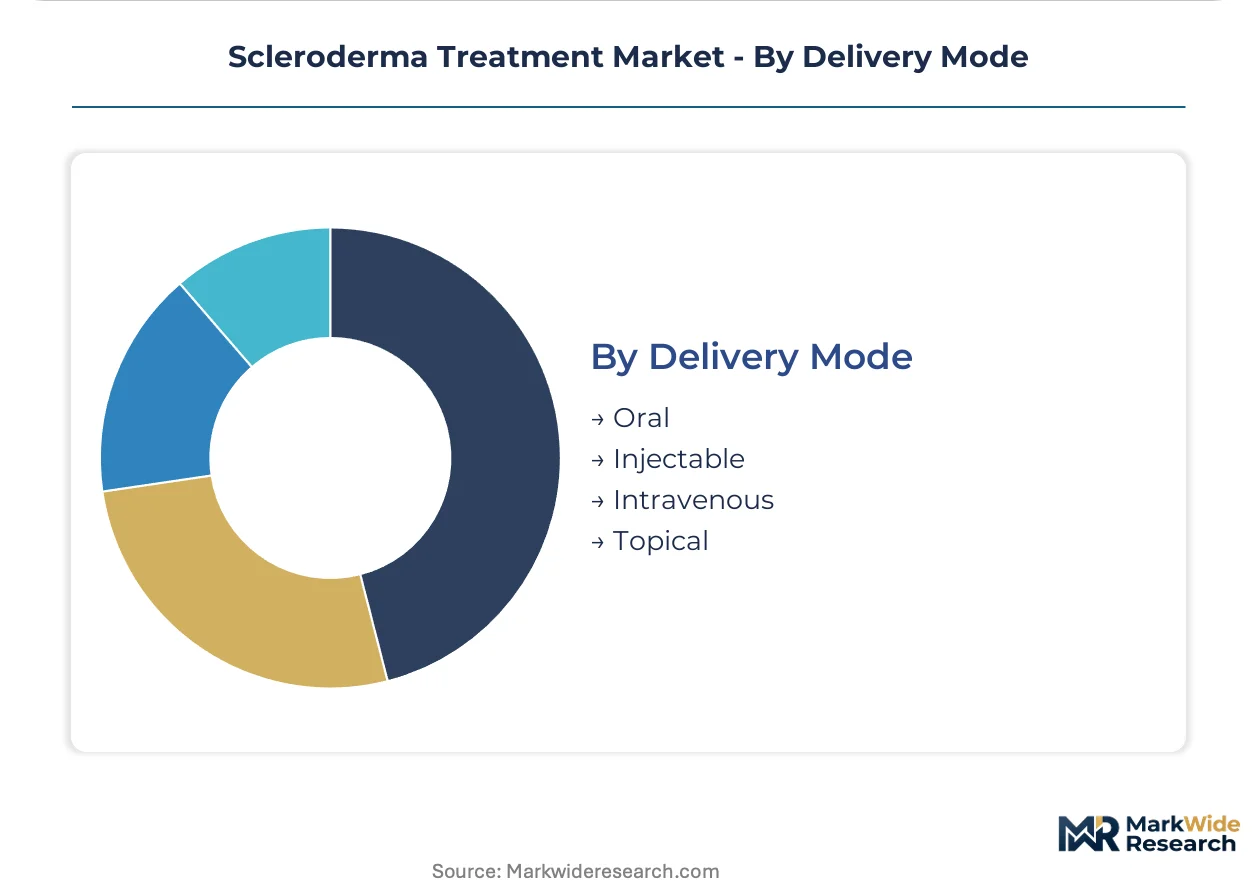
Delivery Mode:
Supply concentration in intravenous administration creates infrastructure barriers that oral alternatives exploit, with JAK inhibitors displacing infusion dependency in early diffuse disease.
- Intravenous:Monoclonal antibody protocols require cold-chain distribution and specialist oversight. United States hospital outpatient departments and accredited specialty pharmacies dominate dispensing due to temperature-controlled logistics requirements.
- Injectable:Subcutaneous biologics enable home administration through specialty pharmacy channels.
- Oral:Small-molecule immunosuppressants and emerging kinase inhibitors shift pharmacy benefit management complexity.
- Topical:Localized cutaneous disease management centers on compounded and commercial formulations.
Intravenous delivery anchors biologic revenue while oral modes climb fastest through JAK inhibitor adoption in early systemic disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's scleroderma program anchors North American patient throughput, while Frankfurt Airport's pharma cargo hub enables cold-chain distribution across European infusion networks.
United States
Medicare Advantage total cost of care contracts steer stable biologic patients toward ambulatory infusion centers with lower facility fees. FDA orphan drug tax credits accelerate IND filings for systemic sclerosis programs. The Johns Hopkins Scleroderma Center in Baltimore maintains one of the largest patient registries, capturing longitudinal outcomes data that shapes payer coverage policies.
Germany
EMA PRIME designation aligns regulatory strategies with US timelines for synchronized Atlantic launches. The country's statutory health insurance system maintains fixed reimbursement rates for biologic infusions that compress pharmacy margins. Heidelberg University Hospital concentrates interstitial lung disease screening protocols through its integrated pulmonology-rheumatology department.
Japan
PMDA's sakigake designation pathway accelerates conditional approval for rare disease biologics targeting diffuse cutaneous subsets. The aging demographic expands the addressable patient pool for organ involvement management. Tokyo Medical and Dental University Hospital anchors clinical trial access through its dedicated autoimmune center.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay biologic adoption until immunosuppressant failure documentation. The NHS Long Term Plan mandates earlier specialist referral for systemic sclerosis through primary care screening triggers. The Royal Free Hospital's scleroderma unit in London captures complex multi-organ cases from across England.
Switzerland
Swissmedic's parallel scientific advice with FDA reduces regulatory divergence for orphan biologic submissions. Premium pricing acceptance for innovative therapies supports manufacturer investment in precision immunology platforms. University Hospital Zurich maintains a dedicated scleroderma day clinic that integrates infusion administration with patient education programs.
Scleroderma Treatment Market Competitive Environment
Concentration sits with large-cap biopharmaceuticals possessing established cold-chain infrastructure and specialist channel relationships. The market structure consolidates around manufacturers with orphan drug program expertise and infusion protocol standardization capabilities. Three archetypes dominate: immunomodulatory specialists, antifibrotic mechanism developers, and biologics manufacturers with registry-building capabilities. Competitive moves center on biosimilar entry preparation and site-of-care migration capture through specialty pharmacy partnerships.
Among Swiss-dominant biologics manufacturers, F. Hoffmann-La Roche Ltd exemplifies the infusion-center registry archetype through established intravenous protocols. Bristol-Myers Squibb Company and Boehringer Ingelheim International GmbH represent complementary positioning—one anchoring immunomodulatory pathway investment, the other specializing in interstitial lung disease comorbidity mechanisms. These three entities collectively illustrate how geographic clustering around Basel and New York shapes competitive differentiation through proximity to FDA and EMA regulatory expertise.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Boehringer Ingelheim International GmbH |
| Bayer AG |
| Sanofi |
| Corbus Pharmaceuticals Holdings, Inc. |
| Pfizer Inc. |
| GSK plc |
| AbbVie Inc. |
| Others |
Value Chain & Pricing Dynamics
Oral JAK inhibitor substitution for intravenous biologics is simultaneously fragmenting United States infusion center geography and compressing pharmacy benefit management complexity toward oral specialty tiers. This mechanism shift redraws cold-chain infrastructure requirements while reallocating margin capture between hospital outpatient departments and ambulatory specialty pharmacies.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroid levels dominates the market. Price differentiation hinges on administration complexity and FDA orphan drug exclusivity status, with biologic infusions commanding facility fee premiums. Cost compression in the standard tier is intensifying because mycophenolate mofetil faces generic erosion and step-therapy mandates. Medicare Advantage plans exhibit highest price sensitivity through total cost of care contracts, while self-funded employer plans show lowest sensitivity for orphan-designated therapies.
Supply Chain Analysis
The United States, Germany, and Switzerland anchor biologic manufacturing and regulatory submission capabilities for scleroderma therapies. Cold-chain distribution draws from specialized pharma logistics providers with temperature-validated container fleets. Single-source vulnerability concentrates in monoclonal antibody fill-finish capacity. Distribution runs through hospital outpatient departments and accredited specialty pharmacies with infusion administration credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug tax credit provisions are accelerating systemic sclerosis program prioritization, creating a high-growth disruption window as manufacturers front-load IND filings to capture seven-year exclusivity incentives.
For Market Incumbents: Secure infusion protocol standardization through specialty pharmacy partnerships before biosimilar entry fragments reference biologic pricing. Lock in pulmonology-rheumatology integrated screening relationships to capture interstitial lung disease patients earlier in progression. Cold-chain infrastructure investment remains the critical lever against oral JAK inhibitor displacement. For New Entrants and Emerging Players: Anchor in Medicare Advantage total cost of care contracts where site-of-care migration incentives favor ambulatory infusion centers over hospital outpatient departments. Target rural rheumatology access gaps through telemedicine-enabled specialist consultation platforms. Pursue patient advocacy foundation partnerships to accelerate diagnostic referral pathways. For Investors and Strategic Acquirers: FDA biosimilar approval timelines for autoimmune indications reshape the acquisition landscape toward manufacturers with established intravenous registry capabilities. Five-to-ten year viability favors entities with orphan drug program expertise and EMA PRIME designation track records. Watch EMA parallel assessment pathway utilization rates as the signal for synchronized Atlantic launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA tax credits and exclusivity provisions accelerate IND filings for systemic sclerosis programs. |
| Specialty Clinic Partnership Network | Dedicated autoimmune centers capture stable biologic patients from hospital outpatient departments. |
| Pulmonology-Rheumatology Integration | Interstitial lung disease screening mandates expand addressable patient pools earlier in progression. |
| Biosimilar Entry Preparation | Established infusion protocols position manufacturers for reference biologic share capture. |
| Patient Registry Development | Longitudinal outcomes data shapes payer coverage policies and specialist referral algorithms. |
Study Parameters
The analysis maps immunosuppressant, biologic, antifibrotic, and corticosteroid treatment categories, each validated through rheumatology department heads, specialty pharmacy operations directors, payer formulary managers, and clinical trial principal investigators. Primary interview insights triangulate against FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocol databases, and Medicare Advantage plan bid filings. Bottom-up patient volume estimates and top-down manufacturer revenue disclosures converge through iterative reconciliation.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models therapeutic mechanism, disease manifestation subset, delivery mode, and site-of-care economics as core segmentation dimensions. CAGRs derive from patient prevalence projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate pulmonology-rheumatology screening mandate adoption rates and biosimilar entry probability assessments.
Underlying assumptions cover orphan drug exclusivity retention, payer step-therapy stability, and cold-chain infrastructure capacity, with deviation risk concentrated in biomarker validation delays and specialist workforce distribution shifts. Recalibration cycles align with material shifts in FDA biosimilar approval decisions and EMA parallel assessment pathway utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Scar Treatment Oils Market
Dermatology
Skin Cancer Market
Dermatology
Erythema Treatment Market
Dermatology
UK Scar Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Dermatology Drugs Market
Dermatology
Global Dermatology Cro Market
Dermatology
Folliculitis Treatment Market
Dermatology
Acne Scar Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
China Scar Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market