
 Global Multiple Sclerosis Therapeutics Market | 2026-2036
Global Multiple Sclerosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multiple Sclerosis Therapeutics Market Foresight
Platform licensing for long-acting interferon formulations is rewriting how originator firms capture recurring revenue without manufacturing exposure. Biogen leverages its entrenched neurology franchise to sustain high-margin royalty streams from legacy molecule partnerships. F. Hoffmann-La Roche Ltd anchors its position through dominant occupancy of the anti-CD20 infusion segment, where dosing intervals create sticky patient relationships. Novartis AG competes by extending its oral sphingosine-1-phosphate receptor modulator portfolio into earlier treatment lines.
Multiple sclerosis therapeutics comprise pharmacological agents designed to modify disease course, manage acute relapses, or alleviate progressive disability symptoms in autoimmune demyelination of the central nervous system; these span synthetic small molecules, recombinant monoclonal antibodies, and plasma-derived protein fractions, with efficacy measured against expanded disability status scale progression and annualized relapse rate reduction. Their primary purpose is to interrupt immune-mediated axonal damage while preserving functional capacity in ambulatory and non-ambulatory patient cohorts. Disease-Modifying Therapies concentrate the majority of commercial value, as payers prioritize agents demonstrating confirmed disability progression delay over symptomatic management alone. The relapsing-remitting therapy area generates disproportionate trial investment, though primary progressive indications represent an underserved structural opportunity where regulatory incentives attract development risk. Oral delivery modes are displacing injectable first-line options in many markets, reshaping pharmacy benefit design and patient adherence monitoring infrastructure.
FDA accelerated approval pathways, EMA conditional marketing authorization frameworks, and WHO essential medicines list inclusion criteria collectively shape which formulations achieve rapid reimbursement access versus prolonged health technology assessment scrutiny. These regulatory mechanisms determine real-world prescribing velocity more than clinical differentiation alone in many markets. Stakeholders must monitor evolving FDA guidance on surrogate endpoint acceptability for progressive MS subtypes, as this will redirect pipeline investment toward or away from high-risk neuroprotection mechanisms.
Market Dynamics
Platform licensing for long-acting interferon formulations is rewriting how originator firms capture recurring revenue without manufacturing exposure. Biogen leverages its entrenched neurology franchise to sustain high-margin royalty streams from legacy molecule partnerships. F. Hoffmann-La Roche Ltd anchors its position through dominant occupancy of the anti-CD20 infusion segment, where dosing intervals create sticky patient relationships. Novartis AG competes by extending its oral sphingosine-1-phosphate receptor modulator portfolio into earlier treatment lines.
Growth Catalysts
- FDA Accelerated Approval Pathway:Compressed development timelines compress time-to-revenue for manufacturers developing neuroprotective mechanisms in progressive MS subtypes.
- Infusion Capacity Expansion:Neurology clinics in the United States are scaling physical infrastructure to accommodate higher patient throughput for anti-CD20 and anti-VLA-4 therapies.
- Oral Delivery Migration:Sphingosine-1-phosphate receptor modulators and fumarate esters are displacing injectable first-line options, triggering pharmacy benefit redesign.
Market Restraints
- Specialist Density Concentration:Reimbursement infrastructure and neurologist availability cluster disproportionately in the United States, limiting therapy access in lower-density markets.
- Health Technology Assessment Scrutiny:EMA conditional marketing authorization frameworks subject progressive MS indications to prolonged cost-effectiveness review versus relapsing-remitting benchmarks.
- Biologic Manufacturing Complexity:Recombinant monoclonal antibody production requires single-use bioreactor capacity that concentrates supply risk among contract manufacturing organizations.
Strategic Opportunities
- Primary Progressive Indications:Regulatory incentives for underserved progressive MS subtypes attract pipeline investment toward neuroprotection mechanisms with surrogate endpoint flexibility.
- WHO Essential Medicines Inclusion:List placement criteria unlock rapid reimbursement access in emerging markets where public procurement dominates specialty pharmaceutical distribution.
- Patient Adherence Monitoring Infrastructure:Oral therapy expansion creates demand for digital therapeutics integration with pharmacy benefit managers and specialty pharmacies.
Industry Challenges
- Surrogate Endpoint Validation:Evolving FDA guidance on expanded disability status scale alternatives forces clinical trial design recalibration for neuroprotective candidates.
- Plasma-Derived Protein Fraction Supply:Immunoglobulin sourcing constraints complicate manufacturing scale-up for acute relapse management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multiple Sclerosis Therapeutics Market |
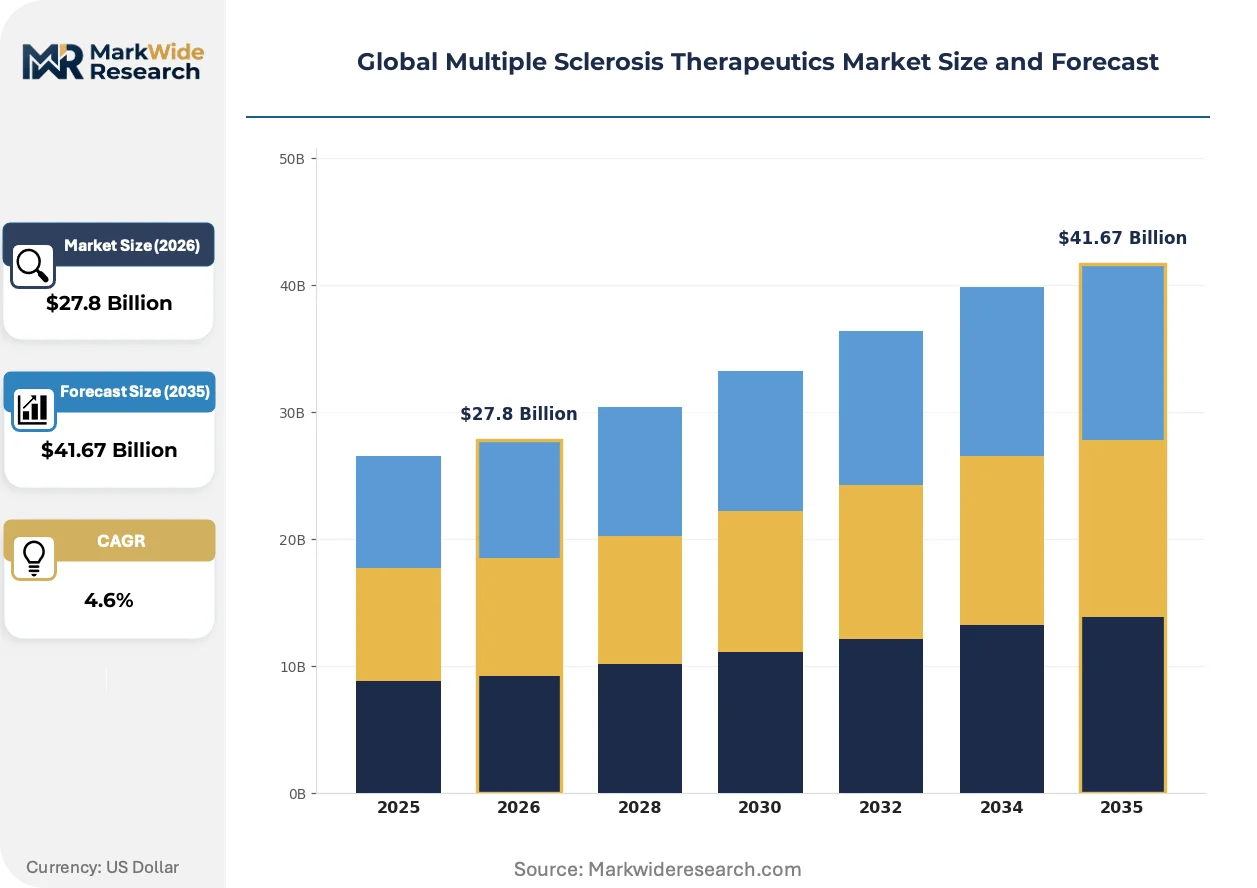
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $41.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disease-Modifying Therapies, Corticosteroids, Plasma Exchange, Symptomatic Treatments, Immunosuppressants Therapy Area: Relapsing-Remitting, Primary Progressive, Secondary Progressive, Clinically Isolated Syndrome, Pediatric MS End User: Neurology Clinics, Research Institutes, Specialized Hospitals, Outpatient Centers, Rehabilitation Facilities Delivery Mode: Oral, Injectable, Intravenous, Infusion, Transdermal |
| Companies Covered | Biogen, F. Hoffmann-La Roche Ltd, Novartis AG, Sanofi, Merck KGaA, Teva Pharmaceutical Industries Ltd, Bayer AG, Bristol-Myers Squibb Company, Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multiple Sclerosis Therapeutics Market Shifts & Advancements
Oral small-molecule platforms are collapsing the traditional injectable-first treatment paradigm across first-line and early second-line prescribing. This shift demands reconfiguration of pharmacy benefit structures and patient monitoring systems built around infusion center economics.
B-cell depletion therapy is collapsing the relapsing-remitting maintenance market as neurologists extend anti-CD20 dosing intervals beyond labeled schedules. United States academic medical centers are piloting personalized interval protocols based on CD19+ cell count monitoring, compressing annualized drug cost exposure while preserving efficacy endpoints. This practice is forcing originator firms to defend position through real-world evidence generation and value-based contract structures.
EMA conditional marketing authorization frameworks are accelerating access for progressive MS candidates with biomarker-based surrogate endpoints. The industrial consequence is pipeline redirection toward neurofilament light chain and brain atrophy metrics as disability progression proxies. Progressive MS trials in European Union member states are now incorporating these biomarkers as primary endpoints, compressing placebo-controlled exposure periods.
Specialty pharmacy consolidation is reshaping how oral disease-modifying therapies reach ambulatory patients. United States payers are narrowing network participation to vertically integrated pharmacy benefit managers with captive specialty dispensing capabilities. This channel compression disadvantages independent infusion centers and community neurologists without formal specialty pharmacy partnerships, concentrating patient volume in integrated delivery systems.
Global Multiple Sclerosis Therapeutics Market Segmentation
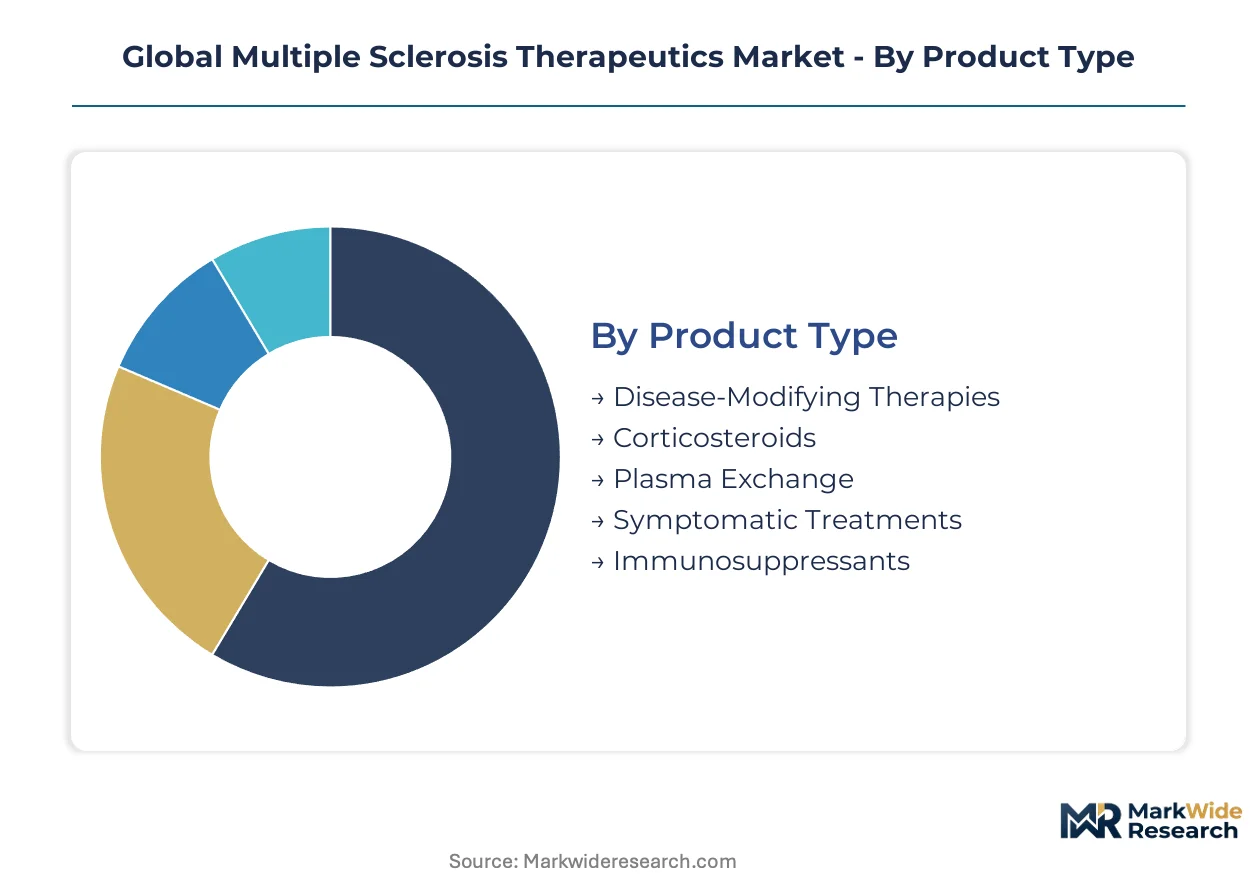
Therapeutic modality selection in multiple sclerosis hinges on disease trajectory, patient ambulatory status, and reimbursement tier placement. Segmentation reveals where prescribing velocity concentrates versus where clinical unmet need persists.
Product Type:
Disease-Modifying Therapies command the longest patient retention cycles, while acute intervention segments turn over rapidly based on relapse frequency.
- Disease-Modifying Therapies:Synthetic small molecules, recombinant monoclonal antibodies, and plasma-derived formulations designed to interrupt immune-mediated axonal damage and delay confirmed disability progression. Demand clusters in the United States where pharmacy benefit managers prioritize agents with demonstrated expanded disability status scale efficacy. FDA accelerated approval pathways compress development timelines for neuroprotective mechanisms targeting progressive subtypes.
- Corticosteroids:High-dose methylprednisolone and equivalent glucocorticoid protocols administered intravenously or orally to abbreviate acute relapse duration and severity. Prescribing concentrates in neurology clinics with established infusion capacity, particularly in academic medical centers managing high-relapse patient cohorts. EMA guidelines influence European Union prescribing thresholds for hospitalization versus outpatient administration.
- Plasma Exchange:Therapeutic apheresis protocols for steroid-refractory acute relapses, requiring specialized vascular access infrastructure.
- Symptomatic Treatments:Pharmacological management of spasticity, fatigue, and neuropathic pain without disease course modification.
- Immunosuppressants:Cytotoxic and antimetabolite agents reserved for aggressive or treatment-refractory disease courses.
Disease-Modifying Therapies dominate installed base. Immunosuppressants are where expansion concentrates for treatment-refractory cohorts.
Therapy Area:
Relapsing-remitting indications absorb the majority of trial investment, while progressive subtypes represent higher per-patient value despite smaller addressable populations.
- Relapsing-Remitting:Characterized by discrete inflammatory episodes with partial or complete recovery intervals, representing the most pharmacologically responsive MS subtype. Clinical development concentrates here due to established surrogate endpoints and shorter placebo-controlled trial durations. United States neurologist density supports premium therapy penetration in this segment.
- Primary Progressive:Continuous neurological deterioration from onset without relapses, historically underserved by disease-modifying options. Ocrelizumab's FDA approval for this indication validated neuroprotective trial designs using disability progression endpoints. WHO essential medicines inclusion criteria are reshaping access in emerging markets with public procurement dominance.
- Secondary Progressive:Initial relapsing-remitting course transitioning to steady progression, with evolving diagnostic criteria complicating trial enrollment.
- Clinically Isolated Syndrome:Single demyelinating event with MRI evidence of dissemination, representing earliest intervention opportunity.
- Pediatric MS:Onset before age 18 with distinct relapse patterns and regulatory trial requirements.
Relapsing-Remitting captures the largest patient volume. Primary Progressive is gaining share fastest as regulatory incentives redirect pipeline investment.
End User:
Infusion-dependent therapies concentrate patient flow in specialized settings, while oral agents disperse prescribing across ambulatory networks.
- Neurology Clinics:Dedicated outpatient facilities with infusion capacity for anti-CD20 and anti-VLA-4 biologics, plus monitoring infrastructure for oral therapy adherence. United States academic medical centers pilot personalized dosing interval protocols based on CD19+ cell count monitoring. Physical infrastructure expansion is underway to accommodate higher patient throughput.
- Specialized Hospitals:Inpatient and emergency settings managing acute relapse hospitalizations and plasma exchange protocols. Reimbursement frameworks in Germany and France influence length-of-stay thresholds for high-dose corticosteroid administration.
- Research Institutes:Sites of experimental therapy trials and biomarker validation studies.
- Outpatient Centers:Community-based settings capturing oral disease-modifying therapy prescribing.
- Rehabilitation Facilities:Post-acute settings addressing progressive disability symptom management.
Neurology Clinics dominate installed base. Outpatient Centers are where expansion concentrates as oral delivery modes displace injectable first-line options.
Delivery Mode:
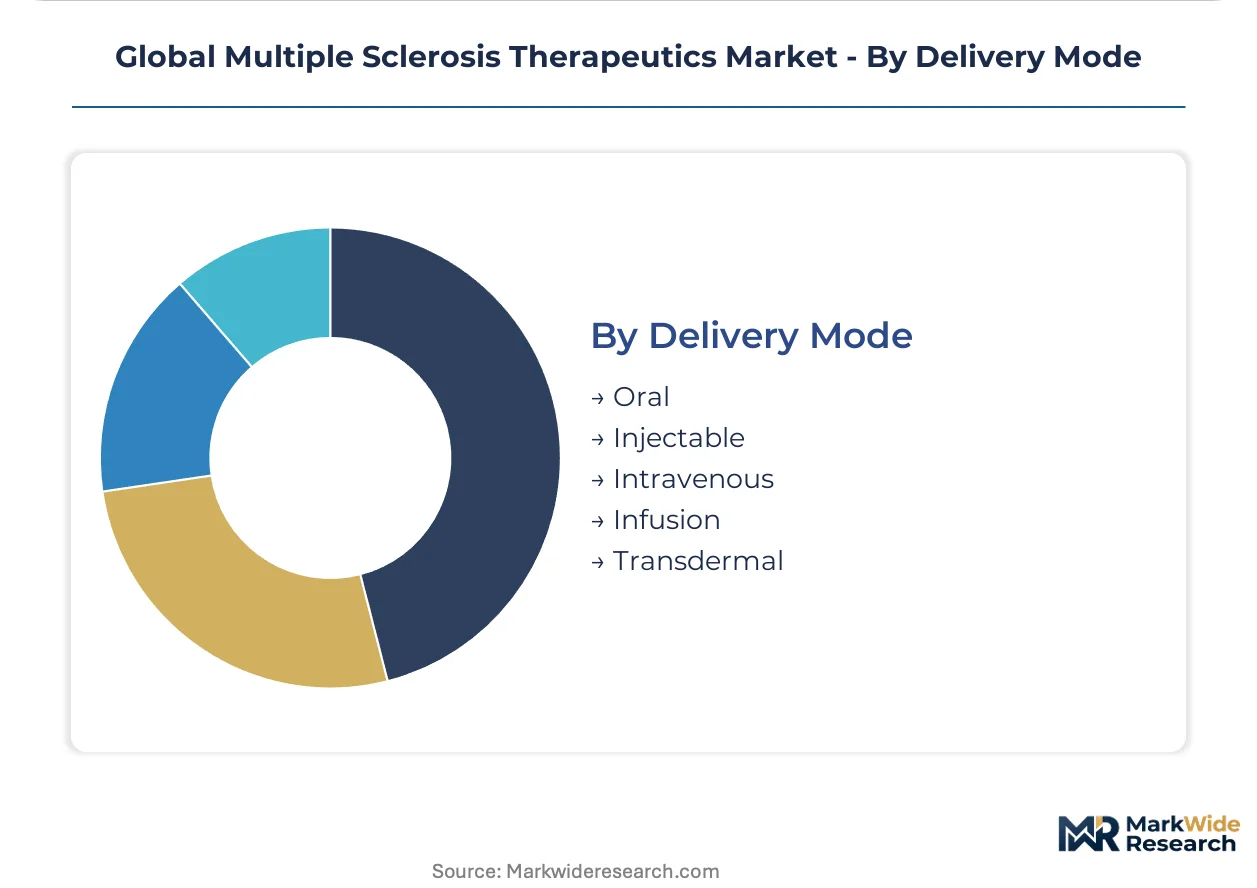
Patient preference and adherence economics are collapsing the traditional injectable-first paradigm toward oral and extended-interval infusion options.
- Oral:Sphingosine-1-phosphate receptor modulators and fumarate esters enabling self-administration without injection training or infusion scheduling. Pharmacy benefit redesign in the United States is narrowing network participation to vertically integrated specialty pharmacies with captive dispensing capabilities. Digital therapeutics integration is emerging for adherence monitoring.
- Intravenous:Infusion center administration of anti-CD20 and anti-VLA-4 monoclonal antibodies with extended dosing intervals creating sticky patient relationships. F. Hoffmann-La Roche Ltd anchors position through dominant occupancy of this segment. EMA conditional marketing authorization frameworks accelerate European Union access.
- Injectable:Subcutaneous and intramuscular platforms including long-acting interferon formulations.
- Infusion:Hospital-based administration for acute relapse management and certain biologic protocols.
- Transdermal:Emerging delivery platforms for symptomatic agents with absorption variability challenges.
Intravenous dominates installed base for high-efficacy maintenance. Oral is climbing the fastest as first-line prescribing patterns shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with United States payers absorbing premium therapy costs while European health technology assessment bodies impose rigorous cost-effectiveness thresholds that compress net pricing. Emerging markets operate on essential medicines procurement frameworks that favor older molecules with established generic availability.
United States
Specialist neurologist density and pharmacy benefit manager infrastructure support accelerated uptake of anti-CD20 infusions and oral sphingosine-1-phosphate modulators. FDA accelerated approval pathways compress time-to-market for progressive MS candidates with biomarker-based endpoints. Neurology clinics in academic medical centers across Boston and the Research Triangle pilot personalized dosing intervals based on CD19+ cell monitoring.
Germany
EMA conditional marketing authorization frameworks shape reimbursement velocity for neuroprotective mechanisms targeting primary progressive subtypes. The Federal Joint Committee applies expanded disability status scale benchmarks in health technology assessment protocols that extend review timelines versus relapsing-remitting comparators. Industrial concentration in Baden-Württemberg hosts contract manufacturing organizations supplying single-use bioreactor capacity for recombinant monoclonal antibody production.
Switzerland
Swissmedic regulatory harmonization with EMA procedures enables rapid European market access for originator firms headquartered in Basel and Zurich. The country's essential medicines procurement influence through WHO list criteria shapes emerging market access strategies for plasma-derived protein fractions. Geneva-based international health agencies coordinate pediatric MS trial protocols that redirect development investment toward earlier intervention windows.
Japan
PMDA review timelines for oral disease-modifying therapies have compressed following prior approval pathway recognition for sphingosine-1-phosphate receptor modulators. METI industrial policy supports domestic biologics manufacturing capacity expansion to reduce import dependency for infusion-dependent maintenance therapies. The Kanto region's academic medical centers concentrate real-world evidence generation for Asian patient cohorts with distinct MRI progression patterns.
India
CDSCO accelerated approval mechanisms for drugs with WHO prequalification status enable rapid market entry for generic interferon formulations and fumarate esters. Central government procurement through the National Health Mission prioritizes cost-containment in disease-modifying therapy distribution to public sector neurology clinics. Maharashtra and Karnataka host specialty pharmacy networks that manage oral therapy adherence monitoring for urban patient populations.
Global Multiple Sclerosis Therapeutics Market Competitive Landscape
Originator biopharmaceutical firms and diversified pharmaceutical conglomerates split the market between innovation-driven premium positioning and portfolio breadth strategies. The competitive structure concentrates around three archetypes: neurology-focused specialists leveraging franchise depth, diversified giants cross-subsidizing MS investment from oncology and immunology cash flows, and emerging biosimilar developers targeting interferon and glatiramer acetate commoditization. Dominant competitive moves include platform licensing for long-acting legacy formulations and real-world evidence generation to defend infusion interval extension practices.
Among neurology franchise specialists, Biogen and F. Hoffmann-La Roche Ltd exemplify contrasting strategic positions within the anti-CD20 and oral platform segments. Novartis AG occupies a position spanning sphingosine-1-phosphate receptor modulator development across relapsing-remitting and progressive indications. These three firms represent divergent archetypes: the legacy interferon royalty stream harvester, the infusion-centric sticky relationship builder, and the oral-first portfolio extender respectively.
| Leading Market Players |
|---|
| Biogen |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Sanofi |
| Merck KGaA |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services Inc. |
| Others |
Supply & Pricing Matrix
Single-use bioreactor undercapacity in the United States and Western Europe is forcing contract manufacturing organizations to prioritize originator firms with volume commitments, compressing access for mid-tier developers and amplifying pricing power for secured capacity holders. This utilization squeeze propagates through the value chain as biologic manufacturers absorb premium slot pricing while oral small-molecule producers exploit comparative supply flexibility.
Pricing Analysis
After-sales revenue from patient monitoring services and adherence digital platforms is extending lifetime value beyond the drug sale itself. Three-tier pricing structure across premium biologics, standard oral agents, and economy interferon generics separates insured academic medical center prescribing from commercial payer tiered formularies and cash-pay emerging market procurement. Price differentiation hinges on FDA accelerated approval tier placement and infusion center network exclusivity. Cost compression in the interferon segment is intensifying as platform licensing erodes originator manufacturing margins. Cash-constrained public health systems exhibit highest price sensitivity; United States commercial payers with pharmacy benefit manager consolidation show lowest elasticity.
Supply Chain Analysis
Upstream plasma fractionation feedstock concentrates in the United States, Germany, and Austria, where collection infrastructure and regulatory frameworks for immunoglobulin sourcing are most developed. Recombinant monoclonal antibody production draws from Chinese hamster ovary cell lines, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability in protein A resin supply creates bottlenecks for anti-CD20 manufacturing scale-up. Distribution runs through vertically integrated specialty pharmacy networks in the United States and hospital-centric procurement in European Union member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiple sclerosis therapeutics is approaching a platform-economics inflection as digital adherence infrastructure and real-world evidence networks create stickier patient-physician-pharmacy ecosystems than molecule differentiation alone. Interoperability between electronic health records and specialty pharmacy dispensing systems is consolidating channel control.
For Market Incumbents: Harden infusion center relationships through exclusive capacity reservation agreements and CD19+ monitoring protocol co-development with academic medical centers. Biologic manufacturers should secure backward integration into single-use bioreactor supply through captive manufacturing partnerships in Baden-Württemberg or Research Triangle clusters. Defensive patent estate extension around dosing interval personalization provides margin protection against biosimilar pressure.
For New Entrants and Emerging Players: Geographic underpenetration in Indian public sector neurology clinics and Southeast Asian academic medical centers offers white-space access before specialty pharmacy consolidation replicates United States channel structures. Primary progressive MS neuroprotection candidates with biomarker endpoints face less entrenched incumbent positioning than relapsing-remitting maintenance. Go-to-market through WHO prequalification pathways unlocks rapid emerging market reimbursement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across oral small-molecule segments as synthetic chemistry manufacturing displaces biologic fermentation infrastructure. Long-term viability favors platform licensors with royalty harvesting capability over capital-heavy manufacturing operators. Acquisition targets should demonstrate formulary placement momentum with at least two of the three dominant United States pharmacy benefit managers. The signal to watch is FDA guidance evolution on surrogate endpoint acceptability for progressive MS subtypes, which would redirect pipeline valuations toward or away from neuroprotection mechanisms.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | Defends anti-CD20 dosing interval extension practices against payer pressure through CD19+ monitoring data. |
| Specialty Pharmacy Partnership | Captures oral therapy patient flow as United States payers narrow network participation to integrated dispensing. |
| Platform Licensing Agreement | Enables originator firms to extract recurring royalties from legacy interferon formulations without manufacturing exposure. |
| Biomarker Endpoint Validation | Accelerates EMA conditional marketing authorization for progressive MS candidates using neurofilament light chain metrics. |
| Infusion Capacity Expansion | Accommodates higher patient throughput for anti-CD20 therapies in academic medical centers piloting personalized protocols. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological prevalence estimates were triangulated to anchor segmentation splits.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning therapeutic modality, disease course subtype, delivery mode, and regional regulatory cluster. CAGRs were derived from patient population projections, therapy line migration assumptions, and pricing elasticity differentials by payer archetype. Forecast inputs incorporated infusion center capacity expansion schedules and WHO essential medicines inclusion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar developers or digital therapeutics platforms would shift outcomes. Regulatory guidance evolution on surrogate endpoints and payer formulary exclusion practices represent specific revision risks. Cross-checking against CMS Medicare Part D utilization trends and EMA conditional authorization conversion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market