
 Cutaneous Fibrosis Treatment Market | 2026-2036
Cutaneous Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cutaneous Fibrosis Treatment Market Outlook
Modular combination kits pairing topical corticosteroids with silicone sheeting is repositioning how dermatology clinics procure wound care protocols. AbbVie leverages its immunology infrastructure to sustain biologic development pipelines in fibrotic skin disorders. Pfizer competes through oral JAK inhibitor platforms that anchor systemic treatment options for diffuse cutaneous fibrosis. Roche differentiates via diagnostic companion tools that extend precision medicine positioning into dermatological indications.
Cutaneous fibrosis treatment encompasses pharmacological, surgical, and device-based interventions targeting excessive collagen deposition in dermal and subcutaneous tissues, with primary mechanisms spanning TGF-beta pathway modulation, extracellular matrix remodeling, and mechanical tension reduction. Injectable therapies command concentrated margin pools where intralesional corticosteroids and 5-FU formulations dominate procedural revenue in dermatology practices. Oral medications represent the fastest-growing delivery category as systemic JAK inhibitors and antifibrotic agents expand beyond off-label use into registrational programs. Transdermal delivery systems occupy a niche but growing position where microneedle arrays and iontophoretic patches improve drug penetration through fibrotic dermal barriers.
FDA oversight shapes investigational new drug pathways for antifibrotic biologics, while EMA's MDR framework governs CE marking for laser and energy-based devices used in scar revision across European markets. The EU AI Act introduces compliance layers for algorithmic diagnostic tools that classify fibrosis severity from digital imaging. Stakeholders must monitor how payer evidence requirements for histological endpoints evolve alongside patient-reported outcome measures in dermatology.
Market Dynamics
FDA's evolving guidance on cell and gene therapies for fibrotic disorders is compressing clinical trial timelines while expanding investigational pathways, forcing sponsors to restructure development programs around novel efficacy endpoints.
Growth Catalysts
- IRA Provisions:Medicare price negotiation frameworks for biologics are accelerating patient access programs for systemic fibrosis treatments in United States dermatology networks.
- Silicone Sheeting Technology:Modular wound care protocols pairing mechanical tension reduction with corticosteroid delivery are standardizing keloid management across outpatient surgical centers.
- Academic Medical Center Concentration:United States-based research hospitals anchor the largest volume of interventional studies, drawing trial sponsorship and investigator-initiated research funding.
Market Restraints
- Biologic Input Cost Volatility:Recombinant protein manufacturing capacity constraints in contract development organizations are inflating cost-of-goods for antifibrotic monoclonal antibodies.
- EMA MDR Compliance Burden:CE marking requirements for laser and energy-based scar revision devices are extending time-to-market for European device manufacturers by 18-24 months.
- Topical Penetration Limitations:Fibrotic dermal barriers restrict drug bioavailability, capping efficacy ceilings for non-invasive delivery systems against deep keloid formations.
Strategic Opportunities
- Microneedle Array Convergence:Combination of dissolvable microneedles with iontophoretic patches is creating transdermal delivery platforms that bypass fibrotic tissue resistance.
- EU AI Act Tailwinds:Algorithmic diagnostic tools for fibrosis severity classification from digital imaging qualify for streamlined conformity assessment under emerging AI liability frameworks.
- Brazil ANVISA Pathway:Expedited review channels for orphan dermatological indications are opening first-mover positioning for novel antifibrotic mechanisms in Latin America's largest market.
Industry Challenges
- Histopathologist Talent Scarcity:Specialized expertise in quantitative collagen morphology assessment is bottlenecking trial site activation for fibrosis-specific endpoints.
- Legacy EHR Integration Friction:Dermatology practices struggle to incorporate patient-reported outcome measures into existing workflow systems, delaying real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutaneous Fibrosis Treatment Market |
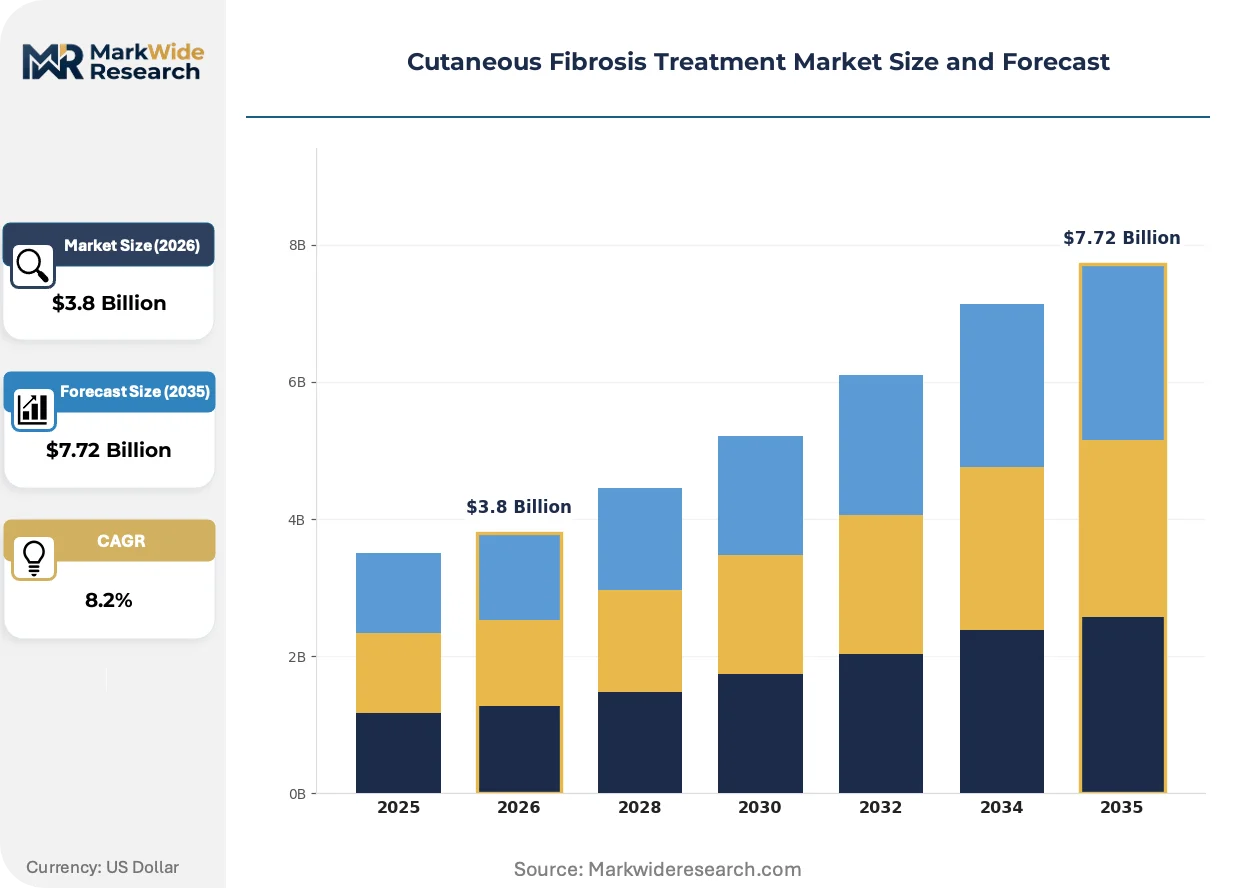
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Injectable Therapies, Oral Medications, Surgical Procedures Delivery Mode: Transdermal, Intravenous, Oral, Subcutaneous End User: Hospitals, Clinics, Home Care, Research Laboratories Application: Aesthetic Procedures, Post-Surgical Care, Chronic Wound Management, Dermatological Conditions |
| Companies Covered | Sanofi, Novartis, Pfizer, Roche, AbbVie, Amgen, Bristol Myers Squibb, Merck, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutaneous Fibrosis Treatment Market Strategic Shifts
Active pharmaceutical ingredient delivery through the stratum corneum is undergoing fundamental redesign as mechanical and electrical penetration methods converge with biologic modulation strategies.
Microneedle arrays combined with dissolvable hydrogel formulations are overtaking conventional intralesional injection protocols in keloid management protocols. Outpatient dermatology clinics in Germany and South Korea are adopting these platforms at accelerating cadence. The shift is compressing procedural revenue per patient while expanding addressable patient populations beyond specialist referral networks.
EMA's MDR framework for medical devices is recalibrating laser scar revision equipment classifications across European markets. Manufacturers must now submit clinical evidence packages for previously grandfathered technologies. German and French notified bodies are processing backlogs that delay market entry for fractional CO2 and pulsed-dye laser systems.
After-sales service unbundling is restructuring device procurement in United States dermatology practices. Clinics now negotiate maintenance contracts separately from capital equipment purchases, compressing vendor margins while extending equipment replacement cycles. This pattern is most visible in multi-site dermatology groups across Texas and Florida where centralized procurement functions have professionalized.
Cutaneous Fibrosis Treatment Market Segmentation
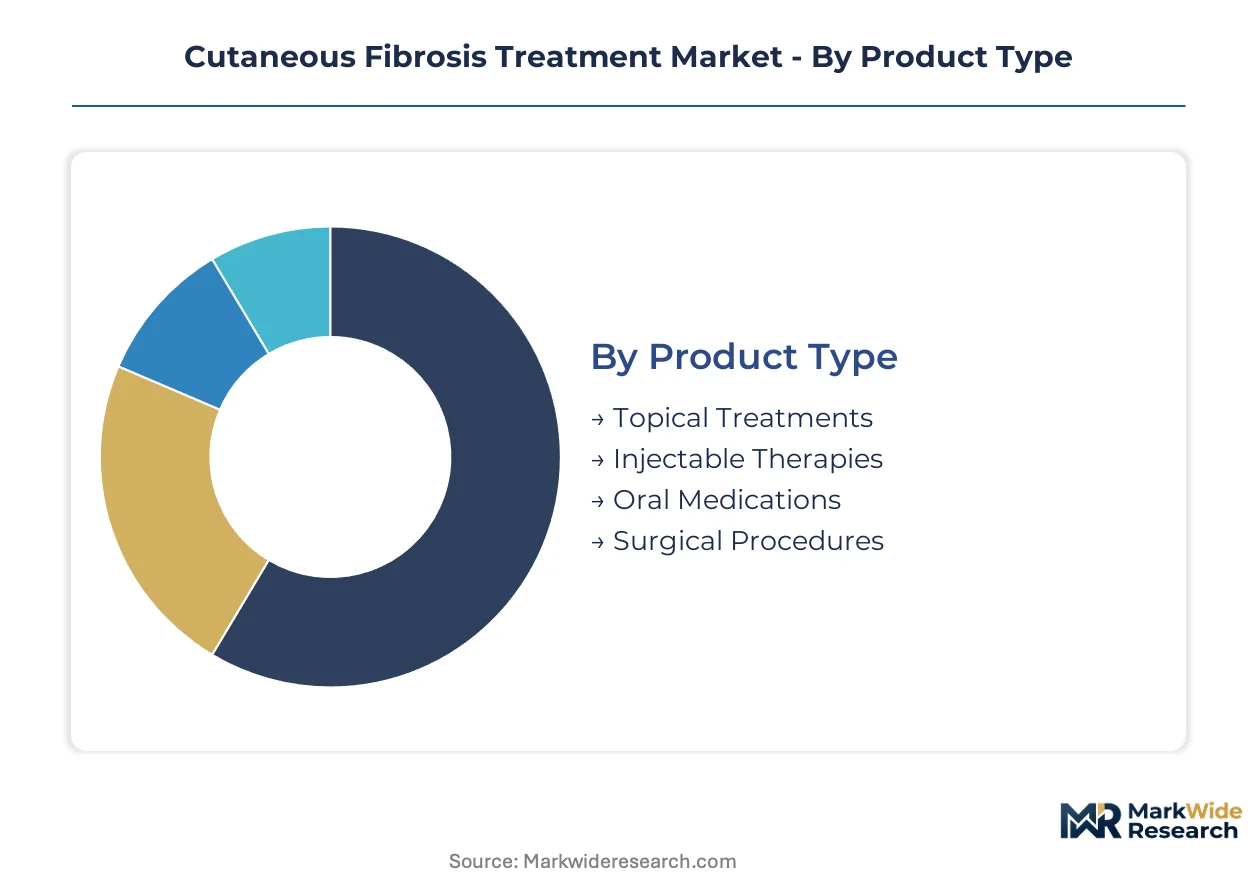
Cutaneous fibrosis treatment segments fragment across intervention intensity and care setting, with product type and delivery mode determining reimbursement pathways and margin structures. Understanding these divisions reveals where capital deployment concentrates and which patient populations remain underserved by current protocols.
Product Type:
Standardization dominates injectable and oral categories, while topical formulations and surgical protocols retain customization flexibility for lesion-specific protocols.
- Injectable Therapies:Intralesional corticosteroids and 5-FU formulations anchor procedural revenue in United States dermatology practices. Academic medical centers in Boston and Houston drive demand for combination injection protocols that pair mechanical tension reduction with pharmacologic modulation.
- Oral Medications:Systemic JAK inhibitors and antifibrotic agents are expanding from off-label use into registrational programs. United States-based specialty pharmacies report concentrated fulfillment volumes for diffuse cutaneous fibrosis indications where topical penetration fails.
- Topical Treatments:Silicone sheeting and corticosteroid creams serve first-line keloid management across outpatient surgical centers.
- Surgical Procedures:Excision with adjuvant radiation or cryotherapy addresses recurrent keloid formations resistant to pharmacologic intervention.
Leading the category by volume: Injectable Therapies. Expanding most quickly: Oral Medications.
Delivery Mode:
Cost tier stratification separates hospital-based intravenous administration from ambulatory oral and transdermal alternatives.
- Transdermal:Microneedle arrays and iontophoretic patches bypass fibrotic dermal barriers through mechanical and electrical penetration enhancement. German outpatient clinics in Munich and Hamburg are adopting these platforms at accelerating cadence for keloid management.
- Oral:Systemic delivery enables treatment of diffuse fibrotic conditions beyond localized lesion boundaries. United States dermatology networks prioritize oral JAK inhibitors for patient populations with extensive skin involvement.
- Intravenous:Hospital infusion centers administer biologic antifibrotic agents under specialist supervision.
- Subcutaneous:Self-administration potential supports home care transition for maintenance dosing protocols.
Climbing the fastest: Transdermal. Dominating current revenue: Oral.
End User:
Customer type segmentation aligns with procedure complexity and reimbursement intensity across institutional settings.
- Clinics:Dermatology and plastic surgery practices generate concentrated procedural revenue for injectable and device-based interventions. Multi-site groups in Texas and Florida have centralized procurement functions that professionalize vendor negotiations.
- Hospitals:Academic medical centers anchor interventional study volume and complex surgical revision cases. Major research hospitals in New York and California draw trial sponsorship through investigator-initiated research funding.
- Home Care:Topical protocol adherence and transdermal device self-application extend treatment continuity beyond clinical visits.
- Research Laboratories:Preclinical and clinical trial sites drive demand for standardized endpoint assessment tools and histological analysis services.
Highest patient throughput: Clinics. Fastest-growing setting: Home Care.
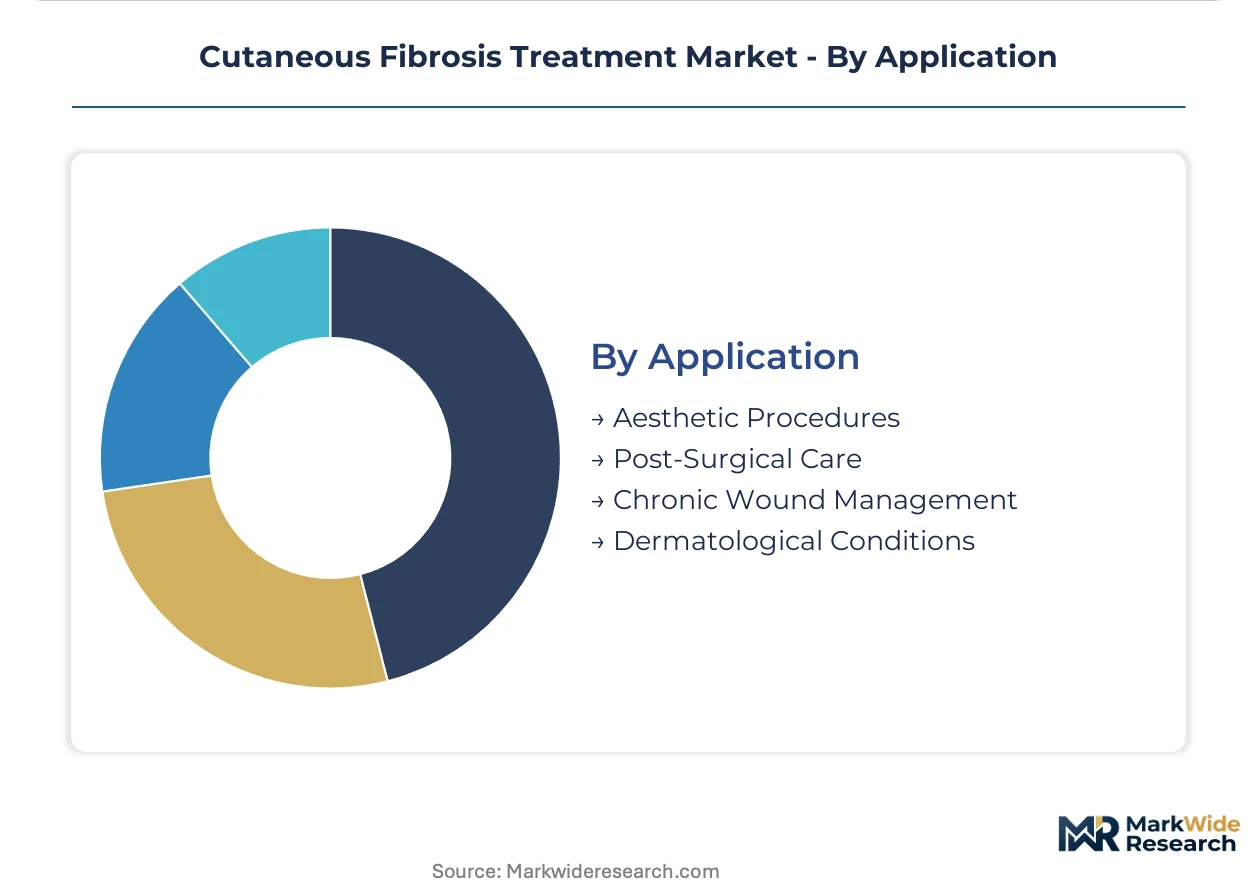
Application:
Maturity gradients separate established post-surgical protocols from emerging aesthetic and chronic wound indications.
- Post-Surgical Care:Keloid and hypertrophic scar prevention protocols follow standardized silicone sheeting and corticosteroid application timelines. Outpatient surgical centers in South Korea have adopted modular combination kits that pair mechanical tension reduction with pharmacologic delivery.
- Dermatological Conditions:Scleroderma and morphea treatment requires systemic intervention for diffuse cutaneous involvement. United States academic centers specialize in these complex autoimmune fibrotic disorders.
- Aesthetic Procedures:Cosmetic scar revision drives demand for laser and energy-based devices with minimal downtime profiles.
- Chronic Wound Management:Fibrotic tissue remodeling in non-healing wounds represents an underpenetrated indication for antifibrotic mechanisms.
Steepest expansion trajectory: Dermatological Conditions. Largest current volume: Post-Surgical Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of recombinant antifibrotic biologics concentrates in Switzerland and Germany, while patient recruitment and clinical trial execution gravitate toward United States academic medical centers. Consumption patterns diverge between procedural-heavy markets and systemic-therapy-preferring regions.
United States
Academic medical centers in Boston and Houston anchor the largest volume of interventional studies for keloid and hypertrophic scar protocols. FDA's evolving guidance on cell and gene therapies for fibrotic disorders is compressing clinical trial timelines while expanding investigational pathways. Multi-site dermatology groups across Texas and Florida have centralized procurement functions that professionalize vendor negotiations for combination injection kits.
Germany
Outpatient clinics in Munich and Hamburg are adopting microneedle arrays and iontophoretic patches at accelerating cadence for keloid management protocols. EMA's MDR framework for medical devices is recalibrating laser scar revision equipment classifications, with German notified bodies processing backlogs that delay market entry for fractional CO2 systems. Bavarian and North Rhine-Westphalian dermatology networks drive adoption of modular wound care protocols pairing mechanical tension reduction with pharmacologic delivery.
South Korea
Outpatient surgical centers in Seoul have pioneered modular combination kits that pair silicone sheeting technology with corticosteroid delivery for post-surgical scar prevention. MFDS maintains expedited review channels for novel dermatological devices, attracting Korean manufacturers of energy-based scar revision equipment. The Seoul Capital Area concentration of aesthetic dermatology practices generates concentrated demand for minimal-downtime laser protocols.
Brazil
ANVISA's expedited review channels for orphan dermatological indications are opening first-mover positioning for novel antifibrotic mechanisms in Latin America's largest market. São Paulo-based research hospitals draw investigator-initiated funding for scleroderma and morphea treatment protocols requiring systemic intervention. Southeast Brazilian dermatology networks are expanding service lines for keloid management beyond specialist referral networks.
Japan
PMDA oversight shapes registrational pathways for oral JAK inhibitors expanding from off-label use into approved indications for diffuse cutaneous fibrosis. Kanto region academic centers specialize in complex autoimmune fibrotic disorders with extensive skin involvement. Tokyo-area specialty pharmacies report concentrated fulfillment volumes for systemic antifibrotic agents where topical penetration fails.
Cutaneous Fibrosis Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the cutaneous fibrosis treatment landscape, creating a tiered structure where immunology infrastructure determines biologic development capacity. Swiss and German pharmaceutical conglomerates leverage recombinant protein manufacturing scale for antifibrotic monoclonal antibodies. United States-based biotech specialists concentrate on JAK inhibitor platforms and cell therapy modalities. The dominant competitive moves involve strategic partnerships for diagnostic companion tools and geographic licensing arrangements for device-based scar revision technologies.
Within the immunology-diversified tier, AbbVie leverages existing infrastructure to sustain biologic development pipelines, while Pfizer competes through oral JAK inhibitor platforms. Roche occupies a precision-medicine position via diagnostic companion tools that extend into dermatological indications. These three exemplify how therapeutic area breadth versus focus shapes competitive positioning in fibrotic skin disorders.
| Leading Market Players |
|---|
| Sanofi |
| Novartis |
| Pfizer |
| Roche |
| AbbVie |
| Amgen |
| Bristol Myers Squibb |
| Merck |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Captive recombinant protein manufacturing in Switzerland and Germany anchors both supply security and premium pricing power for antifibrotic biologics, while outsourced small-molecule API production in India and China enables cost competition in oral JAK inhibitor categories. This bifurcation creates divergent margin structures across the cutaneous fibrosis treatment landscape.
Pricing Analysis
Margin tightening in injectable corticosteroid and 5-FU formulations reflects procurement professionalization among United States multi-site dermatology groups. Three-tier pricing structure across premium biologics, standard small-molecules, and economy topical generics separates reimbursement intensity by intervention complexity. Pricing pressure intensifies in device categories as after-sales service unbundling compresses vendor margins. Hospital infusion centers exhibit lowest price sensitivity for biologic antifibrotics, while outpatient surgical centers drive hardest bargains on silicone sheeting protocols.
Supply Chain Analysis
Returns and refurbishment flows for laser scar revision equipment are minimal, though device leasing programs in German and South Korean outpatient clinics create circular revenue streams that offset capital purchase cycles. Recombinant protein manufacturing concentrates in Switzerland, Germany, and the United States, drawing from CHO cell culture media and single-use bioreactor components. Single-source vulnerability in contract development organization capacity for monoclonal antibody production threatens supply continuity for novel antifibrotic biologics. Distribution runs through specialty pharmacy networks for oral systemic agents and direct-to-clinic procurement for injectable and device-based interventions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
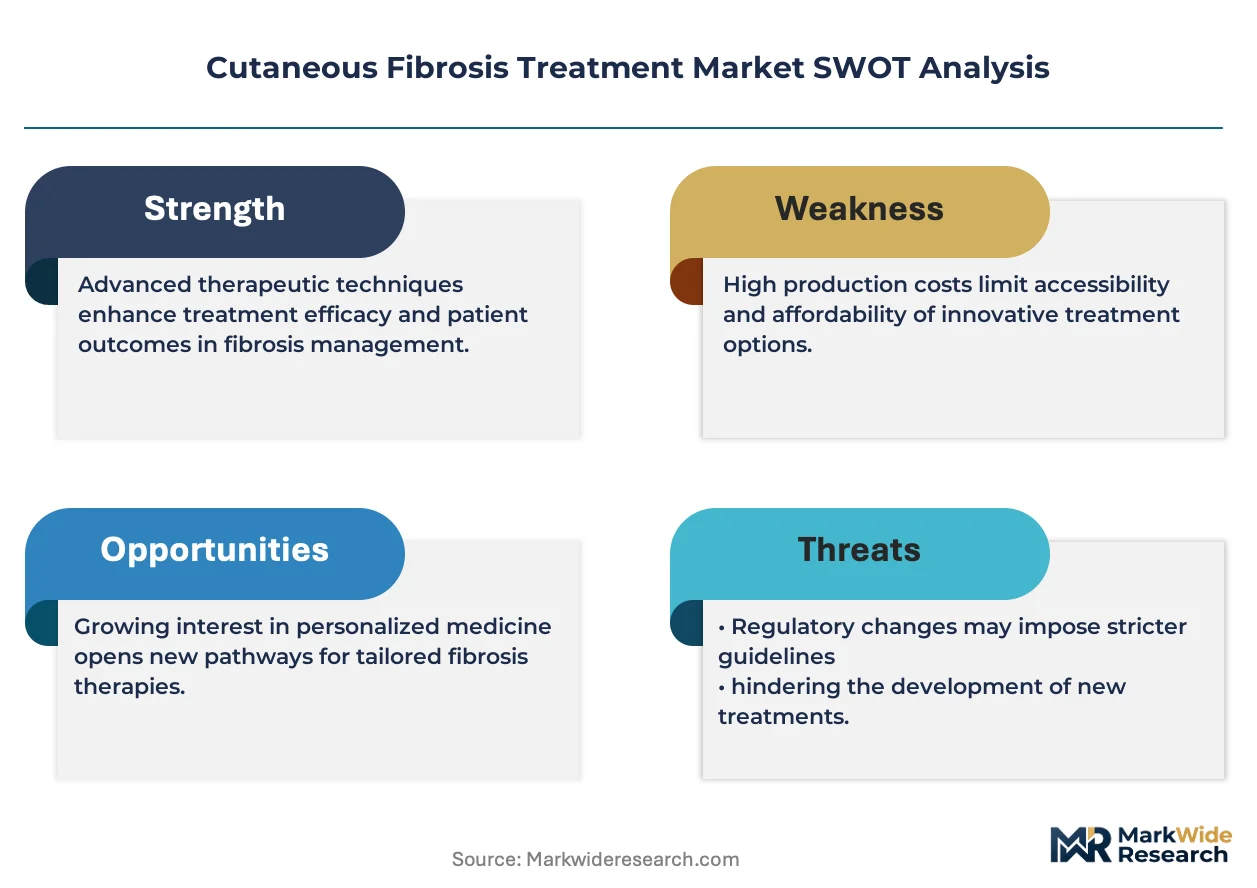
The cutaneous fibrosis treatment market operates as a cost-of-compliance arena where EMA's MDR framework and FDA's evolving cell and gene therapy guidance erect substantial barrier-to-entry moats for players with established regulatory infrastructure.
For Market Incumbents: To counter procurement professionalization among United States dermatology groups, AbbVie and Pfizer should deepen backward integration into recombinant protein manufacturing and secure captive supply of CHO cell culture media. Certification investment in EU AI Act compliance for algorithmic diagnostic tools extends precision medicine positioning against emerging digital health competitors. For New Entrants and Emerging Players: Enter via Brazil's ANVISA expedited review channels for orphan dermatological indications, where first-mover positioning in scleroderma and morphea systemic treatment remains undercontested. Microneedle array convergence with iontophoretic patches offers the most penetrable white-space target, with German outpatient clinics in Munich and Hamburg demonstrating accelerated adoption velocity for transdermal delivery platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by immunology-diversified conglomerates seeking JAK inhibitor platform assets or cell therapy modalities. Long-term viability hinges on registrational program advancement beyond off-label use into approved indications. Watch FDA guidance finalization on cell and gene therapies for fibrotic disorders as the critical inflection signal for pipeline valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA MDR compliance for laser devices recalibrates European market entry timelines for scar revision equipment. |
| Manufacturing Scale-Up | Recombinant protein capacity expansion in Swiss and German contract development organizations secures biologic supply continuity. |
| Pipeline Diversification | Cell and gene therapy modalities for diffuse cutaneous fibrosis expand beyond TGF-beta pathway modulation into novel mechanisms. |
| Reimbursement Strategy | Medicare price negotiation frameworks under IRA provisions accelerate patient access programs for systemic fibrosis treatments. |
| Software Companion Development | Algorithmic diagnostic tools for fibrosis severity classification qualify for streamlined EU AI Act conformity assessment pathways. |
Study Parameters
Multi-period observation of intralesional injection protocol adoption, silicone sheeting procurement patterns, and oral JAK inhibitor fulfillment volumes anchored the trend analysis, supplemented by interviews with dermatology practice administrators, hospital formulary directors, regulatory affairs leads at biopharmaceutical firms, and contract development organization executives. Secondary validation drew from FDA filings, EMA MDR submission databases, ClinicalTrials.gov interventional study records, and CMS Medicare Part D claims data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Input-output matrices mapped treatment line progression, delivery mode substitution elasticities, administration route preferences by care setting, and regional regulatory cluster heterogeneity across the projection horizon. CAGRs derived from logarithmic trend fitting to historical volume trajectories, adjusted for pipeline probability-weighted launch timing. Forecast inputs incorporated histopathologist talent scarcity constraints on trial site activation and payer evidence requirement evolution for histological endpoints.
Revisions become necessary when FDA guidance finalization on cell and gene therapies accelerates or delays, EMA notified body processing backlogs extend beyond current baselines, or recombinant protein manufacturing capacity constraints intensify cost-of-goods inflation. Practitioners should monitor ANVISA regulatory pathway developments in Brazil and MFDS device review channel activity in South Korea for early signals of geographic demand shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Odontogenic Tumor Market