
 Global Vascular Injury Treatment Market | 2026-2036
Global Vascular Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Injury Treatment Market Foresight
The global pool of fellowship-trained vascular surgeons is collapsing under demographic retirement curves and stagnant training pipeline outputs. Medtronic leverages its integrated endovascular portfolio to sustain leadership across catheter-based intervention platforms. Boston Scientific Corporation anchors its position through specialized stent and embolic agent development for peripheral artery trauma. Abbott Laboratories differentiates via hemostatic device innovation that addresses uncontrolled bleeding in emergency settings.
Vascular injury treatment encompasses the surgical and endovascular management of arterial and venous trauma, including stent deployment, graft interposition, and embolization procedures performed under fluoroscopic or open visualization. These interventions restore perfusion, control hemorrhage, and prevent limb loss following penetrating or blunt mechanical damage to the vasculature. Stents and vascular grafts occupy the largest product segments, reflecting established reimbursement and repeat intervention requirements. Embolic agents represent the fastest-growing category, driven by expanding utilization in trauma-related hemorrhage control. Hemostatic devices concentrate margin pools in military and civilian trauma center procurement channels where speed-to-hemorrhage-control determines clinical outcomes.
The FDA's breakthrough device designation shapes competitive timelines for novel hemostatic and endovascular platforms seeking accelerated market access. EMA's Medical Device Regulation imposes clinical evidence requirements that filter market entry for graft and stent manufacturers targeting European trauma centers. Japan's PMDA maintains distinct approval pathways for catheter-based intervention devices that influence regional product availability. Stakeholders must monitor how dual carbon goals in China's MEE framework affect polymer supply chains for synthetic bypass conduits and resorbable embolic materials.
Market Dynamics
Trauma centers are consolidating endovascular capabilities as fellowship-trained vascular surgeons retire faster than training programs replenish supply, forcing hospitals to recalibrate service line economics around catheter-based hemorrhage control.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines compress commercialization cycles for novel hemostatic platforms targeting uncontrolled bleeding scenarios.
- Japan's PMDA pathway modernization:Streamlined catheter-based intervention approvals expand regional availability of stent and embolic agent portfolios.
- Dual carbon goals in China's MEE framework:Polymer supply chain investments for resorbable embolic materials and synthetic bypass conduits attract domestic manufacturing capacity.
Market Restraints
- Petrochemical feedstock volatility:Synthetic graft polymer prices fluctuate with crude oil derivatives, compressing margins on high-volume bypass conduit sales.
- European MDR clinical evidence requirements:EMA's expanded premarket data demands extend timelines for graft and stent manufacturers targeting trauma centers.
- Autologous vein harvest substitution:Saphenous vein bypass remains preferred for young trauma patients with long life expectancy, limiting synthetic graft penetration in specific demographics.
Strategic Opportunities
- Germany's specialized training infrastructure:Heidelberg and Munich vascular surgery programs produce interventionists capable of advanced endovascular trauma management, creating concentrated demand pockets.
- Military-civilian technology transfer:Battlefield hemostatic innovations from US Army research channels enter civilian Level I trauma center procurement streams.
- Telemedicine-enabled prehospital triage:Real-time vascular surgery consultation during ambulance transport compresses time-to-intervention metrics in rural United States markets.
Industry Challenges
- Fellowship pipeline contraction:Vascular surgery residency positions fail to offset boomer-generation retirements, creating acute staffing shortages at high-volume trauma centers.
- Fluoroscopy suite capex requirements:Hybrid operating room installations demand capital allocations that strain community hospital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Injury Treatment Market |
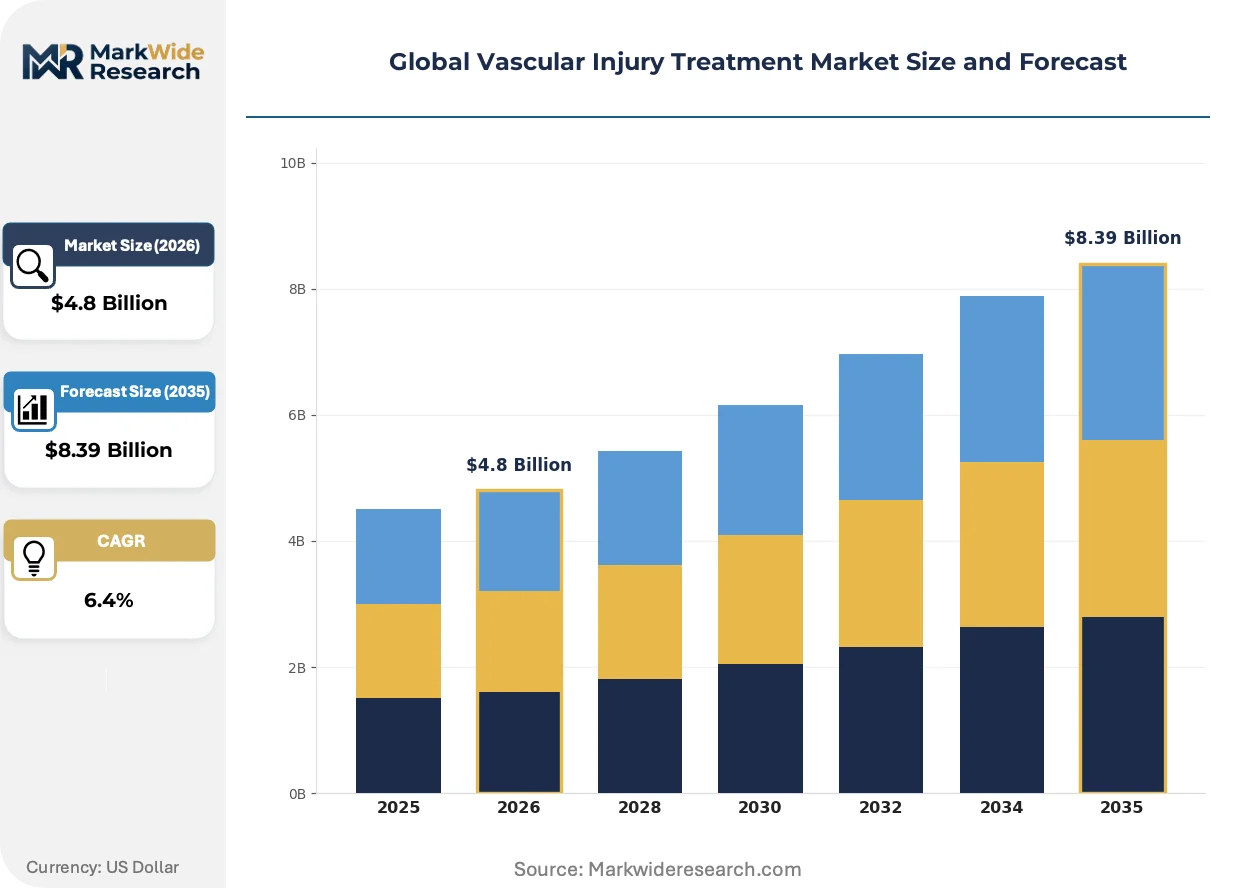
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Vascular Grafts, Embolic Agents, Hemostatic Devices, Bypass Conduits Therapy Area: Peripheral Artery Trauma, Cerebrovascular Accidents, Venous Injuries, Aortic Ruptures, Limb Ischemia End User: Trauma Centers, Specialized Clinics, Surgical Hospitals, Emergency Units, Rehabilitation Facilities Delivery Mode: Minimally Invasive Procedures, Open Surgery, Endovascular Therapy, Catheter-Based Intervention, Percutaneous Techniques |
| Companies Covered | Medtronic, Boston Scientific Corporation, Cardinal Health, Teleflex, Becton Dickinson and Company, 3M, Abbott Laboratories, W L Gore & Associates, LeMaitre Vascular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Injury Treatment Market Shifts & Advancements
Catheter-based platforms are compressing the therapeutic window for hemorrhage control while regulatory pathways fragment across major jurisdictions, forcing manufacturers to architect parallel approval strategies.
Resorbable embolic agents are displacing permanent coil systems in splenic and hepatic trauma applications. Level I trauma centers in the United States and Germany are adopting these platforms within eighteen months of commercial availability. The shift is compressing repeat intervention rates and altering long-term follow-up economics for trauma surgery departments.
EMA's Medical Device Regulation imposes clinical evidence thresholds that filter market entry for European trauma centers. Manufacturers must generate prospective registry data beyond traditional bench testing and animal studies. Graft and stent portfolios face extended validation timelines, favoring incumbents with existing European clinical footprints over new market entrants.
Outcome-based purchasing is reshaping procurement at US civilian trauma centers and military treatment facilities. Bundled payment structures for complex vascular trauma are displacing fee-for-service itemization. The Veterans Health Administration and select German university hospitals are piloting these models, with performance metrics tied to limb salvage rates and thirty-day readmission thresholds.
Global Vascular Injury Treatment Market Segmentation
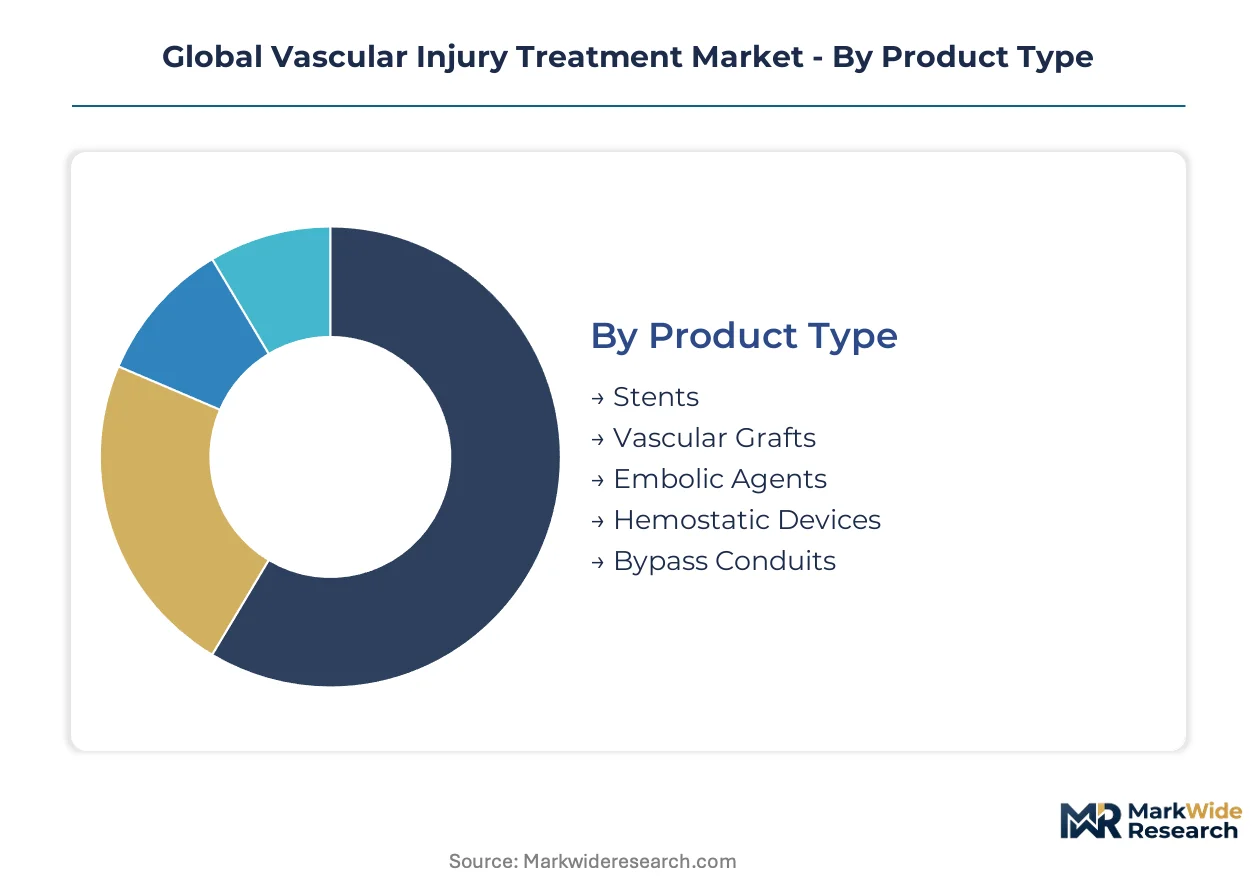
Product differentiation in vascular injury treatment follows distinct margin architectures across implantable devices, procedural approaches, and care settings. Understanding where value concentrates within each dimension enables targeted portfolio allocation and reimbursement strategy.
Product Type:
Margin pools concentrate in devices requiring repeat intervention and specialized surgical training, with permanent implants commanding premium pricing over resorbable alternatives.
- Stents:Self-expanding nitinol and balloon-expandable platforms restore arterial patency following blunt or penetrating trauma. Demand clusters at Level I trauma centers in the United States and Germany where hybrid operating room infrastructure supports fluoroscopic deployment.
- Vascular Grafts:Polyester and expanded polytetrafluoroethylene conduits bridge segmental arterial defects when primary repair fails. Procurement concentrates in surgical hospitals with established vascular surgery service lines, constrained by petrochemical feedstock volatility affecting synthetic polymer costs.
- Embolic Agents:Coils, particles, and liquid embolics occlude bleeding vessels in splenic and hepatic trauma. Resorbable formulations are displacing permanent systems in trauma centers prioritizing reduced long-term follow-up burden.
- Hemostatic Devices:Topical agents and intravascular sealants control hemorrhage in emergency settings. Military and civilian trauma center procurement channels drive volume where speed-to-hemorrhage-control determines clinical outcomes.
- Bypass Conduits:Autologous vein and synthetic alternatives restore perfusion in limb-threatening injuries. Saphenous vein harvest remains preferred for young trauma patients with extended life expectancy, limiting synthetic penetration in specific demographics.
The dominant share belongs to stents and vascular grafts, while embolic agents are closing the gap fastest through expanding trauma applications.
Therapy Area:
Procedure complexity and reimbursement intensity vary sharply across anatomical territories, with central vascular injuries commanding higher episode payments than peripheral trauma.
- Peripheral Artery Trauma:Femoral and popliteal injuries from penetrating mechanisms require urgent revascularization to prevent limb loss. Endovascular approaches are compressing open surgical volumes at trauma centers with catheter-based capabilities.
- Cerebrovascular Accidents:Carotid and vertebral artery trauma demands specialized neurointerventional expertise concentrated at academic medical centers. Japan's PMDA pathway modernization is expanding regional device availability for these complex cases.
- Venous Injuries:Iliac and femoral vein trauma management balances hemorrhage control against thromboembolic risk. Ligation tolerance exceeds arterial equivalents, altering device selection patterns.
- Aortic Ruptures:Thoracic and abdominal trauma requires emergent endovascular or open repair with high per-procedure resource consumption. Outcome-based purchasing pilots at select German university hospitals are reshaping procurement economics.
- Limb Ischemia:Revascularization urgency distinguishes viable from non-salvageable extremities following vascular trauma. Time-to-intervention metrics drive prehospital triage innovation including telemedicine-enabled consultation in rural United States markets.
Peripheral artery trauma generates the highest procedure volume, though aortic ruptures deliver the steepest expansion trajectory through endovascular platform adoption.
End User:
Capital intensity and case acuity stratify purchasing power across the care continuum, with concentrated trauma infrastructure commanding preferential pricing and early technology access.
- Trauma Centers:Level I and II designated facilities manage the most complex vascular injuries with 24-hour surgical coverage. Fellowship pipeline contraction is forcing recalibration of service line economics around catheter-based hemorrhage control.
- Specialized Clinics:Outpatient vascular surgery centers handle delayed reconstruction and follow-up interventions. These settings prioritize cost efficiency over acute capability.
- Surgical Hospitals:Community facilities with vascular surgery programs manage stable trauma transfers and elective revascularization. Hybrid operating room capex requirements strain capital budgets.
- Emergency Units:Initial stabilization and hemorrhage control precede definitive repair. Hemostatic device utilization concentrates here where speed determines outcomes.
- Rehabilitation Facilities:Post-acute care addresses functional recovery following limb salvage procedures. Long-term anticoagulation management and graft surveillance create recurring device demand.
Trauma centers anchor absolute spending, while specialized clinics are gaining share fastest through outpatient procedure migration.
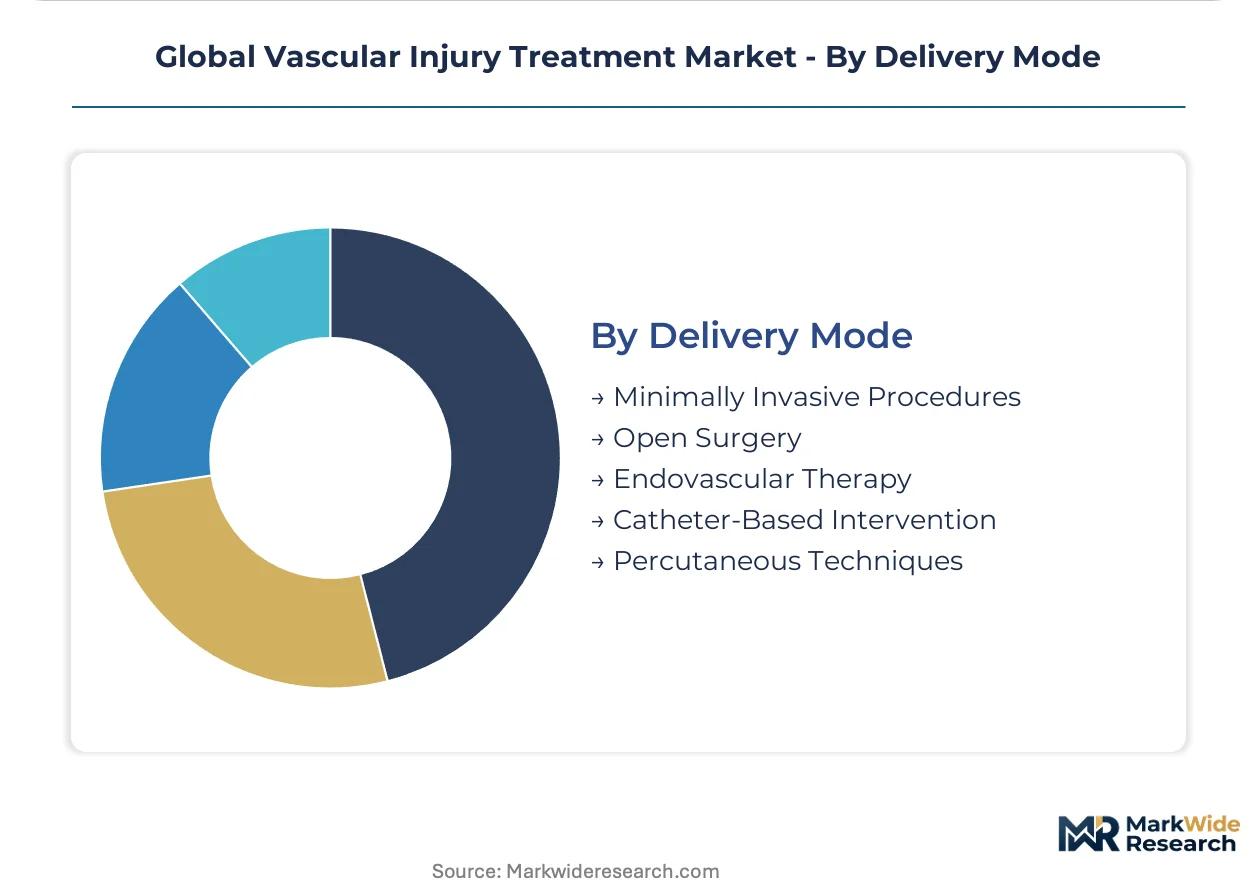
Delivery Mode:
Technical capability requirements and reimbursement differentiation favor minimally invasive approaches where infrastructure investment permits, though open surgery retains essential indications.
- Minimally Invasive Procedures:Small-incision techniques reduce physiological insult in polytrauma patients. Equipment standardization across catheter laboratories and hybrid suites enables platform economics.
- Open Surgery:Direct vessel exposure remains necessary for extensive soft tissue injury or failed endovascular rescue. Autologous vein harvest and graft interposition demand microsurgical expertise.
- Endovascular Therapy:Fluoroscopically guided stent deployment and embolization compress therapeutic windows for hemorrhage control. FDA breakthrough device designation is accelerating commercial timelines for novel platforms.
- Catheter-Based Intervention:Transfemoral and transbrachial access routes enable remote vessel manipulation without surgical exposure. Training program outputs limit procedure availability outside major academic centers.
- Percutaneous Techniques:Closed vascular access methods minimize access site complications. Ultrasound guidance is expanding operator pools beyond fellowship-trained specialists.
Endovascular therapy holds the dominant position, with catheter-based intervention expanding most quickly as trauma centers consolidate fluoroscopy capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where specialized training infrastructure commands premium device procurement, while Japan and China compete on volume through pathway modernization and domestic manufacturing scale.
United States
Level I trauma centers in Baltimore and Houston drive concentrated demand for hybrid operating room infrastructure and catheter-based hemorrhage control platforms. The FDA's breakthrough device designation accelerates commercial timelines for novel hemostatic technologies seeking accelerated market access. Military-civilian technology transfer from US Army research channels at Brooke Army Medical Center in San Antonio feeds directly into civilian procurement streams.
Germany
Heidelberg and Munich vascular surgery programs produce fellowship-trained interventionists capable of advanced endovascular trauma management, creating concentrated demand pockets for stent and embolic agent portfolios. EMA's Medical Device Regulation imposes clinical evidence requirements that filter market entry for graft manufacturers targeting European trauma centers. Outcome-based purchasing pilots at university hospitals in Berlin are reshaping procurement economics around limb salvage metrics.
Japan
PMDA pathway modernization is expanding regional availability of catheter-based intervention devices for carotid and vertebral artery trauma cases concentrated at academic medical centers in Tokyo and Osaka. The regulator's streamlined approvals for stent platforms reduce commercial friction compared to historical timelines. Kobe and Nagoya clusters specialize in fluoroscopy suite manufacturing for domestic trauma center installation.
China
Dual carbon goals in the MEE framework are redirecting polymer supply chain investments toward resorbable embolic materials and synthetic bypass conduits with domestic manufacturing scale in Shanghai and Shenzhen. The NMPA maintains distinct clinical trial requirements for endovascular platforms that influence regional product sequencing. Beijing-Tianjin trauma corridors are consolidating catheter-based capabilities as training program outputs expand.
Global Vascular Injury Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vascular injury treatment landscape. The market structure consolidates around integrated endovascular portfolios, specialized stent developers, and hemostatic device innovators. Three strategic archetypes dominate: diversified medtech conglomerates with catheter-based platforms, focused vascular surgery specialists, and emergency hemorrhage control innovators. Competitive moves center on M&A for technology integration and strategic partnerships for training program co-development.
Among diversified medtech conglomerates, Medtronic, Boston Scientific Corporation, and Abbott Laboratories occupy positions that exemplify distinct competitive vectors. Medtronic anchors the integrated endovascular portfolio archetype through its breadth across catheter-based intervention platforms. Boston Scientific Corporation represents the specialized stent and embolic agent development track for peripheral artery trauma applications. Abbott Laboratories sits within the hemostatic device innovation tier, addressing uncontrolled bleeding scenarios in emergency settings where speed-to-intervention determines clinical outcomes.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Cardinal Health |
| Teleflex |
| Becton Dickinson and Company |
| 3M |
| Abbott Laboratories |
| W L Gore & Associates |
| LeMaitre Vascular |
| Others |
Supply & Pricing Matrix
Resorbable embolic agents replacing permanent coil systems simultaneously shifts manufacturing gravity toward polymer-specialist hubs in Germany and Japan while compressing long-term follow-up pricing premiums previously captured by repeat intervention models. This substitution dynamic reconfigures procurement economics as trauma centers prioritize reduced surveillance burden over device durability.
Pricing Analysis
The customization-premium spread separates standard nitinol stent configurations from patient-specific fenestrated grafts requiring 3D-printed manufacturing workflows. Pricing stratifies across premium, standard, and economy tiers where FDA breakthrough designation commands tier-one positioning, CE-MDR certification filters mid-tier European access, and domestic Chinese manufacturing anchors economy positioning for NMPA-approved platforms. Cost compression in synthetic graft polymers stems from petrochemical feedstock volatility, pressuring margins on high-volume bypass conduit sales. Military procurement channels exhibit lowest price sensitivity due to speed-to-hemorrhage-control mandates, while community surgical hospitals face acute capital constraints on hybrid operating room installations.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time fluoroscopy suite component replenishment at Level I trauma centers and strategic stockpiling of hemostatic devices by military medical logistics commands. Manufacturing concentrates in the United States for FDA-designated breakthrough devices, Germany for EMA-MDR-compliant graft portfolios, and China for resorbable polymer production serving domestic NMPA pathways. Raw material dependencies encompass nitinol shape-memory alloys, expanded polytetrafluoroethylene membranes, and resorbable poly-lactic-co-glycolic acid polymers. Single-source vulnerability concentrates in specialized nitinol melting capacity. Distribution runs through GPO contracts at civilian trauma centers and direct military procurement channels for battlefield hemorrhage control platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
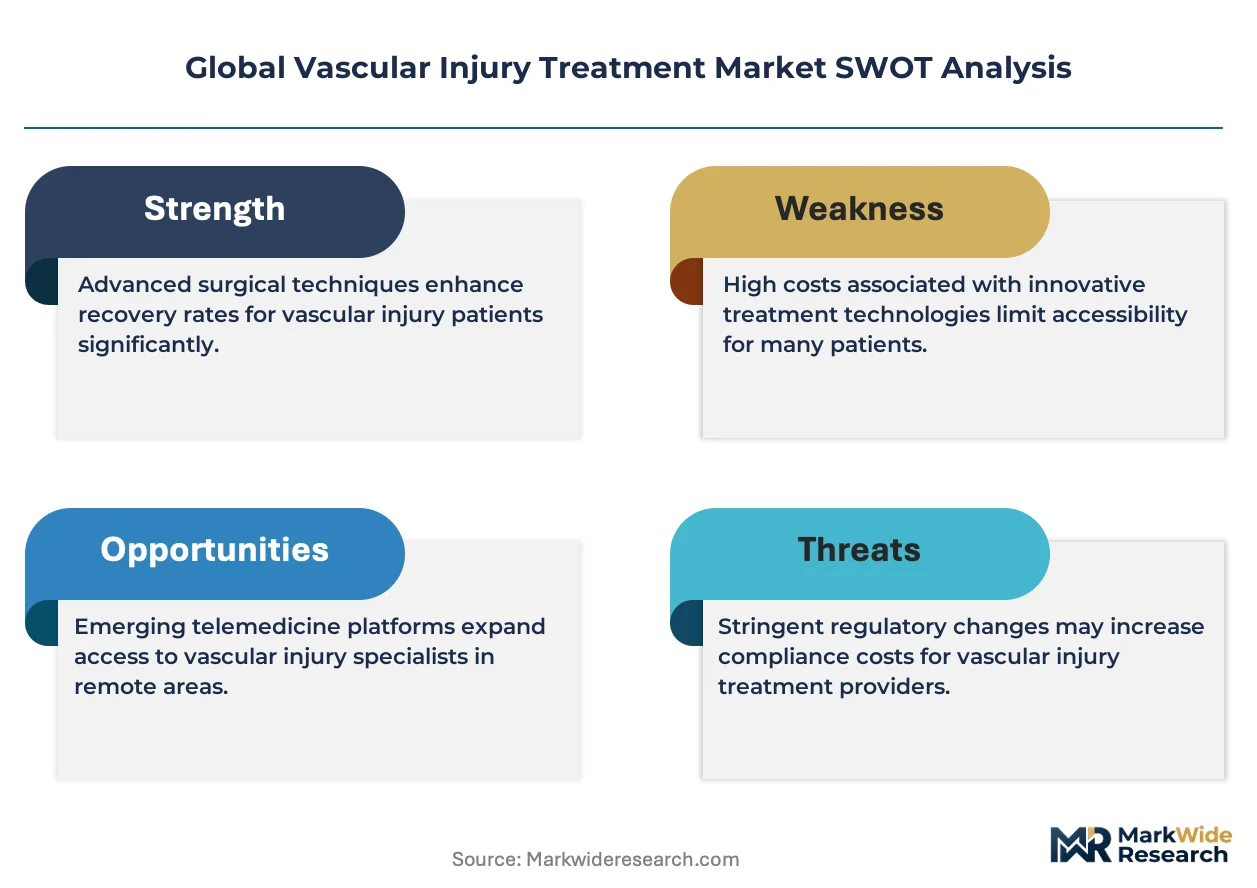
This market functions as a defensive-moat story where regulatory entrenchment through FDA breakthrough designation and EMA MDR clinical evidence requirements creates substantial barriers against unproven entrants.
For Market Incumbents: Fortify market position by deepening backward integration into nitinol alloy production and expanding captive polymer synthesis capacity in Germany to offset petrochemical volatility. Prioritize reimbursement strategy investment for outcome-based purchasing pilots at Veterans Health Administration and German university hospitals, as bundled payment structures threaten traditional fee-for-service itemization. Channel control through exclusive hybrid operating room equipment leasing arrangements locks out emerging stent competitors. For New Entrants and Emerging Players: Differentiate on resorbable formulation chemistry for splenic trauma applications where permanent coil displacement creates immediate white-space opportunity. Target China's Beijing-Tianjin trauma corridor where NMPA pathway modernization and domestic manufacturing scale advantages enable rapid market entry against import-dependent incumbents. Pursue military-civilian technology transfer partnerships with US Army research channels as the most penetrable procurement vector for novel hemostatic platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated endovascular portfolio owners over single-product specialists. Long-term viability over the coming decade rests on catheter-based platform breadth capable of spanning hemorrhage control through definitive revascularization. Acquisition target archetype: focused vascular surgery specialists with established European clinical footprints and existing MDR technical documentation. Watch FDA breakthrough designation grant velocity as the signal indicating competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization cycles for novel hemostatic platforms. |
| CE Marking Pathway Investment | EMA MDR clinical evidence requirements filter market entry for European trauma centers. |
| Hospital System Partnership | Level I trauma center procurement consolidation favors vendors with integrated catheter portfolios. |
| Software Companion Development | Telemedicine-enabled prehospital triage expands addressable market into rural United States corridors. |
| Reimbursement Strategy | Outcome-based purchasing pilots at German university hospitals reshape procurement economics. |
Research Methodology
Cross-validation between primary interviews with vascular surgeons, trauma center purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down market sizing triangulation reconcile demand estimates across the analysis window.
Sensitivity analysis tested forecast robustness across petrochemical price volatility scenarios, fellowship pipeline contraction rates, and regulatory pathway modernization timelines. Segmentation dimensions encompassed product type, therapy area, end user, and delivery mode with regional regulatory cluster differentiation. CAGRs derive from procedure volume growth trajectories, device ASP evolution, and replacement cycle dynamics for resorbable versus permanent implants. Forecast inputs incorporated hybrid operating room installation rates and military-civilian technology transfer velocity.
Material uncertainties — regulatory pathway delays, polymer supply disruptions, and training pipeline collapse — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued endovascular capability expansion at Level I trauma centers and stable reimbursement for catheter-based hemorrhage control. Revision becomes warranted when fellowship-trained vascular surgeon retirement rates exceed training program replacement capacity by thresholds that force trauma center service line closures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market