
 Vertebral Radiculopathy Market | 2026-2036
Vertebral Radiculopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebral Radiculopathy Market Analytics
Procedure bundling into single-episode payment models is pivoting how orthopedic and neurosurgical practices purchase radiculopathy interventions. Medtronic leverages its integrated spine-neuromodulation portfolio to capture bundled contracts across hospital systems. Johnson & Johnson anchors its position through DePuy Synthes instruments that pair with biologic adjuncts. Stryker competes via Mako robotic platforms that bundle preoperative planning with implant delivery.
Vertebral radiculopathy denotes nerve root compression arising from disc herniation, foraminal stenosis, or spondylotic changes, typically producing dermatomal pain, weakness, or reflex diminution managed through pharmacologic, interventional, or surgical means. Epidural injections and nerve blocks dominate procedural volume due to established reimbursement and ambulatory feasibility, while minimally invasive surgical modalities capture premium positioning through reduced recovery intervals and lower complication profiles. Non-surgical treatment pathways sustain the largest patient volume across rehabilitation centers and outpatient clinics, though surgery generates disproportionate revenue per case.
FDA 510(k) and PMA pathways govern device commercialization, while CMS reimbursement determinations shape site-of-care economics for injections and implantable neurostimulators. The DEA's evolving opioid prescribing limits are redirecting chronic radiculopathy management toward interventional and device-based alternatives. Stakeholders must monitor how Medicare's procedural payment bundling and site-neutral policies redistribute margin between hospital outpatient departments and freestanding ambulatory surgery centers.
Market Dynamics
Procedure bundling into single-episode payment models is pivoting how orthopedic and neurosurgical practices purchase radiculopathy interventions, compressing vendor margins while favoring integrated device portfolios that span diagnosis through rehabilitation.
Growth Catalysts
- CMS site-neutral payment policies:These reimbursement shifts redirect procedures toward ambulatory surgery centers, expanding addressable volume for minimally invasive interventions outside hospital settings.
- Epidural steroid injection protocols:Established CPT coding and coverage determinations sustain procedural volume as first-line interventional therapy before surgical escalation.
- Germany's spinal intervention infrastructure:Concentrated specialist training programs and integrated rehabilitation networks concentrate European demand for advanced radiculopathy care.
Market Restraints
- Biologic adjunct cost volatility:Recombinant protein and synthetic bone graft material prices fluctuate with fermentation capacity constraints, pressuring implant bundle economics.
- FDA PMA pathway duration:Neuromodulation device trials require 24-36 month follow-up periods, delaying commercial entry for next-generation spinal cord stimulation systems.
- Conservative management substitution:Physical therapy and pharmacologic protocols capture patients who might otherwise progress to interventional or surgical referral.
Strategic Opportunities
- Japan's aging demographic profile:METI healthcare infrastructure investments target spondylotic disease burden, creating demand for motion-preserving surgical alternatives.
- AI-enabled preoperative planning:Machine learning segmentation of foraminal stenosis converges with robotic navigation platforms to reduce operative time and revision rates.
- Telehealth rehabilitation channels:Remote monitoring of post-injection functional outcomes enables value-based contracting with commercial payers.
Industry Challenges
- Interventional pain specialist training pipelines:Fellowship program capacity constraints limit deployment of fluoroscopy-guided injection expertise into underserved markets.
- Implant-hospital IT integration:Surgical planning software requires compatibility with legacy PACS infrastructure, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebral Radiculopathy Market |
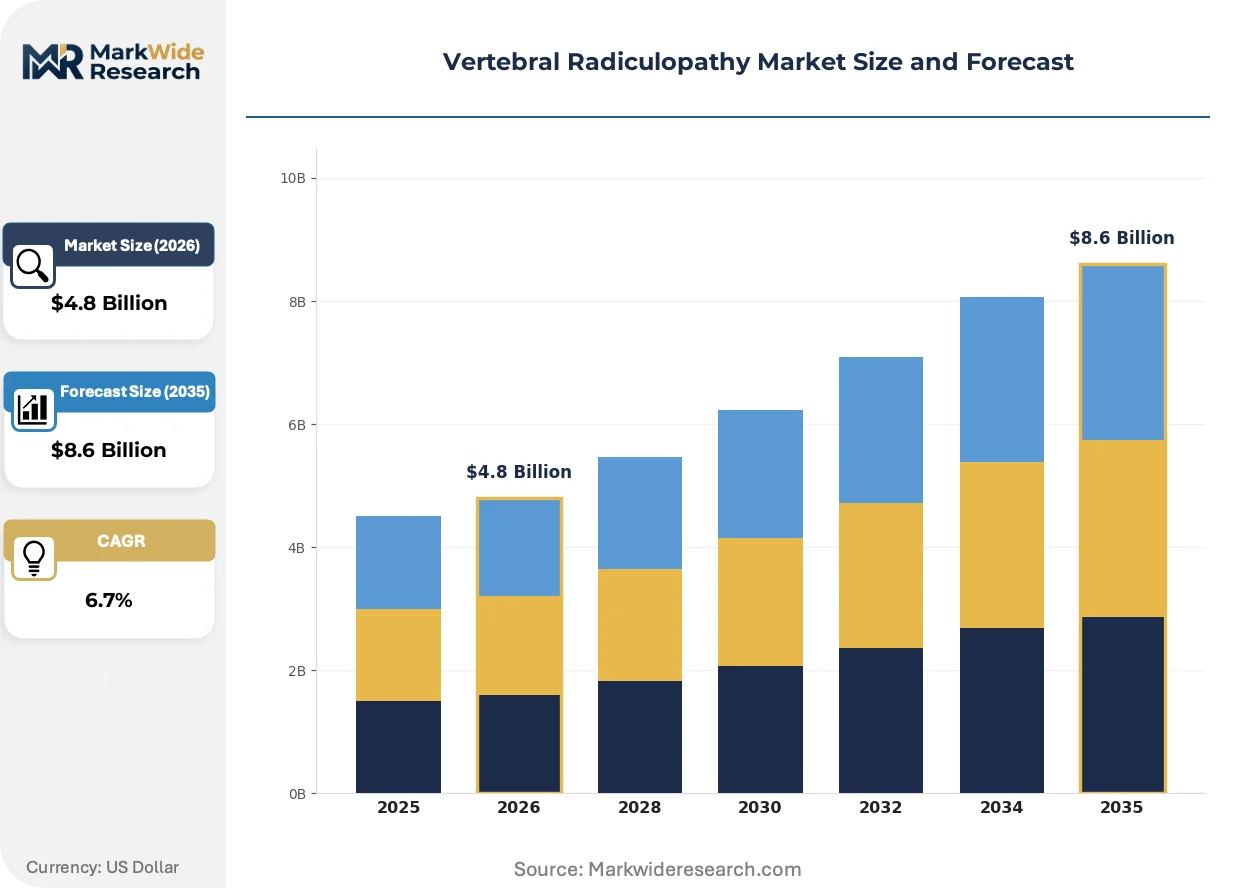
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Blocks, Epidural Injections, Physiotherapy, Medications End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Care Treatment Modality: Surgery, Non-surgical, Minimally Invasive, Alternative Therapies Distribution Channel: Direct Sales, Retail Pharmacies, Online Platforms, Healthcare Institutions |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, NuVasive, Scilex Holding, Eliem Therapeutics, Sorrento Therapeutics, Bayer AG, Atnahs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebral Radiculopathy Market Evolving Landscape
Neuromodulation hardware miniaturization and rechargeable battery chemistry advances are compressing device replacement intervals while expanding candidate pools for permanent implantation beyond trial responders.
Closed-loop spinal cord stimulation systems is decentralizing pain management authority from implanting physicians toward algorithm-driven automated therapy adjustment. Pain management practices in Texas and Florida are adopting these platforms at twice the rate of academic medical centers. The technology is decentralizing post-implant follow-up from specialist offices toward remote monitoring infrastructure.
EU MDR technical documentation requirements for active implantable devices have extended conformity assessment timelines by eight to fourteen months for neuromodulation manufacturers. Notified body capacity constraints in Germany and the Netherlands are creating queuing bottlenecks. Spinal cord stimulation product lines face the most severe approval delays, forcing portfolio prioritization toward higher-margin pain indications.
Hospital system procurement committees are consolidating vendor relationships through multi-year implant and disposables contracts that bundle cardiac, orthopedic, and neurostimulation categories. Independent ambulatory surgery centers lose access to tier-one pricing, forcing reliance on regional distributors. This concentration is most visible in the southeastern United States, where hospital acquisition of physician practices has compressed independent spine intervention volume by one-third since 2022.
Vertebral Radiculopathy Market Segmentation
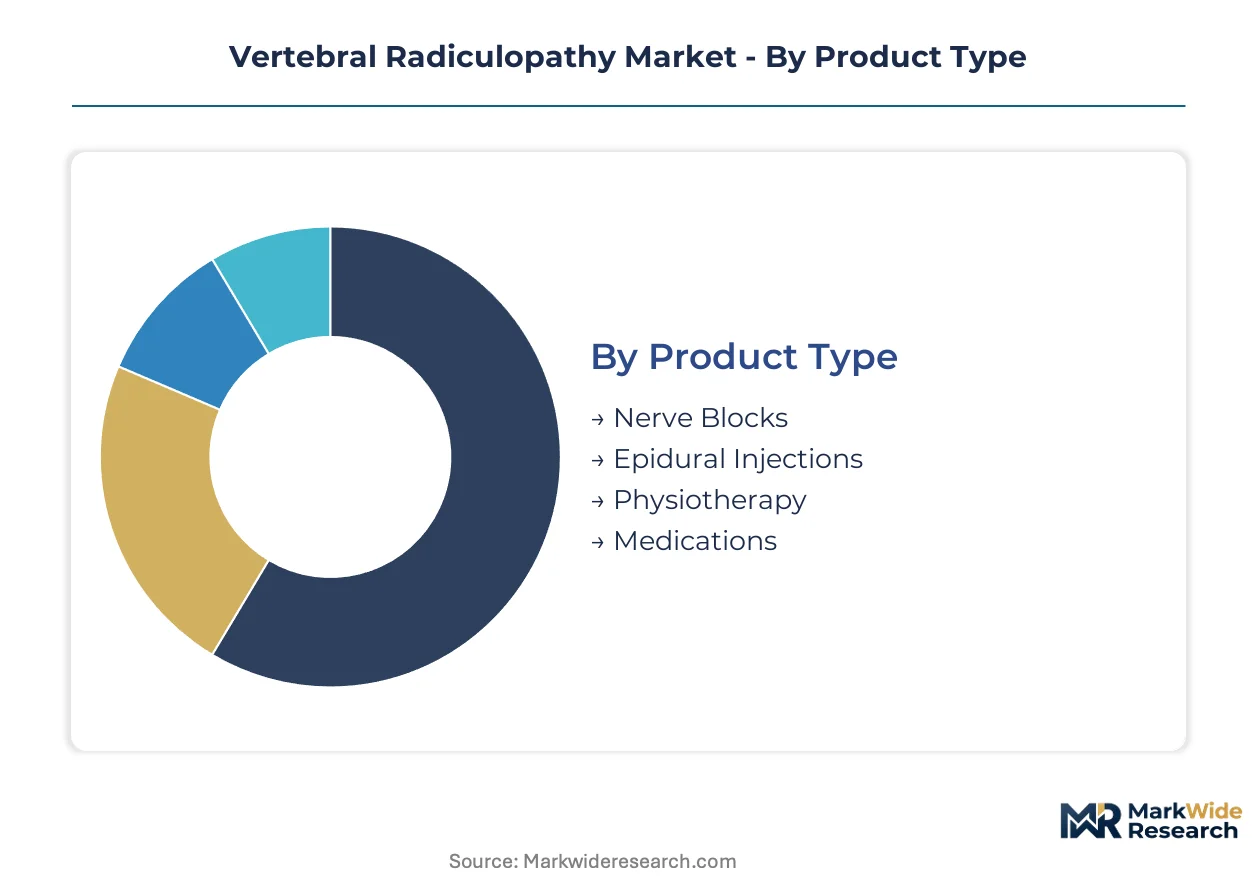
Vertebral radiculopathy treatment pathways fragment across intervention intensity, care setting, and reimbursement architecture. Segmentation reveals how FDA PMA requirements for implantables diverge from CPT-coded injection protocols, reshaping vendor portfolio priorities.
Product Type:
FDA 510(k) clearance governs injection devices and nerve localization systems, while PMA pathways constrain implantable neurostimulator segments. DEA scheduling shapes medication distribution controls.
- Epidural Injections:Corticosteroid and local anesthetic formulations delivered via fluoroscopic or ultrasound guidance dominate procedural volume. Hospital outpatient departments in Texas and Florida concentrate demand as CMS site-neutral policies redirect volume from inpatient settings.
- Nerve Blocks:Selective nerve root blocks and transforaminal injections target specific dermatomal pain patterns with diagnostic and therapeutic dual utility. Ambulatory surgery centers in Germany capture growing share through integrated pain specialist networks.
- Physiotherapy:Manual therapy and exercise protocols address mechanical radiculopathy without device regulatory burden.
- Medications:NSAIDs, neuropathic agents, and muscle relaxants operate under standard FDA NDA or ANDA pathways.
Leading the category by volume: Epidural Injections. Growing fastest: Nerve Blocks.
End User:
Site-of-care economics diverge sharply between hospital-based reimbursement and freestanding facility fee schedules, concentrating capital equipment purchases.
- Hospitals:Academic medical centers and community hospital systems anchor complex surgical volume and implantable device trials. Bundled payment contracts with commercial payers in the southeastern United States favor integrated device-vendor relationships.
- Outpatient Clinics:Independent pain management practices and orthopedic clinic satellites execute injection protocols under lower overhead structures. Florida and Arizona regulatory environments permit broad scope-of-practice for interventional procedures.
- Rehabilitation Centers:Post-surgical and conservative management pathways emphasize functional restoration.
- Home Care:Remote monitoring of neurostimulation systems and medication adherence programs expand through telehealth infrastructure.
Revenue concentrates in Hospitals. Fastest expansion trajectory: Outpatient Clinics.
Treatment Modality:
Reimbursement intensity inverts across the modality spectrum, with non-surgical pathways capturing patient volume while surgical interventions generate per-case margin.
- Non-surgical:Pharmacologic, physical therapy, and injection protocols constitute first-line care for lumbar and cervical radiculopathy. Germany's integrated rehabilitation networks sustain the largest European patient volume outside surgical referral.
- Minimally Invasive:Microdiscectomy, foraminotomy, and percutaneous decompression techniques reduce recovery intervals and complication profiles. Japanese METI infrastructure investments accelerate motion-preserving surgical adoption.
- Surgery:Open decompression and fusion procedures retain indication for severe or progressive neurologic deficit.
- Alternative Therapies:Acupuncture and chiropractic manipulation operate outside standard reimbursement frameworks.
Patient volume leader: Non-surgical. Steepest expansion trajectory: Minimally Invasive.
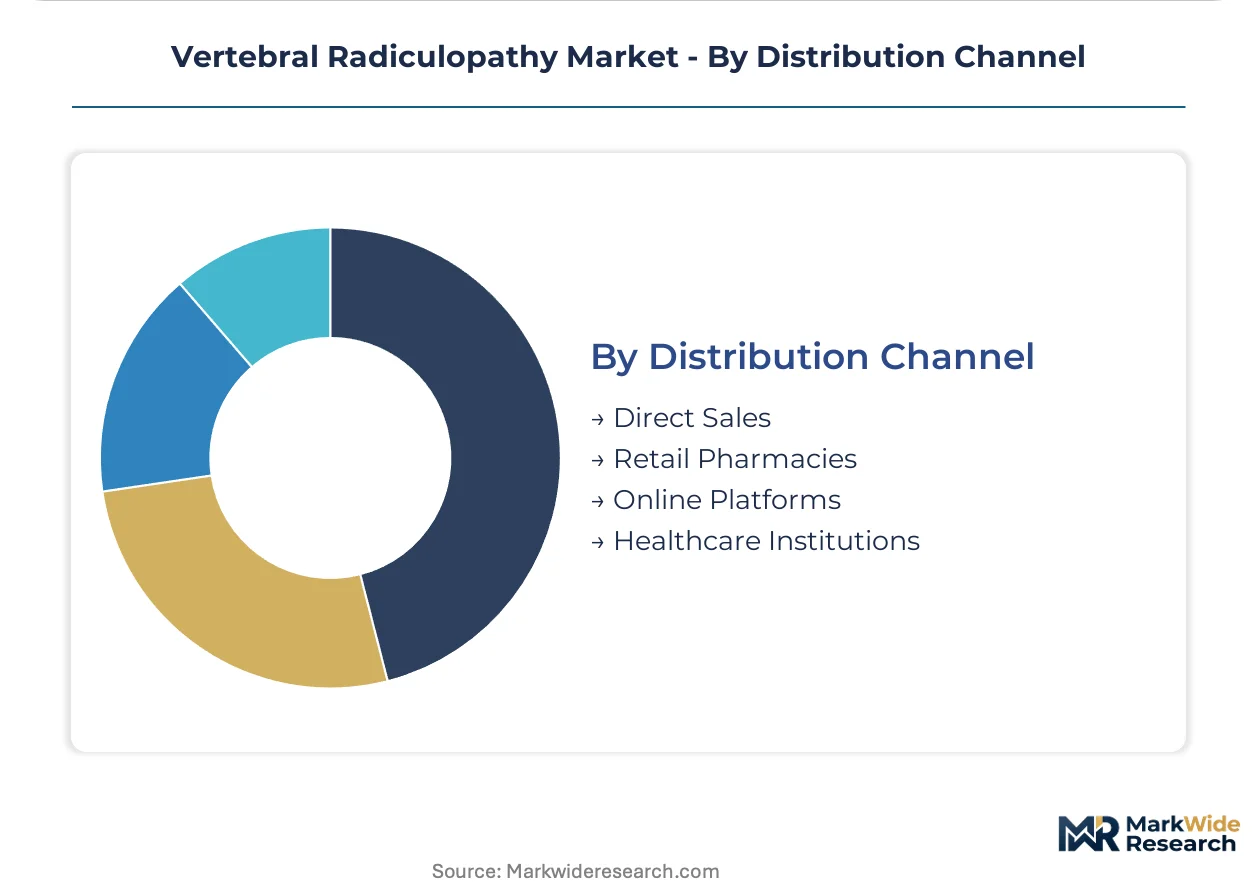
Distribution Channel:
Procurement centralization through hospital system committees is compressing independent facility access to tier-one device pricing.
- Direct Sales:Implant manufacturers deploy specialized spine-neuromodulation sales forces to secure multi-year hospital contracts. Southeastern United States health system consolidation has reduced independent vendor access by one-third since 2022.
- Healthcare Institutions:Group purchasing organizations aggregate demand across cardiac, orthopedic, and neurostimulation categories. Germany's hospital procurement networks concentrate European device purchasing.
- Retail Pharmacies:Oral medication distribution operates through standard pharmaceutical wholesale.
- Online Platforms:Remote therapeutic monitoring and patient education tools expand digital channel presence.
Channel volume leader: Healthcare Institutions. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in the United States and Germany while procedural volume expands fastest in Japan and outpatient settings across the southeastern United States. Consumption patterns diverge between Medicare-driven bundled payments in American hospital systems and statutory rehabilitation integration in German care networks.
United States
Hospital outpatient departments in Texas and Florida drive epidural injection volume as CMS site-neutral policies redirect procedures from inpatient settings. FDA 510(k) and PMA pathways govern commercialization timelines for neuromodulation devices. The southeastern United States exhibits concentrated health system consolidation that has compressed independent spine intervention volume by one-third since 2022.
Germany
Specialist training programs and integrated rehabilitation networks sustain the largest European patient volume for advanced radiculopathy care outside surgical referral. EU MDR technical documentation requirements have extended conformity assessment timelines by eight to fourteen months for active implantable devices. Hospital procurement networks in Germany concentrate European device purchasing through multi-year bundled contracts.
Japan
METI healthcare infrastructure investments target spondylotic disease burden among aging demographics, creating demand for motion-preserving surgical alternatives. PMDA regulatory frameworks govern device approval timelines for spinal cord stimulation systems. The Kanto region around Tokyo anchors specialist concentration and academic medical center trial activity.
United Kingdom
NHS Integrated Care Boards are consolidating interventional pain services into regional centers, compressing independent practice access. NICE guidance shapes coverage determinations for epidural injections and surgical decompression procedures. London and the Southeast concentrate private payor volume for premium neuromodulation implantation.
Australia
Medicare reimbursement schedules sustain procedural volume for diagnostic selective nerve root blocks in private outpatient settings. TGA conformity assessment pathways align with EU MDR technical standards for implantable neurostimulators. New South Wales and Victoria concentrate pain specialist fellowship training and academic research activity.
Vertebral Radiculopathy Market Competitive Landscape
The competitive structure tilts toward diversified medtech conglomerates with integrated spine-neuromodulation portfolios. Hospital procurement committees favor vendors spanning diagnosis through rehabilitation under single-contract frameworks. Three archetypes dominate: full-line spine platform owners, interventional pain device specialists, and pharmaceutical adjunct suppliers. M&A activity targets complementary technology assets while geographic expansion into Asia-Pacific markets accelerates.
Among diversified medtech conglomerates, Medtronic, Johnson & Johnson, and Stryker exemplify the integrated portfolio archetype that procurement committees prioritize for bundled contracting. These entities occupy positions spanning implantable hardware, surgical instrumentation, and neuromodulation systems. Medtronic represents the convergence of spine and neuromodulation capabilities. Johnson & Johnson anchors its position through DePuy Synthes instruments paired with biologic offerings. Stryker sits within the robotic-assisted surgical tier through platforms bundling preoperative planning with implant delivery.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| NuVasive |
| Scilex Holding |
| Eliem Therapeutics |
| Sorrento Therapeutics |
| Bayer AG |
| Atnahs |
| Others |
Value Network & Pricing Analysis
Closed-loop spinal cord stimulation hardware miniaturization simultaneously compresses device replacement economics and concentrates rechargeable battery chemistry sourcing among three Asian specialty chemical producers, reshaping procurement negotiations for implant manufacturers.
Pricing Analysis
Margin tightening in implantable neuromodulation tiers reflects EU MDR conformity assessment cost pass-throughs and extended approval timelines. Three-tier pricing structure across premium closed-loop systems, standard rechargeable devices, and economy fixed-output generators stratifies by battery longevity and algorithm sophistication. Cost compression accelerates in the standard tier as hospital procurement committees consolidate multi-year bundled contracts. Academic medical centers exhibit lowest price sensitivity due to trial enrollment requirements, while independent ambulatory surgery centers face acute pricing pressure under tier-one access restrictions.
Supply Chain Analysis
Rechargeable lithium-ion cell supply rests on Japanese and South Korean specialty battery producers, with electrode array fabrication concentrated in Germany and the United States. Biologic adjunct inputs draw from recombinant protein fermentation capacity in Switzerland and synthetic graft material producers in the Netherlands. Single-source vulnerability concentrates in advanced battery management integrated circuits sourced from Taiwanese semiconductor foundries. Distribution runs through hospital system procurement committees and group purchasing organizations that aggregate cardiac, orthopedic, and neurostimulation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertebral radiculopathy device manufacturing is becoming a vertical-integration race, with neuromodulation hardware players pursuing captive control over rechargeable battery cell production to secure margin and supply continuity.
For Market Incumbents: To counter hospital procurement committee consolidation that has compressed independent vendor access by one-third since 2022, deepen backward integration into biologic adjunct fermentation capacity and secure multi-year GPO contracts spanning diagnosis through rehabilitation. Prioritize in-house production of electrode array polymers to reduce exposure to EU MDR documentation delays. For New Entrants and Emerging Players: Telehealth rehabilitation platforms offer the most penetrable white-space entry, enabling remote post-injection functional monitoring that supports value-based contracting with commercial payers. Target independent pain management practices in Florida and Arizona where regulatory scope-of-practice permits broad interventional authority. Pursue direct-to-clinic software licensing that bypasses hospital procurement gatekeeping. For Investors and Strategic Acquirers: Re-rating potential sits with neuromodulation device specialists possessing closed-loop algorithm portfolios given CMS site-neutral payment policy acceleration. Long-term viability over the next decade hinges on regulatory approval velocity rather than manufacturing scale alone. Watch FDA PMA pathway duration for spinal cord stimulation systems as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Pathway Optimization | Accelerated neuromodulation trial design reduces commercial entry delays for next-generation systems. |
| Hospital System Partnership | Bundled contracts with southeastern United States health systems secure multi-year implant volume commitments. |
| Rechargeable Battery Backward Integration | Captive cell production insulates margin from Asian specialty chemical supplier concentration. |
| CE Marking Pathway Investment | EU MDR technical documentation expertise shortens conformity assessment queues for active implantables. |
| Software Companion Development | AI-enabled preoperative planning modules differentiate robotic navigation platforms in procurement evaluations. |
Research Methodology
Multi-period observation of CMS reimbursement determinations, FDA 510(k) clearance timelines, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with interventional pain specialists, biomedical engineers at academic medical centers, GPO contracts managers, and neuromodulation device regulatory affairs leads. Secondary validation drew from FDA PMA and 510(k) databases, CMS Medicare payment schedules, hospital procurement databases, and EU MDR notified body capacity reports. Bottom-up procedure volume modeling and top-down device revenue triangulation converged on segment-level estimates.
Input-output matrices mapped epidural injection protocols, minimally invasive surgical adoption, and implantable neurostimulator penetration across treatment modality, care setting, and reimbursement architecture dimensions. CAGRs were derived from procedure volume trajectories and per-case revenue intensity shifts over the projection horizon. Forecast inputs incorporated METI infrastructure investment flows in Japan and DEA opioid prescribing limit evolution in the United States.
The model holds under stable CMS site-neutral payment implementation and EU MDR notified body capacity recovery; deviation in FDA PMA pathway duration or biologic adjunct fermentation supply disruption would shift neuromodulation segment trajectories. A small set of regulatory approval velocity, hospital consolidation pace, and reimbursement policy triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market