
 Seasonal Allergy Market | 2026-2036
Seasonal Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Seasonal Allergy Market Analytics
European pharmaceutical manufacturing is consolidating around immunotherapy production hubs. Sanofi leverages its biologics infrastructure to sustain leadership in sublingual allergy tablets. GlaxoSmithKline anchors respiratory portfolios with nasal corticosteroid formulations. Johnson & Johnson competes through private-label dominance in North American retail channels.
Seasonal allergy comprises the physiological immune response to airborne pollen from trees, grasses, and weeds, mediated by immunoglobulin E antibodies triggering histamine release from mast cells; commercial products target H1 receptor antagonism, mast cell stabilization, or corticosteroid-mediated inflammation suppression to enable symptom management during defined pollen periods. Antihistamines represent the most mature revenue pool with established OTC distribution, while nasal sprays command premium positioning through prescription-to-OTC transition pathways. Injection-based immunotherapy occupies the highest-margin tier despite limited patient penetration, and prevention-oriented applications are expanding fastest as allergen forecasting services integrate with digital pharmacy platforms.
FDA OTC monograph reforms and EMA centralized marketing authorization procedures shape product access timelines across developed markets, with the former accelerating switch approvals and the latter harmonizing bioequivalence standards for generic entrants. The EPA's expanded pollen monitoring mandates indirectly stimulate diagnostic application demand by validating localized allergen burden data. Stakeholders must weigh immunotherapy pipeline investments against near-term generics erosion in oral antihistamines.
Market Dynamics
The seasonal allergy market pivots on the FDA's accelerated OTC switch pathway, which compresses prescription-to-consumer timelines and restructures competitive moats around distribution reach rather than clinical data exclusivity.
Growth Catalysts
- EPA Pollen Monitoring Mandates:Expanded federal tracking networks validate localized allergen burden data, stimulating diagnostic application demand and preventive purchasing behavior in high-pollen corridors.
- Digital Pharmacy Integration:Allergen forecasting services embed directly into mobile prescription platforms, creating trigger-based replenishment loops that convert episodic buyers into recurring revenue streams.
- Sublingual Immunotherapy Formulations:European EMA centralized marketing authorization harmonizes bioequivalence standards, enabling cross-border tablet distribution and reducing manufacturer regulatory duplication costs.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Second-generation antihistamine raw material synthesis clusters in Chinese and Indian chemical manufacturing zones, exposing formulators to geopolitical supply interruptions.
- Generic Erosion in Oral Antihistamines:Patent cliff dynamics for loratadine and cetirizine molecules compress branded pricing power and divert R&D capital toward biologic alternatives.
- Immunotherapy Administration Burden:Subcutaneous injection protocols require clinical supervision infrastructure that limits patient penetration in rural and underserved primary care markets.
Strategic Opportunities
- Pediatric Indication Expansion:Unmet need in allergen immunotherapy for children under 12 creates first-mover advantage for sublingual tablet formulations with demonstrated safety profiles.
- Climate-Driven Pollen Season Extension:Lengthening tree and grass pollen periods across the US Midwest and Southeast expand addressable symptom days and drive stockpiling behavior.
- Retail Self-Care Aisle Expansion:Pharmacy chains dedicate linear footage to allergy management categories, creating shelf-space scarcity that rewards early category captains with prime positioning.
Industry Challenges
- Allergy Specialist Workforce Constraints:Board-certified allergist density varies dramatically by metropolitan statistical area, creating diagnostic bottlenecks that delay immunotherapy initiation.
- Cold Chain Integrity for Biologics:Temperature-sensitive monoclonal antibody formulations require specialized distribution infrastructure that elevates logistics costs and limits pharmacy participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seasonal Allergy Market |
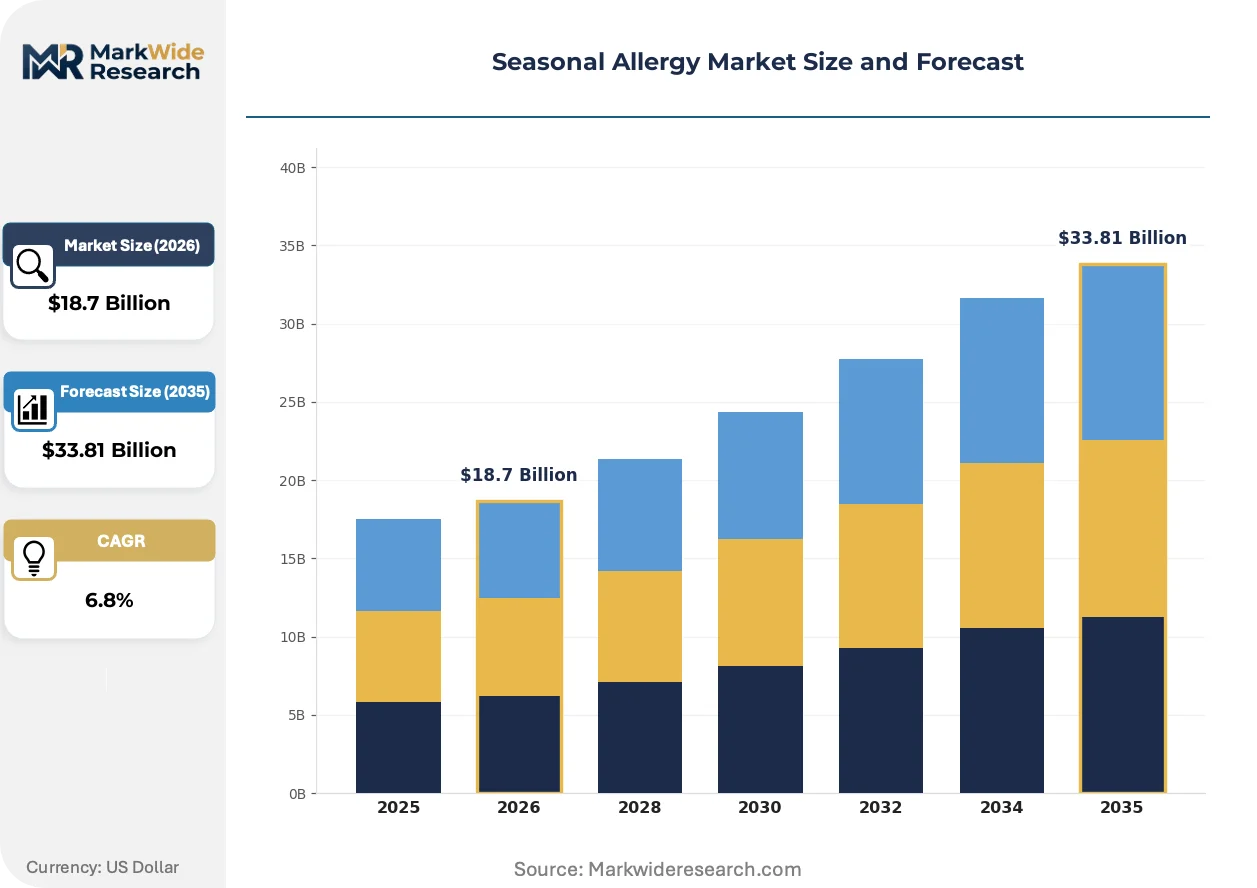
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Nasal Sprays, Eye Drops, Decongestants Delivery Mode: Oral, Nasal, Topical, Injection End User: Individuals, Clinics, Pharmacies, Hospitals Application: Symptom Relief, Prevention, Diagnostics, Maintenance |
| Companies Covered | Sanofi, GlaxoSmithKline, Johnson & Johnson, Bayer, Kenvue, Novartis, ALK-Abello, STALLergenes Greer, Haleon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seasonal Allergy Market Evolving Landscape
Digital biomarker integration and predictive health platforms are restructuring how consumers anticipate and intercept allergic responses before symptom onset.
Sublingual allergy immunotherapy tablets are expanding into mainstream preventive care protocols previously dominated by injection-based desensitization. Primary care physicians in integrated delivery networks adopt these formulations to retain patients within system-owned pharmacies. The technology is expanding into employer-sponsored wellness programs as a mechanism to reduce absenteeism-related productivity losses.
EMA centralized marketing authorization procedures harmonize generic bioequivalence standards across EU member states, compressing time-to-market for non-innovator entrants. This regulatory convergence eliminates redundant national filing requirements and accelerates price competition in nasal corticosteroid categories. Southern European markets with historically slower national approval timelines experience the most pronounced access improvements.
Consumer purchasing patterns increasingly favor subscription-based replenishment models over episodic retail visits. Digital pharmacy platforms displace traditional drugstore foot traffic by integrating pollen count APIs with automated shipping triggers. This behavioral shift concentrates most visibly in coastal US metropolitan areas with high smartphone penetration and established same-day delivery infrastructure.
Seasonal Allergy Market Segmentation
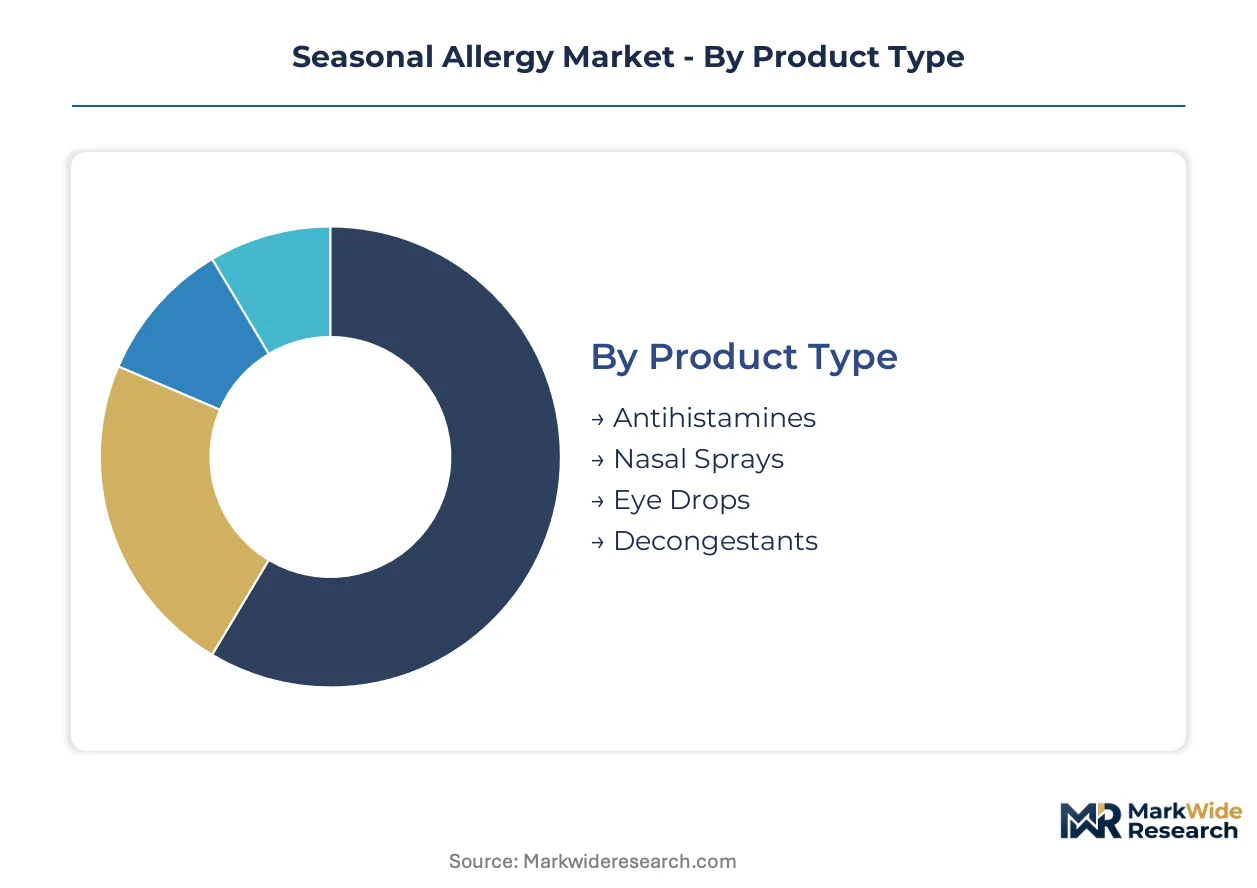
Segmentation in seasonal allergy therapeutics reveals how formulation chemistry, administration convenience, and care setting economics partition patient flows across competing modalities. Product type and delivery mode together determine reimbursement pathways and retail shelf positioning.
Product Type:
Supply concentration in oral antihistamine APIs shapes competitive dynamics across all four product categories, with Indian and Chinese chemical manufacturers controlling key intermediate synthesis.
- Antihistamines:Second-generation H1 receptor antagonists dominate prescription and OTC channels through once-daily dosing profiles. Demand concentrates in United States retail pharmacies where FDA OTC switch approvals have expanded self-care access without physician gatekeeping.
- Nasal Sprays:Corticosteroid formulations command premium positioning through localized inflammation suppression with minimal systemic exposure. United States demand clusters in the Southeast and Midwest where extended pollen seasons drive preventive stocking behavior.
- Eye Drops:Mast cell stabilizers and dual-action antihistamine formulations address ocular pruritus and conjunctival injection. These products capture episodic purchasers seeking targeted relief beyond systemic therapy.
- Decongestants:Sympathomimetic vasoconstrictors provide short-term nasal patency restoration with documented rebound rhinitis limitations. Pseudoephedrine purchase restrictions in United States jurisdictions channel demand toward phenylephrine alternatives with contested efficacy profiles.
Antihistamines absorb the bulk of installed capacity; nasal sprays are expanding most quickly through prescription-to-OTC transition pathways.
Delivery Mode:
Cost tier differentiation separates mass-market oral tablets from premium biologic injections requiring cold chain infrastructure and specialist administration.
- Oral:Tablet and liquid formulations achieve highest patient penetration through pharmacy distribution and household stockpiling. United States consumers in high-pollen corridors maintain seasonal inventory reserves triggered by pollen count alerts.
- Nasal:Metered-dose pumps deliver topical corticosteroids and antihistamines with rapid onset and limited systemic absorption. These products gain share in employer-sponsored wellness programs seeking absenteeism reduction.
- Topical:Ophthalmic and dermal preparations address localized symptoms with minimal drug-drug interaction risk. Demand concentrates among polypharmacy populations requiring symptom-specific intervention.
- Injection:Subcutaneous immunotherapy and monoclonal antibody administration requires clinical supervision infrastructure. United States metropolitan markets with adequate allergist density support this highest-margin tier despite rural access limitations.
Oral delivery captures the greatest prescription volume; injection modalities command the steepest expansion trajectory through biologic pipeline progression.
End User:
Volume concentration in direct-to-consumer channels is displacing institutional procurement as digital pharmacy platforms capture replenishment loyalty.
- Individuals:Self-directed purchasers drive OTC category growth through mobile-integrated pollen forecasting and automated subscription replenishment. United States coastal metropolitan areas with same-day delivery infrastructure exhibit highest platform adoption.
- Clinics:Primary care and allergy specialty practices initiate immunotherapy protocols and prescription nasal corticosteroid therapy. These settings face workforce constraints that limit subcutaneous injection penetration in underserved markets.
- Pharmacies:Retail chains and digital dispensaries compete for category captaincy through dedicated linear footage and personalized allergen alerts. Shelf-space scarcity rewards early movers with prime positioning.
- Hospitals:Emergency departments manage acute allergic presentations and anaphylaxis protocols requiring epinephrine and corticosteroid intervention. This channel represents smallest volume share due to episodic utilization patterns.
Individual purchasers absorb the bulk of transaction volume; pharmacy channels are gaining share fastest through digital integration.
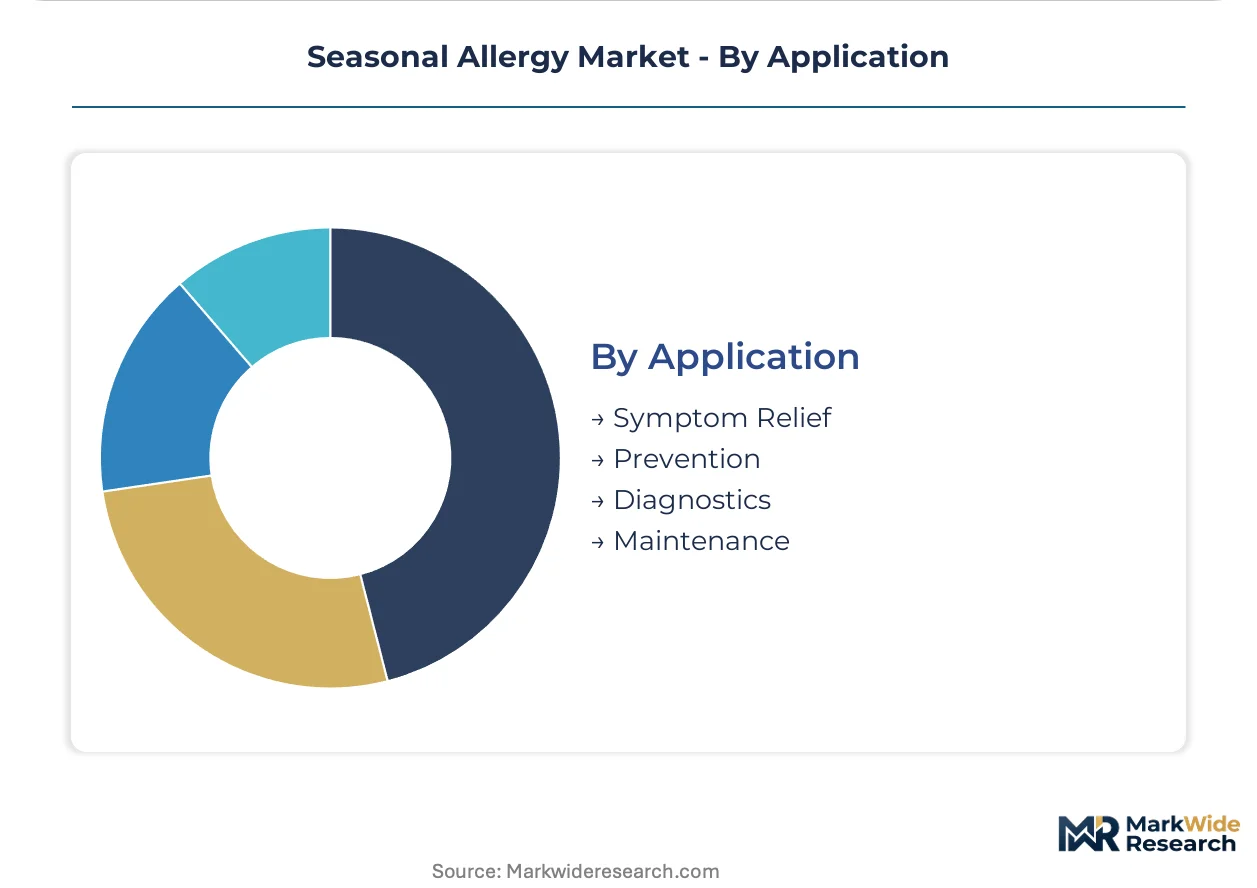
Application:
Maturity gradients separate established symptomatic relief from emerging preventive and diagnostic modalities requiring patient education investment.
- Symptom Relief:Reactive treatment of rhinitis, conjunctivitis, and dermatitis represents the most mature revenue pool with established OTC distribution. United States demand peaks during regional pollen maxima with predictable seasonal patterns.
- Prevention:Pre-season immunotherapy initiation and prophylactic antihistamine loading expand addressable symptom days. Climate-driven pollen season extension across the Midwest and Southeast amplifies preventive purchasing windows.
- Diagnostics:Skin prick testing and serum-specific IgE assays identify sensitization profiles to guide therapeutic selection. EPA pollen monitoring mandates stimulate demand by validating localized allergen burden data.
- Maintenance:Long-term immunotherapy protocols and chronic rhinitis management require sustained patient adherence. Sublingual tablet formulations reduce administration burden and support primary care retention strategies.
Symptom relief absorbs the bulk of current expenditure; prevention applications are climbing the fastest as digital biomarker integration enables pre-symptom intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for second-generation antihistamines clusters in Chinese and Indian chemical manufacturing zones, exposing finished dose formulators to geopolitical supply interruptions while European immunotherapy production consolidates around specialized biologics hubs.
United States
Extended pollen seasons across the Midwest and Southeast expand addressable symptom days and drive preventive stocking behavior. EPA pollen monitoring mandates validate localized allergen burden data, stimulating diagnostic application demand. The Research Triangle Park corridor in North Carolina anchors sublingual immunotherapy tablet manufacturing for domestic distribution.
Germany
EMA centralized marketing authorization procedures harmonize bioequivalence standards for generic nasal corticosteroid entrants. The country's national pharmaceutical regulator accelerates prescription-to-OTC switch timelines for established antihistamine molecules. The Rhine-Main biopharma cluster around Frankfurt sustains leadership in subcutaneous immunotherapy formulation development.
India
CDSCO streamlined approval pathways for fixed-dose combination antihistamines attract multinational licensing agreements. The country's national pharmaceutical regulator enforces tightened good manufacturing practice inspections for API export facilities. Hyderabad and Ahmedabad chemical manufacturing zones dominate loratadine and cetirizine intermediate synthesis for global formulators.
Japan
PMDA abbreviated review pathways for second-generation antihistamines with established overseas safety profiles compress market entry timelines. METI industrial policy directs investment toward pollen forecasting digital infrastructure integration. The Kansai pharmaceutical corridor around Osaka specializes in ophthalmic allergy drop formulation for Asian export markets.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated OTC switch decisions for nasal corticosteroids previously under prescription control. NHS England allergy service specifications expand sublingual immunotherapy access in primary care settings. The Cambridge-London life sciences corridor hosts biologics manufacturing for monoclonal antibody pipeline candidates.
Seasonal Allergy Market Competitive Landscape
Global majors compete with regional champions across distribution reach and immunotherapy specialization tiers. The market structures around three concentration nodes: multinational pharmaceutical conglomerates with respiratory portfolios, European biologics specialists with sublingual tablet platforms, and private-label dominant consumer health divisions. Strategic moves center on prescription-to-OTC switch execution and sublingual immunotherapy primary care adoption.
Within the multinational conglomerate tier, Sanofi, GlaxoSmithKline, and Johnson & Johnson occupy positions defined by manufacturing infrastructure scale and retail channel penetration depth. Sanofi exemplifies biologics-forward positioning through sublingual allergy tablet platforms. GlaxoSmithKline anchors respiratory portfolio concentration around nasal corticosteroid formulations. Johnson & Johnson represents private-label dominance archetypes in North American retail channel competition.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Johnson & Johnson |
| Bayer |
| Kenvue |
| Novartis |
| ALK-Abello |
| STALLergenes Greer |
| Haleon |
| Others |
Value Network & Pricing Analysis
EPA pollen monitoring mandates gate qualified supply for premium-tier allergen forecasting services and immunotherapy platforms, restricting market access to vendors with validated environmental data partnerships and certified clinical distribution infrastructure. This sustainability-linked qualification separates premium-positioned sublingual tablet manufacturers from economy-tier antihistamine suppliers dependent on undifferentiated API sourcing.
Pricing Analysis
Service bundling distinguishes premium sublingual immunotherapy platforms with integrated patient adherence monitoring from unbundled OTC antihistamine transactions. Three-tier pricing structure across premium, standard, and economy levels reflects bioequivalence certification status and cold chain capability investment. Cost compression in oral antihistamines intensifies because patent cliff dynamics for loratadine and cetirizine molecules divert R&D capital toward biologic alternatives. Retail pharmacy chains exhibit highest price sensitivity through private-label sourcing, while allergy specialists demonstrate lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
Domestic-content mandates in Indian pharmaceutical manufacturing reshape API sourcing patterns for multinational formulators seeking CDSCO export certification. Loratadine and cetirizine intermediate synthesis concentrates in Hyderabad and Ahmedabad chemical zones, with finished dose formulation drawing from European biologics hubs and North American respiratory manufacturing corridors. Single-source vulnerability in Chinese and Indian API production exposes formulators to geopolitical supply interruptions. Distribution runs through retail pharmacy chains with dedicated allergy category linear footage and digital pharmacy platforms with automated replenishment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API synthesis capacity bottlenecks in Indian and Chinese chemical manufacturing zones prop pricing power for qualified suppliers with diversified production footprints and regulatory certification depth.
For Market Incumbents: To counter generic erosion in oral antihistamines, Sanofi and GlaxoSmithKline should deepen backward integration into sublingual tablet biologics manufacturing and secure exclusive pollen forecasting data partnerships with EPA monitoring networks. Channel control through retail category captaincy and R&D investment in pediatric immunotherapy indications provide defensive moats against patent cliff revenue compression. For New Entrants and Emerging Players: A mid-tier price-point gap between premium sublingual immunotherapy and economy antihistamines creates entry space for digital-native allergy platforms with subscription-based preventive care bundling. Employer-sponsored wellness programs in high-pollen US corridors represent the most penetrable segment. Direct-to-consumer launch with pollen count API integration and automated shipping triggers captures replenishment loyalty from episodic retail purchasers. For Investors and Strategic Acquirers: FDA OTC switch approval acceleration for second-generation antihistamines is the leading indicator that prescription-to-consumer transition timelines will compress further, rewarding platforms with established retail distribution infrastructure. Over the projection horizon, vertically integrated mid-scale specialists with captive API supply and EMA centralized marketing authorization capability present optimal acquisition profiles. Watch for EPA pollen monitoring mandate expansion as the signal for diagnostic application demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Execution | FDA accelerated pathways compress timelines and restructure competitive moats around distribution reach. |
| Sublingual Immunotherapy Scale-Up | EMA centralized authorization harmonizes bioequivalence standards across EU member states for tablet distribution. |
| Digital Pharmacy Platform Integration | Pollen count APIs with automated shipping triggers convert episodic buyers into recurring revenue streams. |
| Pediatric Indication Expansion | Unmet need in allergen immunotherapy for children under 12 creates first-mover advantage for tablet formulations. |
| API Supply Diversification | Domestic-content mandates in Indian manufacturing reshape sourcing patterns for multinational formulators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases provided validation. Bottom-up patient flow modeling and top-down revenue reconciliation ensured cross-verification.
Data-stream reconciliation across product type, delivery mode, end user, and application segmentation dimensions structured the analytical framework. CAGRs were derived from patient volume trajectories, pricing elasticity coefficients, and regulatory approval timelines over the projection horizon. Pollen season extension patterns and digital pharmacy adoption curves served as industry-specific forecast inputs.
Inputs from EPA monitoring databases and EMA centralized authorization records were available through the study window; gaps in real-time patient adherence data from sublingual immunotherapy programs introduce uncertainty bands around preventive application growth assumptions. Forecasts reflect documented assumptions regarding OTC switch velocity and climate-driven pollen season extension. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market