
 Histamine Toxicity Market | 2026-2036
Histamine Toxicity Market Size, Share, and Industry Trends Forecast 2026-2036
Histamine Toxicity Market Foresight
Hospital procurement of histamine toxicity diagnostics is reshaping vendor relationships across North America and Western Europe. Thermo Fisher Scientific leverages its analytical instrument portfolio to anchor laboratory-based histamine detection workflows. Eurofins Scientific competes through specialized food safety and clinical toxicology testing services. Pfizer Inc dominates prescription antihistamine distribution through established pharmacy networks.
Histamine toxicity encompasses adverse physiological responses triggered by elevated histamine levels from spoiled fish, fermented foods, or pharmacological interactions, with scombroid poisoning representing the most common foodborne manifestation characterized by flushing, headache, and gastrointestinal distress within minutes to hours of ingestion. The condition demands rapid diagnostic differentiation from IgE-mediated allergic reactions to guide appropriate therapeutic intervention. Antihistamines command the largest product type position due to immediate symptomatic relief requirements, while enzyme preparations represent the fastest-expanding category as DAO (diamine oxidase) supplementation gains clinical traction for histamine intolerance management. Healthcare providers absorb the dominant end-user share through emergency department presentations, though home users are emerging as a growth vector through direct-to-consumer testing kits and over-the-counter prophylactic supplements.
FDA pharmacovigilance programs and EMA risk management plans shape post-market surveillance obligations for histamine-modulating therapeutics, while ISO 15189 accreditation standards govern clinical laboratory diagnostic accuracy for histamine quantification. The EU F-Gas Regulation indirectly affects cold-chain integrity for histamine-sensitive biologics through refrigerant phase-down requirements. Stakeholders must monitor evolving regulatory divergence between FDA fast-track designations for rare histamine disorders and EMA conditional marketing authorizations to optimize portfolio allocation and clinical trial site selection.
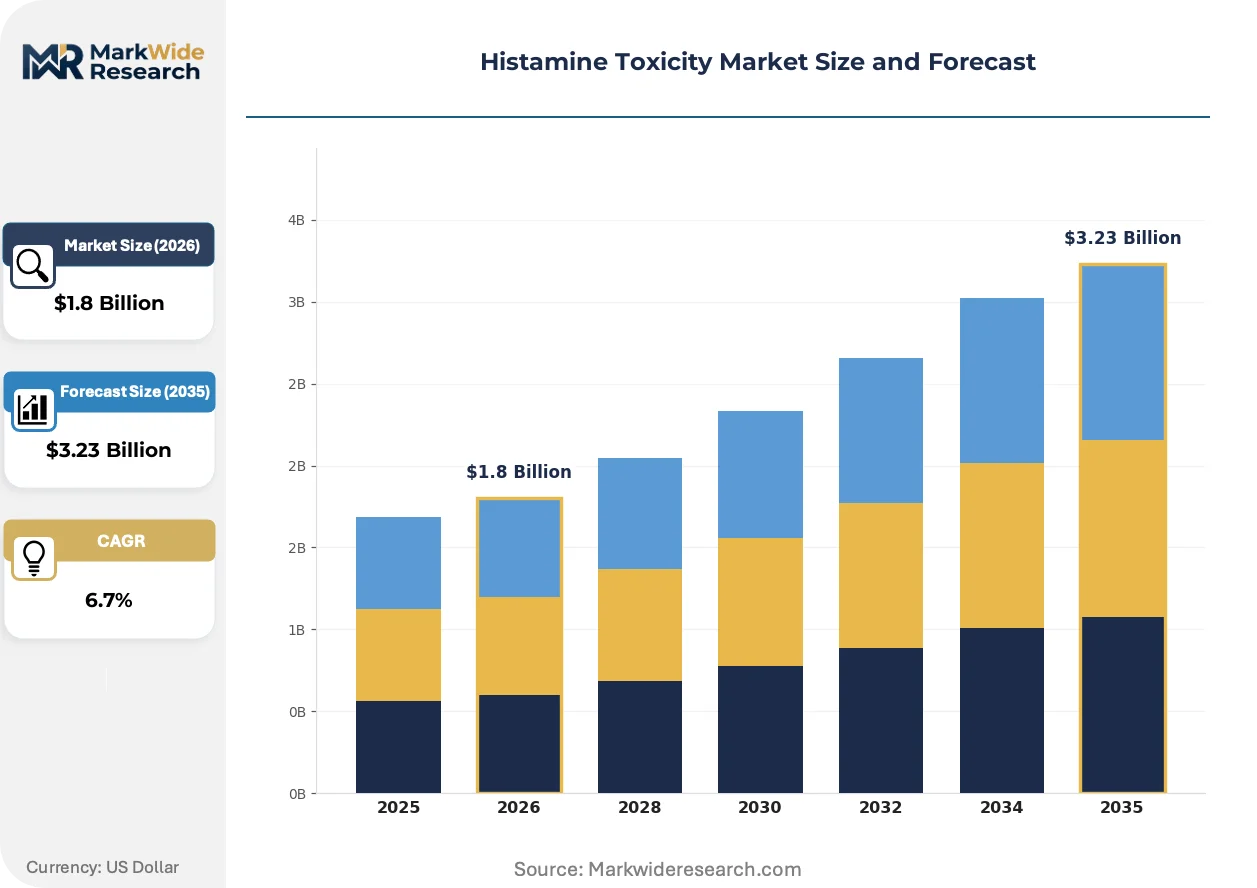
Market Dynamics
FDA pharmacovigilance tightening and EMA post-market surveillance expansion are forcing diagnostic manufacturers and pharmaceutical suppliers to restructure compliance operations around real-world evidence collection and adverse event reporting automation.
Growth Catalysts
- ISO 15189 Accreditation Mandates:Clinical laboratories across Germany, Japan, and the United States face intensifying pressure to achieve standardized histamine quantification protocols, driving replacement demand for certified analytical instruments.
- Emergency Department Protocol Standardization:Hospital networks in urban clusters are embedding rapid histamine toxicity differentiation into acute care workflows, expanding consumable volumes for point-of-care testing platforms.
- Direct-to-Consumer Supplement Channels:DAO enzyme preparations and prophylactic antihistamine formulations are penetrating pharmacy retail and e-commerce platforms, creating parallel demand streams outside traditional prescription pathways.
Market Restraints
- Cold-Chain Input Cost Volatility:The EU F-Gas Regulation refrigerant phase-down requirements are elevating operational costs for histamine-sensitive biologic storage and transportation infrastructure.
- Diagnostic Differentiation Complexity:IgE-mediated allergy testing protocols overlap symptomatically with histamine toxicity presentations, creating reimbursement ambiguity and clinical decision friction in emergency settings.
- Substitute Detection Modalities:Mass spectrometry approaches in centralized reference laboratories threaten to displace immunoassay-based point-of-care devices in high-throughput hospital networks.
Strategic Opportunities
- Home-Based Monitoring Applications:Self-administered histamine testing kits and wearable biomarker sensors are penetrating consumer wellness segments in Japan and Germany, opening subscription revenue models.
- Regulatory Tailwind from FDA Fast-Track:Rare histamine disorder therapeutics qualify for accelerated approval pathways, compressing clinical trial timelines and reducing capital requirements for novel enzyme replacement candidates.
- Technology Convergence:Integration of smartphone-connected lateral flow devices with cloud-based symptom tracking apps is collapsing the feedback loop between detection, diagnosis, and dietary modification.
Industry Challenges
- Specialized Toxicology Skill Scarcity:Clinical laboratories report persistent gaps in histamine quantification expertise, particularly in smaller regional hospital systems lacking dedicated toxicology departments.
- Multi-Jurisdiction Compliance Burden:Divergent FDA and EMA pharmacovigilance reporting timelines force manufacturers to maintain parallel adverse event tracking systems, elevating administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histamine Toxicity Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Antioxidants, Enzyme Preparations, Dietary Supplements Therapy Area: Gastrointestinal Disorders, Allergic Reactions, Chronic Inflammation, Skin Conditions End User: Healthcare Providers, Pharmacies, Research Institutions, Home Users Distribution Channel: Online Stores, Retail Pharmacies, Direct Sales, Hospitals |
| Companies Covered | Travere Therapeutics, Inc., Johnson and Johnson company, Neogen Corporation, PerkinElmer, Thermo Fisher Scientific, Eurofins Scientific, Sanofi Aventis Ltd, Pfizer Inc, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histamine Toxicity Market Shifts & Advancements
Histamine toxicity management is undergoing platform-level transformation as diagnostic miniaturization, regulatory data requirements, and patient-directed care models converge to reshape vendor priorities and buyer expectations.
Point-of-care lateral flow immunoassays with smartphone-readable outputs are collapsing the traditional separation between emergency department triage and outpatient monitoring. Urgent care networks in the United States and specialized allergy clinics in Germany are deploying these devices to compress diagnostic turnaround from hours to minutes. The structural consequence is a redistribution of testing volume away from centralized hospital laboratories toward distributed clinical settings and, increasingly, direct-to-consumer channels.
EMA conditional marketing authorization frameworks and FDA risk evaluation and mitigation strategies are mandating post-approval real-world evidence collection for histamine-modulating therapeutics. Pharmaceutical manufacturers must now embed digital pharmacovigilance infrastructure into product launch planning, elevating data science capabilities alongside traditional clinical affairs functions. Biologics developers targeting rare histamine disorders face the steepest compliance burden, with pediatric and geriatric subpopulations triggering enhanced surveillance obligations.
Specialized allergy clinics and hospital emergency departments are unbundling diagnostic service contracts from therapeutic procurement, enabling standalone testing vendors to capture value previously absorbed by integrated pharmaceutical suppliers. This purchasing pattern shift is most pronounced in Japan's prefectural hospital networks and Germany's ambulatory care centers, where reference laboratory partnerships are displacing captive in-house toxicology capabilities. The fragmentation creates entry points for niche diagnostic specialists lacking legacy pharmacy distribution relationships.
Histamine Toxicity Market Segmentation
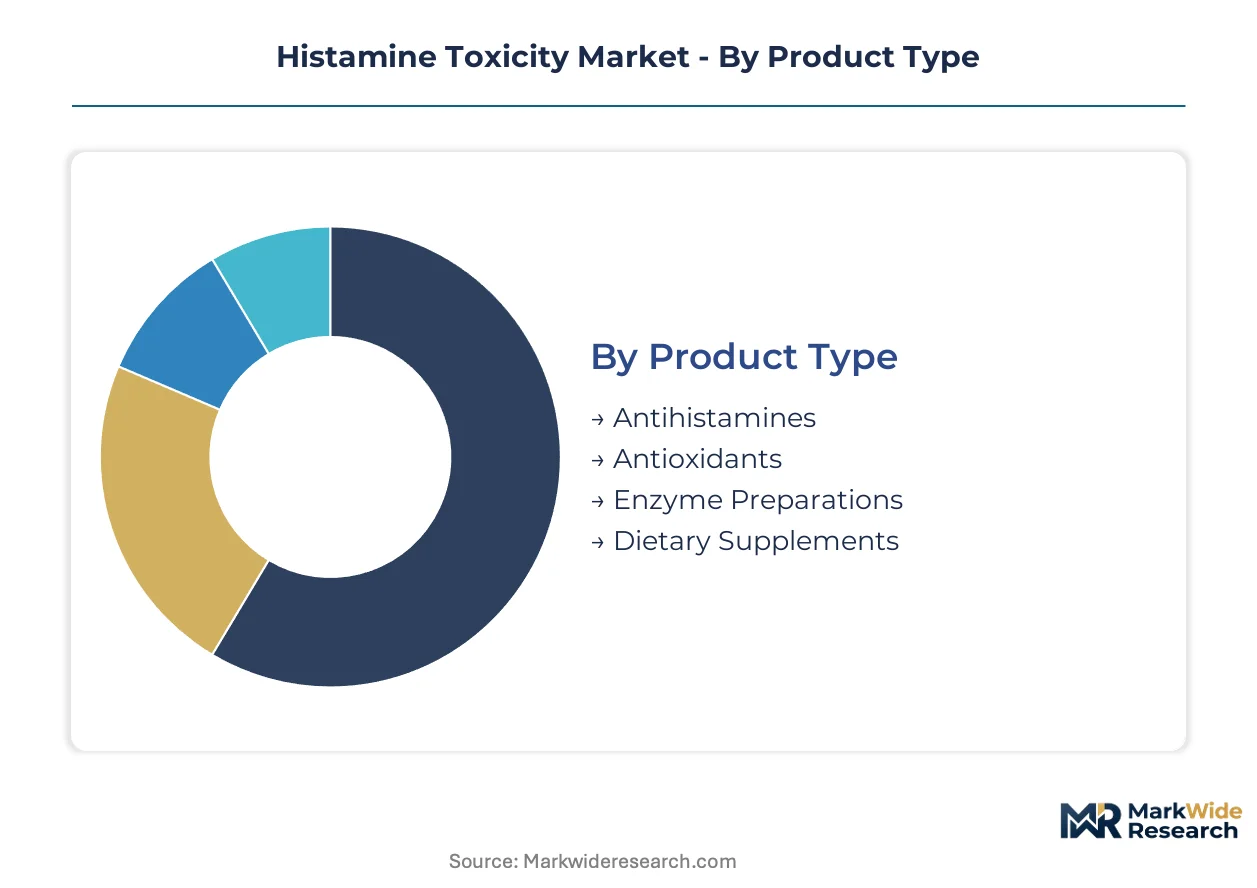
Histamine toxicity management requires precise matching of therapeutic modality to clinical presentation and care setting. Segmentation reveals how emergency protocols, chronic management pathways, and consumer self-care create divergent demand profiles across product categories and access channels.
Product Type:
Cost tiers separate acute symptomatic relief from long-term enzymatic management strategies.
- Antihistamines:First-generation H1 antagonists and second-generation non-sedating formulations block histamine receptor binding for rapid symptom suppression. Hospital emergency departments in the United States and Germany absorb the highest prescription volumes due to scombroid poisoning protocols.
- Enzyme Preparations:DAO (diamine oxidase) supplements restore endogenous histamine degradation capacity in patients with genetic or acquired enzyme deficiency. Direct-to-consumer channels in Japan and Germany are expanding fastest as histamine intolerance awareness spreads beyond specialist clinics.
- Antioxidants:Quercetin and vitamin C formulations modulate mast cell stability as adjunctive therapy.
- Dietary Supplements:Probiotic and prebiotic blends target gut microbiome modulation to reduce histamine production.
Antihistamines command the established base. The steepest expansion runs through Enzyme Preparations.
Therapy Area:
Application severity determines reimbursement eligibility and prescribing authority boundaries.
- Allergic Reactions:IgE-mediated hypersensitivity and non-allergic histamine release syndromes demand immediate pharmacological intervention with clear diagnostic differentiation from toxicity. Emergency medicine specialists in urban United States hospital clusters drive protocol standardization.
- Gastrointestinal Disorders:Histamine-mediated diarrhea, abdominal cramping, and malabsorption syndromes require chronic management through elimination diets and enzyme supplementation. German gastroenterology practices lead European adoption of DAO testing protocols.
- Chronic Inflammation:Systemic histamine involvement in mast cell activation disorders extends treatment duration.
- Skin Conditions:Urticaria and flushing presentations overlap with dermatological allergy profiles.
Allergic Reactions anchor acute care revenue. Gastrointestinal Disorders are gaining share fastest as functional medicine approaches penetrate mainstream practice.
End User:
Customer type fragmentation separates institutional procurement from individual purchasing decisions.
- Healthcare Providers:Hospital emergency departments and specialized allergy clinics require rapid diagnostic-therapeutic integration with formulary compliance. United States health system consolidation is concentrating purchasing power among integrated delivery networks.
- Home Users:Self-directed consumers manage chronic histamine intolerance through over-the-counter enzyme supplements and elimination diet tools. Japanese and German markets show strongest e-commerce penetration for testing kits and subscription supplement models.
- Pharmacies:Community and hospital-based dispensaries bridge prescription and self-care segments.
- Research Institutions:Academic medical centers and contract research organizations support biomarker validation and therapeutic development.
Healthcare Providers retain the volume base. Home Users are climbing the fastest as diagnostic democratization collapses traditional gatekeeper roles.
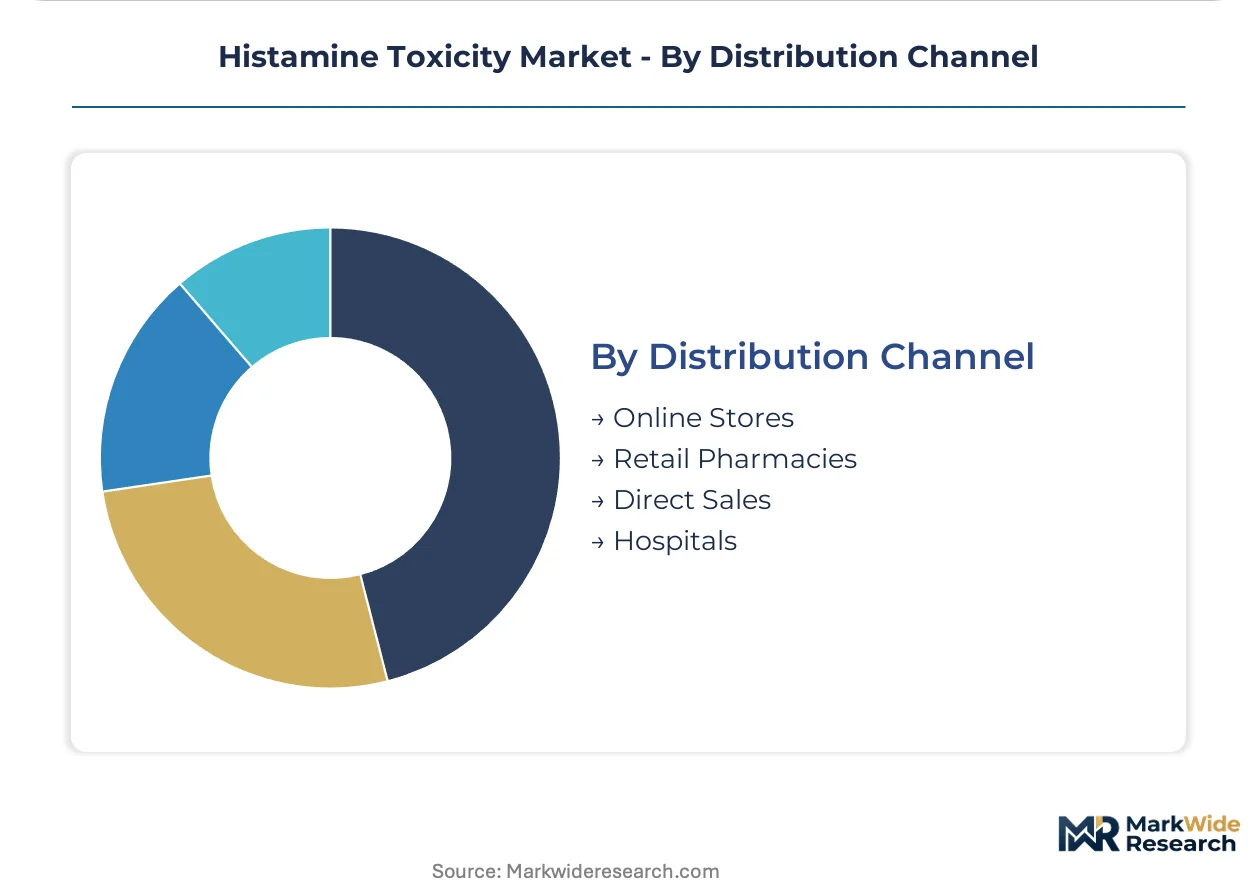
Distribution Channel:
Channel maturity reflects regulatory control intensity and patient access convenience trade-offs.
- Hospitals:Captive pharmacy and emergency department dispensing ensures immediate availability for acute toxicity presentations. Formulary committees in United States and German hospital systems increasingly restrict antihistamine selection to preferred agents.
- Retail Pharmacies:Community-based access supports both prescription fulfillment and pharmacist-guided over-the-counter selection. Japan's prefectural pharmacy networks maintain strong counseling relationships with chronic histamine intolerance patients.
- Online Stores:Direct-to-consumer platforms bypass traditional prescriber relationships for enzyme supplements and testing devices.
- Direct Sales:Manufacturer-controlled channels serve specialized clinical and research segments.
Hospitals dominate acute therapeutic access. Online Stores are expanding most quickly as regulatory frameworks adapt to remote care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's histamine-sensitive biologics distribution, while Japan's Kansai International Airport anchors Asia-Pacific pharmaceutical logistics for temperature-controlled therapeutics.
United States
Emergency department protocol standardization in urban hospital clusters drives antihistamine procurement volumes. FDA pharmacovigilance programs mandate real-world evidence collection for histamine-modulating therapeutics. The Greater Boston biomedical corridor concentrates specialized allergy clinic networks and reference laboratory partnerships.
Germany
Ambulatory care centers and gastroenterology practices lead European adoption of DAO testing protocols for histamine intolerance management. EMA conditional marketing authorization frameworks shape post-approval surveillance obligations for enzyme replacement candidates. The Rhine-Ruhr metropolitan region hosts concentrated pharmaceutical distribution networks serving Western European markets.
Japan
Prefectural hospital networks and pharmacy counseling relationships sustain chronic histamine intolerance patient management. METI industrial standards govern diagnostic device quality assurance for point-of-care testing platforms. The Osaka-Kobe manufacturing belt supplies enzymatic supplement production for domestic and export markets.
United Kingdom
Specialized allergy clinics in London and the Southeast drive diagnostic differentiation service demand. NHS procurement frameworks influence formulary selection for emergency department antihistamine protocols. The Cambridge-London life sciences corridor supports biomarker validation research for novel detection modalities.
Switzerland
Swissmedic regulatory pathways attract biologics developers targeting rare histamine disorders for accelerated approval. Precision medicine initiatives in Basel and Zurich integrate pharmacogenomic testing into individualized antihistamine prescribing. The country's pharmaceutical logistics infrastructure serves as a European distribution hub for temperature-sensitive therapeutics.
Histamine Toxicity Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base stratifies between consolidated pharmaceutical manufacturers with established pharmacy networks and fragmented diagnostic specialists competing on analytical accuracy. Two strategic archetypes dominate: diversified life sciences conglomerates leveraging cross-portfolio synergies, and niche toxicology testing laboratories capturing unbundled diagnostic contracts. Competitive intensity centers on M&A activity to acquire complementary enzyme preparation capabilities and strategic partnerships to embed digital pharmacovigilance infrastructure.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and PerkinElmer exemplify platform integrators anchoring laboratory-based detection workflows through analytical instrument portfolios. Eurofins Scientific occupies a position within the specialized testing tier, representing the niche laboratory archetype competing through food safety and clinical toxicology service differentiation. Pfizer Inc sits within the established pharmaceutical tier, its position reflecting legacy pharmacy distribution relationships rather than diagnostic integration.
| Leading Market Players |
|---|
| Travere Therapeutics, Inc. |
| Johnson and Johnson company |
| Neogen Corporation |
| PerkinElmer |
| Thermo Fisher Scientific |
| Eurofins Scientific |
| Sanofi Aventis Ltd |
| Pfizer Inc |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in DAO enzyme manufacturing across Germany and Japan is compressing supplier margins while amplifying pricing power for certified producers. This utilization squeeze forces contract manufacturers to prioritize pharmaceutical-grade batches over nutraceutical volumes, reshaping procurement negotiations for direct-to-consumer supplement brands.
Pricing Analysis
Volume-discount tiering separates hospital formulary contracts from retail pharmacy and e-commerce channels. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification status and cold-chain assurance documentation. Pricing pressure stems from EU F-Gas Regulation compliance costs elevating biologics storage expenses. Hospital procurement committees exhibit lowest price sensitivity due to emergency stock requirements, while direct-to-consumer enzyme supplement buyers demonstrate highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized enzyme fermentation facilities in Germany, Japan, and Switzerland serving pharmaceutical and nutraceutical clients. Raw material dependencies include porcine kidney extract, recombinant yeast cultures, and chromatography resins for purification. Single-source vulnerability runs through European refrigerant supply chains governing cold-chain integrity. Distribution runs through pharmaceutical wholesalers for institutional channels and direct fulfillment centers for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mass spectrometry-based reference laboratories threatening to displace immunoassay point-of-care devices in high-throughput hospital networks.
For Market Incumbents: Pre-empt reference laboratory encroachment by embedding smartphone-connected lateral flow devices into emergency department protocols with real-time cloud integration. Secure backward integration into DAO enzyme fermentation capacity in Germany to insulate against contract manufacturing bottlenecks. FDA pharmacovigilance automation investments will compress adverse event reporting overhead relative to competitors maintaining parallel EMA tracking systems. For New Entrants and Emerging Players: Build out home-based monitoring applications in Japan's consumer wellness segment where e-commerce penetration for testing kits exceeds institutional channels. Target gastroenterology practices in Germany's ambulatory care centers with DAO testing protocols as the most penetrable clinical entry point. Pursue strategic partnerships with established pharmacy counseling networks rather than direct prescriber engagement to bypass formulary gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because diagnostic-therapeutic integration is collapsing traditional vendor boundaries. Acquisition candidates with ISO 15189-accredited histamine quantification capabilities and existing hospital laboratory relationships command structural scarcity value. Monitor EMA conditional marketing authorization timelines for rare histamine disorder therapeutics as the inflection signal for enzyme replacement pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA fast-track designation compresses clinical trial timelines for rare histamine disorder candidates. |
| Platform Integration | Smartphone-connected lateral flow devices with cloud symptom tracking collapse detection-to-treatment feedback loops. |
| Acquisition of Specialist Firm | ISO 15189-accredited toxicology laboratories capture unbundled diagnostic contracts from integrated pharmaceutical suppliers. |
| Manufacturing Scale-Up | DAO enzyme fermentation capacity expansion in Germany addresses undercapacity constraining direct-to-consumer supplement growth. |
| Strategic Partnership | Reference laboratory alliances with Japanese prefectural hospital networks displace captive in-house toxicology capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with emergency medicine specialists, formulary directors at integrated delivery networks, diagnostic laboratory managers, and regulatory affairs leads at enzyme supplement manufacturers. Secondary validation drew from FDA pharmacovigilance databases, EMA risk management plan submissions, ISO 15189 accreditation registries, and hospital procurement contract disclosures. Bottom-up therapeutic volume modeling and top-down market sizing triangulated across point-of-care testing platform installations and antihistamine prescription audit data.
Calibration against historical adoption curves for diagnostic miniaturization and direct-to-consumer supplement penetration informed trajectory assumptions across the analysis window. Segmentation dimensions encompassed product type, therapy area severity, end-user archetype, and distribution channel maturity. CAGRs were derived from fitted growth curves weighted by regulatory approval timelines and reimbursement pathway clarity. Forecast inputs included EMA conditional marketing authorization progression rates and cold-chain infrastructure investment disclosures.
Sensitivities concentrate around FDA-EMA regulatory divergence, EU F-Gas refrigerant phase-down acceleration, and mass spectrometry displacement of immunoassay platforms. Forecasts reflect documented assumptions regarding protocol standardization timelines and consumer diagnostic adoption elasticity. Quarterly review of pharmacovigilance enforcement intensity and point-of-care testing reimbursement decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market