
 Glioma Therapeutics Market | 2026-2036
Glioma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Glioma Therapeutics Market Analysis
Academic medical centers and specialized neuro-oncology units within hospital networks is recalibrating the primary demand profile for glioma therapeutics. Pfizer Inc. leverages its broad oncology infrastructure to sustain clinical trial access across multiple glioma subtypes. F. Hoffmann-La Roche Ltd anchors its position through biomarker-driven patient stratification in high-grade glioma protocols. Novocure differentiates with tumor treating fields technology that competes alongside systemic therapy paradigms.
Glioma therapeutics comprise systemic and localized interventions targeting malignant glial cell proliferation, with temozolomide alkylating activity and bevacizumab anti-angiogenic mechanisms representing established pharmacological benchmarks against WHO grade III-IV tumors. Immunotherapy approaches including checkpoint inhibitors and CAR-T constructs are gaining protocol inclusion despite blood-brain barrier penetration challenges that constrain efficacy thresholds. Intravenous delivery dominates current administration patterns, though oral formulations are capturing adjuvant maintenance settings where patient compliance and outpatient convenience determine protocol adherence. Hospitals retain the largest end-user share, while research institutions concentrate early-phase investigational access where margin pools from trial sponsorship offset reimbursement constraints on approved agents.
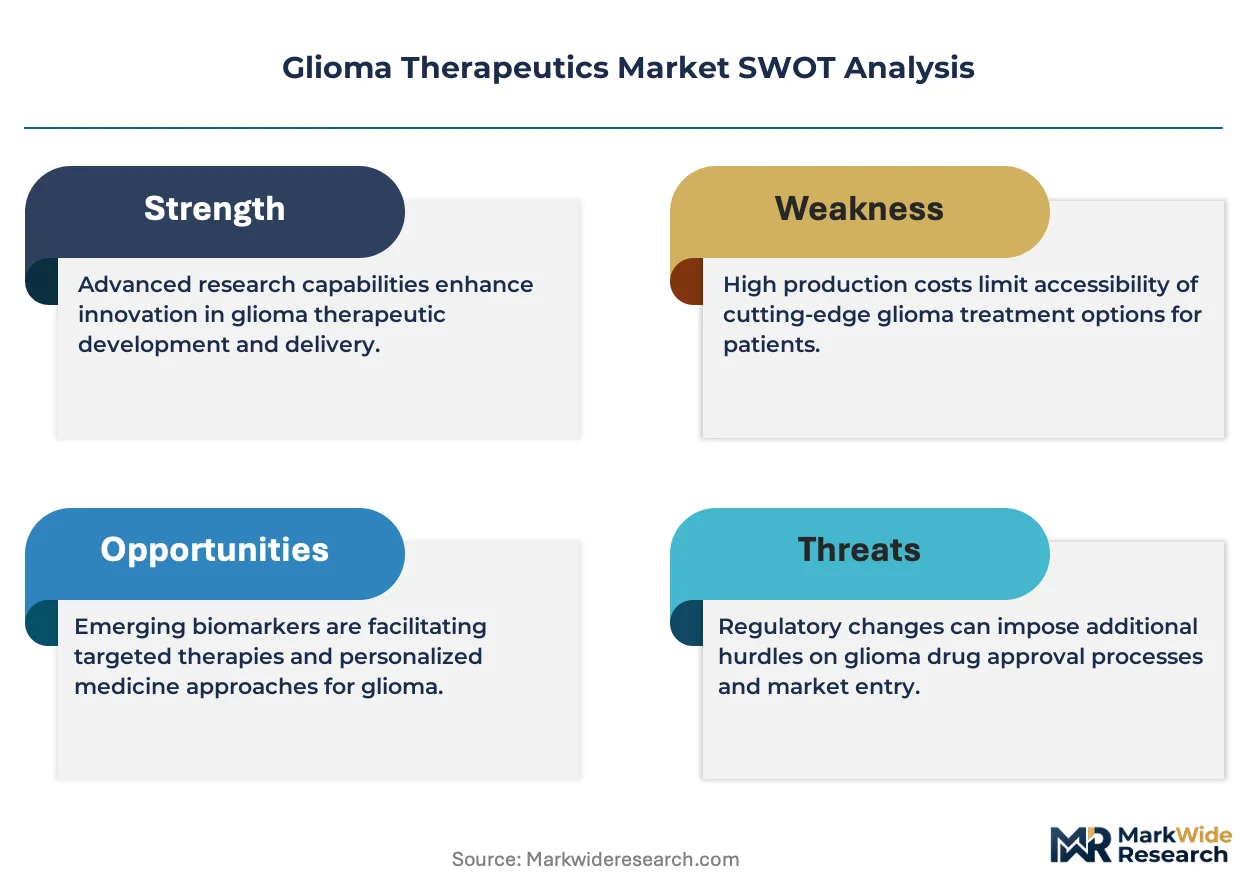
FDA breakthrough therapy designation and EMA PRIME eligibility criteria compress development timelines for glioma drug candidates, while orphan drug exclusivity provisions shape portfolio prioritization decisions at major pharmaceutical developers. WHO classification updates for central nervous system tumors redefine trial endpoints and reimbursement coding requirements across major markets. Stakeholders must monitor biomarker qualification pathways and adaptive licensing frameworks to anticipate which therapeutic modalities gain priority access to restricted payer budgets.
Market Dynamics
Accelerated FDA breakthrough therapy designations and EMA PRIME eligibility are compressing clinical trial timelines, forcing developers to front-load biomarker qualification and adaptive protocol design before regulatory submission.
Growth Catalysts
- Orphan Drug Exclusivity:FDA and EMA provisions grant seven to ten years of market exclusivity for glioma indications, concentrating portfolio prioritization at major pharmaceutical developers toward rare CNS malignancies.
- Tumor Treating Fields Technology:Novocure's Optune device category is expanding protocol inclusion alongside systemic therapy, creating new reimbursement codes in US and German hospital networks.
- Academic Medical Center Expansion:Hospital-based neuro-oncology departments in the United States, Germany, and Japan are scaling combination protocol adoption, anchoring demand for multimodal therapeutic regimens.
Market Restraints
- Blood-Brain Barrier Penetration:Systemic immunotherapy agents face fundamental pharmacokinetic limitations that constrain efficacy thresholds in high-grade glioma, capping addressable patient populations.
- Clinical Trial Cost Concentration:Central nervous system oncology trials require specialized imaging infrastructure and extended survival endpoints that inflate development expenditure beyond other solid tumor categories.
- Reimbursement Compression:Payer budget restrictions in tertiary care networks limit formulary access for novel agents outside accelerated approval pathways, constraining commercial uptake velocity.
Strategic Opportunities
- Biomarker-Driven Stratification:WHO classification updates for CNS tumors are redefining trial endpoints, enabling sponsors to qualify companion diagnostics alongside therapeutic candidates for priority regulatory review.
- Oral Formulation Adjuvant Settings:Temozolomide maintenance protocols demonstrate compliance advantages that outpatient administration models can capture, shifting volume from infusion centers to retail pharmacy networks.
- Japan PMDA Sakigake Pathway:Japan's regenerative medicine and innovative drug designation offers compressed review timelines for glioma candidates, attracting early regulatory filing strategies for Asia-Pacific market entry.
Industry Challenges
- Neuro-Oncology Trial Design Complexity:Pseudoprogression and pseudoresponse phenomena complicate radiographic response assessment, requiring specialized neuroradiology expertise that concentrates at academic centers.
- Adaptive Licensing Framework Navigation:Conditional approval mechanisms demand post-marketing confirmatory trial infrastructure that strains sponsor resource allocation across concurrent development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioma Therapeutics Market |
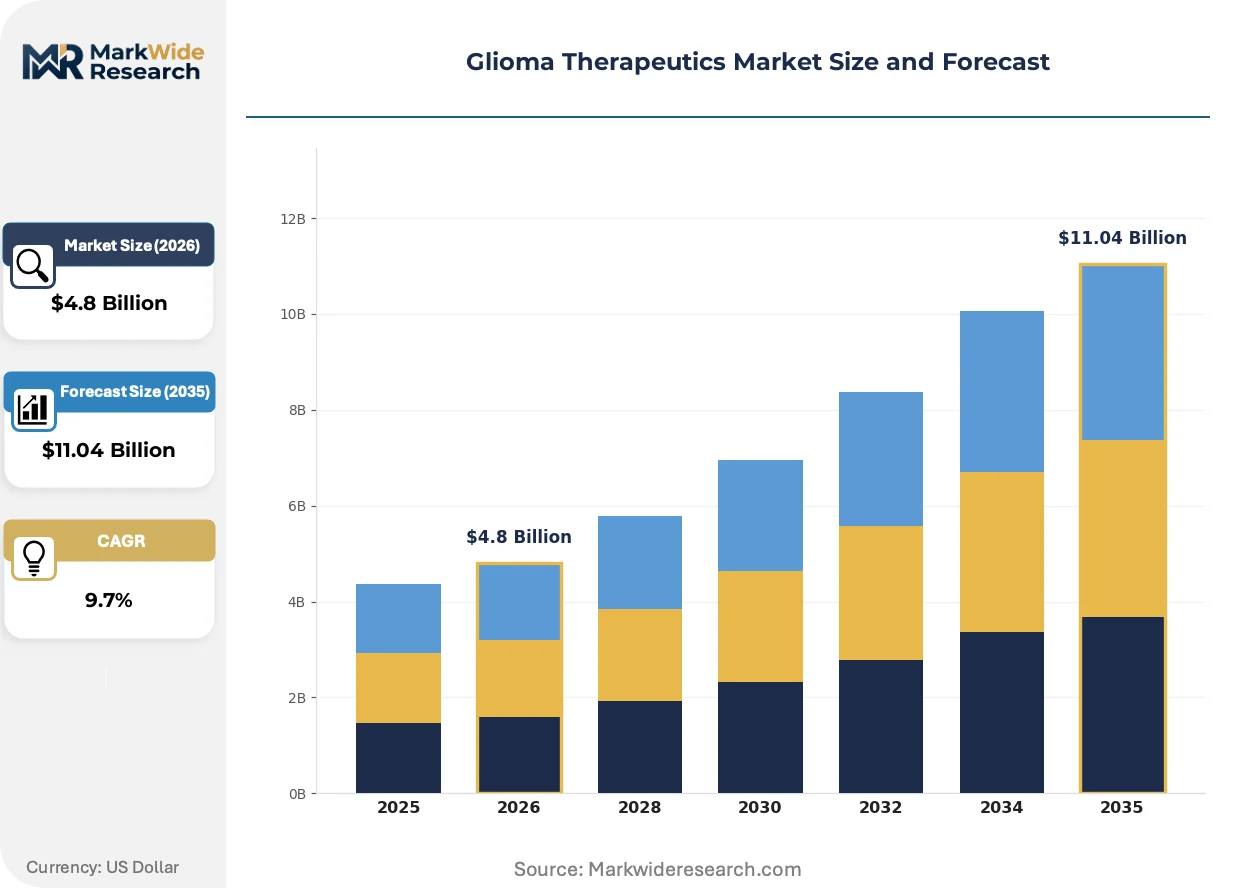
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Application: Ongoing Treatment, Adjuvant Therapy, Palliative Care, Post-Surgical Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal End User: Hospitals, Clinics, Research Institutions, Homecare |
| Companies Covered | Pfizer Inc., Amgen Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, AbbVie Inc., Novocure, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioma Therapeutics Market Emerging Trajectories
Convergence of localized device therapy with systemic pharmacology is restructuring glioma treatment protocols, while biomarker qualification pathways and adaptive trial designs are compressing traditional development timelines.
Checkpoint inhibitor and CAR-T construct platforms are consolidating clinical trial access despite blood-brain barrier constraints, as academic medical centers in the United States and Germany expand basket trial infrastructure for CNS malignancies. These immunotherapy modalities are capturing protocol slots previously reserved for cytotoxic regimens, enabling sponsors to front-load biomarker stratification and compress enrollment timelines.
FDA breakthrough therapy designation criteria and EMA PRIME eligibility frameworks are compressing glioma drug development timelines, mandating earlier patient advocacy engagement and accelerated manufacturing scale-up before phase completion. Sponsors are responding by embedding health technology assessment evidence generation into phase II protocols, particularly for German and French reimbursement submissions.
Hospital procurement committees are unbundling device and pharmaceutical purchasing decisions, creating separate evaluation tracks for tumor treating fields equipment versus systemic therapy formularies. This bifurcation is most visible in US tertiary care networks, where neuro-oncology departments negotiate distinct contracts with device manufacturers and pharmaceutical account managers, fragmenting traditional vendor relationships and demanding specialized contracting expertise from suppliers.
Glioma Therapeutics Market Segmentation
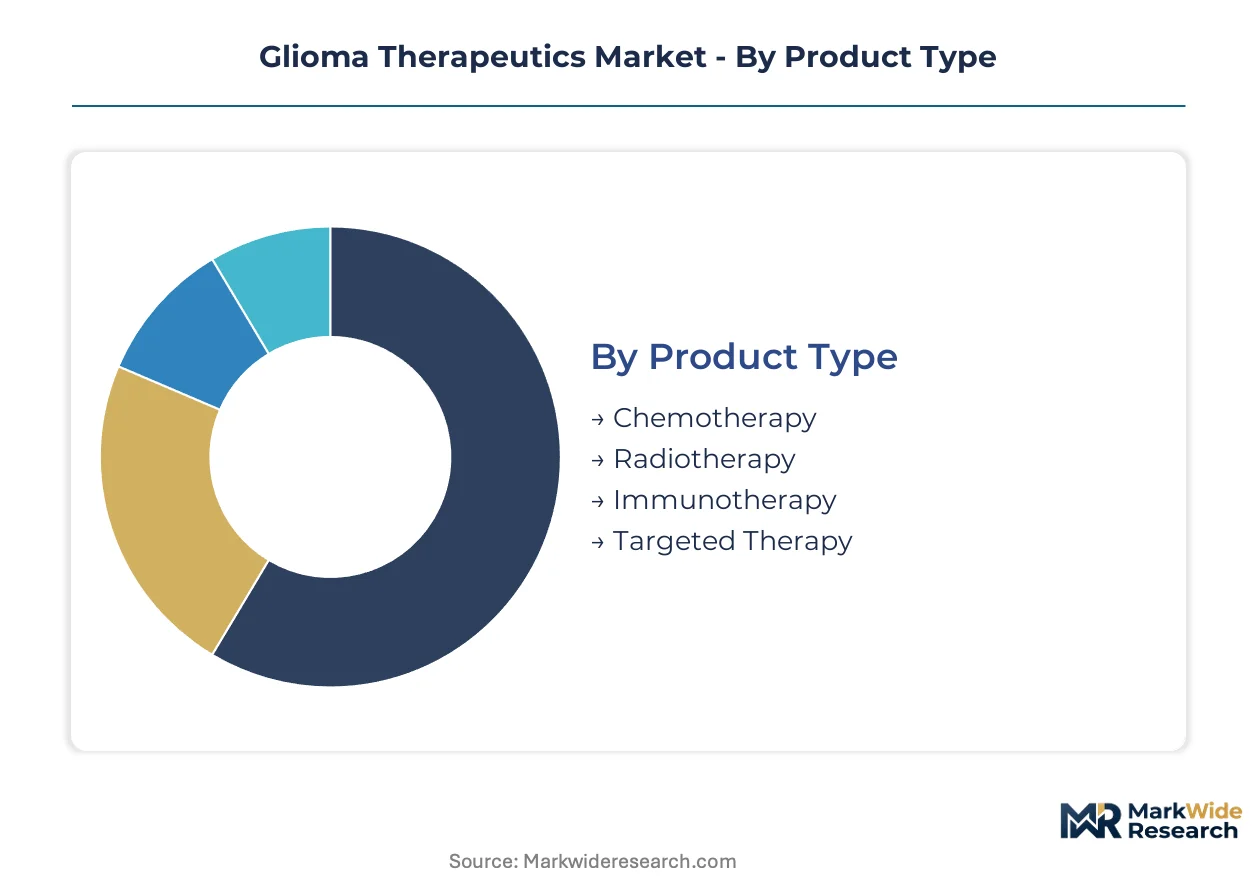
Glioma treatment protocols demand precise matching of therapeutic modality to tumor grade, patient functional status, and care setting. Segmentation reveals how delivery infrastructure and reimbursement pathways reshape competitive positioning across systemic and localized interventions.
Product Type:
Protocol upgrade cycles favor modalities demonstrating survival benefit in biomarker-defined populations, with reimbursement tailwinds concentrating volume in established therapeutic classes.
- Chemotherapy:Alkylating agents like temozolomide remain foundational for WHO grade III-IV gliomas. Academic medical centers in the United States and Germany anchor demand for combination regimens integrating cytotoxic backbone with experimental adjuncts.
- Radiotherapy:External beam and stereotactic approaches target residual disease post-resection. Japanese tertiary networks concentrate adoption of proton therapy for pediatric and recurrent cases where dose sparing determines eligibility.
- Immunotherapy:Checkpoint inhibitors face blood-brain barrier constraints but gain protocol slots through academic basket trials.
- Targeted Therapy:Bevacizumab and emerging kinase inhibitors address angiogenic signaling in recurrent settings.
Volume placements concentrate in chemotherapy; the faster expansion belongs to immunotherapy.
Application:
Care phase determines reimbursement tier and site-of-service economics, with outpatient migration reshaping margin structures across intervention categories.
- Ongoing Treatment:Active disease management demands continuous monitoring and protocol adjustment. Hospital-based neuro-oncology departments in Germany and Japan concentrate complex case volume requiring multidisciplinary tumor boards.
- Adjuvant Therapy:Post-radiation systemic maintenance reduces recurrence probability. United States outpatient infusion centers capture volume through oral formulation dispensing and remote monitoring infrastructure.
- Palliative Care:Symptom-focused interventions prioritize quality-of-life endpoints.
- Post-Surgical:Immediate perioperative protocols target residual tumor burden.
Volume placements concentrate in ongoing treatment; adjuvant therapy climbs the fastest as oral maintenance protocols expand.
Delivery Mode:
Administration route dictates site-of-service requirements and patient compliance economics, with formulation innovation driving shifts between institutional and retail channels.
- Intravenous:Infusion-dependent biologics require specialized nursing infrastructure. United States hospital outpatient departments and German day-clinic networks anchor volume for bevacizumab and investigational immunotherapy.
- Oral:Temozolomide and emerging small molecules enable home-based administration. Japanese retail pharmacy networks and US specialty pharmacies capture volume through adherence packaging and patient support programs.
- Subcutaneous:Reduced infusion time appeals to ambulatory settings.
- Intrathecal:Direct CNS delivery bypasses blood-brain barrier for leptomeningeal spread.
Volume placements concentrate in intravenous; oral formulations gain share fastest through adjuvant maintenance expansion.
End User:
Procurement authority and reimbursement coding vary sharply across settings, with research sponsorship offsetting margin pressure at investigational sites.
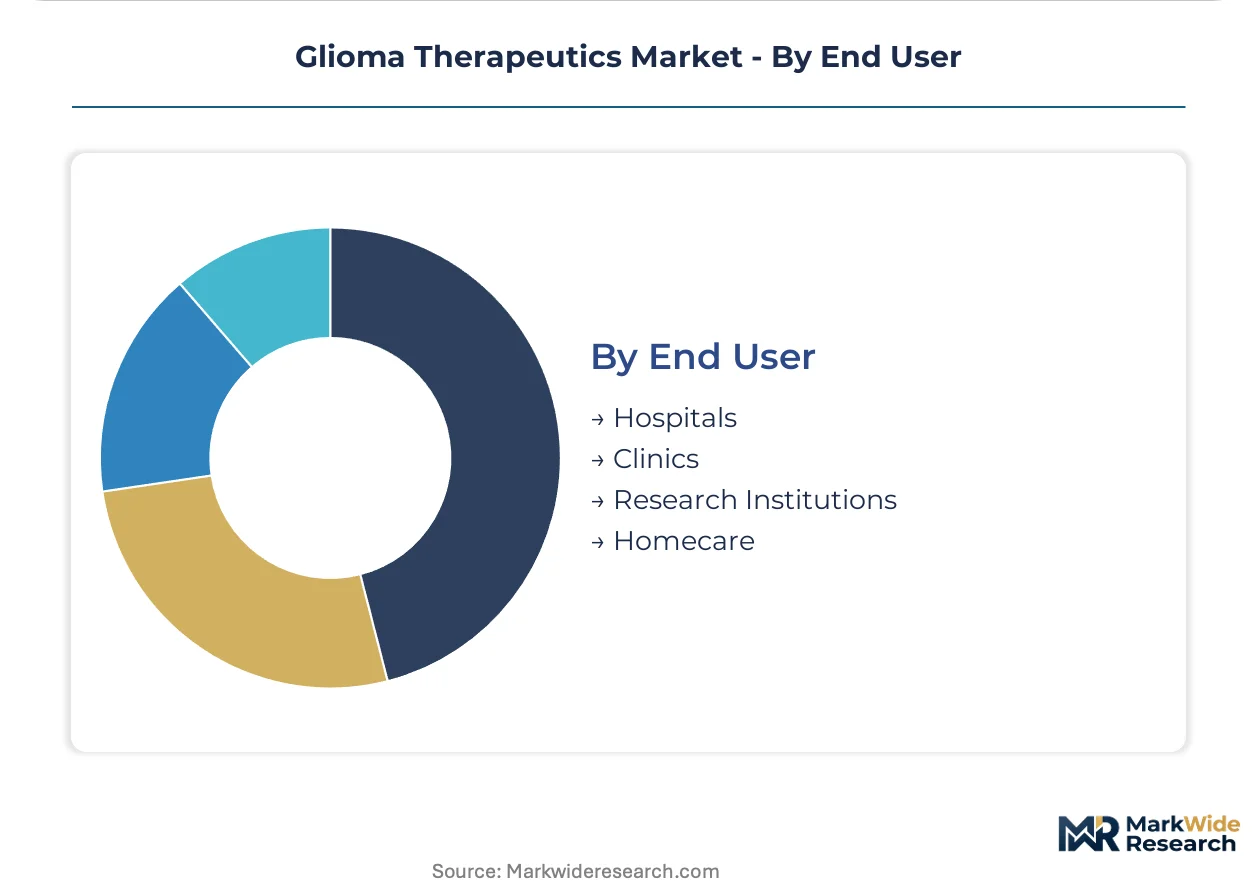
- Hospitals:Tertiary neuro-oncology units control protocol definition and formulary access. United States academic medical centers and German university hospitals concentrate high-grade glioma volume and clinical trial enrollment.
- Clinics:Community oncology practices handle stable patients on maintenance protocols. Japanese cancer center satellite clinics and US community networks capture oral therapy volume.
- Research Institutions:Early-phase trial sponsorship offsets reimbursement constraints on approved agents.
- Homecare:Nursing-supported oral administration extends treatment access.
Volume placements concentrate in hospitals; research institutions expand most quickly through basket trial infrastructure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Opportunity Zones and German BioRegions anchor glioma therapeutic development through targeted tax incentives and cluster funding that concentrate clinical trial infrastructure and manufacturing investment.
United States
FDA breakthrough therapy designations and orphan drug exclusivity provisions drive biopharma concentration in Greater Boston and the San Francisco Bay Area. The 21st Century Cures Act accelerates review timelines for CNS malignancies. Massachusetts General Hospital and MD Anderson Cancer Center anchor multicenter trial networks that enroll high-grade glioma patients.
Germany
EMA PRIME eligibility and national cancer plan funding expand neuro-oncology department capacity across university hospital networks. The BioRegions program channels federal-state investment into Heidelberg and Munich clusters. German Cancer Research Center coordinates biomarker qualification studies that feed into EMA scientific advice procedures.
Japan
PMDA Sakigake designation offers compressed review timelines that attract early filing strategies for glioma candidates. The national health insurance system maintains separate reimbursement tracks for innovative oncology drugs. Tokyo and Osaka metropolitan areas concentrate proton therapy installations and specialized neuro-oncology units.
United Kingdom
NHS England specialized commissioning frameworks create dedicated funding streams for rare CNS malignancies. The Early Access to Medicines Scheme enables pre-approval reimbursement for promising glioma therapies. London and Manchester academic medical centers host basket trial infrastructure for immunotherapy platforms.
Switzerland
Swissmedic adaptive licensing pathways and orphan drug incentives align with Basel-region pharmaceutical R&D concentration. Federal innovation vouchers support precision medicine startups targeting glioma biomarker discovery. University Hospital Zurich and Geneva University Hospitals anchor multicenter European trial coordination.
Glioma Therapeutics Market Vendor Landscape
Top-tier vendors anchor the concentrated biopharma tier, while mid-cap specialists and device-therapy hybrids occupy differentiated positions below. The market structure reflects heavy R&D capitalization requirements and regulatory expertise barriers that limit new entrant viability. Three archetypes dominate: multinational oncology platforms with CNS portfolios, precision medicine specialists with biomarker-driven stratification capabilities, and localized device-therapy integrators. Consolidation pressure manifests through strategic partnerships for blood-brain barrier delivery technologies and geographic licensing arrangements for Asia-Pacific market entry.
Within the multinational platform tier, Pfizer Inc. and F. Hoffmann-La Roche Ltd occupy positions defined by broad clinical trial infrastructure and biomarker qualification capabilities. Novocure represents the device-therapy integration archetype, anchoring a distinct competitive vector through tumor treating fields technology that complements systemic pharmacology rather than displacing it. These three entities exemplify how competitive positioning in glioma therapeutics depends on securing priority access to academic medical center protocol committees and payer formulary committees across US, German, and Japanese tertiary networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Amgen Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc. |
| Novocure |
| Bristol-Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committee consolidation across United States tertiary networks and German university hospital systems is compressing vendor margins and forcing manufacturers to restructure distribution contracts around outcome-based reimbursement benchmarks.
Pricing Analysis
Short lead-time premiums for temozolomide and bevacizumab emergency replenishment command pricing spreads against standard contract terms. Contract-based long-term offtake dominates the pricing model, with price differentiation resting on FDA breakthrough therapy designation tier and volume scale commitments. Cost compression in the immunotherapy segment is intensifying because basket trial sponsorship offsets limit formulary pricing power. Community oncology practices in Japan exhibit the highest price sensitivity, while academic medical centers in Germany demonstrate the lowest due to research funding buffers.
Supply Chain Analysis
Domestic-content mandates under the US Biopreparedness Act and Japan's PMDA Sakigake local manufacturing incentives are reshaping active pharmaceutical ingredient sourcing toward domestic fill-finish capabilities. Manufacturing concentration centers on the United States, Switzerland, and Ireland for finished dose forms, with India and China anchoring intermediate chemical synthesis. Supply chains draw from glioma-specific alkylating agent precursors, monoclonal antibody cell lines, and tumor treating fields electronic components. Single-source vulnerability in the Novocure device component tier creates concentration risk. Distribution runs through hospital procurement committees and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tumor treating fields technology is displacing cytotoxic maintenance regimens in first-line glioblastoma protocols, creating a technology-transition window where device-pharma hybrid models capture margin previously held by systemic therapy alone.
For Market Incumbents: To counter blood-brain barrier delivery limitations eroding immunotherapy efficacy claims, Pfizer and Roche should deepen backward integration into focused ultrasound and convection-enhanced delivery platforms while locking academic medical center trial exclusivity through sponsored neuroradiology infrastructure. For New Entrants and Emerging Players: The premium-to-economy pricing gap in adjuvant oral maintenance offers entry space for biosimilar temozolomide developers targeting Japanese retail pharmacy networks and US specialty pharmacy channels with adherence-optimized packaging and remote monitoring bundles. For Investors and Strategic Acquirers: The window for entry favors precision medicine specialists with biomarker-qualified companion diagnostics and blood-brain barrier penetration platforms. Long-term viability hinges on securing priority regulatory review pathways across FDA, EMA, and PMDA jurisdictions simultaneously. Watch for EMA PRIME eligibility announcements as the inflection signal for portfolio valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway | WHO classification updates enable companion diagnostic co-approval with therapeutic candidates. |
| Adaptive Trial Design Implementation | FDA breakthrough therapy criteria compress enrollment timelines through protocol flexibility. |
| Academic Medical Center Partnership | Hospital-based neuro-oncology departments anchor combination protocol adoption and trial access. |
| Oral Formulation Development | Adjuvant maintenance settings shift volume from infusion centers to retail pharmacy networks. |
| Reimbursement Strategy Execution | German G-BA and Japan MHLW separate innovative oncology drug tracks accelerate formulary access. |
Methodological Framework
FDA filings, EMA submission documents, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with formulary database extracts from US hospital systems and German sickness funds. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated secondary findings. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical trendline analysis across approved glioma therapeutic launches established baseline adoption curves applied across the projection horizon. Segmentation dimensions modeled include tumor grade, treatment line, administration route, and regional regulatory cluster. CAGRs derived from patent expiry impact modeling, biosimilar entry probability, and device-therapy convergence velocity. Blood-brain barrier penetration success rates and pseudoprogression correction factors informed immunotherapy segment assumptions.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world evidence collection timelines for tumor treating fields introduce uncertainty bands around device adoption trajectories. Forecasts reflect assumptions on accelerated approval pathway utilization and orphan drug exclusivity enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Cholangiocarcinoma Market