
 Leukocyte Adhesion Deficiency Management Market | 2026-2036
Leukocyte Adhesion Deficiency Management Market Size, Share, and Industry Trends Forecast 2026-2036
Leukocyte Adhesion Deficiency Management Market Foresight
Specialized pediatric immunology centers is hardening as the dominant referral channel for Leukocyte Adhesion Deficiency management, shifting volume away from general hematology wards. Rocket Pharmaceuticals leverages its lentiviral gene therapy platform to occupy the autologous HSC gene therapy niche. Orchard Therapeutics sustains European manufacturing scale for ex vivo modified CD34+ cell therapies. CSL Behring anchors plasma-derived immunoglobulin supply for bridging supportive care in transplant-ineligible patients.
Leukocyte Adhesion Deficiency management encompasses clinical protocols for correcting defective leukocyte trafficking caused by mutations in ITGB2, ITGAL, or FERMT3 genes, primarily through allogeneic hematopoietic stem cell transplantation or emerging autologous gene-modified cell therapies that restore CD18 integrin expression on neutrophil surfaces. Gene therapy product types are attracting disproportionate R&D allocation as curative alternatives to matched sibling donor transplants, though stem cell transplantation treatment methods retain dominance in current clinical practice due to established efficacy data. Pharmacological interventions remain a mature margin pool centered on prophylactic antibiotics and antifungals, while enzyme replacement therapy holds limited applicability given the structural rather than enzymatic nature of LAD pathophysiology.
FDA orphan drug designations and EMA PRIME eligibility shape competitive timelines by granting protocol assistance and accelerated assessment for LAD-directed gene therapies. Health Canada and the country's national pharmaceutical regulator enforce comparable manufacturing standards for imported cellular therapy products, constraining market access for non-domestic manufacturers. Stakeholders must monitor payer willingness to fund single-administration curative therapies against chronic supportive care benchmarks as gene therapy readouts mature.
Market Dynamics
The transition from allogeneic donor dependency toward autologous gene-modified cell platforms is compressing clinical timelines and redrawing competitive boundaries across curative intervention pathways.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-approval intervals for rare disease gene therapies, enabling earlier commercialization of LAD-directed lentiviral products.
- Pediatric Hematology-Oncology Concentration:Referral volume is hardening around specialized immunology centers with transplant infrastructure, creating predictable demand funnels for advanced therapies.
- CD34+ Cell Processing Automation:Closed-system manufacturing platforms are reducing contamination risk and enabling decentralized production of patient-specific gene-modified cell products.
Market Restraints
- Matched Sibling Donor Scarcity:Only 25-30% of LAD patients identify suitable allogeneic donors, forcing prolonged bridging therapy with plasma-derived immunoglobulin and prophylactic antimicrobials.
- EMA Manufacturing Compliance:European Good Manufacturing Practice requirements for ex vivo modified cell therapies impose facility validation timelines that delay market entry for non-domestic manufacturers.
- Viral Vector Production Bottleneck:Lentiviral vector supply concentrates among contract manufacturers with limited capacity, constraining enrollment in gene therapy trials.
Strategic Opportunities
- Health Canada Import Pathway:The regulator's alignment with FDA manufacturing standards creates streamlined access for US-based autologous cell therapy developers seeking North American expansion.
- In-Utero Gene Editing:Preclinical CRISPR platforms targeting ITGB2 mutations during gestation could eliminate neonatal sepsis mortality in severe LAD-I phenotypes.
- Real-World Evidence Frameworks:Payer acceptance of single-arm trial data and registry outcomes is expanding reimbursement eligibility for curative therapies against chronic supportive care benchmarks.
Industry Challenges
- Cell Processing Workforce Gap:Qualified specialists in GMP-compliant ex vivo cell modification remain concentrated at academic medical centers, limiting manufacturing scale-out.
- Vector Integration Site Analysis:Long-term clonal tracking of lentiviral insertions requires bioinformatics infrastructure that most treatment centers lack.
- Reimbursement Code Fragmentation:Gene therapy products lack established DRG classifications in US Medicare and commercial payer systems, creating prior authorization friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukocyte Adhesion Deficiency Management Market |
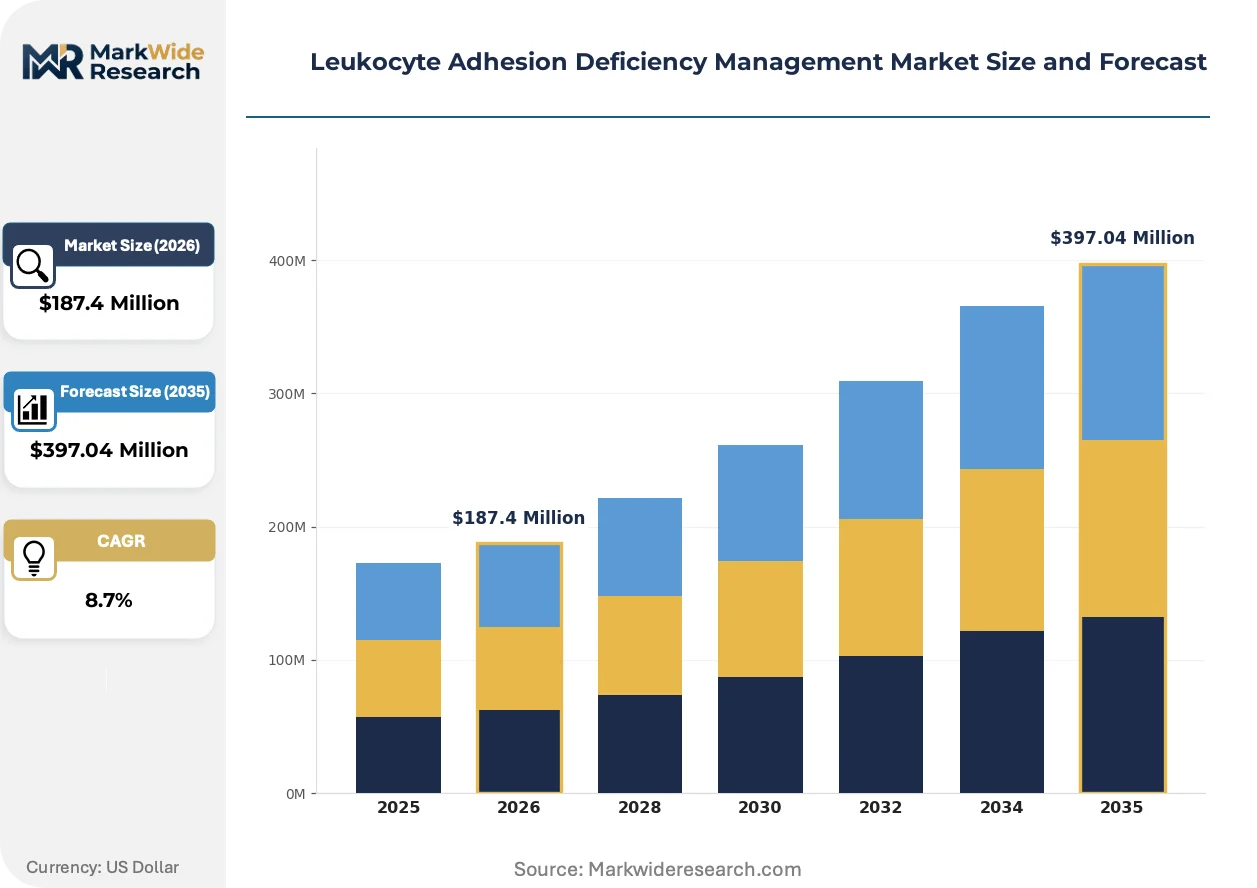
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Pharmacological Interventions, Supportive Treatments Application: Pediatric Patients, Adult Patients, Clinical Research, Hospital Treatments End User: Hospitals, Specialized Clinics, Research Institutions, Home Care Treatment Method: Immunotherapy, Stem Cell Transplantation, Symptomatic Treatment, Nutritional Support |
| Companies Covered | Rocket Pharmaceuticals, Orchard Therapeutics, Avrobio, Inc., Magenta Therapeutics, CSL Behring, Bluebird Bio, Novartis Gene Therapies, Gilead Sciences, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukocyte Adhesion Deficiency Management Market Shifts & Advancements
Gene therapy manufacturing automation and regulatory science advances are converging to compress development timelines while payer frameworks struggle to adapt to single-administration curative pricing models.
Lentiviral vector engineering with self-inactivating designs and improved tropism for hematopoietic stem cells is electrifying the efficiency of CD18 integrin restoration in LAD-I patient cells. Pediatric immunology centers in the United States are adopting these next-generation vectors for investigator-initiated trials ahead of formal approval pathways. This technological leap is enabling outpatient administration protocols that displace prolonged inpatient conditioning regimens.
EMA PRIME eligibility and FDA Breakthrough Therapy designation are creating parallel accelerated assessment tracks that compress regulatory review from 18 months to 6-8 months for LAD-directed gene therapies. Manufacturers are responding by pre-positioning manufacturing slots and vector inventory ahead of pivotal readouts. European reference pricing systems remain the binding constraint, as Germany's AMNOG process and France's HAS evaluation require cost-effectiveness thresholds that single-administration curative therapies struggle to meet.
Specialized pediatric immunology centers are consolidating referral volume through formal network agreements with payers, displacing general hematology wards as the default care setting. Parents of LAD patients are driving geographic relocation to access transplant-eligible centers in Boston, Cincinnati, and London. This concentration pattern is most visible in the United States, where Medicaid waivers and commercial payer carve-outs enable cross-state travel for ultra-orphan interventions.
Leukocyte Adhesion Deficiency Management Market Segmentation
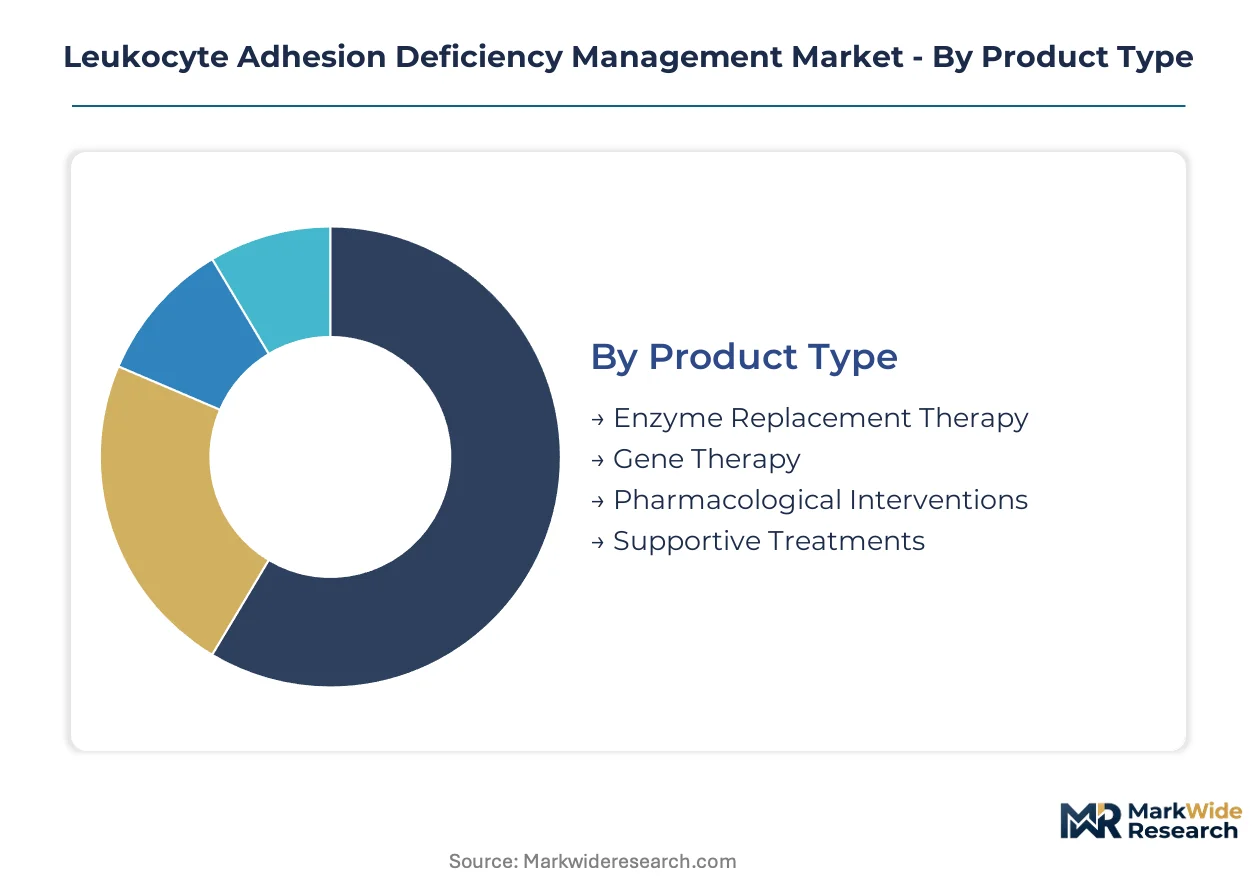
Segmentation in Leukocyte Adhesion Deficiency management reveals sharp divides between curative and supportive modalities, with product type and treatment method categories commanding premium pricing while application and end-user segments determine access geography.
Product Type:
Gene therapy products capture the premium tier with single-administration curative pricing, while pharmacological interventions anchor the volume base through chronic administration protocols.
- Gene Therapy:Autologous HSC gene-modified cell therapies restore CD18 integrin expression via lentiviral vectors. Demand concentrates at pediatric immunology centers in Boston and Cincinnati where FDA accelerated pathways enable early access. Manufacturing bottlenecks in viral vector supply constrain enrollment expansion despite disproportionate R&D allocation.
- Pharmacological Interventions:Prophylactic antibiotics and antifungals constitute the mature margin pool bridging patients to curative options. Volume hardens around Medicaid-covered chronic care protocols in transplant-ineligible populations across the United States. Payer familiarity with these agents sustains reimbursement despite non-curative outcomes.
- Supportive Treatments:Plasma-derived immunoglobulin from CSL Behring anchors bridging therapy for donor-scarce patients.
- Enzyme Replacement Therapy:Limited applicability given the structural rather than enzymatic nature of LAD pathophysiology involving ITGB2 mutations.
Today's leader: Pharmacological Interventions. Tomorrow's challenger: Gene Therapy.
Application:
Pediatric concentration drives referral network formation, while adult segments remain underserved due to delayed diagnosis patterns.
- Pediatric Patients:Severe LAD-I phenotypes present in neonatal period with omphalitis and delayed umbilical cord separation. Specialized transplant centers in Cincinnati and London attract geographic relocation from parents seeking curative protocols. FDA orphan drug incentives align development timelines with this segment's unmet mortality burden.
- Clinical Research:Investigator-initiated trials at academic medical centers generate real-world evidence for payer acceptance of single-arm gene therapy data. EMA PRIME eligibility compresses regulatory assessment for protocols enrolling across European reference sites.
- Adult Patients:Milder phenotypes and delayed presentations limit addressable population despite comparable therapeutic options.
- Hospital Treatments:Inpatient conditioning regimens for stem cell transplantation retain protocol standardization at consolidated centers.
Clinical Research is expanding most quickly as registry frameworks mature for gene therapy outcomes.
End User:
Site-of-care consolidation favors specialized infrastructure over generalist settings.
- Specialized Clinics:Pediatric immunology centers with formal payer network agreements displace general hematology wards as default referral channels. These sites concentrate GMP-compliant cell processing capability and qualified workforce for ex vivo modification protocols.
- Research Institutions:Academic medical centers host lentiviral vector engineering programs and clonal tracking bioinformatics infrastructure absent at community sites.
- Hospitals:General wards retain residual volume for acute infectious complications requiring inpatient antimicrobial management.
- Home Care:Prophylactic antibiotic administration and family education protocols extend care beyond institutional boundaries.
Specialized Clinics are gaining share fastest through referral hardening and manufacturing co-location.
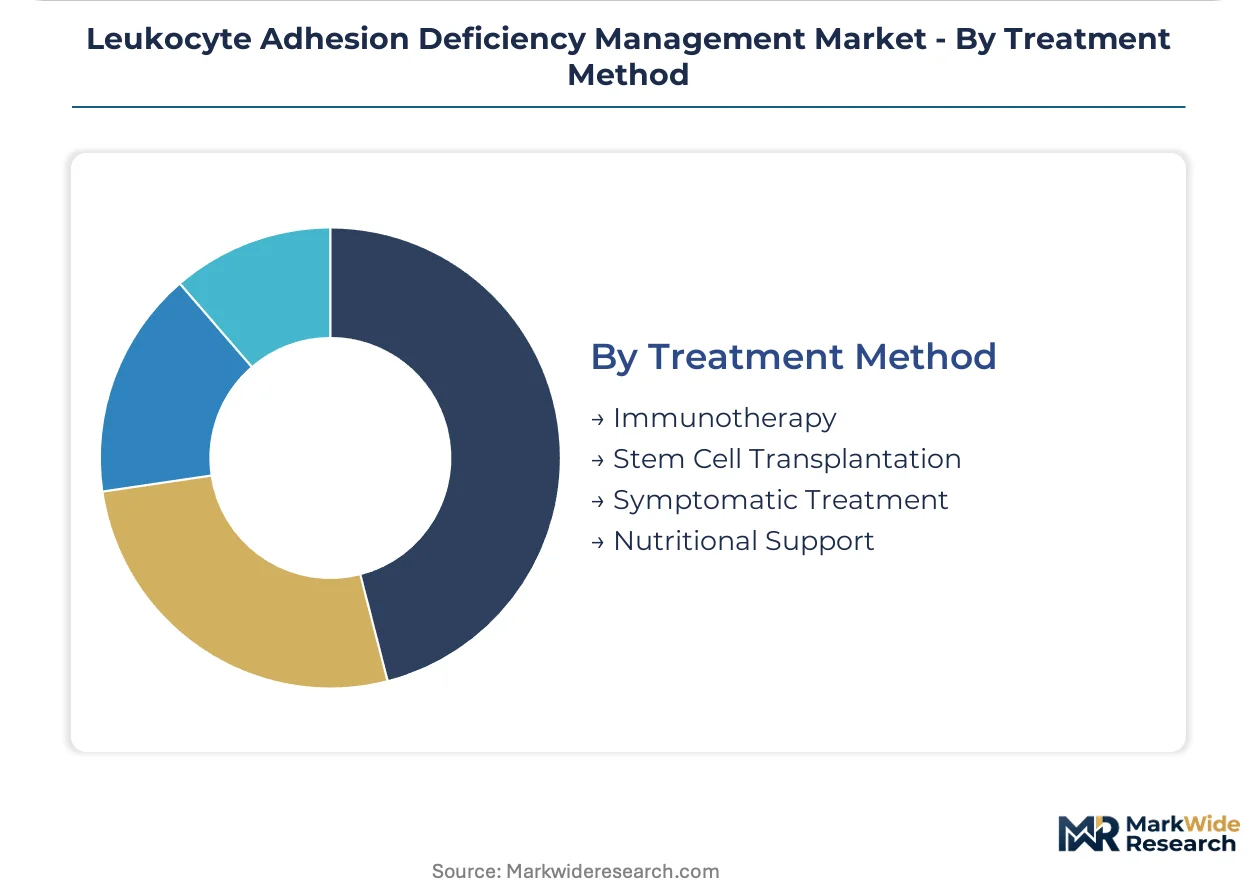
Treatment Method:
Curative modalities command pricing power against chronic supportive benchmarks.
- Stem Cell Transplantation:Allogeneic matched sibling donor transplants retain dominance in current practice due to established efficacy data spanning decades. Only 25-30% of patients identify suitable donors, forcing prolonged bridging therapy and geographic concentration at eligible centers.
- Immunotherapy:Autologous gene-modified platforms eliminate allogeneic dependency and graft-versus-host risk. CD34+ cell processing automation enables decentralized production of patient-specific products.
- Symptomatic Treatment:Acute infection management and wound care protocols address LAD complications without modifying underlying pathophysiology.
- Nutritional Support:Adjunctive interventions for failure-to-thrive in severe pediatric presentations.
Stem Cell Transplantation anchors current revenue. Immunotherapy presents the steepest expansion trajectory as manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor jurisdictions with streamlined cell therapy approval pathways, concentrating manufacturing investment where FDA-aligned standards reduce compliance duplication costs.
United States
Pediatric immunology centers in Boston and Cincinnati attract cross-state patient relocation through Medicaid waivers for ultra-orphan interventions. FDA Breakthrough Therapy designation compresses review timelines for LAD-directed gene therapies from 18 months to 6-8 months. The Greater Boston cluster anchors lentiviral vector engineering programs and GMP-compliant cell processing infrastructure.
Germany
Academic medical centers in Munich and Heidelberg host EMA PRIME-eligible investigator-initiated trials generating real-world evidence for payer acceptance. The AMNOG cost-effectiveness process imposes pricing thresholds that single-administration curative therapies struggle to meet. Bavaria concentrates ex vivo CD34+ cell modification capability alongside clonal tracking bioinformatics infrastructure.
United Kingdom
London-based pediatric immunology centers formalize network agreements with NHS England, displacing general hematology wards as default referral channels. The MHRA operates accelerated assessment tracks aligned with FDA manufacturing standards for imported autologous cell therapies. The Golden Triangle research corridor anchors lentiviral vector production and hematopoietic stem cell gene modification programs.
Canada
Health Canada alignment with FDA manufacturing standards creates streamlined access for US-based autologous cell therapy developers seeking North American expansion. Provincial health authorities in Ontario and British Columbia negotiate outcomes-based reimbursement for single-administration curative therapies against chronic supportive care benchmarks. Toronto anchors specialized pediatric transplant centers with formal payer carve-outs enabling cross-provincial patient travel.
Switzerland
Swissmedic operates accelerated assessment pathways for rare disease gene therapies, compressing regulatory review for LAD-directed interventions. Basel concentrates pharmaceutical manufacturing expertise and contract viral vector production capacity serving European gene therapy developers. The country's reference pricing system maintains cost-effectiveness thresholds that curative therapies must demonstrate through single-arm trial data and registry outcomes.
Leukocyte Adhesion Deficiency Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers secure lentiviral vector supply and manufacturing slots ahead of pivotal readouts. The vendor base concentrates around three tiers: gene therapy platform specialists, plasma-derived product incumbents, and contract manufacturing organizations. Platform specialists occupy the premium tier through autologous HSC modification capabilities. Incumbents anchor the volume base through bridging supportive care products. Contract manufacturers control critical bottlenecks in viral vector production and GMP-compliant cell processing. Competitive moves center on manufacturing co-location with specialized pediatric centers and pre-positioning vector inventory.
Within the gene therapy platform tier, Rocket Pharmaceuticals and Orchard Therapeutics exemplify divergent geographic strategies. Rocket Pharmaceuticals represents US-based developers leveraging FDA accelerated pathways to compress Phase II-to-approval intervals. Orchard Therapeutics occupies a position as a European-headquartered developer sustaining manufacturing scale for ex vivo modified CD34+ cell therapies. CSL Behring anchors the supportive care segment through plasma-derived immunoglobulin supply for transplant-ineligible patients. These three entities collectively illustrate the competitive structure: platform specialists racing to eliminate allogeneic donor dependency, incumbents defending bridging therapy revenue, and manufacturers constraining enrollment through vector scarcity.
| Leading Market Players |
|---|
| Rocket Pharmaceuticals |
| Orchard Therapeutics |
| Avrobio, Inc. |
| Magenta Therapeutics |
| CSL Behring |
| Bluebird Bio |
| Novartis Gene Therapies |
| Gilead Sciences |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Pediatric immunology centers with formal payer network agreements concentrate procurement authority for curative therapies, anchoring value-based pricing models that benchmark single-administration gene therapies against lifetime chronic care costs. This buyer concentration enables manufacturers to command premium pricing for autologous HSC gene-modified products while plasma-derived immunoglobulin suppliers compete on contract reliability for bridging protocols.
Pricing Analysis
Direct-to-institution contracting with specialized transplant centers eliminates traditional distributor margins, compressing channel economics to manufacturer-negotiated value-based arrangements. Pricing stratifies across curative gene therapy tiers, chronic pharmacological bridging protocols, and acute supportive interventions, with differentiation driven by FDA breakthrough designation status and manufacturing scale. Cost compression in plasma-derived products intensifies as fractionation capacity expands, while gene therapy pricing reflects lentiviral vector scarcity and GMP facility slot premiums. Medicaid programs exhibit highest price sensitivity due to budget cycle constraints, whereas commercial payer carve-outs for ultra-orphan conditions demonstrate lowest sensitivity when mortality endpoints are demonstrated.
Supply Chain Analysis
Patient cell return logistics from specialized immunology centers to GMP processing facilities require temperature-controlled chain-of-custody protocols with validated cryopreservation handoffs. Manufacturing concentrates in the United States, Switzerland, and the United Kingdom where FDA-aligned standards reduce compliance duplication for North American and European market access. Raw material dependencies center on lentiviral vector supply from contract manufacturers, CD34+ cell selection reagents, and cryopreservation media formulations. Single-source vulnerability in viral vector production constrains enrollment expansion across competing gene therapy programs. Distribution runs through centralized cell processing hubs co-located with academic medical centers, displacing traditional pharmaceutical wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
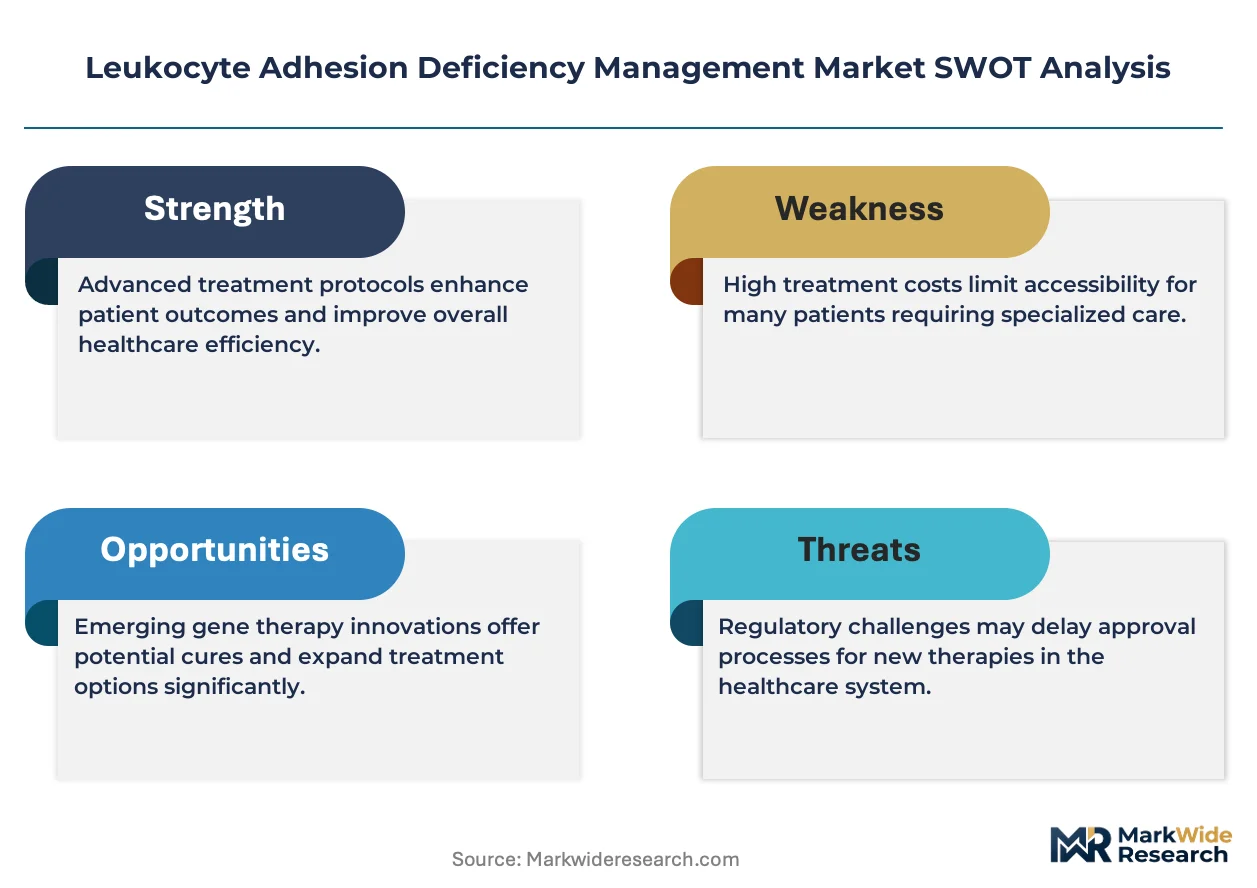
The Leukocyte Adhesion Deficiency Management Market functions as a regulatory compounder where FDA accelerated approval pathways for rare disease gene therapies compress development timelines and concentrate competitive advantage among first movers. EMA PRIME eligibility and Breakthrough Therapy designation create parallel assessment tracks that reward manufacturing pre-positioning and vector inventory buildup ahead of pivotal readouts.
For Market Incumbents: Anticipate autologous gene-modified platforms displacing allogeneic transplant protocols by securing lentiviral vector supply commitments through multi-year manufacturing agreements with contract producers. Plasma-derived immunoglobulin suppliers should anchor bridging therapy revenue through formulary lock-in with transplant-ineligible populations while gene therapy platform specialists prioritize vertical integration into GMP-compliant cell processing to reduce dependency on academic medical center capacity. The threat of in-utero CRISPR editing platforms entering preclinical development demands early positioning in next-generation vector engineering programs. For New Entrants and Emerging Players: The price-point gap between premium single-administration gene therapies and economy-tier chronic supportive care creates white-space opportunity for mid-market autologous platforms with streamlined manufacturing protocols. Target Health Canada import pathways for North American market entry with FDA-aligned manufacturing standards, leveraging provincial outcomes-based reimbursement frameworks in Ontario and British Columbia. The most penetrable segment lies in adult LAD patients with delayed diagnoses currently underserved by pediatric-centric referral networks. A go-to-market angle centered on decentralized CD34+ cell processing automation can displace centralized hub dependency. For Investors and Strategic Acquirers: Large-cap gene therapy developers with existing lentiviral vector infrastructure are the most active acquirer category in this space, targeting platform specialists with investigator-initiated trial networks and GMP manufacturing slots. Long-term viability over the analysis window hinges on payer acceptance of single-arm trial data and registry outcomes as sufficient evidence for curative therapy reimbursement. Acquisition targets should demonstrate clonal tracking bioinformatics capabilities and formal payer network agreements with specialized pediatric immunology centers. The signal to watch is EMA manufacturing compliance timelines for non-domestic manufacturers, which indicate competitive entry velocity and pricing pressure direction.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system CD34+ cell processing automation reduces contamination risk and enables decentralized production capacity. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses review timelines from standard 18-month cycles to 6-8 month assessments. |
| Licensing Agreement | Vector supply partnerships with Lonza Group and Oxford Biomedica secure critical manufacturing slots ahead of pivotal readouts. |
| Clinical Trial Advancement | Investigator-initiated trials at Boston Children's and Cincinnati Children's generate real-world evidence for payer acceptance frameworks. |
| Reimbursement Strategy | Outcomes-based contracts with provincial health authorities in Canada establish precedent for value-based curative therapy pricing. |
Research Methodology
Multiple input streams — regulatory filing databases, clinical trial registries, and hospital procurement records — were reconciled through structured primary interviews with gene therapy development executives, pediatric immunology center directors, payer access specialists, and GMP facility operations managers. Secondary validation drew from FDA orphan drug designations, EMA PRIME eligibility decisions, ClinicalTrials.gov protocol records, and CMS Medicare reimbursement code analyses. Bottom-up patient population estimates were triangulated against top-down market sizing from plasma-derived product shipment data and transplant center capacity surveys.
Historical enrollment trajectories in gene therapy trials were cross-referenced against expert panel inputs from regulatory affairs leads and formulary directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, treatment method, patient age category, and regional regulatory cluster. CAGRs were derived from slope consensus across Delphi rounds with clinical investigators and manufacturing operations heads, with vector production capacity constraints and payer willingness-to-pay thresholds serving as industry-specific forecast inputs.
Caveats apply where EMA manufacturing compliance timelines, viral vector supply disruptions, or payer rejection of single-arm trial data could materially shift the outlook. Practitioners should monitor Health Canada import pathway decisions and provincial reimbursement negotiations for early signals of North American market expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market