
 Cardio-Selective Beta Blockers Market | 2026-2036
Cardio-Selective Beta Blockers Market Size, Share, and Industry Trends Forecast 2026-2036
Cardio-Selective Beta Blockers Market Outlook
Buyer concentration among integrated hospital networks and specialty cardiology clinics is broadening the procurement landscape for cardio-selective beta blockers. AstraZeneca leverages its cardiovascular franchise depth to sustain formulary positioning across major health systems. Novartis anchors its presence through established metoprolol portfolios with broad geographic reach. Teva Pharmaceutical Industries competes aggressively on generic bisoprolol and atenolol supply to cost-sensitive institutional buyers.
Cardio-selective beta blockers are beta-1 adrenergic receptor antagonists engineered with greater affinity for cardiac tissue than bronchial or vascular smooth muscle, typically achieving beta-1 selectivity ratios exceeding 20:1 at therapeutic doses. These agents function primarily to reduce myocardial oxygen demand, control ventricular rate, and inhibit renin release in hypertension management. Metoprolol and bisoprolol dominate prescription volume due to extensive outcome trial evidence and flexible dosing across oral and intravenous delivery modes. The sustained-release formulation segment captures disproportionate margin pools as patients transition from acute hospital settings to home care monitoring programs.
FDA bioequivalence standards for narrow therapeutic index compounds constrain rapid generic substitution for nebivolol and certain metoprolol salt forms. EMA's updated cardiovascular guideline requirements for outcome data in heart failure indications shape trial investment priorities for developers seeking European market access. Health Canada and Australia's TGA maintain aligned pharmacovigilance reporting that influences labeling revisions across Anglo-Pacific markets. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP and EP standards, as divergence in impurity thresholds could fragment active pharmaceutical ingredient sourcing strategies and complicate multi-region filing pathways.
Market Dynamics
Hospital formulary consolidation and FDA narrow therapeutic index bioequivalence protocols are restructuring competitive access for cardio-selective beta blockers, forcing manufacturers to differentiate through sustained-release formulation science rather than commodity pricing alone.
Growth Catalysts
- Integrated Delivery Network Procurement:United States hospital systems are consolidating purchasing authority across regional networks, creating volume incentives for manufacturers with multi-site formulary placement capabilities.
- EMA Heart Failure Outcome Requirements:Updated cardiovascular guideline mandates for European market access are directing clinical trial investment toward heart failure indications with hard endpoint evidence.
- Home Care Monitoring Transition:Post-acute care programs are extending prescription continuity from hospital discharge to outpatient settings, expanding addressable patient months per therapy initiation.
Market Restraints
- API Sourcing Concentration:Active pharmaceutical ingredient production for metoprolol succinate concentrates among Indian and Chinese contract manufacturers, exposing supply continuity to geopolitical trade friction.
- Narrow Therapeutic Index Substitution Barriers:FDA bioequivalence constraints on nebivolol and certain metoprolol salt forms limit automatic generic substitution, constraining rapid price erosion.
- Fixed-Dose Combination Displacement:Single-pill combinations incorporating ACE inhibitors or diuretics are capturing hypertension market share from standalone beta blocker monotherapy.
Strategic Opportunities
- Pediatric Formulation Gaps:Liquid and age-appropriate dosing formats for bisoprolol remain underdeveloped across North American and European markets, presenting first-mover potential.
- Pharmacogenomic-Guided Dosing:CYP2D6 metabolizer status testing integration with metoprolol prescribing protocols is expanding into specialty cardiology clinics.
- Anglo-Pacific Labeling Harmonization:Health Canada and Australia's TGA aligned pharmacovigilance reporting standards are streamlining multi-region filing pathways for sponsors with coordinated regulatory strategies.
Industry Challenges
- USP-EP Impurity Threshold Divergence:Pharmacopeial monograph misalignment between United States and European standards is fragmenting active pharmaceutical ingredient qualification requirements and complicating batch release protocols.
- Specialty Cardiology Talent Scarcity:Clinical pharmacists with narrow therapeutic index drug monitoring expertise are concentrated within academic medical centers, limiting formulary stewardship program expansion to community hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardio-Selective Beta Blockers Market |
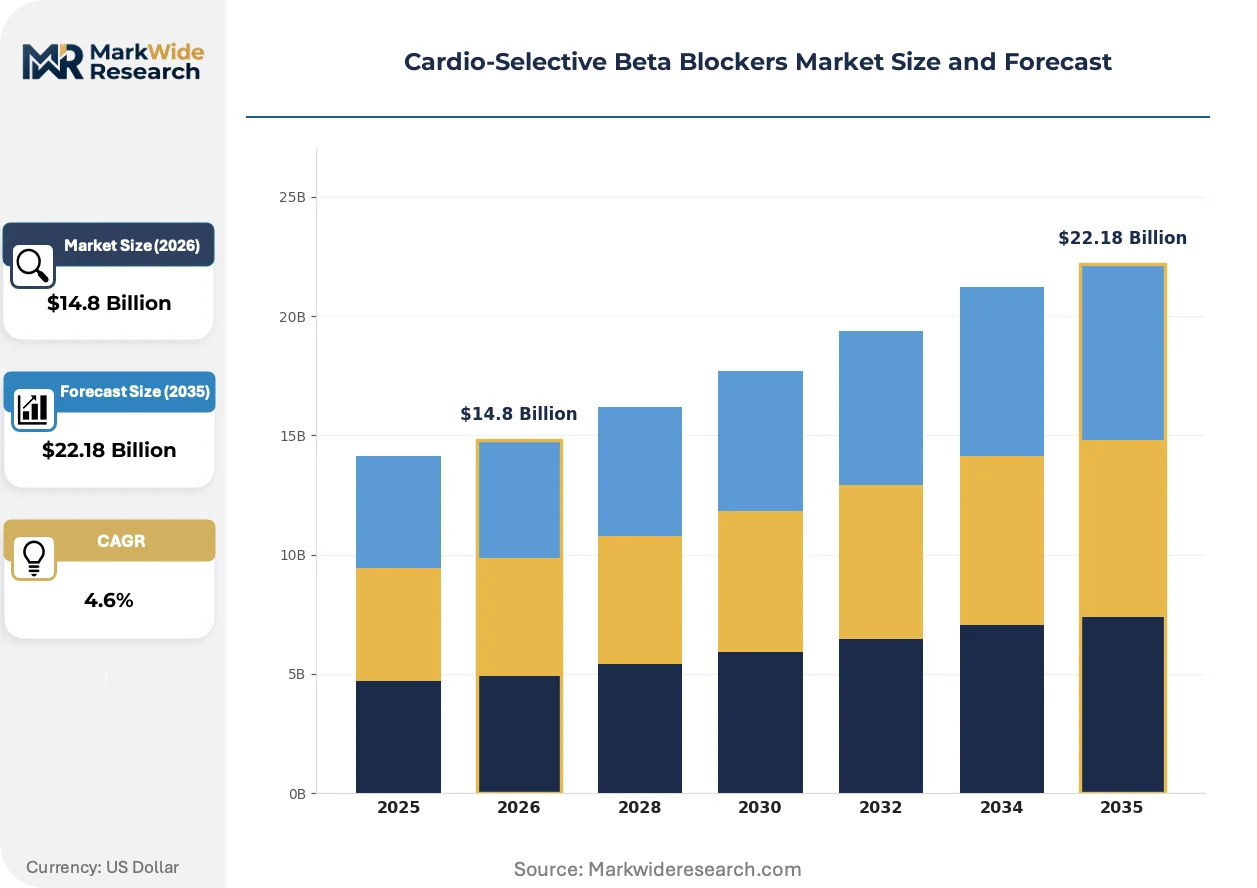
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atenolol, Bisoprolol, Metoprolol, Nebivolol Application: Hypertension, Arrhythmias, Heart Failure, Angina Delivery Mode: Oral, Intravenous, Injectable, Sustained Release End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Merck, Viatris, AstraZeneca, Sanofi, AbbVie, Novartis, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardio-Selective Beta Blockers Market Strategic Shifts
Sustained-release formulation engineering and pharmacogenomic integration are displacing immediate-release commoditization as the primary competitive dimension in cardio-selective beta blocker development.
Multiparticulate bead technology for metoprolol succinate is expanding into chronotherapeutic delivery profiles that align plasma concentration peaks with morning sympathetic surge patterns. Cardiology-focused integrated delivery networks in the United States are piloting these formulations for resistant hypertension populations. The technology is compressing differentiation timelines for generic manufacturers lacking complex modified-release capabilities.
EMA's updated cardiovascular outcome data requirements for heart failure indications are redirecting phase III investment toward hard endpoint trials with mortality and hospitalization measures. Sponsors without existing cardiovascular franchise infrastructure face elevated capital requirements for European market access. Metoprolol and bisoprolol developers with legacy outcome trial assets are leveraging historical data packages for label expansion.
Hospital-at-home programs are unbundling traditional inpatient dispensing from discharge prescription fulfillment, with specialty pharmacies capturing medication therapy management services previously internal to hospital systems. This channel shift is most visible in United States Medicare Advantage contracts with capitated cardiovascular risk arrangements. Manufacturers are restructuring account management teams to engage pharmacy benefit managers alongside traditional hospital formulary committees.
Cardio-Selective Beta Blockers Market Segmentation
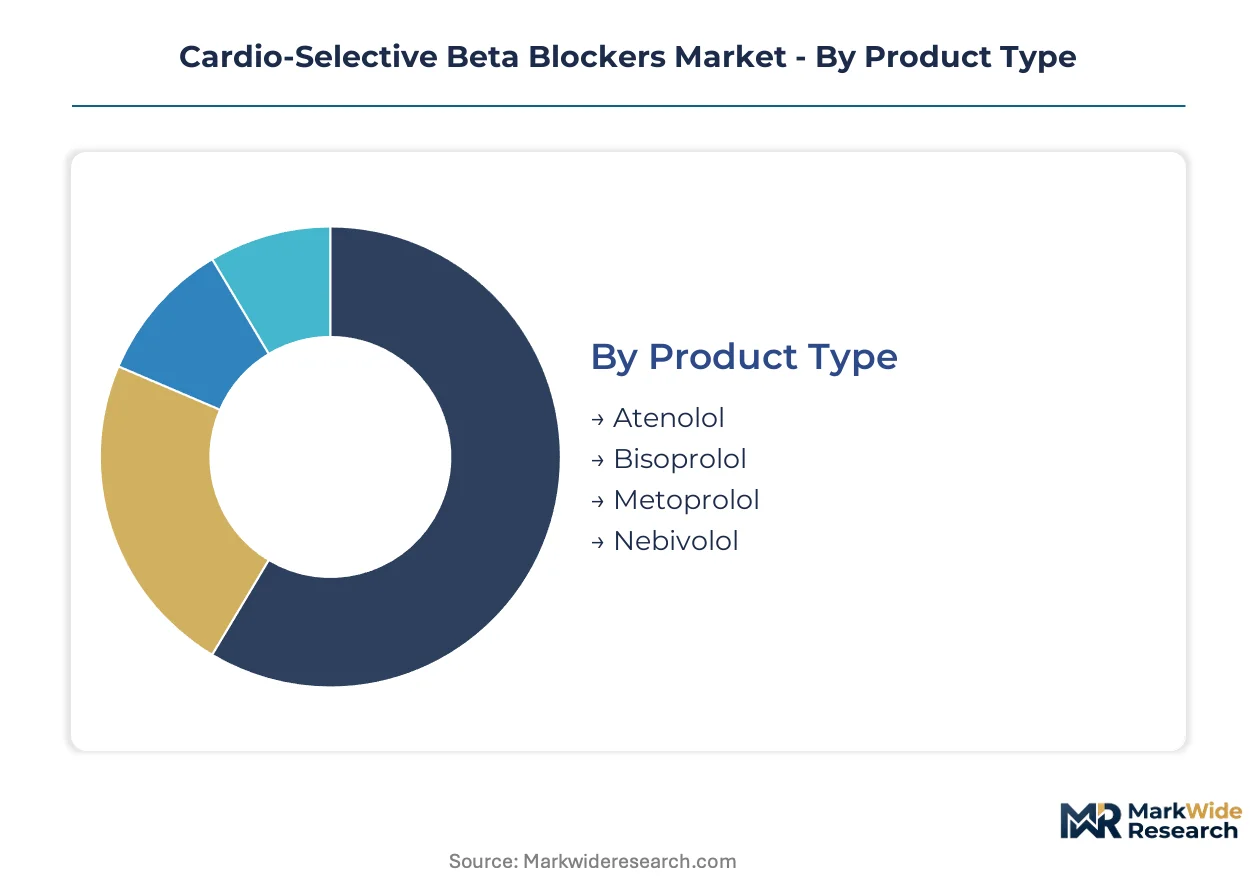
Segmentation in cardio-selective beta blockers reveals how formulation science, clinical indication, and care setting interact to determine procurement patterns. Manufacturers must align product development with specific delivery requirements and end-user infrastructure to secure formulary placement.
Product Type:
Structural selectivity ratios and metabolic pathways differentiate therapeutic profiles across this category.
- Metoprolol:Beta-1 selectivity exceeds 20:1 at therapeutic doses with extensive CYP2D6 metabolism variability. United States integrated delivery networks favor this agent for formulary standardization due to flexible intravenous-to-oral conversion protocols.
- Bisoprolol:Higher beta-1 selectivity and lower lipid solubility reduce central nervous system penetration. European hospital systems concentrate procurement here for heart failure regimens requiring once-daily dosing compliance.
- Atenolol:Hydrophilic properties limit blood-brain barrier crossing with renal-dominant elimination.
- Nebivolol:Nitric oxide-mediated vasodilation distinguishes its hemodynamic profile from pure beta-blockade.
Mature deployment sits with metoprolol across acute care protocols. Newer deployment is concentrated in bisoprolol for chronic heart failure management programs.
Application:
Clinical indication determines dosing intensity, monitoring requirements, and reimbursement pathways.
- Hypertension:First-line status in JNC-8 and ESC/ESH guidelines drives volume. United States Medicare Advantage contracts with capitated cardiovascular risk arrangements prioritize sustained-release formulations for medication adherence metrics.
- Heart Failure:Mortality benefit evidence from MERIT-HF and CIBIS-II trials mandates specific agents. EMA outcome data requirements for new entrants elevate barriers to label expansion in European markets.
- Arrhythmias:Rate control in atrial fibrillation requires rapid onset intravenous options.
- Angina:Myocardial oxygen demand reduction targets exercise-induced ischemia episodes.
Volume concentration favors hypertension management. Steepest expansion trajectory appears in heart failure as hospital-at-home programs extend post-discharge monitoring.
Delivery Mode:
Pharmacokinetic engineering determines therapeutic coverage and manufacturing complexity.
- Sustained Release:Multiparticulate bead technology enables chronotherapeutic profiles aligning plasma peaks with morning sympathetic surge. United States specialty pharmacies capture margin pools as discharge prescriptions transition to outpatient fulfillment.
- Oral:Immediate-release tablets dominate generic substitution with bioequivalence constraints on narrow therapeutic index compounds.
- Intravenous:Acute care settings require sterile manufacturing capabilities with short shelf-life logistics.
- Injectable:Pre-filled syringe formats reduce compounding errors in emergency departments.
Technology investment clusters in sustained-release engineering. Cost-sensitive procurement remains anchored to immediate-release oral tablets.
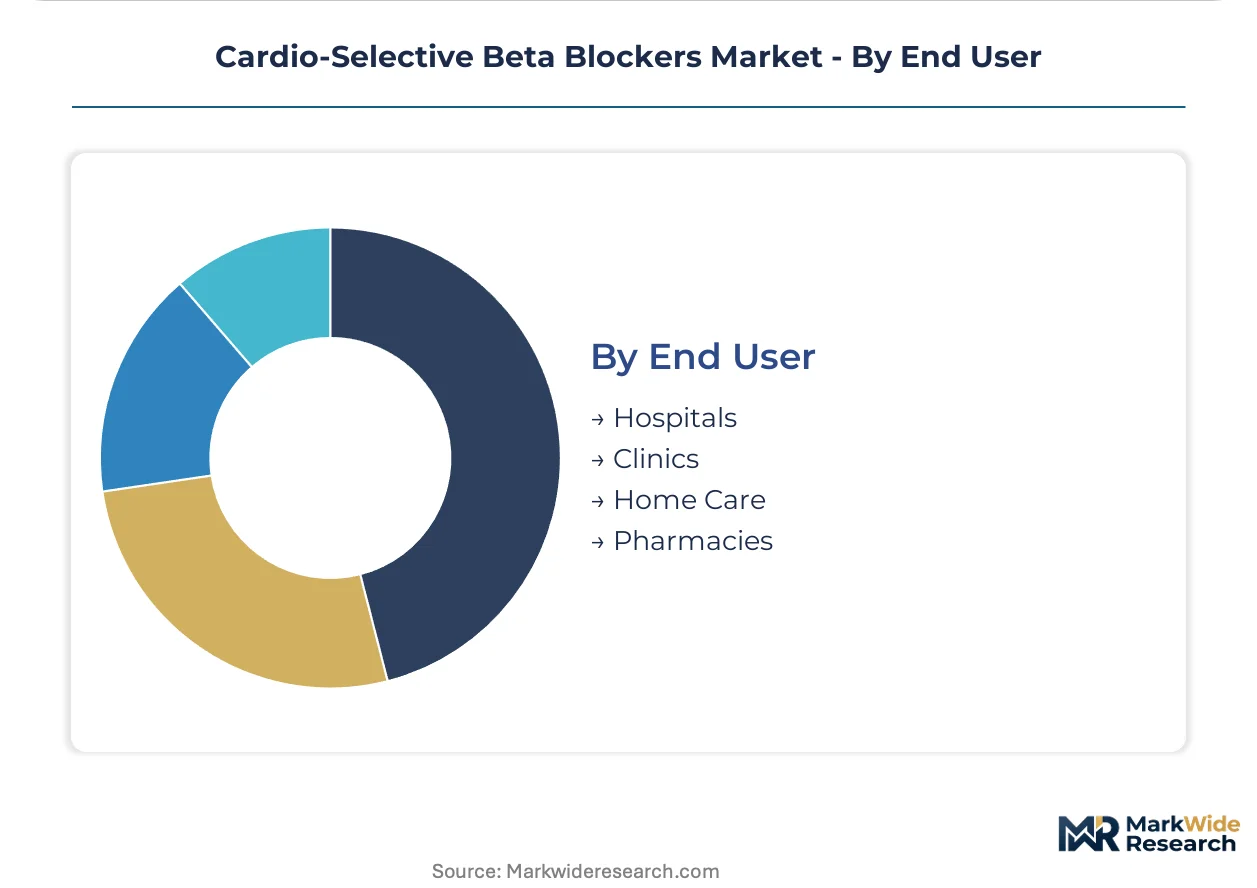
End User:
Purchasing authority and patient acuity shape contract structures and service bundling.
- Hospitals:Formulary committees negotiate multi-site agreements with manufacturers demonstrating sustained-release formulation capabilities. United States academic medical centers pilot pharmacogenomic-guided metoprolol dosing protocols.
- Home Care:Remote monitoring integration extends prescription continuity from discharge. Medicare Advantage capitation models incentivize medication therapy management services.
- Clinics:Cardiology specialty practices concentrate narrow therapeutic index monitoring expertise.
- Pharmacies:Retail dispensing faces automatic substitution constraints for nebivolol and certain metoprolol salt forms.
Account management resources concentrate on hospital systems. Channel expansion is gaining share fastest in home care monitoring programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production for metoprolol succinate concentrates among Indian and Chinese contract manufacturers, exposing supply continuity to geopolitical trade friction. Hospital systems in the United States negotiate active pharmaceutical ingredient sourcing at scale. European regulators demand outcome data for heart failure indications.
United States
Integrated delivery networks consolidate purchasing authority across regional hospital systems, creating volume incentives for manufacturers with multi-site formulary placement capabilities. FDA bioequivalence guidance for narrow therapeutic index drugs reshapes generic substitution protocols for nebivolol and certain metoprolol salt forms. Academic medical centers in Boston and the Research Triangle pilot pharmacogenomic-guided metoprolol dosing protocols for CYP2D6 metabolizer status.
Germany
Hospital systems concentrate procurement on bisoprolol for heart failure regimens requiring once-daily dosing compliance and extensive outcome trial evidence. EMA updated cardiovascular guideline requirements mandate hard endpoint data for mortality and hospitalization measures in new market entrants. The Rhine-Ruhr metropolitan region anchors manufacturing infrastructure for sustained-release formulation engineering serving European distribution networks.
India
Contract manufacturers dominate active pharmaceutical ingredient production for metoprolol succinate, supplying cost-sensitive institutional buyers across Anglo-Pacific markets. CDSCO maintains pharmacovigilance reporting standards aligned with international harmonization initiatives. Gujarat and Maharashtra host concentrated API synthesis facilities facing escalating regulatory scrutiny on impurity threshold compliance.
China
Domestic hospital formularies expand sustained-release beta blocker coverage as first-line hypertension management under national essential medicines program revisions. NMPA bioequivalence standards for narrow therapeutic index compounds constrain rapid generic substitution pathways. The Yangtze River Delta clusters pharmaceutical manufacturing infrastructure with integrated chemical synthesis and finished dosage form capabilities.
Australia
Specialty pharmacies capture medication therapy management services as hospital-at-home programs extend prescription continuity from discharge to outpatient settings. TGA aligned pharmacovigilance reporting with Health Canada standards, streamlining multi-region filing pathways for sponsors with coordinated regulatory strategies. Sydney and Melbourne metropolitan health networks pilot chronotherapeutic delivery profiles aligning plasma concentration peaks with morning sympathetic surge patterns.
Cardio-Selective Beta Blockers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue complex modified-release capabilities and pharmacogenomic integration services. The vendor base stratifies between originator cardiovascular franchises and generic manufacturers competing on institutional supply contracts. Three archetypes dominate: multinational pharmaceutical conglomerates with legacy outcome trial assets, mid-cap generic specialists with API-to-tablet integration, and regional contract manufacturers serving cost-sensitive hospital systems. Competitive moves concentrate on sustained-release formulation science investments and strategic partnerships with integrated delivery networks for multi-site formulary placement.
Within the multinational tier, AstraZeneca and Novartis occupy positions anchored by extensive cardiovascular franchise infrastructure and historical outcome trial data packages. Teva Pharmaceutical Industries represents the generic specialist archetype, competing aggressively on bisoprolol and atenolol supply to cost-sensitive institutional buyers. These three entities exemplify the competitive tension between originator brand maintenance and commodity pricing pressure that defines procurement negotiations across United States hospital systems and European hospital formularies.
| Leading Market Players |
|---|
| Merck |
| Viatris |
| AstraZeneca |
| Sanofi |
| AbbVie |
| Novartis |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Sustained-release formulation capability separates premium-tier manufacturers from commodity tablet suppliers, with this bifurcation manifesting in divergent procurement contracts and API sourcing strategies across United States hospital systems and European hospital formularies. FDA narrow therapeutic index bioequivalence constraints on nebivolol and certain metoprolol salt forms preserve pricing power for complex modified-release developers, while immediate-release generic substitution erodes margins for undifferentiated tablet producers.
Pricing Analysis
Service-bundling unbundles across the value chain, with medication therapy management and pharmacogenomic-guided dosing protocols now priced separately from product supply in United States Medicare Advantage contracts. Three-tier pricing structure across premium sustained-release, standard immediate-release, and economy generic tablet levels reflects formulation complexity and bioequivalence certification tiers. Cost compression in immediate-release atenolol and bisoprolol intensifies as Indian and Chinese API suppliers expand capacity. Cost-sensitive institutional buyers in community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Reverse-logistics for expired or recalled cardio-selective beta blockers remains underdeveloped, with limited refurbishment pathways for returned sustained-release formulations outside specialized hospital pharmacy networks. Active pharmaceutical ingredient production for metoprolol succinate concentrates in India, China, and selected European contract manufacturing organizations. Key inputs include metoprolol base compounds, succinate salt forms, and multiparticulate bead excipients. Single-source vulnerability in Indian API synthesis facilities exposes supply continuity to regulatory inspection disruptions and geopolitical trade friction. Distribution runs through integrated delivery network central warehouses and specialty pharmacy direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in sustained-release formulation engineering prop pricing power, with capacity bottlenecks in multiparticulate bead technology and chronotherapeutic delivery profiles limiting rapid generic entry.
For Market Incumbents: Anchor formulary positioning through backward integration into API synthesis and captive supply of metoprolol succinate precursors. Defend against fixed-dose combination displacement by bundling pharmacogenomic testing services with prescribing protocols. Prioritize capacity addition in Rhine-Ruhr metropolitan region manufacturing clusters to secure European hospital system contracts. For New Entrants and Emerging Players: Pharmacogenomic-guided dosing platform development offers technology-first entry into specialty cardiology clinics concentrated in Boston and Research Triangle metropolitan areas. Target pediatric liquid formulation gaps for bisoprolol across North American markets, where age-appropriate dosing formats remain undeveloped. Pursue hospital-at-home program partnerships as primary go-to-market channel, capturing medication therapy management services previously internal to hospital systems. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap generic specialists possessing API-to-tablet integration capabilities given EMA outcome data requirements elevating capital barriers for new cardiovascular market entrants. Long-term viability favors manufacturers with demonstrated sustained-release formulation science and established integrated delivery network relationships. Monitor FDA bioequivalence guidance revisions for narrow therapeutic index compounds as inflection indicator for generic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multiparticulate Bead Technology Investment | Chronotherapeutic delivery profiles align plasma peaks with morning sympathetic surge patterns in resistant hypertension populations. |
| Pharmacogenomic Testing Integration | CYP2D6 metabolizer status protocols expand into specialty cardiology clinics with narrow therapeutic index monitoring expertise. |
| API Sourcing Diversification | Backward integration into metoprolol succinate precursor synthesis reduces exposure to Indian and Chinese contract manufacturer concentration. |
| Hospital-at-Home Partnership Development | Specialty pharmacy channel capture extends prescription continuity from discharge to outpatient settings under Medicare Advantage capitation. |
| Pediatric Formulation Pipeline Expansion | Liquid and age-appropriate bisoprolol formats address underpenetrated North American and European market gaps. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and specialty pharmacy operations executives. FDA bioequivalence guidance documents, EMA cardiovascular guideline submissions, ClinicalTrials.gov outcome trial registries, and United States hospital formulary databases provided validation sources. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis triangulated market sizing across the analysis window.
Granularity-level modeling disaggregated volume and value outputs by product type, application, delivery mode, and end user, with regional regulatory clusters and CYP2D6 metabolizer prevalence patterns incorporated as industry-specific dimensions. CAGR derivation synthesized historical prescription trend analysis, patent expiration timelines, and formulation technology diffusion curves. Forecast inputs included integrated delivery network consolidation trajectories, pharmacogenomic testing adoption curves, and hospital-at-home program expansion rates.
Several conditions sit outside the modeled scope, including unforeseen FDA bioequivalence standard revisions, abrupt geopolitical trade restrictions on API imports, and breakthrough fixed-dose combination therapies displacing beta blocker monotherapy. Forecasts reflect documented assumptions regarding sustained-release formulation adoption rates and narrow therapeutic index substitution barriers. Material deviation in EMA outcome data requirements, pharmacopeial monograph harmonization progress, or specialty cardiology talent availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Stroke Management Market