
 Global Restless Legs Syndrome Market | 2026-2036
Global Restless Legs Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Global Restless Legs Syndrome Market Foresight
Market Context
Iron supplementation is broadening treatment economics for restless legs syndrome patients with ferritin-deficient profiles. Boehringer Ingelheim International GmbH leverages its dopamine agonist portfolio to sustain leadership in pharmacological treatments across European sleep centers. Sun Pharmaceutical Industries Ltd anchors its competitive position through generic manufacturing scale in neurology-focused dosage forms. GlaxoSmithKline plc differentiates via established brand strength in dopaminergic therapy areas across hospital distribution channels.
Technical Definition and Segment Structure
Restless legs syndrome constitutes a sensorimotor neurological disorder characterized by an irresistible urge to move the legs, typically accompanied by uncomfortable sensations during periods of rest, with diagnostic criteria requiring symptom onset at rest, partial relief with movement, and circadian worsening in evening hours. The condition primarily serves clinical and commercial purposes through chronic disease management, sleep quality restoration, and reduction of secondary cardiovascular complications linked to sleep deprivation. Pharmacological treatments occupy the dominant margin pool due to entrenched prescribing habits among neurologists and sleep specialists, while wearable sensors represent the fastest-expanding category as real-time limb movement monitoring technology matures. Non-pharmacological devices sit at an earlier commercialization stage, with reimbursement codes still consolidating across major healthcare systems.
Regulatory Framework and Outlook
The FDA governs neuromodulation and wearable device approvals through premarket pathways for restless legs syndrome adjunct therapies, while the EMA's MDR framework imposes stricter clinical evidence requirements on European device manufacturers. Japan's PMDA maintains distinct pharmacovigilance protocols for dopamine agonists that shape post-market surveillance obligations for UCB S.A. and Jazz Pharmaceuticals plc. Stakeholders must monitor evolving reimbursement decisions for non-pharmacological interventions across Medicare, NHS England, and Germany's G-BA to anticipate channel shifts between retail pharmacies and home care settings.
Market Dynamics
The restless legs syndrome market is bifurcating around neuromodulation device reimbursement decisions, with FDA premarket pathways for wearable sensors creating divergent commercial timelines versus entrenched dopamine agonist prescribing patterns among sleep specialists.
Growth Catalysts
- Iron Deficiency Screening Protocols:Expanded ferritin testing in primary care settings is identifying subclinical RLS cases earlier, broadening the addressable patient pool for pharmacological intervention.
- EMA MDR Device Pathways:Streamlined clinical evidence requirements for Class IIa neuromodulation devices are accelerating European market entry for non-pharmacological alternatives.
- Home Care Monitoring Infrastructure:Wearable limb movement sensors integrated with telemedicine platforms enable remote symptom tracking, reducing specialist visit burden while maintaining therapeutic oversight.
Market Restraints
- Reimbursement Code Fragmentation:Medicare's non-coverage determinations for experimental neuromodulation devices limit US patient access despite FDA clearance.
- Active Pharmaceutical Ingredient Concentration:Dopamine agonist raw material synthesis concentrates among Indian contract manufacturers, creating supply vulnerability for European formulation facilities.
- Augmentation Ceiling:Long-term levodopa use triggers symptom worsening in 60-80% of patients, capping chronic therapy duration and forcing treatment cycling.
Strategic Opportunities
- German Sleep Center Network Expansion:G-BA reimbursement incentives for integrated diagnostic pathways position specialized clinics as high-volume prescription gateways.
- AI-Powered Polysomnography Integration:Machine learning algorithms analyzing nocturnal limb movement patterns from standard sleep studies enable cost-effective RLS screening without dedicated actigraphy.
- Japan's Elderly Care Integration:METI guidelines promoting non-pharmacological dementia comorbidity management create channel access for neuromodulation devices in nursing home settings.
Industry Challenges
- Biomarker Validation Timelines:CSF neurofilament light chain and other proposed RLS severity correlates lack standardized assay certification, delaying stratified medicine implementation.
- Legacy EHR Integration Friction:Sleep clinic information systems require costly middleware development to incorporate real-time wearable sensor data streams into clinical decision workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Restless Legs Syndrome Market |
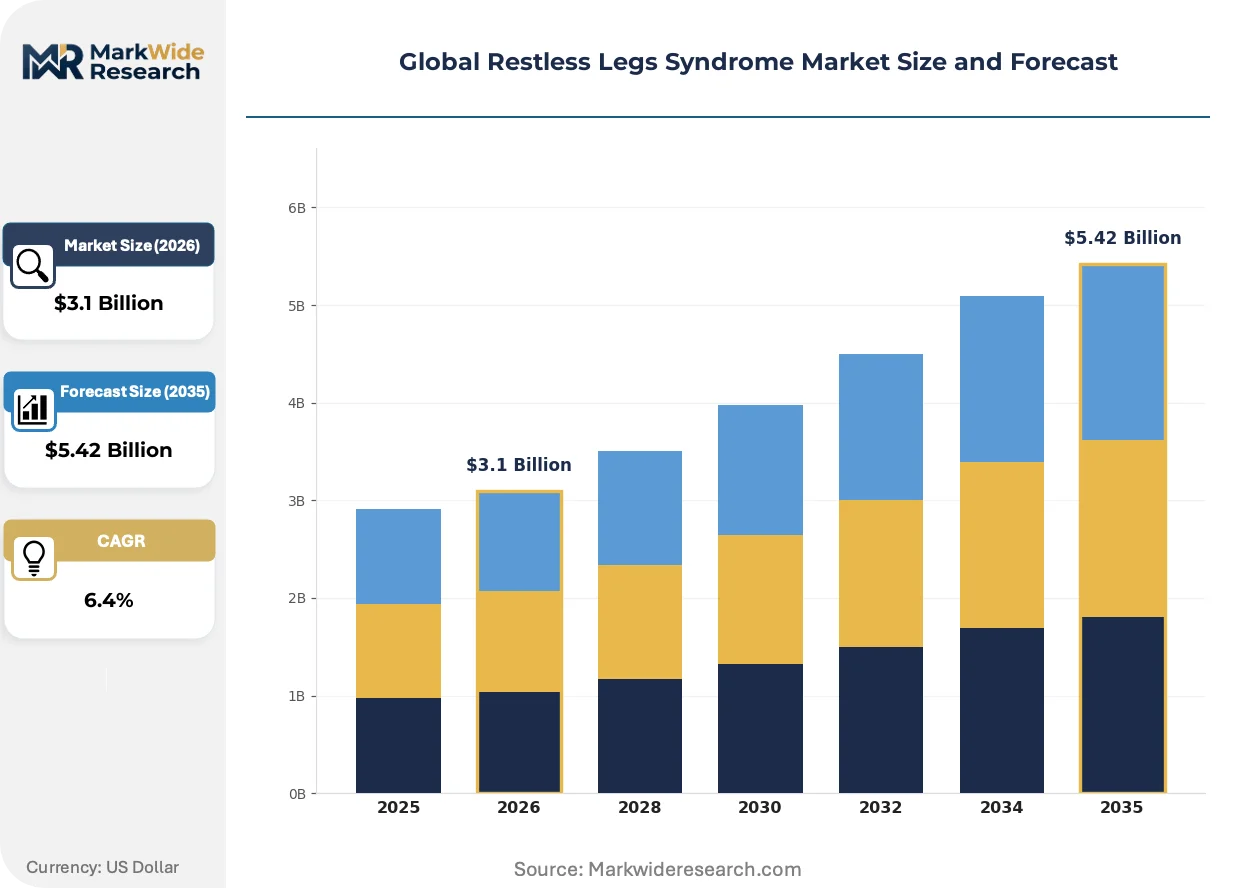
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacological Treatments, Non-Pharmacological Devices, Supplements, Wearable Sensors, Others Therapy Area: Neurological Disorders, Sleep Disorders, Dopaminergic Dysfunction, Iron-Deficiency Related, Peripheral Neuropathy, Others End User: Specialized Clinics, Sleep Centers, Neurology Clinics, Diagnostic Laboratories, Home Care Settings Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Direct Sales, Wholesale Distributors |
| Companies Covered | Boehringer Ingelheim International GmbH, Sun Pharmaceutical Industries Ltd, GlaxoSmithKline plc, Ligand Pharmaceuticals, Inc., Azurity Pharmaceuticals, LLC, UCB S.A., Jazz Pharmaceuticals plc, Kyowa Hakko Kirin Co., Ltd, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Restless Legs Syndrome Market Shifts & Advancements
Neuromodulation hardware miniaturization and algorithmic symptom prediction are converging to shift treatment locus from episodic clinical intervention toward continuous home-based management, compressing the traditional pharmaceutical-dominant care model.
Wearable transcutaneous electrical nerve stimulation devices are absorbing patient preference share among chronic RLS sufferers seeking dopamine-sparing alternatives. Sleep medicine practices in the Netherlands and Sweden are piloting prescription-to-device pathways that bypass traditional pharmacy dispensing. The technology is absorbing margin pressure from generic dopamine agonist price erosion by capturing out-of-pocket wellness spending.
Japan's PMDA revised its pharmacovigilance protocols for ergot-derived dopamine agonists, mandating enhanced cardiac valvulopathy monitoring in post-market surveillance programs. This regulatory tightening is compressing prescribing confidence for pergolide and cabergoline formulations across East Asian markets. Device manufacturers are responding by accelerating clinical trial enrollment for non-pharmacological alternatives in Tokyo and Osaka sleep centers.
Patient-initiated therapy switching is compressing brand loyalty cycles in dopaminergic treatments, with online symptom communities facilitating peer-to-peer comparison of augmentation risks and device efficacy claims. Hospital-based neurology departments are losing prescription control to direct-to-consumer wearable channels in urban Australian and Canadian markets. This behavioral shift is most pronounced among patients with ferritin-normal RLS phenotypes who have exhausted first-line pharmacological options.
Global Restless Legs Syndrome Market Segmentation
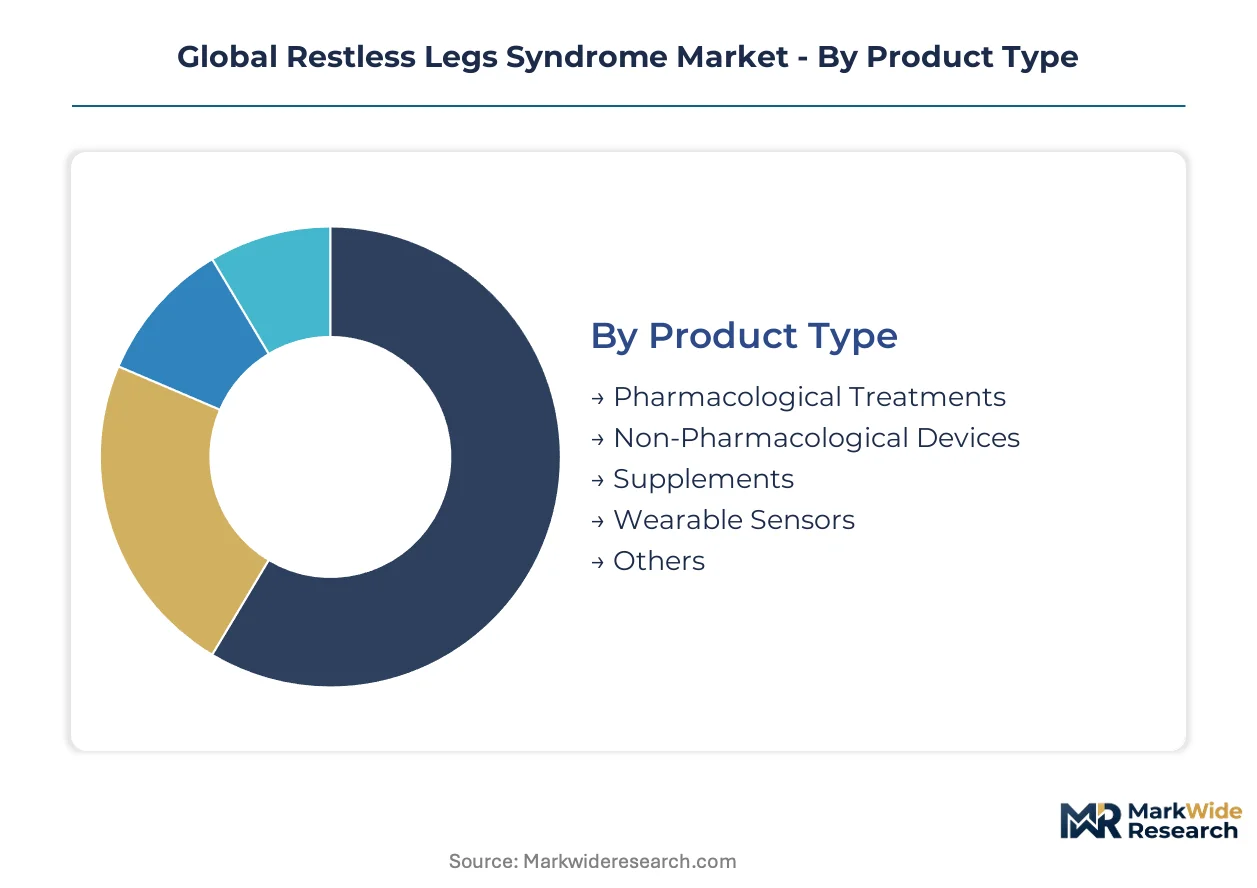
Segmentation in the restless legs syndrome market tracks divergent reimbursement pathways and patient mobility preferences. Product type splits reveal pharmaceutical margin concentration versus device growth acceleration. Therapy area and end user dimensions expose where diagnostic capacity expansion meets home-based monitoring adoption.
Product Type:
Cost tier separates chronic medication users from out-of-pocket device purchasers seeking dopamine-sparing alternatives.
- Pharmacological Treatments:Dopamine agonists and alpha-2-delta ligands constitute the established standard of care with entrenched prescriber familiarity. Hospital formularies in Germany and the United States maintain preferential contracting for these agents despite augmentation risks limiting long-term use.
- Wearable Sensors:Real-time limb actigraphy devices integrate with telemedicine platforms to enable remote symptom quantification. Sleep medicine practices in the Netherlands and Sweden are piloting prescription-to-device pathways that bypass traditional pharmacy dispensing entirely.
- Non-Pharmacological Devices:Transcutaneous electrical nerve stimulation units target patients with ferritin-normal phenotypes who have exhausted pharmacological options.
- Supplements:Iron formulations serve ferritin-deficient patient subpopulations identified through expanded primary care screening protocols.
- Others:Emerging therapeutic categories including pneumatic compression garments and vibratory stimulation devices occupy early commercialization stages.
Volume sits with pharmacological treatments; growth tilts toward wearable sensors.
Therapy Area:
Application focus distinguishes between primary idiopathic presentations and secondary comorbid conditions driving differential treatment selection.
- Dopaminergic Dysfunction:Central nervous system dopamine pathway irregularities define the core pathophysiological mechanism for moderate-to-severe cases. German sleep centers and neurology clinics are expanding diagnostic capacity specifically for this phenotype.
- Iron-Deficiency Related:Peripheral iron insufficiency correlates with symptom severity in subclinical populations identified through ferritin testing. Primary care screening expansion in the United States and United Kingdom is broadening the addressable patient pool for supplementation protocols.
- Neurological Disorders:Comorbid Parkinson's disease and multiple sclerosis presentations require integrated movement disorder management.
- Sleep Disorders:Periodic limb movement disorder overlap drives polysomnography referral patterns in tertiary care settings.
- Peripheral Neuropathy:Diabetes and uremia-associated sensory-motor symptoms complicate differential diagnosis.
- Others:Pregnancy-related and medication-induced subtypes require specialized obstetric or psychiatric co-management.
Clinical volume concentrates in dopaminergic dysfunction; iron-deficiency related cases are climbing the fastest as screening protocols expand.
End User:
Customer type reflects the shift from institutional diagnosis toward distributed home-based monitoring infrastructure.
- Specialized Clinics:Integrated sleep medicine and movement disorder centers provide comprehensive diagnostic workups including polysomnography and actigraphy. Germany's G-BA reimbursement incentives position these facilities as high-volume prescription gateways.
- Home Care Settings:Patient-directed monitoring with wearable sensors reduces specialist visit burden while maintaining therapeutic oversight. Urban Australian and Canadian markets show pronounced behavioral shift toward direct-to-consumer device channels.
- Sleep Centers:Dedicated nocturnal monitoring facilities concentrate polysomnography capacity for complex differential diagnosis.
- Neurology Clinics:Movement disorder specialists manage augmentation complications and treatment cycling protocols.
- Diagnostic Laboratories:Ferritin and iron panel testing sites identify supplementation candidates in primary care referral networks.
Patient volume remains with specialized clinics; expansion tilts most sharply toward home care settings.
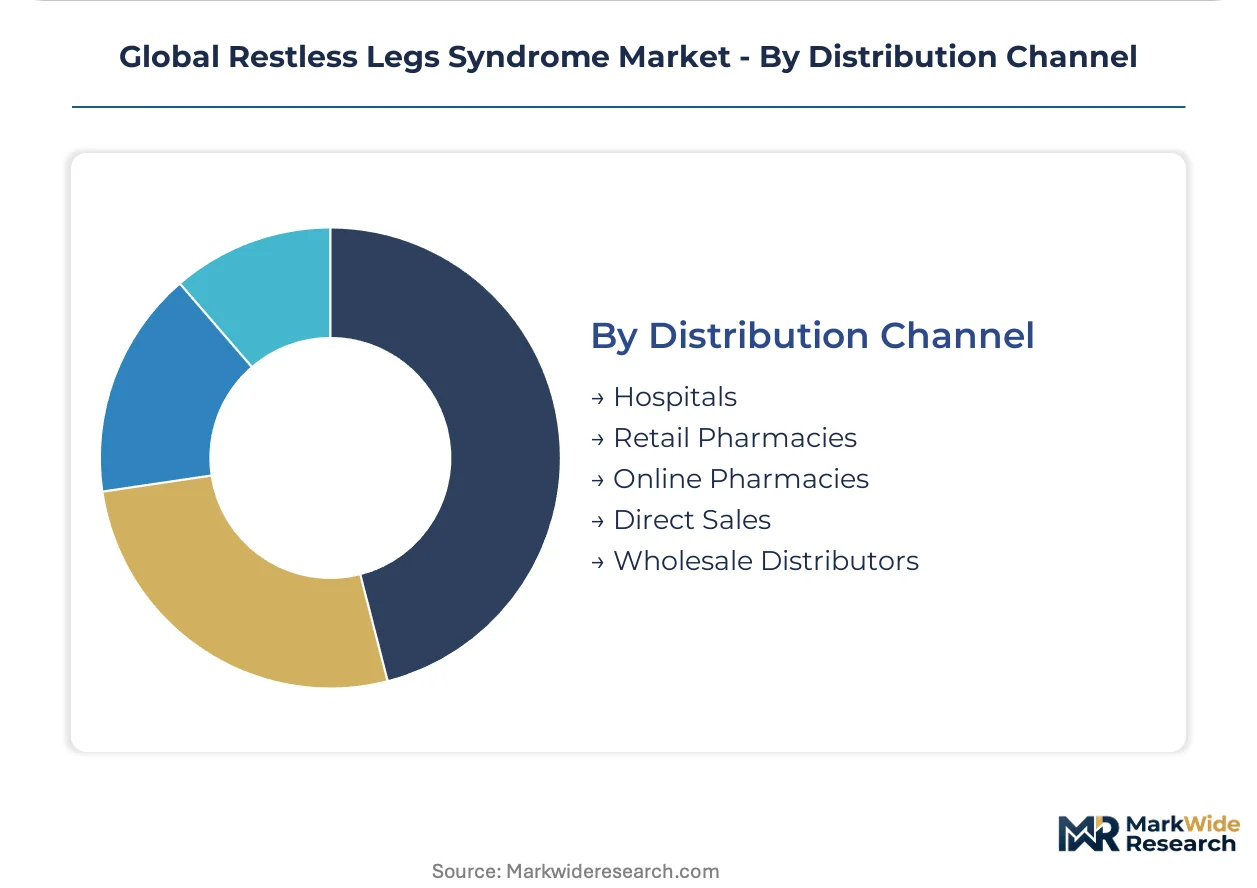
Distribution Channel:
Supply concentration varies between institutional procurement and retail pharmacy networks versus emerging direct-to-patient pathways.
- Hospitals:Inpatient and outpatient pharmacy operations manage formulary-controlled dopamine agonist distribution. Hospital-based neurology departments in Japan maintain strict PMDA pharmacovigilance compliance for ergot-derived formulations.
- Online Pharmacies:Digital dispensing platforms capture patient-initiated therapy switching among brand-comparison-seeking chronic sufferers. Patient forums facilitate peer-to-peer augmentation risk discussion that compresses loyalty cycles.
- Retail Pharmacies:Community-based dispensing maintains geographic accessibility for maintenance medication refills.
- Direct Sales:Manufacturer-to-patient wearable device distribution bypasses traditional pharmacy markup structures.
- Wholesale Distributors:Centralized procurement serves institutional accounts with volume-based contracting.
Pharmaceutical volume flows through hospitals; device distribution is gaining share fastest via online and direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient volume concentrates in Germany, where specialized sleep centers and neurology clinics are expanding diagnostic capacity for dopaminergic dysfunction-related cases. The United States and Japan follow as distinct regulatory environments shaping device approval timelines and pharmacovigilance obligations. Home care adoption is accelerating most sharply in Australia and Canada as direct-to-consumer wearable channels bypass traditional pharmacy distribution.
United States
FDA premarket pathways for neuromodulation devices are reshaping product approval timelines for wearable sensor manufacturers. Medicare's non-coverage determinations for experimental devices limit patient access despite regulatory clearance. Sleep medicine practices in Boston and Stanford clusters are piloting integrated diagnostic-to-treatment protocols for ferritin-deficient patient subpopulations.
Germany
G-BA reimbursement incentives for integrated diagnostic pathways position specialized clinics as high-volume prescription gateways for dopamine agonist therapies. The EMA's MDR framework imposes stricter clinical evidence requirements on domestic device manufacturers seeking Class IIa neuromodulation approvals. Munich and Hamburg sleep center networks are consolidating polysomnography capacity with real-time actigraphy integration.
Japan
METI guidelines promoting non-pharmacological dementia comorbidity management create channel access for neuromodulation devices in nursing home settings. PMDA revised pharmacovigilance protocols for ergot-derived dopamine agonists, mandating enhanced cardiac valvulopathy monitoring in post-market surveillance programs. Tokyo and Osaka sleep centers are accelerating clinical trial enrollment for device alternatives as prescribing confidence compresses.
Australia
Urban markets show pronounced behavioral shift toward direct-to-consumer wearable channels as hospital-based neurology departments lose prescription control. The TGA maintains distinct approval pathways for transcutaneous electrical nerve stimulation devices compared to pharmaceutical registrations. Melbourne and Sydney patient communities facilitate peer-to-peer augmentation risk discussion that compresses brand loyalty cycles in dopaminergic treatments.
Canada
Health Canada oversees parallel review processes for neuromodulation devices and dopamine agonist formulations that create divergent commercial timelines. Provincial reimbursement decisions for non-pharmacological interventions remain fragmented across Ontario, Quebec, and British Columbia health authorities. Toronto and Vancouver sleep medicine practices are integrating AI-powered polysomnography analysis to enable cost-effective RLS screening without dedicated actigraphy.
Global Restless Legs Syndrome Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance dopamine agonist legacy revenue against device category expansion. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with neurology-focused divisions, mid-cap generic manufacturers with neurology dosage form specialization, and emerging device developers targeting home care monitoring infrastructure. Strategic archetypes include the diversified pharma incumbent defending formulary position, the scale-driven generic supplier capturing price-eroded volume, and the technology-native device developer bypassing traditional pharmacy channels. Competitive intensity centers on M&A activity targeting wearable sensor platforms and strategic partnerships integrating real-time monitoring with telemedicine infrastructure.
Among European-based pharmaceutical specialists, Boehringer Ingelheim International GmbH and UCB S.A. occupy positions within the diversified incumbent tier, with the former representing established dopamine agonist portfolio strength and the latter exemplifying integrated movement disorder management capabilities. GlaxoSmithKline plc anchors the hospital distribution channel archetype through brand strength in dopaminergic therapy areas. These entities exemplify how legacy pharmaceutical players are responding to device category pressure through formulation lifecycle management and geographic contracting concentration rather than direct technology acquisition.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Sun Pharmaceutical Industries Ltd |
| GlaxoSmithKline plc |
| Ligand Pharmaceuticals, Inc. |
| Azurity Pharmaceuticals, LLC |
| UCB S.A. |
| Jazz Pharmaceuticals plc |
| Kyowa Hakko Kirin Co., Ltd |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
EMA MDR sustainability and clinical evidence mandates gate qualified supply for Class IIa neuromodulation devices, reserving premium-tier pricing access for manufacturers with robust post-market surveillance infrastructure while generic dopamine agonist producers compete on cost without such certification burdens.
Pricing Analysis
Volume concentrates in generic dopamine agonist formulations where Indian contract manufacturers compete on scale, while margins accrue to branded device developers with FDA-cleared wearable sensors. Price differentiation separates premium neuromodulation units with real-time telemedicine integration from standard pharmacological maintenance therapies. Pricing pressure stems from Medicare non-coverage determinations for experimental devices that compress out-of-pocket affordability. Hospital formularies in Germany demonstrate lowest price sensitivity due to G-BA reimbursement security, whereas direct-to-consumer channels in Australia face acute cost consciousness among augmentation-affected patients cycling therapies.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for dopamine agonists rests on Indian specialty chemical producers and Chinese intermediate suppliers, with European formulation facilities completing final dosage manufacturing. Raw material dependencies include ergot alkaloid derivatives, alpha-2-delta ligand precursors, and lithium-ion cells for wearable device power systems. Single-source vulnerability concentrates in ergot-derived raw material extraction where climatic conditions constrain harvest predictability. Distribution runs through hospital procurement consortia for pharmacological products and direct-to-patient e-commerce for sensor-enabled home care devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The restless legs syndrome market sits in a technology-transition phase where wearable neuromodulation devices are displacing chronic dopamine agonist dependency among ferritin-normal patient cohorts.
For Market Incumbents: Lock in formulary positioning at German G-BA-contracted sleep centers before device reimbursement codes consolidate, while acquiring wearable sensor platforms to hedge against direct-to-consumer channel erosion. Augmentation risk education and lifecycle management of existing dopamine agonist portfolios remain essential defensive levers against non-pharmacological substitution. For New Entrants and Emerging Players: Enter via Japan's nursing home METI-aligned channels where dementia comorbidity protocols create reimbursement pathways for neuromodulation devices without competing against entrenched pharmacy distribution. Australia's urban direct-to-consumer wearable market offers the most penetrable geography given hospital neurology department prescription control weakening. For Investors and Strategic Acquirers: FDA premarket pathway acceleration for wearable sensors is the leading indicator that home care monitoring infrastructure will capture margin share from pharmaceutical incumbents. Target acquisition profiles center on device developers with validated limb actigraphy algorithms and existing telemedicine platform integrations. Watch G-BA reimbursement decisions for integrated diagnostic pathways as the signal for European market tipping.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | G-BA and Medicare coding decisions determine patient access for neuromodulation alternatives. |
| Wearable Sensor Platform Acquisition | Real-time actigraphy capability compresses competitive moats for legacy pharmaceutical portfolios. |
| Clinical Trial Enrollment Acceleration | PMDA-mandated cardiac monitoring for ergot agonists creates device trial recruitment opportunities in Japan. |
| Telemedicine Infrastructure Partnership | Remote symptom tracking integration reduces specialist visit burden while maintaining therapeutic oversight. |
| Iron Deficiency Screening Protocol Expansion | Primary care ferritin testing broadens addressable patient pools for supplementation and device stratification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among sleep medicine clinicians, hospital formulary directors, neurology procurement managers, and wearable device regulatory affairs specialists. FDA 510(k) submissions, EMA MDR technical documentation, PMDA pharmacovigilance reports, and G-BA reimbursement determinations provided secondary validation. Bottom-up patient volume estimates triangulated against top-down pharmaceutical and device revenue allocations across the analysis window.
Data-stream reconciliation across product type, therapy area, end user, and distribution channel dimensions generated segmented volume and value outputs. CAGRs derived from trend extrapolation of historical approval timelines, reimbursement adoption curves, and patient demographic shifts. Forecast inputs incorporated iron deficiency screening protocol expansion rates, wearable sensor technology maturation, and pharmacological augmentation incidence patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement code fragmentation and raw material supply disruption scenarios. Projections reflect assumptions regarding regulatory pathway stability and patient behavioral adoption curves. A small set of named triggers—Medicare coverage determinations, G-BA integrated diagnostic incentives, and PMDA device trial outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Glaucoma Market