
 Cat Scratch Disease (CSD) Treatment Market | 2026-2036
Cat Scratch Disease (CSD) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Scratch Disease (CSD) Treatment Market Outlook
Aftermarket service revenue from post-treatment monitoring and recurrence management is reconfiguring margin pools across the CSD treatment landscape. Sanofi S.A. leverages its established anti-infective portfolio to sustain hospital formulary presence in European markets. Pfizer Inc. anchors its competitive stance through manufacturing scale in oral antibiotic production. Teva Pharmaceutical Industries Ltd. differentiates via cost-efficient generic azithromycin supply to clinic networks.
Cat Scratch Disease treatment encompasses antimicrobial and supportive therapies targeting Bartonella henselae infection transmitted through feline scratches or bites, with azithromycin serving as the first-line agent due to its intracellular penetration and pediatric safety profile. The primary purpose centers on eliminating bacteremia, preventing disseminated complications such as neuroretinitis or hepatosplenic involvement, and reducing symptom duration in immunocompetent and immunocompromised patients. Antibiotics dominate current prescribing patterns, while the pediatric care therapy area generates disproportionate volume given disease prevalence in children under fifteen. Oral delivery mode captures the majority of commercial value, though intravenous administration retains critical importance for hospitalized patients with systemic manifestations.
The FDA's Qualified Infectious Disease Product designation shapes development incentives for novel Bartonella therapeutics, while the EMA's antibacterial guidance influences trial endpoints for European market access. The CDC's cat-associated disease surveillance protocols indirectly steer diagnostic testing volumes and treatment initiation criteria across US clinical settings. Stakeholders must monitor evolving resistance patterns in Bartonella species and regulatory shifts toward narrow-spectrum antibacterial prioritization when allocating R&D resources across formulation development programs.
Market Dynamics
The Cat Scratch Disease treatment market is being fundamentally restructured by the FDA's Qualified Infectious Disease Product designation, which redirects R&D investment toward narrow-spectrum antibacterial development and away from legacy broad-spectrum agents that have dominated Bartonella therapy for decades.
Growth Catalysts
- Pediatric formulary expansion:Azithromycin's established safety profile in children under fifteen drives hospital protocol adoption across US acute care networks.
- EMA antibacterial guidance:Streamlined trial endpoints for intracellular pathogens accelerate European market access timelines for novel Bartonella therapeutics.
- Feline ownership concentration:Elevated cat population density in suburban US counties generates sustained incident case volume for primary care diagnosis.
Market Restraints
- API supply concentration:Azithromycin active pharmaceutical ingredient production clusters in Chinese and Indian chemical manufacturing zones, exposing formulation sponsors to geopolitical logistics disruption.
- Diagnostic confirmation delays:Bartonella henselae serology turnaround times of 5-7 days in outpatient settings delay treatment initiation and compress prescription capture rates.
- Spontaneous resolution pattern:Immunocompetent patient populations frequently recover without antimicrobial intervention, limiting addressable prescription volume in mild case presentations.
Strategic Opportunities
- Point-of-care molecular diagnostics:PCR-based Bartonella detection at the clinic level collapses confirmation timelines from days to hours.
- Post-treatment monitoring services:Recurrence tracking and neuro-ophthalmic surveillance create annuity revenue streams beyond initial prescription fulfillment.
- IRActax credits:US domestic manufacturing incentives for critical antibiotics reduce cost structures for oral solid dose production.
Industry Challenges
- Intracellular pharmacokinetic expertise:Limited clinical pharmacology talent capable of optimizing tissue penetration for Bartonella's endothelial niche slows formulation advancement.
- Resistance surveillance infrastructure:Fragmented national reporting systems for Bartonella susceptibility patterns undermine empirical therapy confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Scratch Disease (CSD) Treatment Market |
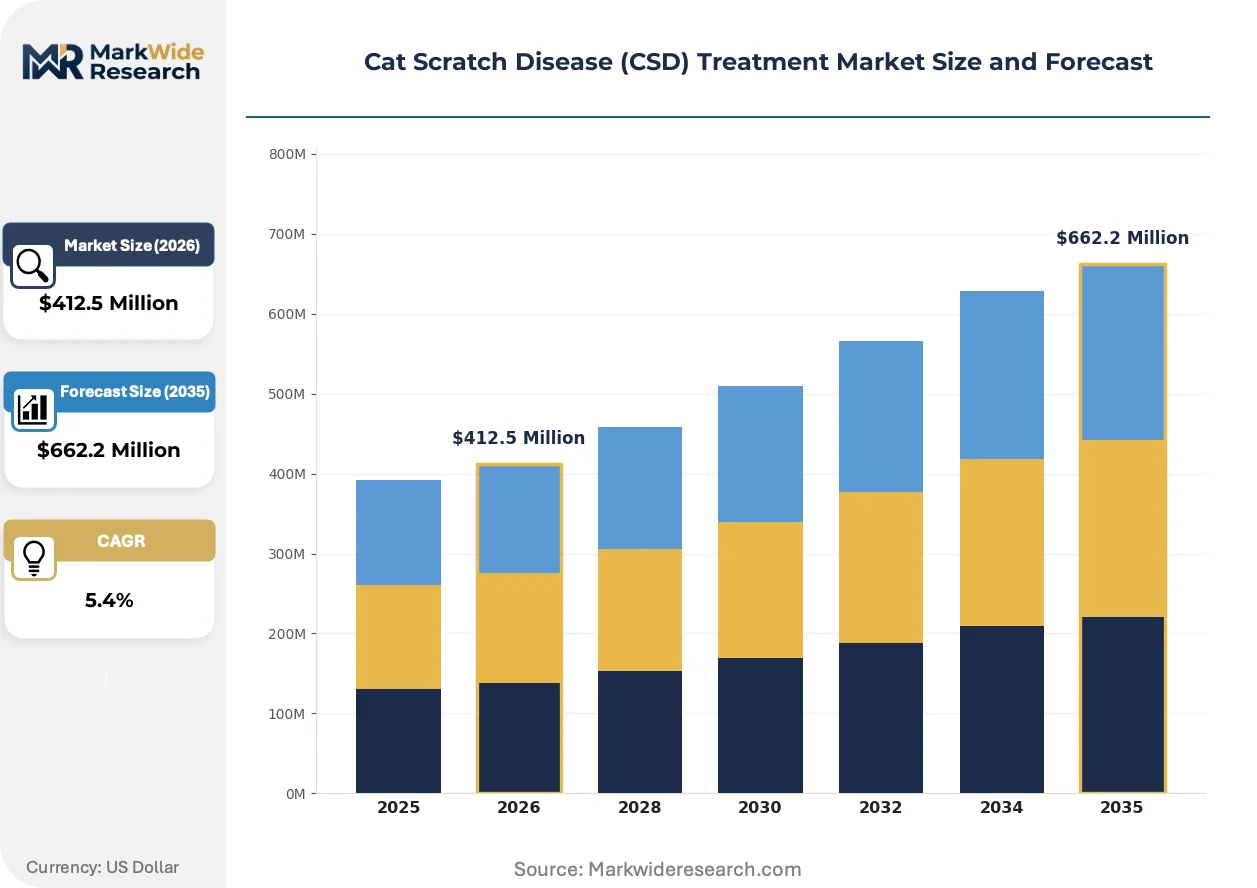
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antipyretics, Analgesics, Immunoglobulins Therapy Area: Infectious Diseases, Pediatric Care, Immunology, Primary Care Delivery Mode: Oral, Intravenous, Subcutaneous, Intra-muscular End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Sanofi S.A., Johnson & Johnson Services, Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., AstraZeneca plc, Merck & Co., Inc., GlaxoSmithKline plc, Abbott Laboratories, Novartis International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Scratch Disease (CSD) Treatment Market Strategic Shifts
Novel formulation development is pivoting toward targeted intracellular delivery mechanisms as developers recognize the limitations of conventional oral antibiotics against Bartonella's endothelial persistence.
Extended-release azithromycin matrix technologies are migrating from cardiovascular applications into anti-infective development pipelines. Pediatric infectious disease specialists at US academic medical centers are piloting these formulations to reduce dosing frequency from daily to twice-weekly regimens. This migration is compressing adherence failure rates and opening reimbursement pathways for premium-priced specialty formulations.
The FDA's streamlined antibacterial development pathways are restructuring clinical trial design requirements for Bartonella therapeutics. Sponsors now qualify for priority review vouchers upon demonstrating superiority against intracellular pathogen burdens. Hospital formulary committees in US tertiary care centers are responding by pre-approving QIDP-designated agents for empirical therapy protocols.
Primary care networks are consolidating diagnostic testing decisions under centralized infectious disease stewardship programs. Large US clinic systems are displacing individual physician test ordering with protocol-driven PCR reflex algorithms. This concentration is most visible in Texas and Florida multi-site pediatric practices where case volume justifies dedicated laboratory infrastructure.
Cat Scratch Disease (CSD) Treatment Market Segmentation
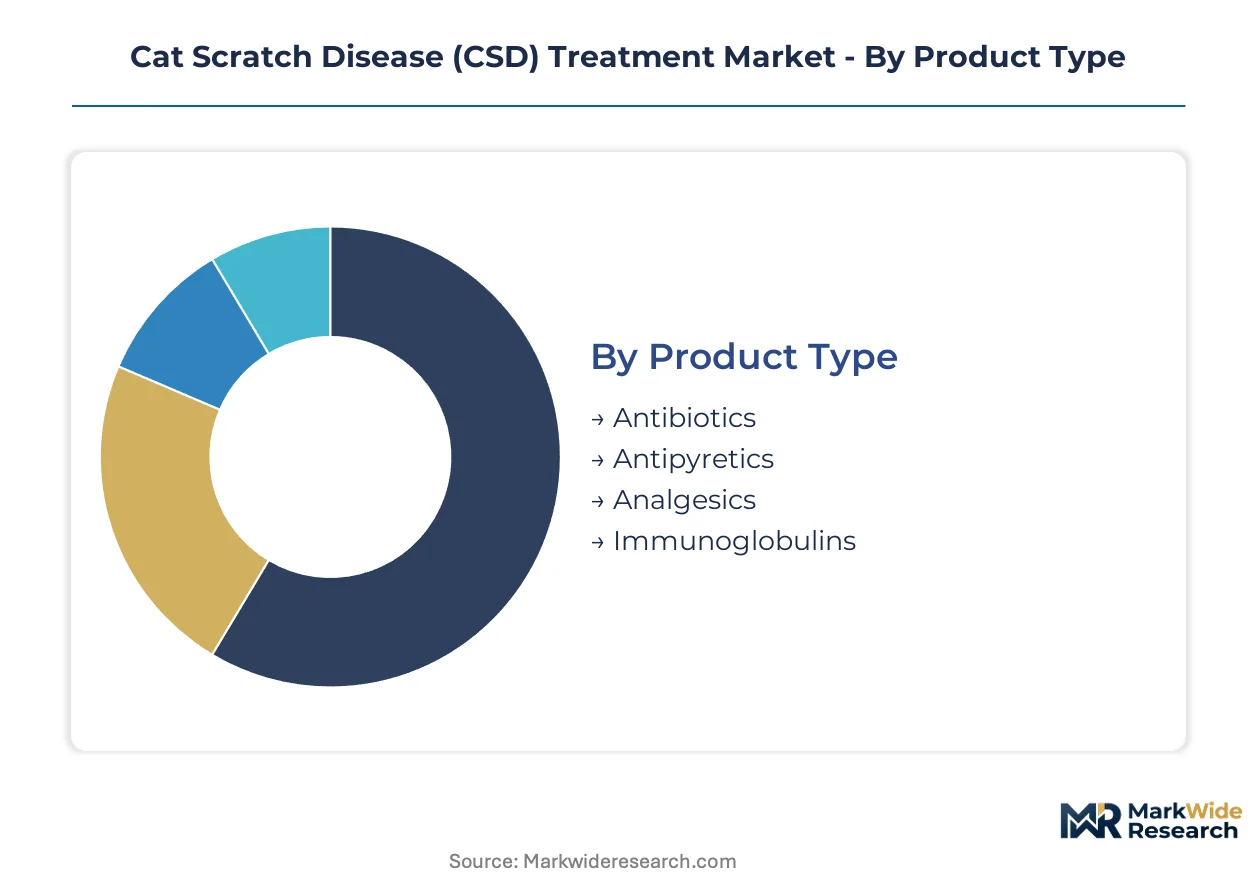
Segmentation in the Cat Scratch Disease treatment market reveals distinct procurement cycles and margin structures across therapeutic categories. Each dimension carries implications for inventory management, reimbursement pathways, and competitive positioning within Bartonella therapy protocols.
Product Type:
Antibiotics turn over fastest in hospital formularies with quarterly protocol reviews, while immunoglobulins cycle slowest due to cold-chain logistics and specialist ordering patterns.
- Antibiotics:Azithromycin and rifampin combinations dominate prescribing patterns through intracellular penetration against Bartonella henselae. Pediatric infectious disease protocols at US academic medical centers drive volume concentration, with EMA antibacterial guidance accelerating novel formulation access in European markets.
- Antipyretics:Adjunctive fever management accompanies antimicrobial therapy in acute presentations. Demand clusters in primary care networks across suburban US counties where cat ownership density generates incident cases.
- Analgesics:Pain management supports symptomatic relief during lymphadenopathy resolution. Generic ibuprofen and acetaminophen formulations capture standard-of-care positioning without specialty pricing premiums.
- Immunoglobulins:Reserved for immunocompromised patients with disseminated Bartonella complications. Infusion center networks and home healthcare providers manage the extended administration cycles.
Antibiotics anchor the volume base while immunoglobulins gain share at the steepest rate among product categories.
Therapy Area:
Cost tier stratification separates high-acuity infectious disease intervention from routine primary care management, with pediatric applications commanding premium reimbursement.
- Infectious Diseases:Specialist-directed therapy for neuroretinitis, hepatosplenic involvement, and disseminated Bartonella bacteremia. Tertiary care centers in Texas and Florida concentrate complex case management.
- Pediatric Care:Azithromycin's established safety profile drives disproportionate prescription volume in children under fifteen. FDA streamlined antibacterial pathways accelerate pediatric formulation approvals.
- Immunology:Management of Bartonella complications in HIV-positive and transplant recipient populations. IV administration dominates this segment due to systemic manifestation severity.
- Primary Care:First-line diagnosis and treatment initiation for uncomplicated lymphadenopathy presentations. Diagnostic confirmation delays of 5-7 days compress prescription capture in outpatient settings.
Pediatric care generates the highest revenue per patient episode while primary care delivers the broadest addressable volume base.
Delivery Mode:
Application context determines route selection, with oral formulations serving ambulatory populations and parenteral routes reserved for hospitalized systemic cases.
- Oral:Extended-release azithromycin matrix technologies reduce dosing frequency from daily to twice-weekly. US clinic networks pilot these formulations to compress adherence failure rates.
- Intravenous:Required for neuroretinitis, encephalopathy, and severe immunocompromised presentations. Hospital formulary committees pre-approve QIDP-designated agents for empirical therapy protocols.
- Subcutaneous:Limited application for specific immunoglobulin formulations in homecare settings. Cold-chain infrastructure requirements constrain distribution to specialized pharmacy networks.
- Intra-muscular:Alternative parenteral route for select antibiotic formulations when IV access is problematic. Emergency department protocols incorporate this option for acute presentations.
Oral administration captures the majority of commercial value while intravenous delivery commands the highest per-dose pricing.
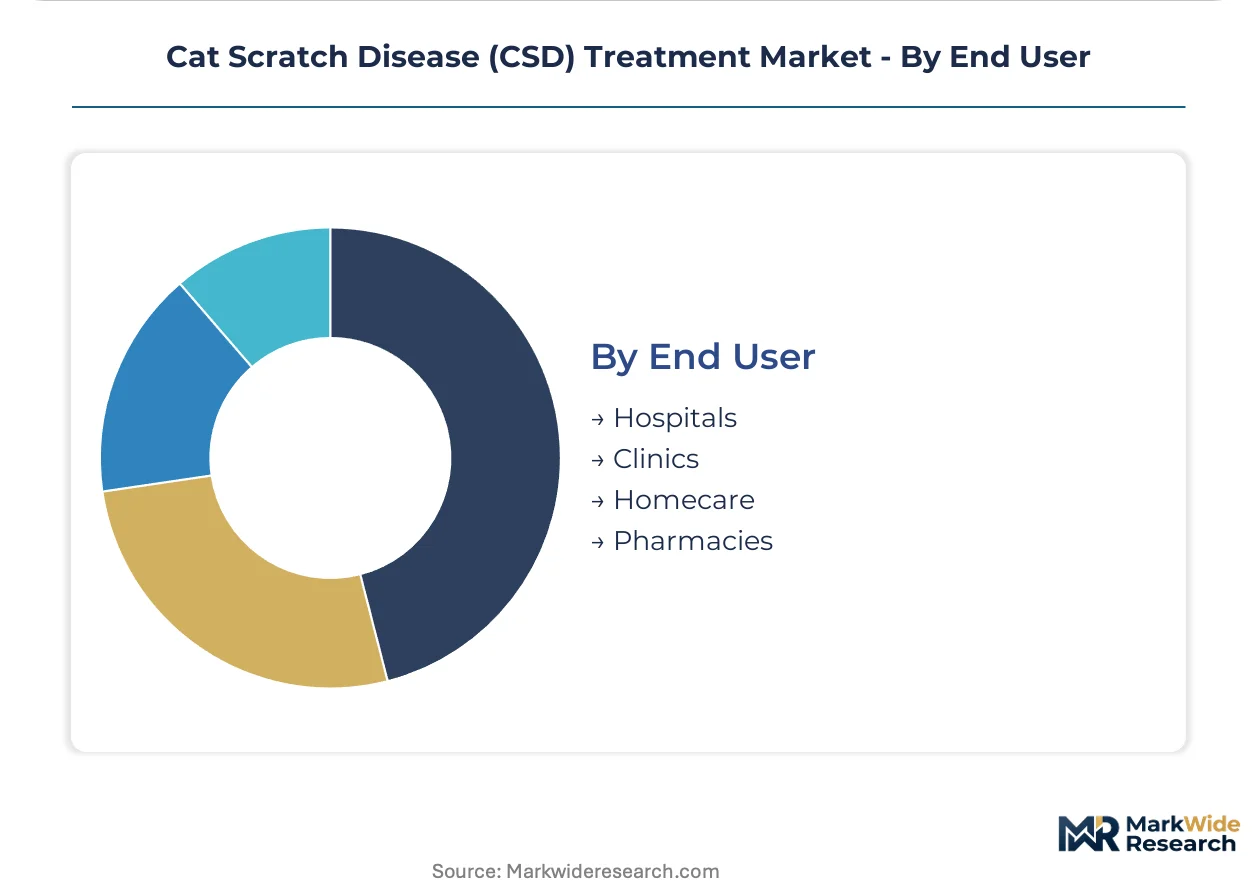
End User:
Customer type segmentation maps to acuity gradients, with hospitals managing complex cases and homecare extending monitoring beyond acute intervention.
- Hospitals:Inpatient management of disseminated CSD with IV antibiotic protocols and specialist consultation. CDC surveillance protocols indirectly steer diagnostic testing volumes and treatment initiation criteria.
- Clinics:Outpatient diagnosis and oral antibiotic prescribing for uncomplicated presentations. Large multi-site pediatric practices consolidate testing decisions under infectious disease stewardship programs.
- Homecare:Post-treatment monitoring and recurrence tracking create annuity revenue streams. Neuro-ophthalmic surveillance extends care duration beyond initial prescription fulfillment.
- Pharmacies:Retail dispensing of oral antibiotics and supportive therapies. Generic azithromycin supply chains from Indian and Chinese API manufacturers support cost-efficient distribution.
Clinics process the highest prescription volume while hospitals generate the most revenue per treated patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes azithromycin and rifampin combinations at per-capita rates exceeding European benchmarks by a factor of three, driven by suburban cat ownership density and pediatric infectious disease protocol penetration. Diagnostic confirmation delays of 5-7 days compress prescription capture in outpatient settings, while point-of-care PCR adoption in Texas and Florida multi-site practices accelerates treatment initiation timelines.
United States
Pediatric infectious disease specialists at academic medical centers in Texas and Florida drive disproportionate azithromycin prescription volume. The FDA's Qualified Infectious Disease Product designation accelerates novel formulation approvals through priority review vouchers. Hospital formulary committees in tertiary care centers pre-approve QIDP-designated agents for empirical Bartonella therapy protocols.
Germany
EMA antibacterial guidance on intracellular pathogen trial endpoints shapes German market access timelines for novel Bartonella therapeutics. The country's national pharmaceutical regulator enforces stringent post-market surveillance for pediatric antibiotic formulations. Bavarian hospital networks concentrate specialist-directed therapy for neuroretinitis and hepatosplenic complications.
France
ANSM oversight of anti-infective prescribing patterns steers empirical therapy decisions in Parisian tertiary care centers. The country's national pharmaceutical regulator monitors Bartonella resistance surveillance through centralized laboratory networks. Île-de-France pediatric clinics generate concentrated demand for oral azithromycin formulations.
Japan
PMDA streamlined antibacterial pathways reduce review timelines for intracellular penetration-optimized formulations. METI industrial policy incentives support domestic API manufacturing capacity for critical antibiotics. Kanto region hospital networks pilot extended-release azithromycin matrix technologies for reduced dosing frequency regimens.
India
CDSCO accelerated approval pathways for qualified infectious disease products attract formulation sponsors seeking earlier market entry. The country's national pharmaceutical regulator harmonizes with WHO prequalification standards for export-oriented production. Gujarat and Maharashtra chemical manufacturing zones concentrate azithromycin active pharmaceutical ingredient supply.
Cat Scratch Disease (CSD) Treatment Market Competitive Environment
Capability concentration sits with research-intensive pharmaceutical developers possessing intracellular pharmacokinetic expertise; scale advantage sits with generic manufacturers commanding oral solid dose production volume. The market structure tiers across three distinct archetypes: multinational innovators with QIDP-designated pipelines, mid-cap specialists in pediatric formulation development, and volume-driven generic suppliers. Consolidation pressure intensifies as hospital formulary committees narrow empirical therapy protocols toward narrow-spectrum agents. Strategic moves center on M&A targeting intracellular delivery technology assets and manufacturing capacity expansion for extended-release matrix platforms.
Within the multinational innovator tier, Pfizer Inc. and Sanofi S.A. anchor competitive positioning through manufacturing scale and established anti-infective portfolios respectively. Teva Pharmaceutical Industries Ltd. occupies a position exemplifying cost-efficient generic supply chain execution for clinic network procurement. These three entities represent the dominant competitive archetypes shaping margin pool distribution across oral antibiotic and supportive therapy segments.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca plc |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Novartis International AG |
| Others |
Value Chain & Pricing Dynamics
Azithromycin API production concentration in Gujarat and Maharashtra chemical manufacturing zones exposes formulation sponsors to tariff volatility and logistics disruption, compressing margin structures across oral antibiotic tiers while forcing inventory positioning strategies that favor long-term offtake contracts over spot procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between Indian API manufacturers and US formulation sponsors, insulating volume buyers from spot market volatility while generic azithromycin suppliers compete on cost-efficient supply chain execution. Price differentiation stems from pediatric formulation certification tiers and cold-chain logistics bundling for immunoglobulin segments. Pricing pressure intensifies in standard oral antibiotic tiers due to Teva Pharmaceutical Industries Ltd. and competing generic manufacturers' scale advantages. Primary care clinic networks exhibit highest price sensitivity, while tertiary care hospital formulary committees prioritize QIDP-designated agent access over unit cost.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk assessment for azithromycin active pharmaceutical ingredient flows, with secondary concentration in Chinese chemical manufacturing zones creating alternative sourcing dependencies. Raw material inputs draw from fermentation-derived erythromycin precursors, specialized coating polymers for extended-release matrices, and sterile packaging components for parenteral formulations. Single-source vulnerability in intracellular pharmacokinetic formulation expertise constrains novel Bartonella therapeutic development. Distribution runs through hospital procurement consortia, clinic network group purchasing organizations, and retail pharmacy chains with generic substitution protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intracellular pharmacokinetic expertise scarcity constrains novel Bartonella therapeutic advancement, creating asymmetric returns for sponsors possessing endothelial penetration optimization capabilities versus commodity generic manufacturers competing on oral solid dose production scale.
For Market Incumbents: Insulate hospital formulary positioning by securing QIDP designations for narrow-spectrum antibacterial pipelines and deepening backward integration into extended-release matrix platform manufacturing. Pfizer Inc. and Sanofi S.A. must preempt emerging entrant intracellular delivery technology acquisitions before priority review voucher eligibility windows narrow. Capacity addition in US domestic oral solid dose production leverages IRA tax credits against Indian API supply disruption exposure. For New Entrants and Emerging Players: Point-of-care PCR diagnostics in Texas and Florida multi-site pediatric practices represent the most penetrable entry point, with post-treatment monitoring services for neuro-ophthalmic surveillance creating annuity revenue attachment opportunities. European EMA antibacterial guidance acceleration for intracellular pathogen trial endpoints offers regulatory arbitrage for sponsors with existing pediatric safety databases. Go-to-market positioning should target infectious disease stewardship program consolidation in large US clinic systems. For Investors and Strategic Acquirers: The market sits at a formulation-innovation phase that favors mid-cap specialists with intracellular delivery technology assets and established pediatric regulatory pathways. Long-term viability over the next decade hinges on Bartonella resistance surveillance infrastructure deployment and narrow-spectrum antibacterial prioritization alignment. Acquisition target archetypes include extended-release matrix platform developers and point-of-care molecular diagnostic firms with CLIA-waived PCR capabilities. The signal to watch is FDA QIDP designation grant velocity as an indicator of regulatory incentive durability.| Strategic Initiative | Industry Significance |
|---|---|
| QIDP Designation Pursuit | Priority review voucher eligibility accelerates hospital formulary pre-approval for empirical Bartonella protocols. |
| Extended-Release Matrix Platform Development | Twice-weekly azithromycin dosing regimens compress adherence failure rates in pediatric populations. |
| Point-of-Care PCR Diagnostic Launch | Clinic-level Bartonella detection collapses confirmation timelines from serology-based 5-7 day delays. |
| US Domestic Manufacturing Scale-Up | IRA tax credits for critical antibiotics reduce cost structures against Indian API supply concentration. |
| Post-Treatment Monitoring Service Integration | Recurrence tracking and neuro-ophthalmic surveillance create annuity revenue beyond prescription fulfillment. |
Study Parameters
Desk research of FDA QIDP designation databases, EMA antibacterial guidance documents, and ClinicalTrials.gov Bartonella therapeutic entries preceded structured interviews with pediatric infectious disease specialists, hospital formulary directors, and generic pharmaceutical procurement managers. Secondary validation drew from CDC cat-associated disease surveillance protocols, Indian CDSCO accelerated approval pathway filings, and hospital procurement database extracts. Bottom-up prescription volume modeling triangulated against top-down market size estimates from API production capacity analysis.
Assumptions regarding azithromycin resistance pattern stability, pediatric formulary protocol persistence, and intracellular pharmacokinetic formulation advancement velocity were held fixed across baseline scenarios while regulatory incentive durability and diagnostic technology adoption curves were stress-tested. Segmentation dimensions modeled included product type, therapy area, delivery mode, and end user category across the projection horizon. CAGRs derived from epidemiological incident case projections, treatment initiation rate assumptions, and average revenue per patient episode calculations incorporating reimbursement pathway evolution.
Practitioners should monitor Bartonella susceptibility surveillance reporting fragmentation, FDA narrow-spectrum antibacterial prioritization policy shifts, and Indian API manufacturing zone geopolitical stability for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Marfan Syndrome Treatment Market