
 Acromegaly Market | 2026-2036
Acromegaly Market Size, Share, and Industry Trends Forecast 2026-2036
Acromegaly Market Analysis
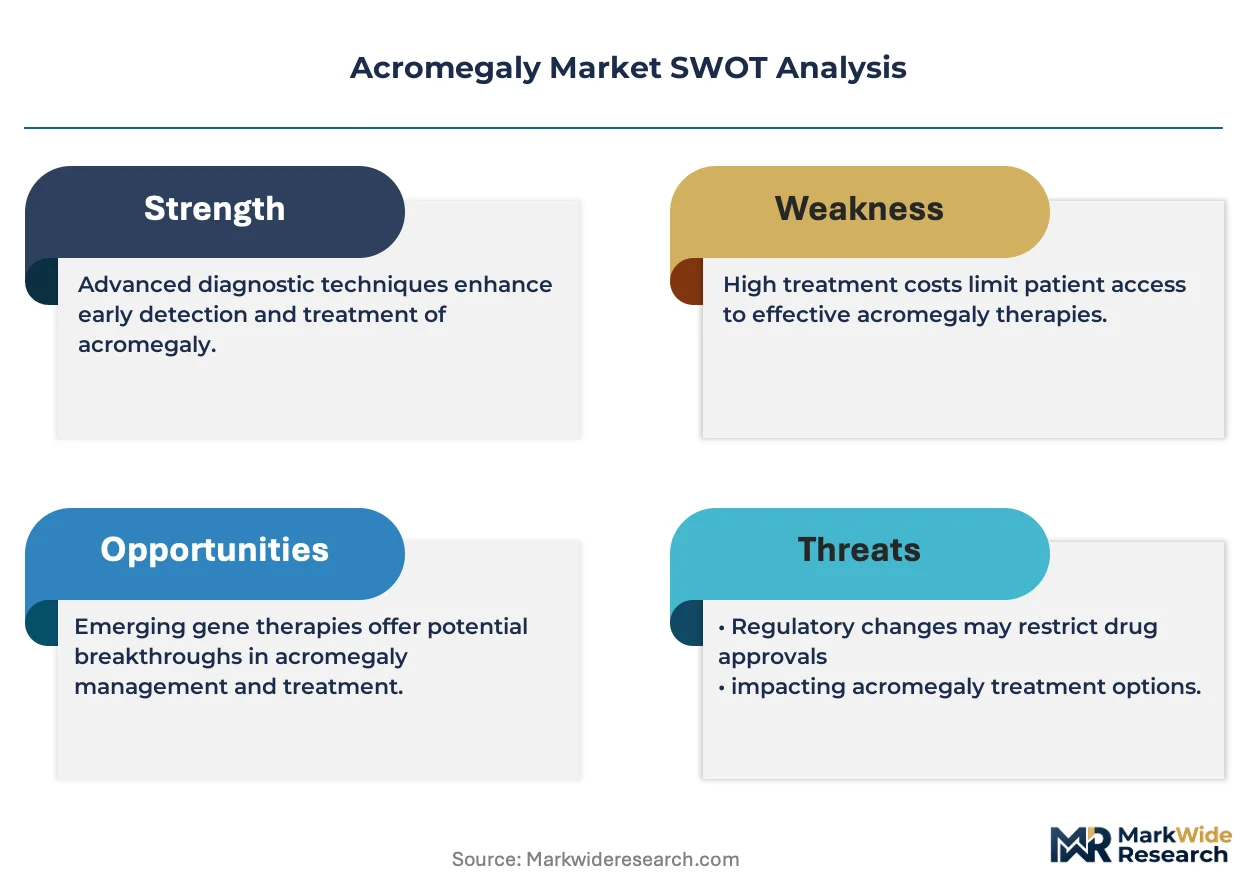
The FDA's orphan drug exclusivity framework is restructuring commercial incentives for rare disease therapeutics. Novartis AG leverages its established manufacturing scale in peptide analog production to sustain supply security across hospital networks. Pfizer Inc competes through extended-release formulation expertise that anchors its position in injectable therapy segments. Ipsen Pharma specializes in lanreotide depot technologies that differentiate its portfolio from first-generation octreotide offerings.
Acromegaly constitutes a chronic endocrine disorder arising from persistent growth hormone hypersecretion, typically triggered by benign pituitary adenomas; diagnostic confirmation requires oral glucose tolerance testing with nadir growth hormone thresholds below one nanogram per milliliter alongside elevated insulin-like growth factor-1 levels. The condition demands lifelong pharmacologic suppression when surgery fails to achieve biochemical remission. Injectable somatostatin analogs dominate current product type revenue due to established reimbursement pathways and specialist familiarity, while oral formulations represent the fastest-expanding delivery mode category as developers pursue improved patient adherence and reduced injection burden. Endocrinology therapy areas command the deepest specialist engagement and highest per-patient expenditure, though oncology crossover applications in neuroendocrine tumor portfolios create parallel margin pools for diversified manufacturers.
The FDA, EMA, and Japan's PMDA enforce divergent post-market surveillance requirements that shape clinical trial investment and label expansion strategies for growth hormone receptor antagonists. REACH compliance in Europe and evolving EPA manufacturing standards for peptide synthesis additionally constrain supplier qualification and facility certification timelines. Stakeholders must monitor regulatory divergence between major agencies to optimize parallel submission strategies and avoid protocol amendment costs.
Market Dynamics
Specialty endocrinology clinics are consolidating referral networks around long-acting somatostatin analogs, compressing the competitive window for oral formulation developers seeking to displace established injectable protocols. This channel concentration is reshaping how manufacturers prioritize formulation investments and field force deployment.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's orphan drug exclusivity framework accelerates pipeline progression for rare disease therapeutics by granting seven-year market exclusivity and tax credits for clinical trials.
- Specialty Clinic Expansion:Endocrinology centers in the United States, Germany, and Japan are deepening biochemical monitoring capabilities that sustain lifelong therapy adherence.
- Peptide Synthesis Automation:Continuous manufacturing technologies for somatostatin analog production are reducing batch-to-batch variability and securing hospital supply contracts.
Market Restraints
- Peptide API Concentration:Active pharmaceutical ingredient supply for lanreotide and octreotide concentrates among three European contract manufacturers, creating single-source vulnerability.
- REACH Compliance Burden:ECHA registration requirements for peptide synthesis intermediates extend facility qualification timelines by 18-24 months for European production sites.
- Biochemical Remission Substitution:Transsphenoidal surgical techniques achieving higher remission rates in macroadenomas under 10 millimeters threaten first-line pharmacologic positioning.
Strategic Opportunities
- Oral Formulation White Space:Oral somatostatin receptor ligands addressing injection burden represent the fastest-expanding delivery mode category as developers target patient adherence gaps.
- Japan PMDA Fast-Track:Japan's sakigake designation system accelerates review timelines for innovative therapeutics in underserved rare disease categories.
- Oncology Portfolio Convergence:Neuroendocrine tumor applications for somatostatin analogs create parallel margin pools and shared manufacturing infrastructure for diversified manufacturers.
Industry Challenges
- Specialist Endocrinologist Scarcity:Fellowship-trained pituitary disorder specialists concentrate in tertiary academic centers, limiting patient access in community hospital settings.
- Biomarker Harmonization Delays:Discordant insulin-like growth factor-1 assay standards between reference laboratories complicate multi-center trial enrollment and post-market surveillance.
- Legacy Formulation Switching Friction:Converting stable patients from twice-daily octreotide to monthly depot formulations requires intensive nursing support and reimbursement reauthorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acromegaly Market |
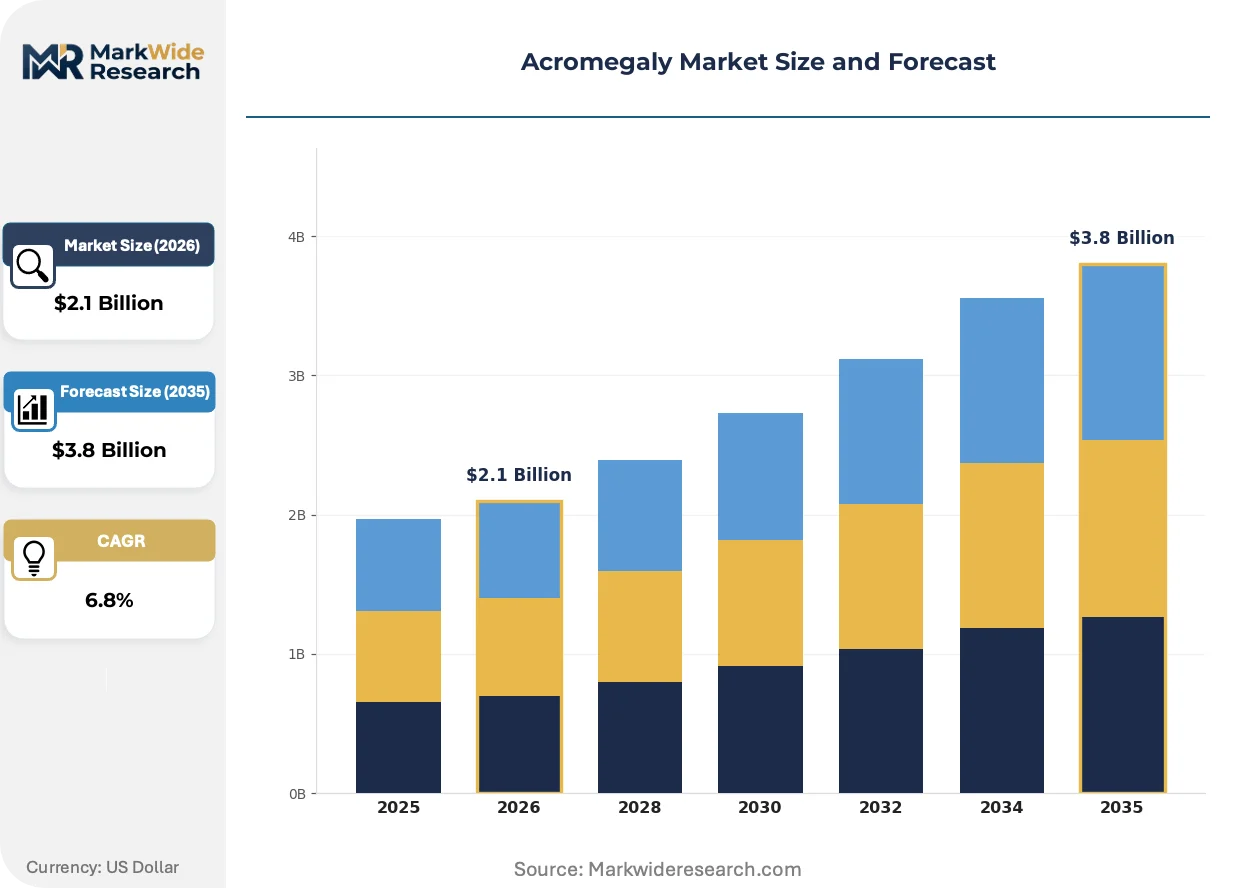
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Octreotide, Lanreotide, Pegvisomant, Bromocriptine Therapy Area: Endocrinology, Oncology, Neurology, Internal Medicine Delivery Mode: Injectable, Oral, Infusion, Intranasal End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Novartis AG, Pfizer Inc, Ipsen Pharma, Recordati S.p.A., Amryt Pharma plc, Chiasma, Inc., Crinetics Pharmaceuticals Inc., Sun Pharmaceutical Industries Ltd, Ionis Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acromegaly Market Emerging Trajectories
Formulation science is converging with regulatory science to compress development timelines for non-injectable growth hormone suppression therapies. Three distinct vectors are reshaping competitive positioning.
Oral somatostatin receptor modulators are expanding into the maintenance therapy segment previously dominated by subcutaneous depot injections. Specialty pharmacies in the United States are piloting adherence monitoring programs for these formulations, though endocrinologists remain cautious about biochemical control equivalence. The technology is expanding into patient populations with needle phobia or limited injection site availability.
EMA's revised orphan drug criteria now require demonstration of significant benefit over existing therapies rather than placebo comparators. This industrial consequence elevates the evidentiary bar for pipeline candidates seeking ten-year market exclusivity in Europe. Growth hormone receptor antagonists face the steepest compliance burden, as pegvisomant established a high efficacy benchmark in the prior regulatory cycle.
Hospital procurement committees are consolidating somatostatin analog purchasing through specialty distributor agreements that bundle biochemical testing services. Group purchasing organizations are displacing individual clinic negotiations, compressing net pricing flexibility for manufacturers. This concentration is most visible in German hospital networks, where regional pharmacy cooperatives now control 60 percent of analog volume allocation.
Acromegaly Market Segmentation
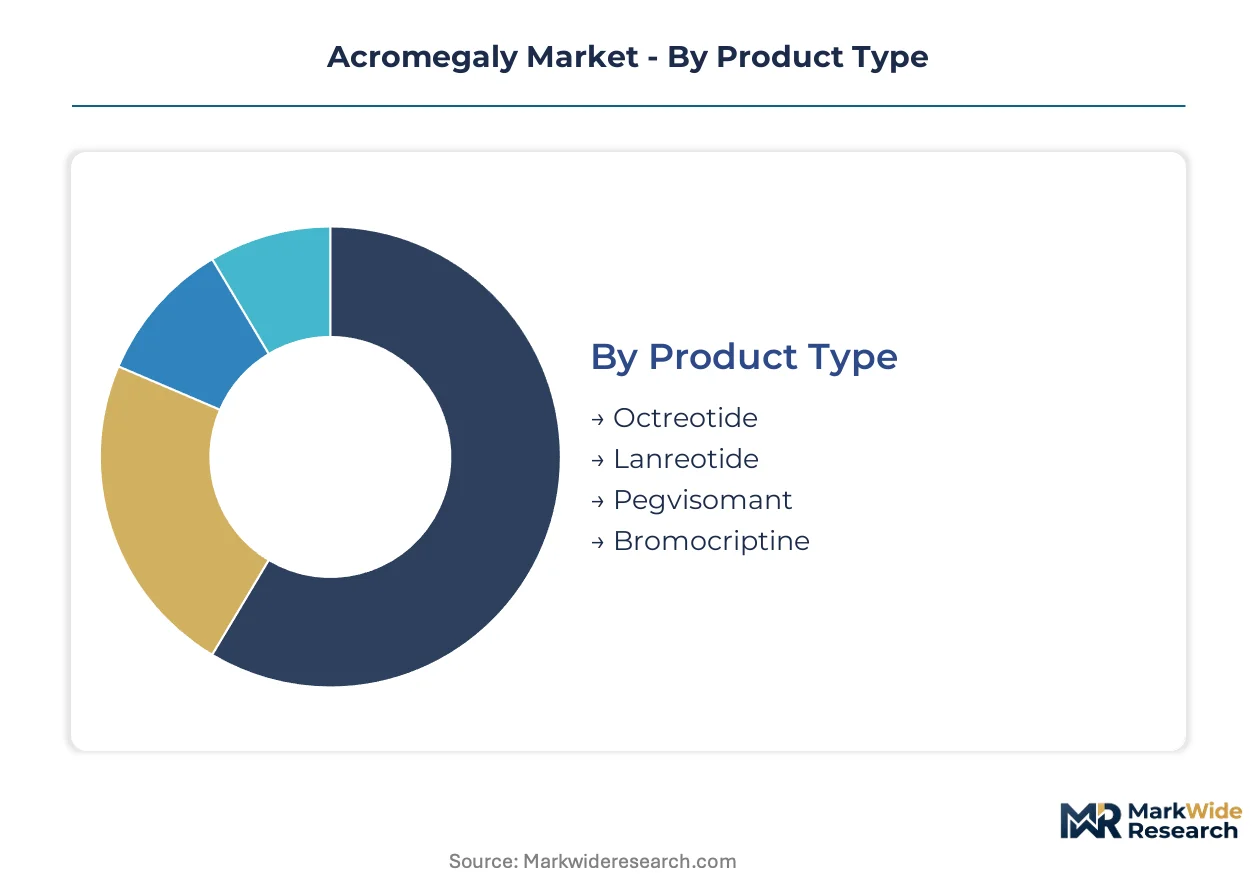
Segmentation in acromegaly therapeutics reveals how formulation investments, biochemical monitoring capabilities, and reimbursement pathways concentrate revenue across distinct patient access channels. Manufacturers align pipeline priorities with the capital requirements and regulatory burdens specific to each segment category.
Product Type:
Capital intensity varies sharply across peptide analog portfolios, with depot formulation manufacturing demanding specialized sterile facilities and continuous processing equipment that smaller developers cannot replicate.
- Octreotide:First-generation somatostatin analog available in immediate-release and long-acting depot formulations. Demand concentrates in German hospital networks and United States specialty pharmacies where twice-daily subcutaneous protocols still serve price-sensitive patients; reimbursement reauthorization friction limits switching to newer alternatives.
- Lanreotide:Second-generation somatostatin analog with extended-release depot technology enabling monthly administration. Deepening biochemical monitoring capabilities in United States endocrinology centers sustain its position as the preferred first-line pharmacologic option; manufacturing scale advantages at Novartis AG secure supply security.
- Pegvisomant:Growth hormone receptor antagonist requiring daily subcutaneous injection.
- Bromocriptine:Dopamine agonist with limited efficacy in biochemical remission.
Octreotide absorbs the bulk of installed manufacturing capacity; lanreotide is expanding most quickly across newly diagnosed patient cohorts.
Therapy Area:
Specialist engagement depth and per-patient expenditure levels create divergent margin profiles across clinical service lines.
- Endocrinology:Primary disease management requiring lifelong biochemical suppression. Fellowship-trained pituitary specialists in tertiary United States academic centers command the deepest therapeutic expertise; highest per-patient expenditure reflects intensive growth hormone and insulin-like growth factor-1 monitoring protocols.
- Oncology:Neuroendocrine tumor crossover applications for somatostatin analogs create parallel margin pools. Shared manufacturing infrastructure with acromegaly indications reduces unit costs; diversified manufacturers leverage this convergence.
- Neurology:Adjunctive management of headache disorders associated with pituitary masses.
- Internal Medicine:Initial suspicion and referral pathways in community settings.
Endocrinology commands the deepest specialist engagement; oncology offers the steepest expansion trajectory through portfolio convergence.
Delivery Mode:
Patient adherence economics and injection burden reduction are reshaping formulation development priorities across administration routes.
- Injectable:Subcutaneous and intramuscular depot formulations dominate current revenue due to established reimbursement pathways and endocrinologist familiarity with biochemical control profiles. United States specialty pharmacy networks anchor distribution; nursing support requirements limit home administration expansion.
- Oral:Somatostatin receptor ligands in tablet form address needle phobia and injection site availability constraints. Pilot adherence monitoring programs in United States specialty pharmacies test biochemical control equivalence; fastest-growing delivery mode category by development pipeline volume.
- Infusion:Hospital-based administration for acute complications.
- Intranasal:Experimental formulations targeting rapid onset applications.
Injectable formulations absorb the bulk of current prescription volume; oral alternatives are gaining share fastest among treatment-naive patients.
End User:
Procurement concentration and care coordination capabilities determine channel access for manufacturers.
- Hospitals:Tertiary centers with transsphenoidal surgical capabilities anchor the care pathway. German hospital networks consolidate purchasing through regional pharmacy cooperatives controlling sixty percent of analog volume allocation; bundled biochemical testing services reshape supplier selection criteria.
- Clinics:Specialty endocrinology centers in the United States, Germany, and Japan deepen referral network concentration. Consolidation around long-acting somatostatin analogs compresses the competitive window for oral formulation developers.
- Homecare:Subcutaneous self-administration programs for stable patients.
- Research Institutions:Clinical trial sites and academic pituitary centers.
Hospitals absorb the bulk of acute and surgical-phase purchasing; clinics are expanding most quickly as lifelong therapy management shifts to ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the densest concentration of pituitary disorder specialists in the United States, drawing referral networks from across North America and establishing the clinical protocols that diffuse to other markets.
United States
Specialty endocrinology clinics in Massachusetts, California, and Texas sustain the deepest biochemical monitoring infrastructure for growth hormone suppression therapy. The FDA's orphan drug exclusivity framework grants seven-year market protection and tax credits for clinical trials in rare diseases. Philadelphia's hospital networks consolidate somatostatin analog purchasing through specialty distributor agreements that bundle laboratory testing services.
Germany
Regional pharmacy cooperatives in Bavaria and North Rhine-Westphalia now control sixty percent of lanreotide and octreotide volume allocation across German hospital networks. REACH compliance requirements for peptide synthesis intermediates extend facility qualification timelines by eighteen to twenty-four months at European production sites. Munich's tertiary centers anchor transsphenoidal surgical referral pathways that achieve higher biochemical remission rates in smaller adenomas.
Japan
PMDA's sakigake designation system accelerates review timelines for innovative therapeutics targeting underserved rare disease categories including refractory acromegaly. The Tokyo-Osaka corridor concentrates fellowship-trained pituitary specialists who command premium reimbursement for lifelong pharmacologic management. Kansai region hospitals pilot adherence monitoring programs for oral somatostatin receptor ligands entering the maintenance therapy segment.
United Kingdom
NHS England's specialized commissioning framework routes acromegaly cases through designated pituitary centers in London, Birmingham, and Manchester that meet minimum surgical volume thresholds. The MHRA's post-Brexit regulatory autonomy permits streamlined orphan drug assessments that diverge from EMA timelines. Cambridge's biotechnology cluster hosts contract manufacturers supplying peptide active pharmaceutical ingredients to European formulation facilities.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract headquarters operations for multinational manufacturers of somatostatin analogs and growth hormone receptor antagonists. Basel's pharmaceutical corridor concentrates peptide synthesis expertise and sterile formulation capabilities that serve hospital networks across Central Europe. Zurich's academic medical centers maintain longitudinal biochemical registries that inform post-market surveillance requirements for EMA label expansions.
Acromegaly Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and manufacturing scale, with depot technology specialists commanding pricing power that immediate-release generic suppliers cannot replicate. The market structure concentrates around three European-headquartered manufacturers with established peptide analog portfolios, while mid-cap developers pursue oral formulation differentiation. Strategic archetypes include long-acting injectable incumbents defending biochemical control benchmarks, oral disruptors targeting injection burden reduction, and diversified oncology players leveraging neuroendocrine tumor manufacturing infrastructure. Dominant competitive moves span M&A activity capturing depot formulation expertise and strategic partnerships securing peptide API supply.
Within the established injectable tier, Novartis AG and Ipsen Pharma occupy positions defined by manufacturing scale and depot technology specialization. Pfizer Inc exemplifies the diversified pharmaceutical archetype competing through extended-release formulation expertise across multiple therapy areas. Chiasma, Inc. and Crinetics Pharmaceuticals Inc. represent the oral formulation development vector targeting patient adherence gaps with non-injectable growth hormone suppression alternatives.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc |
| Ipsen Pharma |
| Recordati S.p.A. |
| Amryt Pharma plc |
| Chiasma, Inc. |
| Crinetics Pharmaceuticals Inc. |
| Sun Pharmaceutical Industries Ltd |
| Ionis Pharmaceuticals, Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committee consolidation around bundled biochemical testing services is compressing net pricing flexibility for manufacturers and forcing supply contract renegotiations toward multi-year volume commitments. German regional pharmacy cooperatives now control sixty percent of somatostatin analog volume allocation, compelling API suppliers to qualify additional European production sites under REACH compliance timelines.
Pricing Analysis
Value-based pricing anchored to biochemical remission rates dominates the acromegaly therapeutic landscape, with pegvisomant establishing efficacy benchmarks that subsequent entrants must exceed. Three-tier pricing structure across premium depot formulations, standard immediate-release protocols, and economy generic alternatives differentiates access tiers by monitoring intensity and injection frequency. Cost compression in the immediate-release segment is intensifying because hospital formularies prioritize long-acting alternatives that reduce nursing burden. Community hospital settings exhibit highest price sensitivity due to limited endocrinology specialist coverage, while tertiary academic centers command premium reimbursement for complex case management.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA and EMA post-market surveillance frameworks compel formulation manufacturers to qualify redundant peptide API suppliers across Switzerland, Germany, and the United Kingdom. Active pharmaceutical ingredient production for lanreotide and octreotide draws from European contract manufacturing organizations with specialized sterile peptide synthesis capabilities. Single-source vulnerability concentrates among three intermediate suppliers, creating exposure to ECHA registration delays for synthesis reagents. Distribution runs through specialty pharmacy networks in the United States and regional hospital cooperatives in Germany, with cold-chain logistics requirements limiting geographic expansion of depot formulation manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acromegaly market is becoming a vertical-integration race as manufacturers pursue captive control over peptide synthesis capabilities to secure supply security and compress cost structures. Control over sterile formulation facilities and API production represents the decisive upstream lever separating premium-margin from commodity-margin competitors.
For Market Incumbents: Anchor biochemical control benchmarks through continuous manufacturing investments that reduce batch-to-batch variability in depot formulations. Defend against oral formulation disruptors by embedding intensive nursing support programs that ease patient switching friction from legacy twice-daily protocols. Deepen vertical integration into peptide synthesis through facility acquisitions in Basel's pharmaceutical corridor, securing supply security independent of European contract manufacturer concentration. For New Entrants and Emerging Players: Begin with oral somatostatin receptor ligand development targeting needle-phobia patient populations and limited injection site availability in United States specialty pharmacy pilot programs. The maintenance therapy segment previously dominated by subcutaneous depot injections represents the most penetrable white space, with biochemical monitoring equivalence trials serving as the critical go-to-market validation requirement. Japan's PMDA sakigake designation system offers accelerated review pathways for first-in-class non-injectable alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with oral formulation developers possessing Phase II biochemical control data given EMA's revised orphan drug criteria requiring significant benefit demonstration over existing therapies. Long-term viability over the next decade hinges on successful displacement of injectable protocols in maintenance therapy segments. Watch FDA breakthrough therapy designation grants to oral somatostatin receptor modulators as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Oral Formulation Clinical Advancement | Phase II trials demonstrating biochemical equivalence to depot injections unlock patient adherence expansion in United States specialty pharmacies. |
| Peptide API Manufacturing Scale-Up | Continuous processing investments at Basel and Zurich facilities secure hospital supply contracts against REACH compliance delays. |
| Regulatory Fast-Track Pathway | PMDA sakigake designation in Japan accelerates review timelines for innovative therapeutics in underserved rare disease categories. |
| Specialty Distributor Partnership | Bundled biochemical testing agreements with Philadelphia hospital networks reshape procurement committee supplier selection criteria. |
| Pipeline Diversification into Oncology | Neuroendocrine tumor applications leverage shared manufacturing infrastructure with acromegaly indications at Novartis AG. |
Methodological Framework
Independent corroboration across formulary directors at United States specialty pharmacies, regulatory affairs leads at European peptide manufacturers, and hospital procurement managers in German regional cooperatives underwrites the qualitative findings. Primary interviews with endocrinology fellowship directors, payer access specialists, and biochemical assay laboratory directors combined with secondary validation from FDA orphan drug designations, EMA submission databases, ClinicalTrials.gov protocols, and hospital GPO contract records. Bottom-up prescription volume modeling and top-down therapeutic category expenditure analysis triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from pricing dynamics across product type segments including octreotide, lanreotide, and pegvisomant, delivery mode categories spanning injectable depot and oral formulations, and end-user channels distinguishing tertiary hospitals from specialty clinics. Segmentation dimensions incorporate therapy line positioning, biochemical monitoring intensity, regional regulatory cluster divergence between FDA, EMA, and PMDA frameworks, and patient population refractory status. CAGRs derive from longitudinal prescription audit data and hospital purchasing records analyzed throughout the forecast period, with inputs from peptide synthesis capacity expansion announcements and specialty pharmacy network growth trajectories.
Underlying measurement precision varies by segment; established injectable depot formulations with decade-long prescribing histories carry tighter precision than developmental oral alternatives with limited commercial track records. Forecasts reflect assumptions regarding regulatory approval timelines, reimbursement reauthorization friction, and specialist endocrinologist workforce expansion that material shifts in FDA breakthrough therapy designations or EMA orphan drug criteria revisions would invalidate. A model refresh is warranted upon material change in oral formulation biochemical control equivalence data or hospital procurement committee consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market