
 Syringes and Cannulas Market | 2026-2036
Syringes and Cannulas Market Size, Share, and Industry Trends Forecast 2026-2036
Syringes and Cannulas Market Intelligence
Chinese polymer converters is recalibrating resin sourcing strategies after medical-grade polypropylene supply tightened across East Asian ports. Becton, Dickinson and Company leverages backward integration into prefillable glass barrel production to protect margin pools in the biologics delivery segment. Terumo Corporation anchors its competitive stance through dominance in thin-wall needle technology for diabetes care applications. Nipro Corporation specializes in ceramic-coated cannula surfaces for reduced friction during vascular access procedures.
Syringes and cannulas constitute precision-engineered fluid transfer devices, typically constructed from medical-grade polypropylene barrels, stainless steel needles with bevel angles between 12 and 30 degrees, and elastomeric plunger seals, designed for sterile administration or extraction of liquids from biological systems. Prefilled syringes command premium positioning due to their integration with biologic drug stability requirements and reduced medication preparation error rates, while safety syringes are displacing conventional designs in institutional settings under sharps injury prevention mandates. Custom cannulas occupy niche margin pools in ophthalmic and cosmetic intervention workflows where tip geometry and lumen diameter require patient-specific configuration.
The FDA enforces current good manufacturing practice requirements under 21 CFR Part 820, compelling syringe producers to maintain validated sterilization processes and device master records for each product family. The European Medicines Agency's Medical Device Regulation mandates unique device identification and enhanced clinical evidence for higher-risk cannula classifications, reshaping market access timelines for non-European suppliers. Stakeholders must monitor evolving polymer biocompatibility standards and homecare reimbursement pathways to anticipate where product portfolios require retooling.
Market Dynamics
The shift from institutional to homecare administration is restructuring syringe demand patterns, with chronic disease patients managing therapies outside hospital settings and manufacturers retooling portfolios for self-injection compatibility.
Growth Catalysts
- Production-Linked Incentive Schemes:India's PLI scheme for medical devices is accelerating domestic disposable syringe capacity expansion and reducing import dependency for basic injection devices.
- Sharps Injury Prevention Mandates:OSHA bloodborne pathogen standards and equivalent workplace safety regulations across industrialized economies are compelling institutional procurement of safety-engineered syringe designs.
- Biologics Drug Stability Requirements:Prefillable glass barrel technology is commanding expanded utilization as protein-based therapeutics demand container systems with extractables and leachables profiles matched to molecular sensitivity.
Market Restraints
- Medical-Grade Polypropylene Supply Tightness:East Asian resin converters face allocation constraints as pharmaceutical-grade polymer output prioritizes vaccine packaging over general-purpose syringe barrels.
- Sterilization Validation Burden:FDA 21 CFR Part 820 quality system requirements impose extended process qualification timelines that compress product launch windows for novel syringe formats.
- Glass Barrel Cost Premium:Borosilicate and aluminosilicate glass sourcing for prefillable systems carries 3-4x material cost multiples versus polymer alternatives, constraining price-competitive positioning in volume markets.
Strategic Opportunities
- Homecare Reimbursement Pathway Expansion:CMS and comparable national health technology assessment bodies are expanding coverage codes for self-administered injection therapies, opening device procurement budgets outside institutional purchasing.
- Ceramic-Coated Cannula Surfaces:Reduced-friction vascular access devices are penetrating interventional cardiology workflows where insertion force minimization correlates with procedural success metrics.
- Thin-Wall Needle Technology Convergence:Diabetes care applications are integrating ultra-fine gauge designs with connected dose-capture electronics for integrated disease management platforms.
Industry Challenges
- Process Validation Engineering Talent Scarcity:Sterility assurance and aseptic processing expertise pools concentrate among legacy medical device hubs, constraining geographic diversification of manufacturing footprints.
- Unique Device Identification Implementation:EMA MDR and FDA UDI mandates require serialized labeling infrastructure investments that disproportionately burden mid-scale syringe producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringes and Cannulas Market |
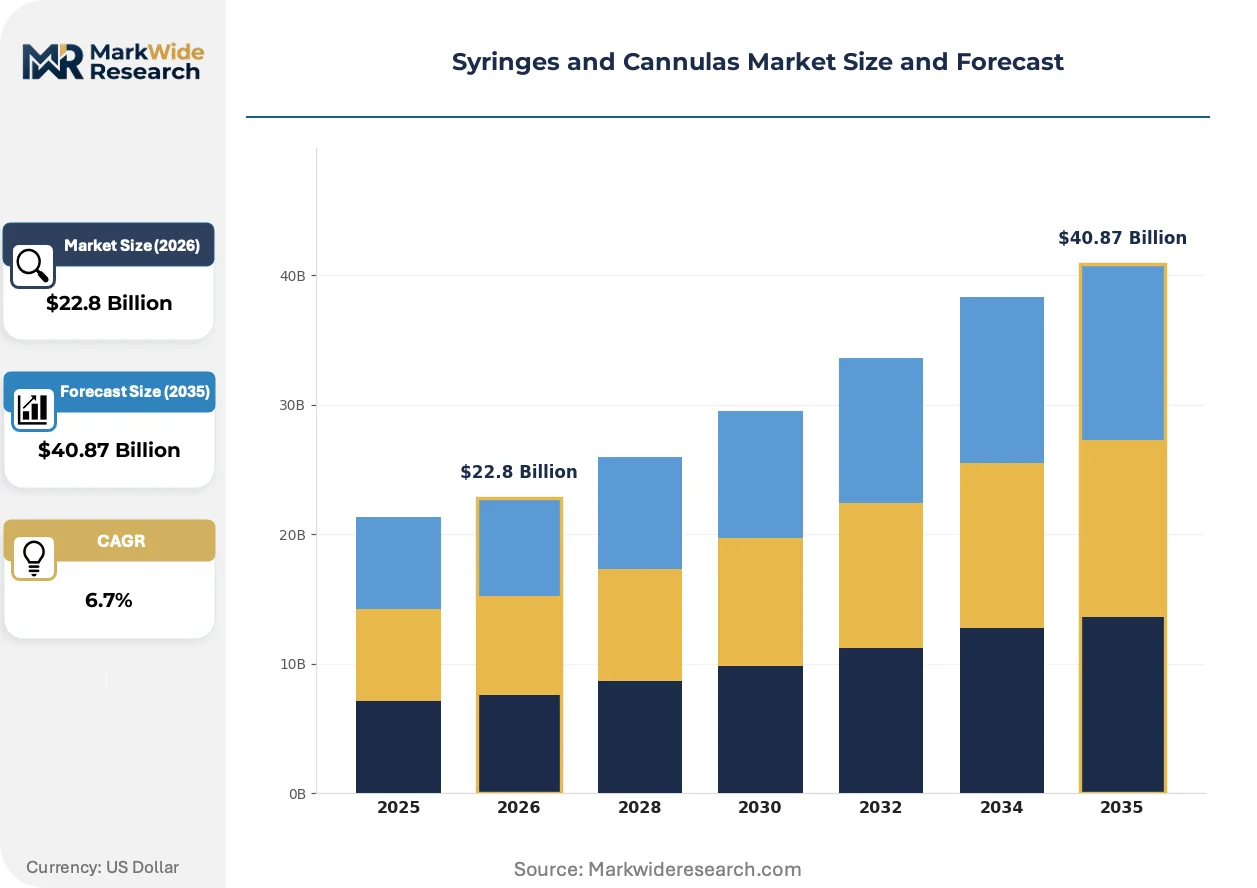
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Safety Syringes, Custom Cannulas, Prefilled Syringes Application: Vaccination, Drug Delivery, Blood Sampling, Anesthesia End User: Hospitals, Clinics, Homecare, Research Laboratories Material: Glass, Plastic, Stainless Steel, Rubber |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, Nipro Corporation, Gerresheimer AG, Schott AG, Cardinal Health, Inc., B. Braun SE, Hindustan Syringes & Medical Devices Ltd., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringes and Cannulas Market Strategic Shifts & Innovations
Connected injection devices and advanced surface engineering are redefining competitive differentiation, with functionality expansion outpacing commoditization pressures in standard disposable segments.
Connected autoinjector platforms integrating dose-capture sensors and wireless transmission modules are rewriting patient adherence monitoring economics. Pharmaceutical sponsors deploying these systems in Phase III trials capture real-world evidence streams that accelerate regulatory submissions. The data infrastructure requirement is compressing device supplier selection criteria toward electronics integration capabilities.
EMA Medical Device Regulation enforcement is extending clinical evidence requirements to higher-risk cannula classifications. Non-European suppliers face elongated market access timelines as notified body capacity constrains conformity assessment throughput. The regulatory friction is concentrating European procurement among established suppliers with MDR technical documentation libraries.
Hospital purchasing consortiums are consolidating syringe procurement under category management frameworks that unbundle device selection from pharmaceutical sourcing. Integrated delivery networks in North America are negotiating multi-year supply agreements with safety-engineered product mandates. The buying pattern compression is visible most acutely in United States group purchasing organization contract structures.
Syringes and Cannulas Market Segmentation
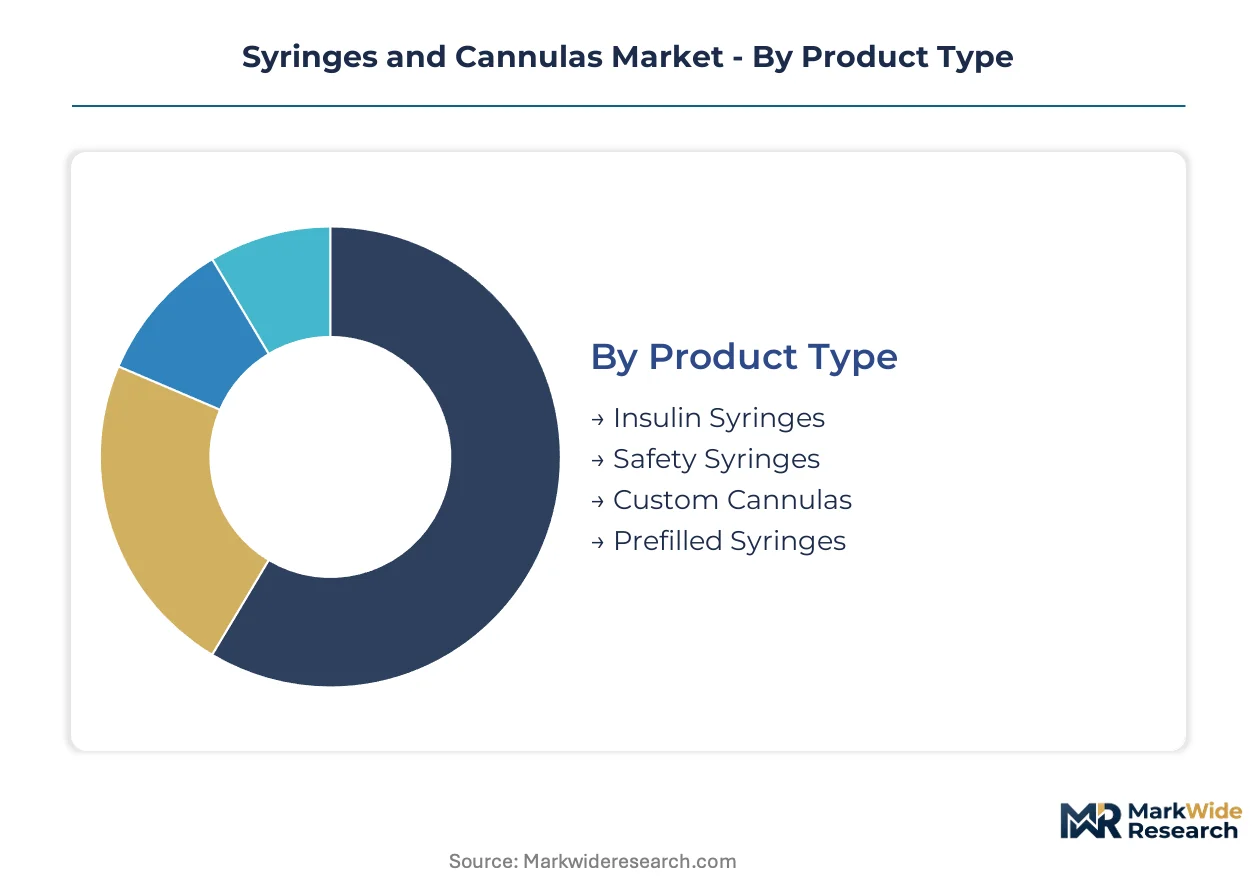
Syringes and cannulas manufacturers must align portfolio depth against therapy-specific requirements. Product configurations range from mass-market disposable formats to patient-matched precision instruments. Material selection and end-use environment dictate margin architecture across each segment category.
Product Type:
The customization-standardization spectrum spans commodity disposables to biologics-integrated delivery systems requiring validated extractables profiles.
- Safety Syringes:Engineered with retractable needles or protective shields that activate post-injection. OSHA bloodborne pathogen standards and equivalent workplace safety mandates across Germany, Japan, and Brazil are institutionalizing procurement of these designs in hospital settings.
- Prefilled Syringes:Borosilicate or aluminosilicate glass barrels preloaded with sterile drug product, sealed with elastomeric plunger-stopper combinations. Demand concentrates in biologics manufacturing corridors of Massachusetts, Switzerland, and Singapore where protein-based therapeutics require container-drug compatibility validation.
- Insulin Syringes:Ultra-fine gauge needles paired with unit-calibrated barrels for subcutaneous hormone administration.
- Custom Cannulas:Patient-specific tip geometries and lumen configurations for ophthalmic, cosmetic, and interventional procedures.
Most installed capacity flows through safety syringes. Expansion is steepest in prefilled syringes.
Application:
Volume concentration versus clinical complexity creates divergent margin profiles across therapeutic use cases.
- Drug Delivery:Encompasses chronic disease self-administration, parenteral nutrition, and biologic therapy protocols. Homecare reimbursement expansion by CMS and comparable national health technology assessment bodies in France and South Korea is redirecting procurement volumes outside institutional purchasing.
- Vaccination:High-volume immunization campaigns utilizing standard disposable syringes with fixed or detachable needles. UNICEF and Gavi procurement specifications dominate demand patterns in low-income country distribution.
- Blood Sampling:Vacuum tube systems and capillary collection devices for diagnostic laboratory workflows.
- Anesthesia:Specialized spinal and epidural needles with pencil-point or cutting bevel designs for neuraxial blockade.
Procurement volume concentrates in drug delivery. Technology investment intensity runs highest in anesthesia.
End User:
Site-of-care migration is restructuring demand toward patient-operated formats with simplified handling protocols.
- Homecare:Self-injection devices for diabetes, multiple sclerosis, rheumatoid arthritis, and growth hormone therapies. Japan's Ministry of Health, Labour and Welfare expanded reimbursement codes for home-administered biologics, accelerating device format adaptation.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidating procurement under category management frameworks with safety-engineered product mandates. United States hospital purchasing consortiums negotiate multi-year supply agreements specifying retractable needle systems.
- Clinics:Outpatient procedure centers requiring rapid turnover disposables for vaccination and minor surgical intervention.
- Research Laboratories:Precision-calibrated glass syringes for analytical chemistry and preclinical dosing studies.
Hospital procurement retains the largest absolute spend. Homecare is gaining share fastest.
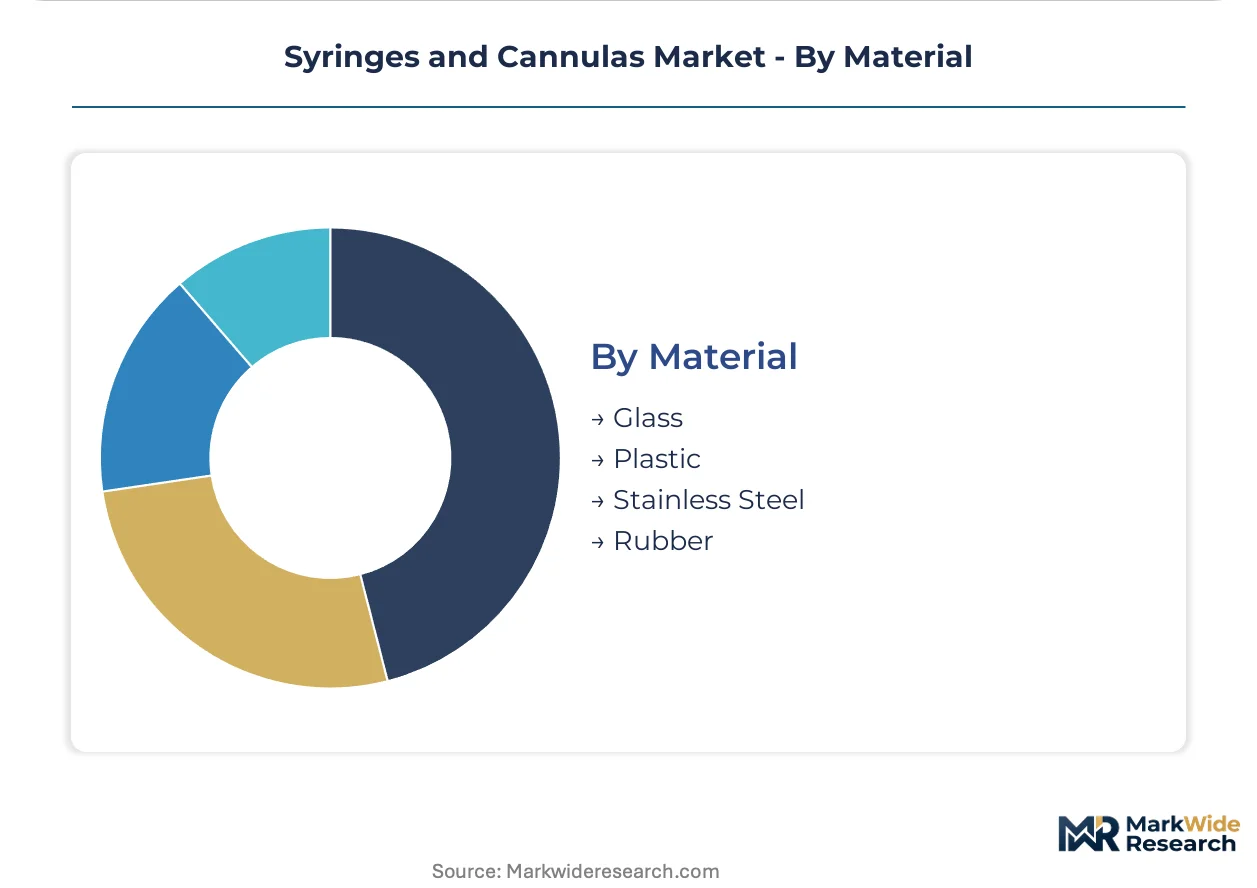
Material:
Performance requirements and cost constraints drive material selection across therapeutic risk tiers.
- Glass:Borosilicate and aluminosilicate formulations for prefillable systems requiring inert contact surfaces and visible drug inspection. European Medicines Agency extractables and leachables guidelines favor glass for sensitive biologics despite 3-4x cost multiples versus polymer alternatives.
- Plastic:Medical-grade polypropylene barrels and polycarbonate hubs forming the dominant cost-optimized segment. East Asian resin converters face allocation constraints as pharmaceutical-grade polymer output prioritizes vaccine packaging.
- Stainless Steel:Cannula substrates and needle tubing with controlled bevel geometry and siliconization for penetration force reduction.
- Rubber:Bromobutyl and chlorobutyl elastomeric plunger seals and tip caps for container closure integrity.
Plastic dominates unit volume. Glass commands the steepest expansion trajectory in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting syringe and cannula manufacturing toward jurisdictions with streamlined quality system compliance and production-linked incentive frameworks. Cost-of-compliance gaps between mature and emerging regulatory environments are accelerating capacity migration across East Asia and South Asia.
United States
Integrated delivery networks and group purchasing organizations are consolidating procurement under category management frameworks with mandatory safety-engineered product specifications. FDA 21 CFR Part 820 quality system requirements impose extended sterilization validation timelines that compress launch windows for novel formats. Massachusetts and North Carolina biologics manufacturing corridors drive prefillable glass barrel demand for protein-based therapeutics.
Germany
Workplace safety regulations and sharps injury prevention mandates are institutionalizing retractable needle procurement across hospital systems. EMA Medical Device Regulation enforcement extends clinical evidence requirements to higher-risk cannula classifications, elongating market access timelines for non-European suppliers. Baden-Württemberg precision engineering clusters concentrate thin-wall needle technology development for diabetes care applications.
India
Domestic production capacity for disposable syringes is expanding under the government's production-linked incentive scheme for medical devices, reducing import dependency for basic injection devices. CDSCO quality system requirements are tightening sterility assurance protocols for export-oriented manufacturers. Gujarat and Maharashtra industrial corridors are attracting medical-grade polymer processing investments from East Asian resin converters.
China
Medical-grade polypropylene supply tightness across East Asian ports is recalibrating resin sourcing strategies for domestic syringe barrel production. NMPA updated good manufacturing practice requirements are accelerating manufacturer investment in process validation infrastructure. Yangtze River Delta polymer converters are reallocating pharmaceutical-grade output toward vaccine packaging over general-purpose syringe applications.
Japan
Home-administered biologics reimbursement expansion by the Ministry of Health, Labour and Welfare is accelerating device format adaptation for self-injection therapies. PMDA quality system requirements maintain stringent sterility assurance standards that protect domestic manufacturer margin pools. Kanto region precision metalworking clusters dominate thin-wall stainless steel needle tubing production for regional diabetes care markets.
Syringes and Cannulas Market Key Industry Players
United States and European producers anchor the premium-tier prefillable and safety-engineered segments; East Asian specialists hold dominant positions in high-volume disposable and thin-wall needle categories. The vendor structure exhibits tiered consolidation, with integrated multinationals controlling biologics-integrated delivery systems and regional specialists capturing commoditized institutional procurement. Three archetypes define competitive positioning: backward-integrated glass barrel manufacturers, polymer-focused disposable specialists, and surface-engineering innovators in vascular access. Dominant competitive moves include capacity expansion under production-linked incentive schemes and technology licensing partnerships for connected dose-capture electronics.
Among integrated multinationals, Becton, Dickinson and Company and Terumo Corporation exemplify the backward-integration archetype into prefillable glass and precision needle technologies. Nipro Corporation occupies a position within the surface-engineering specialist tier. These named entities represent geographic and structural diversity across the competitive landscape without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| Gerresheimer AG |
| Schott AG |
| Cardinal Health, Inc. |
| B. Braun SE |
| Hindustan Syringes & Medical Devices Ltd. |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Sterility assurance engineering talent pools concentrate in Massachusetts and North Carolina biologics corridors, where labor-cost differentials widen pricing-tier spreads between prefillable glass systems and commodity polymer disposables.
Pricing Analysis
Distributor margins absorb the steepest compression in institutional procurement channels, where group purchasing organizations negotiate multi-year safety-syringe contracts. Three-tier pricing structure across premium, standard, and economy levels separates prefillable glass barrels with validated extractables profiles from medical-grade polypropylene alternatives and unbranded disposables. Cost compression in standard disposable tiers stems from East Asian resin allocation constraints favoring vaccine packaging. Homecare self-injection formats exhibit the lowest price sensitivity due to reimbursement code expansion, while vaccination campaigns through UNICEF procurement maintain the highest volume-price elasticity.
Supply Chain Analysis
Reverse-logistics flows for prefillable glass barrel returns and refurbishment anchor closed-loop material recovery in European pharmaceutical manufacturing corridors. Supply concentrates in China for medical-grade polypropylene resin, India for disposable syringe finished goods under PLI scheme incentives, and Germany for precision stainless steel needle tubing. Component dependencies rest on East Asian pharmaceutical-grade polymer output, borosilicate glass from Schott and Gerresheimer captive facilities, and elastomeric bromobutyl seals. Single-source vulnerability concentrates in thin-wall needle technology where Baden-Württemberg precision clusters dominate. Distribution runs through hospital purchasing consortiums in North America, government procurement tenders in low-income countries, and direct-to-biologics-manufacturer contracts for prefillable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syringes and cannulas market functions as a regulatory compounder, where FDA 21 CFR Part 820 quality system mandates and EMA MDR enforcement continuously elevate compliance investment thresholds that reshape competitive economics.
For Market Incumbents: Hedge against polymer cost volatility through backward integration into captive medical-grade polypropylene compounding or long-term offtake agreements with Yangtze River Delta resin converters. Defend margin pools in prefillable glass by accelerating sterilization validation engineering recruitment in legacy medical device hubs before talent scarcity worsens.
For New Entrants and Emerging Players: Begin with ceramic-coated cannula surface technology for interventional cardiology workflows, where reduced-friction performance commands premium positioning and incumbent concentration remains lower than in diabetes needle segments. Target India's expanding domestic production-linked incentive scheme corridors in Gujarat and Maharashtra for disposable syringe capacity buildout with export-oriented CDSCO quality certification.
For Investors and Strategic Acquirers: Pharmaceutical sponsors developing connected autoinjector platforms are the most active acquirer in this space, seeking electronics integration capabilities that compress supplier selection criteria. Mid-scale syringe producers with incomplete unique device identification serialization infrastructure represent distressed acquisition targets. Monitor FDA warning letter issuance rates for sterilization validation deficiencies as an early signal of margin compression among non-compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Barrel Production | Becton Dickinson's captive borosilicate sourcing protects biologics delivery margins from extractables validation bottlenecks. |
| Production-Linked Incentive Capacity Expansion | Hindustan Syringes leverages Gujarat industrial corridor subsidies to displace imported disposables in government immunization programs. |
| Ceramic Surface Coating Technology Licensing | Nipro Corporation's reduced-friction vascular access patents penetrate interventional cardiology procedural success metrics. |
| Connected Dose-Capture Electronics Partnership | Terumo integrates thin-wall needle platforms with wireless adherence monitoring for pharmaceutical sponsor Phase III trials. |
| Unique Device Identification Serialization Infrastructure | EMA MDR compliance investments disproportionately burden mid-scale producers, accelerating consolidation toward notified-body-ready suppliers. |
Research Approach
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterilization validation specialists grounded the qualitative foundation. Secondary validation drew from FDA 510(k) premarket notification databases, EMA medical device registration filings, CMS reimbursement code updates, and UNICEF procurement tender archives. Bottom-up and top-down triangulation cross-checked manufacturer capacity announcements against institutional procurement volume patterns.
Bottom-up modeling aggregated segment-level volume assumptions across product type, application, end user, and material dimensions. Top-down validation anchored aggregate market sizing against pharmaceutical packaging demand correlations and biologics manufacturing capacity expansion in Massachusetts, Switzerland, and Singapore corridors. CAGRs were derived from therapy-specific administration frequency trends and site-of-care migration patterns. Forecast inputs incorporated PLI scheme disbursement timelines and MDR notified body capacity constraints.
Several conditions sit outside the modeled scope, including sudden polymer feedstock price shocks, trade restriction imposition on East Asian resin exports, and accelerated safety-syringe mandate adoption in jurisdictions without existing OSHA-equivalent frameworks. Practitioners should monitor FDA quality system inspection citation rates and EMA MDR technical documentation approval backlogs for early signals of supply constraint propagation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
First Aid Kit Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Global Povidone Iodine Market