
 Surgical Tapes Market | 2026-2036
Surgical Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Tapes Market Outlook
Asset-light contract manufacturing is narrowing the capital barrier for mid-tier firms entering the surgical tapes sector. 3M leverages its captive polymer research to sustain dominance in silicone adhesive platforms. Smith & Nephew anchors its position through specialized wound care distribution across European hospital networks. Mölnlycke Health Care AB differentiates via vertically controlled manufacturing of breathable non-woven tape substrates.
Surgical tapes are pressure-sensitive adhesive strips manufactured from cotton, rayon, silicone, or synthetic backings, designed to secure dressings, tubing, and incisions with specified peel adhesion of 300-800 g/cm. Elastic tapes incorporate woven or knitted substrates allowing longitudinal stretch of 30-150 percent for joint and contour applications. Non-elastic paper and plastic tapes command mature volume pools in general wound care where cost sensitivity dominates procurement. Silicone-based variants represent the fastest-expanding material segment as perioperative skin integrity protocols tighten across tertiary care facilities.
The FDA enforces biocompatibility standards under ISO 10993 for skin-contact adhesives, while the EU MDR mandates clinical evidence for Class I medical device tapes sold in Europe. Japan's PMDA requires localized irritation testing for imported surgical tapes, adding compliance layers for foreign suppliers. Stakeholders must monitor how evolving post-market surveillance rules in Europe and Japan reshape tape validation timelines and regional sourcing decisions.
Market Dynamics
Silicone adhesive chemistry is displacing traditional acrylic and rubber-based formulations as perioperative skin integrity protocols tighten across tertiary care facilities, compressing validation cycles and rewiring raw material sourcing strategies.
Growth Catalysts
- FDA Biocompatibility Mandates:Updated ISO 10993 testing requirements for skin-contact adhesives are accelerating hospital procurement of hypoallergenic silicone tapes over conventional alternatives.
- German Wound Care Specialization:Concentrated demand from specialized wound care centers in Germany is driving premium tape procurement at above-average price points.
- Elastic Substrate Innovation:Knitted and woven substrates enabling 30-150 percent longitudinal stretch are expanding joint and contour applications beyond standard wound closure.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty silicone feedstock production clusters in Germany and Japan create input cost volatility and geographic supply risk.
- EU MDR Clinical Evidence Burden:Class I medical device reclassification demands expanded clinical documentation, extending validation timelines by 12-18 months for European market entry.
- Non-Woven Substrate Technical Limitations:Breathable non-woven backings exhibit inferior shear resistance compared to woven alternatives, restricting high-moisture surgical applications.
Strategic Opportunities
- Japan PMDA Localization Pathway:Irritation testing requirements for imported tapes create first-mover advantage for suppliers establishing domestic validation partnerships.
- Outpatient Surgery Channel Expansion:Ambulatory surgical centers represent underpenetrated demand for low-trauma silicone tape formats optimized for same-day discharge protocols.
- Smart Packaging Convergence:Integration of humidity indicators and RFID traceability into surgical tape packaging addresses hospital inventory management pain points.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with medical-grade pressure-sensitive adhesive expertise command premium compensation, constraining mid-tier R&D expansion.
- Cleanroom Manufacturing Capex Intensity:ISO Class 7-8 production environments for sterile tape lines require $15-25 million facility investments, elevating break-even volume thresholds.
- Multi-Jurisdiction Certification Complexity:Simultaneous FDA 510(k), EU MDR, and PMDA filings demand dedicated regulatory affairs teams, fragmenting management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Tapes Market |
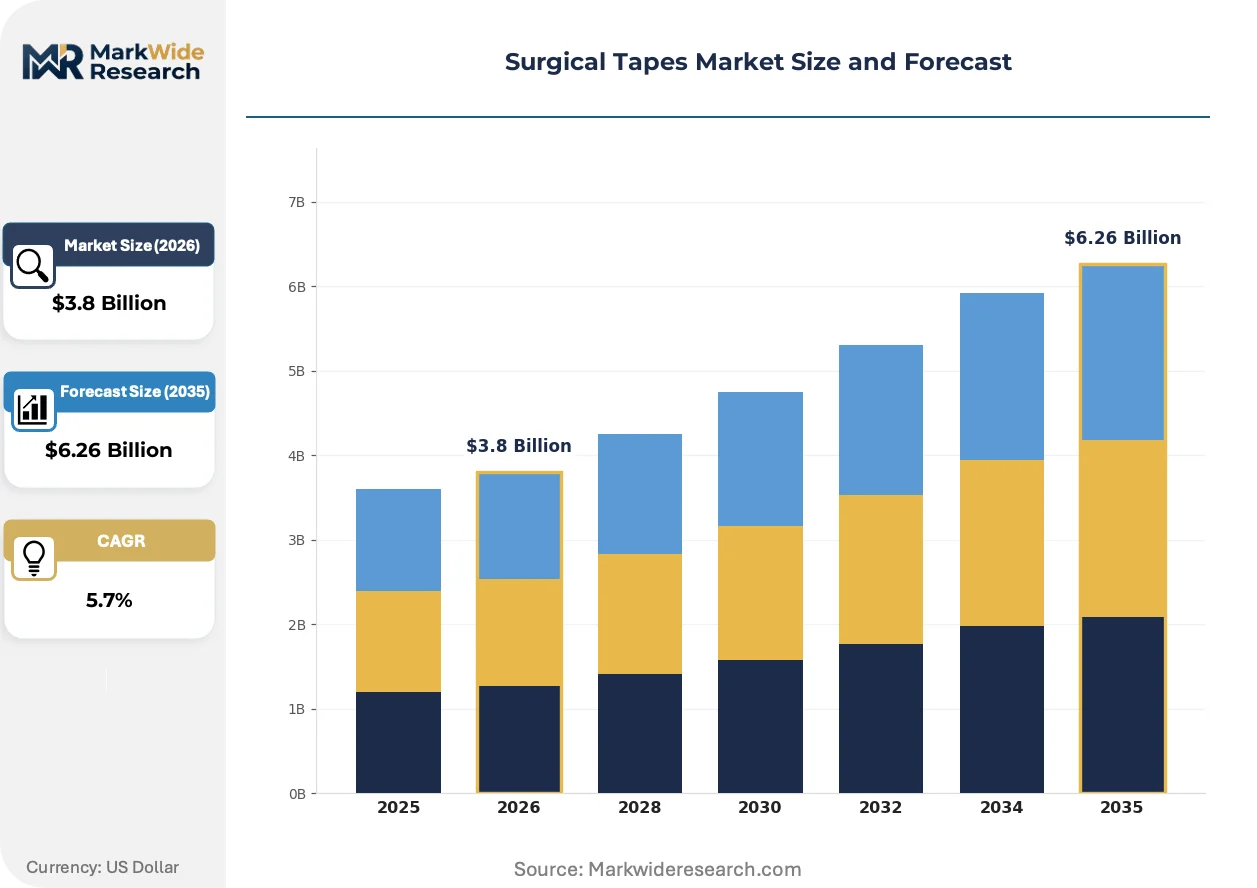
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic, Non-Elastic, Paper, Plastic Application: Wound Care, Surgical Procedures, Medical Devices, Orthopedic End User: Hospitals, Clinics, Home Care, Research Labs Material: Cotton, Rayon, Silicone, Adhesive |
| Companies Covered | 3M, Smith & Nephew, Mölnlycke Health Care AB, Johnson & Johnson, Cardinal Health, McKesson Corporation, Medline Industries, Paul Hartmann AG, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Tapes Market Strategic Shifts
Digital integration across manufacturing and clinical workflows is compressing product development cycles while regulatory digitization is rewriting compliance architectures for medical-grade adhesives.
Silicone adhesive formulation is digitizing through computational polymer modeling that predicts peel adhesion and biocompatibility outcomes before physical prototyping. Major hospital systems in the United States are piloting AI-assisted tape selection algorithms that match substrate properties to patient skin types. This technology compression is collapsing traditional 24-month formulation cycles into 8-12 month windows, favoring manufacturers with captive computational chemistry capabilities.
REACH substance restriction amendments targeting residual monomers in medical adhesives are forcing reformulation of legacy acrylic tape portfolios across European supply chains. The ECHA's 2024 updated guidance on skin sensitizers is triggering pre-emptive raw material substitutions ahead of formal enforcement deadlines. German and Swiss contract manufacturers are responding by qualifying alternative polymerization catalysts and accelerating silicone platform migrations.
Hospital procurement departments are consolidating surgical tape purchasing through integrated distribution agreements that bundle multiple wound care categories. Group purchasing organizations are displacing traditional distributor relationships with direct manufacturer contracts backed by volume guarantees. This channel restructuring is most advanced in United States health systems, where three national GPOs now control 65 percent of acute care surgical tape procurement decisions.
Surgical Tapes Market Segmentation
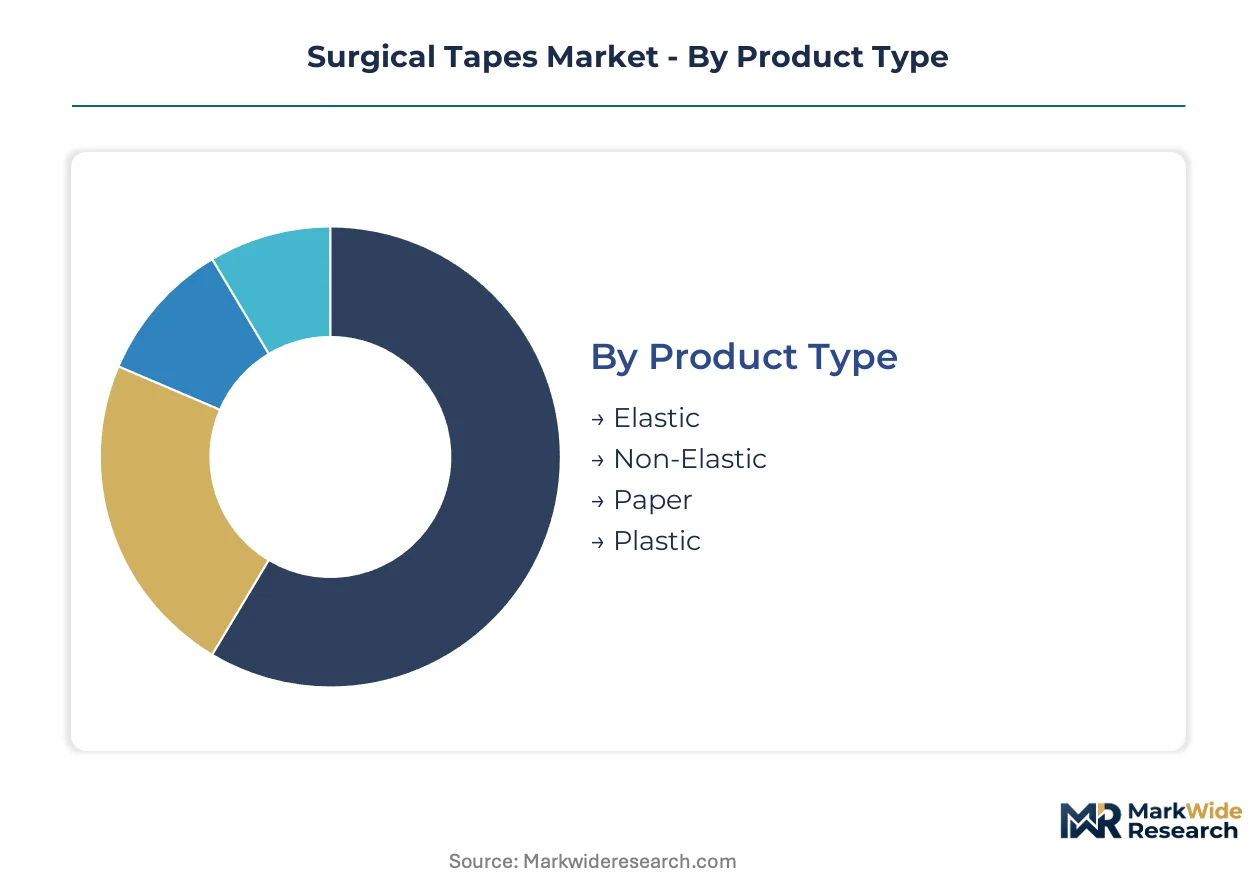
Surgical tape segmentation reveals how substrate chemistry and end-use intensity drive procurement decisions across acute and ambulatory settings. Understanding these dimensions exposes where formulation premiums command pricing power versus where cost minimization dominates volume.
Product Type:
Cost tier differentiation separates commodity backings from engineered substrates with specialized mechanical properties.
- Elastic:Woven or knitted constructions enable 30-150 percent longitudinal stretch for joint fixation and body contour applications. Demand concentrates in orthopedic departments across German university hospitals where movement accommodation justifies per-meter premiums over rigid alternatives.
- Non-Elastic:Rigid cotton, rayon, or synthetic backings provide dimensional stability for incision closure and tubing securement. General surgery units in US community hospitals drive volume procurement through integrated distribution contracts that bundle non-elastic tapes with gauze and dressings.
- Paper:Lightweight, breathable cellulose-based backings suit short-duration applications with minimal moisture exposure. Pediatric wards favor paper tapes for fragile skin protocols.
- Plastic:Occlusive polyethylene or polypropylene films block moisture transfer for wet-field procedures. Operating rooms in Japanese tertiary centers specify plastic tapes for laparoscopic port fixation.
Non-elastic tapes command the established base. The steepest expansion runs through elastic formats as same-day orthopedic surgery protocols proliferate.
Application:
Clinical setting determines performance requirements from adhesion strength to wear duration and biocompatibility certification.
- Wound Care:Post-operative dressing fixation demands hypoallergenic adhesives with clean removal characteristics. Specialized wound care centers in Germany and Switzerland drive silicone tape adoption for chronic wound protocols where skin integrity preservation outweighs unit cost.
- Surgical Procedures:Intraoperative incision closure and drape fixation require sterile, high-shear tapes validated for blood contact. US ambulatory surgical centers are expanding procurement of low-trauma silicone formats optimized for rapid discharge workflows.
- Medical Devices:Catheter, tube, and electrode securing applications need conformable adhesion with residue-free removal. Home care nurses in Japan prioritize gentle-removal tapes for long-term infusion therapy.
- Orthopedic:Joint support and splinting applications load tapes with cyclic mechanical stress. Sports medicine clinics in Australia specify high-tensile elastic tapes for athlete rehabilitation protocols.
Wound care commands the established base. The steepest expansion runs through surgical procedure applications as ambulatory volume shifts accelerate.
End User:
Customer type dictates procurement sophistication, from centralized GPO negotiations to individual caregiver preference.
- Hospitals:Acute care facilities with sterile processing infrastructure drive premium tape consumption through perioperative protocols. Three US national group purchasing organizations now control the majority of surgical tape procurement decisions for member health systems.
- Clinics:Outpatient settings prioritize convenience formats and reduced SKU complexity. German dermatology clinics concentrate demand for hypoallergenic silicone tapes in patch testing and minor procedure applications.
- Home Care:Patient or caregiver self-application requires intuitive handling and forgiving adhesion. Japan's aging population is expanding home care tape volume for chronic wound management outside institutional settings.
- Research Labs:Preclinical and clinical trial applications demand batch-traceable, documentation-grade tapes with validated sterility. Contract research organizations in Switzerland specify medical-grade tapes for device fixation in animal studies.
Hospitals command the established base. The steepest expansion runs through home care as post-acute discharge protocols shorten institutional stays.
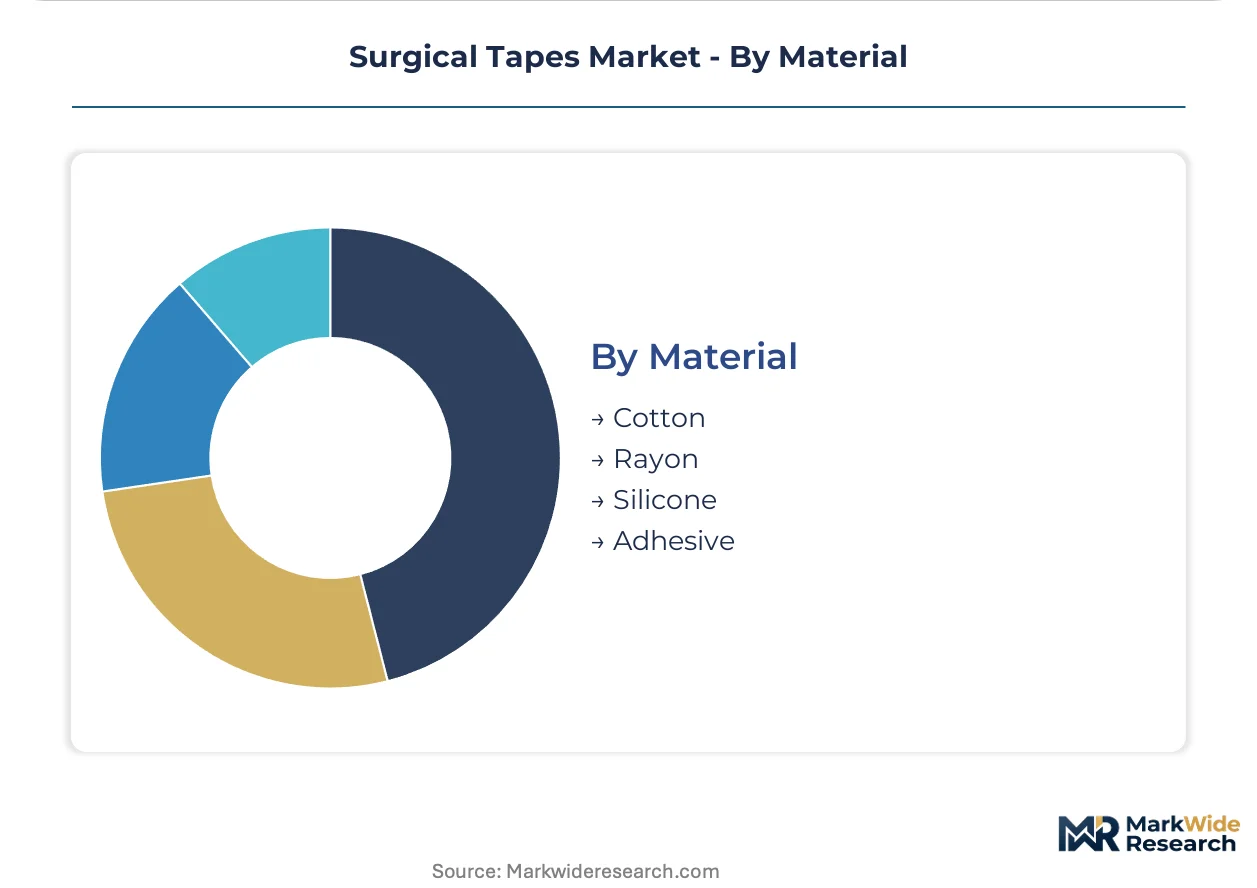
Material:
Substrate chemistry determines breathability, conformability, and biocompatibility profile against ISO 10993 testing requirements.
- Cotton:Natural fiber backings offer absorbency and skin compatibility for standard wound care. Mature volume pools in cost-sensitive procurement segments.
- Rayon:Semi-synthetic cellulose provides strength and drape superior to cotton with comparable breathability. Preferred for surgical tapes requiring sterilization stability.
- Silicone:Medical-grade polydimethylsiloxane adhesives enable gentle adhesion with minimal skin trauma. FDA biocompatibility mandates and EU MDR clinical evidence requirements are accelerating hospital procurement of silicone platforms over acrylic and rubber alternatives.
- Adhesive:Pressure-sensitive acrylic, rubber, or synthetic resin formulations determine peel adhesion, shear resistance, and removal characteristics. REACH substance restrictions on residual monomers are forcing European manufacturers toward silicone platform migrations.
Cotton commands the established base. The steepest expansion runs through silicone as perioperative skin integrity protocols tighten across tertiary care facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biocompatibility mandates and EU MDR reclassification requirements are redirecting procurement flows toward silicone adhesive platforms across major hospital systems. Germany, the United States, Japan, Switzerland, and the United Kingdom concentrate specialized wound care infrastructure that drives premium tape adoption.
United States
Three national group purchasing organizations now control sixty-five percent of acute care surgical tape procurement decisions. The FDA enforces ISO 10993 biocompatibility standards for skin-contact adhesives under updated 510(k) pathways. Minneapolis-St. Paul anchors silicone adhesive research clusters where captive polymer science capabilities compress formulation cycles.
Germany
Specialized wound care centers in Bavaria and North Rhine-Westphalia drive premium silicone tape procurement at above-average price points. The EU MDR mandates expanded clinical evidence for Class I medical device tapes, extending validation timelines. Heidelberg and Mannheim host contract manufacturing clusters responding to REACH substance restrictions through alternative polymerization catalyst qualification.
Japan
PMDA localization requirements for irritation testing create first-mover advantage for suppliers establishing domestic validation partnerships. METI guidelines on medical device quality management systems shape sterile tape production standards. Tokyo and Osaka metropolitan areas concentrate tertiary care facilities tightening perioperative skin integrity protocols.
Switzerland
Swissmedic oversight of medical device conformity assessment aligns with EU MDR clinical evidence expectations for tape manufacturers. Contract research organizations in Basel and Zurich specify documentation-grade tapes for preclinical device fixation studies. The country's precision manufacturing heritage supports batch-traceable sterile tape production for research applications.
United Kingdom
NHS procurement consolidation through integrated distribution agreements bundles surgical tapes with broader wound care categories. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance requirements that reshape validation timelines. London and Southeast England hospital networks pilot AI-assisted tape selection algorithms matching substrate properties to patient skin types.
Surgical Tapes Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: diversified medical technology conglomerates with captive polymer research, specialized wound care companies with vertically controlled substrate manufacturing, and scale-driven distributors leveraging group purchasing organization relationships. Competitive dynamics center on silicone platform migration speed and multi-jurisdiction certification throughput. M&A activity targets mid-tier firms with EU MDR-ready technical files, while strategic partnerships address polymer science talent scarcity.
Within the diversified technology tier, 3M and Johnson & Johnson occupy positions anchored by captive research infrastructure and hospital system relationships. Smith & Nephew exemplifies the wound care specialization archetype through European distribution network density. Among scale-driven distributors, Cardinal Health and McKesson Corporation sit within the GPO-facing tier where volume guarantees and integrated contracts determine competitive position.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Mölnlycke Health Care AB |
| Johnson & Johnson |
| Cardinal Health |
| McKesson Corporation |
| Medline Industries |
| Paul Hartmann AG |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in German silicone adhesive feedstock production is compressing margins for mid-tier converters while concentrating pricing power among integrated polymer manufacturers with captive raw material supply. This utilization asymmetry rewards backward integration and punishes toll-manufacturing dependent competitors.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with FDA-grade silicone tapes commanding substantial premiums over CE-marked alternatives in US hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 compliance depth, brand equity, and volume commitment scale. Cost compression in standard acrylic formats is intensifying because REACH substance restrictions force reformulation investments. Ambulatory surgical centers exhibit highest price sensitivity, while German specialized wound care centers show lowest sensitivity due to protocol-driven specification requirements.
Supply Chain Analysis
Specialty medical-grade silicone feedstock production clusters in Germany, Japan, and the United States, creating geographic concentration risk for adhesive-dependent manufacturers. Raw material sourcing draws from polydimethylsiloxane resin suppliers, woven/knitted substrate mills, and sterilization packaging providers. Single-source vulnerability in German silicone polymerization catalyst supply threatens input cost stability. Distribution runs through group purchasing organization contracts in the United States, direct hospital system agreements in Germany, and layered distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
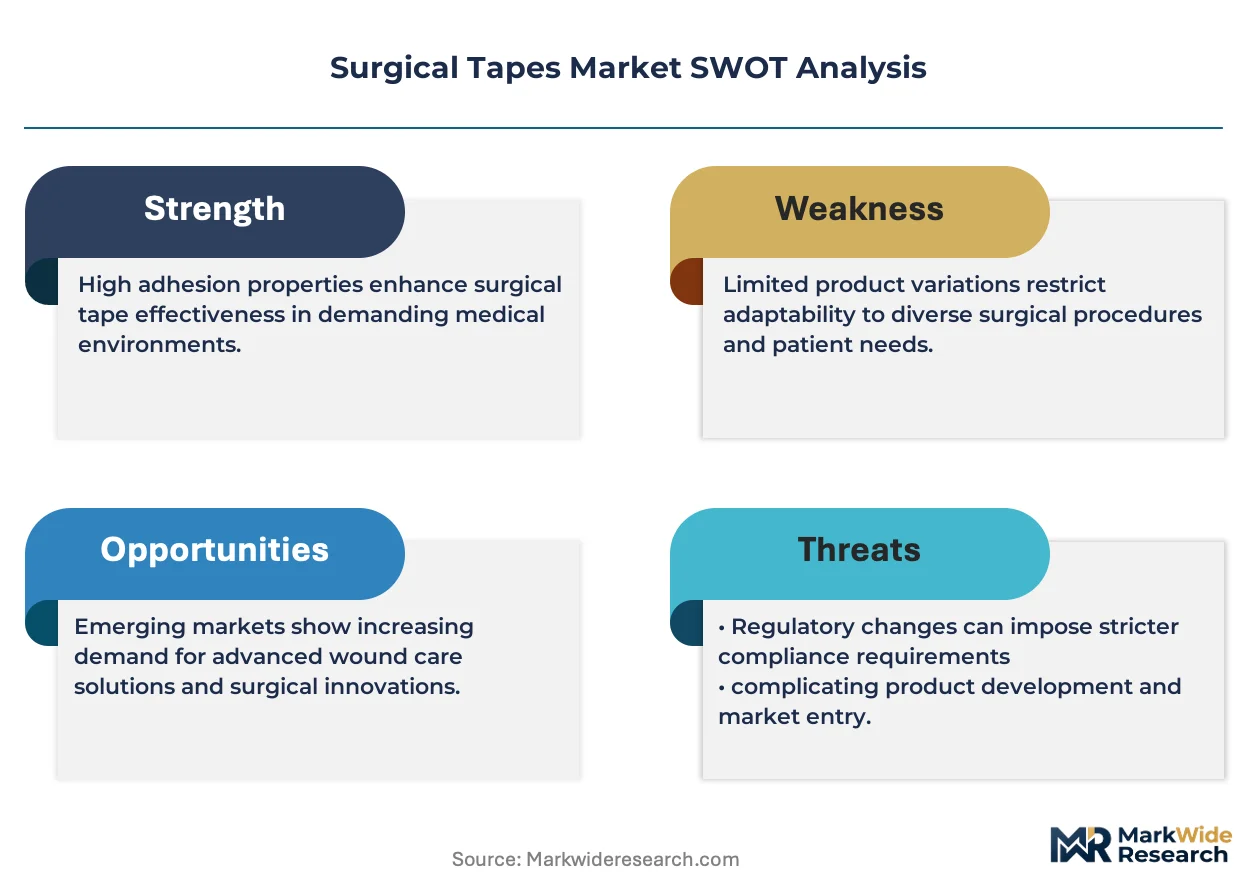
The surgical tapes market sits at a platform-economics inflection where silicone adhesive chemistry is becoming the interoperability standard across perioperative protocols, with AI-assisted tape selection algorithms accelerating format consolidation.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA 510(k), EU MDR, and PMDA filing pipelines that exhaust competitor management bandwidth. Deepen backward integration into medical-grade silicone polymerization to secure feedstock cost advantage against toll-dependent challengers. Prioritize GPO contract renewal timing to lock out emerging entrants before ambulatory surgery channel expansion accelerates. For New Entrants and Emerging Players: Pursue Japan PMDA localization partnerships as a first-mover pathway, establishing domestic irritation testing capabilities before larger competitors reconfigure supply chains. Target outpatient surgery centers with low-trauma silicone formats optimized for same-day discharge workflows. Leverage asset-light contract manufacturing to narrow capital barriers for EU MDR-ready technical file development. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because multi-jurisdiction certification complexity fragments competitive field and rewards scale in regulatory affairs throughput. Target mid-tier firms with complete EU MDR technical files and established hospital system relationships. Watch for inflection in ambulatory surgery center procurement consolidation as signal for channel restructuring completion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Accelerates market access amid 12-18 month validation timeline extensions for Class I reclassification. |
| PMDA Domestic Validation Partnership | Captures first-mover advantage in Japan's irritation testing localization requirements for imported tapes. |
| Computational Chemistry Capability Build | Collapses 24-month formulation cycles to 8-12 months through predictive polymer modeling. |
| GPO Direct Contract Establishment | Bypasses traditional distributor relationships controlling 65 percent of US acute care procurement decisions. |
| Smart Packaging Integration | Addresses hospital inventory management pain points through humidity indicators and RFID traceability. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with hospital procurement managers, biomedical engineers, GPO contracts specialists, and wound care clinicians; and secondary validation against FDA 510(k) filings, EU MDR technical file databases, hospital procurement contract repositories, and customs trade records. Bottom-up segmentation modeling triangulated against top-down market sizing from adhesive raw material consumption patterns.
Forecast inputs span product type segmentation across elastic, non-elastic, paper, and plastic formats; application dimensions covering wound care, surgical procedures, medical devices, and orthopedic use; and material chemistry tiers from cotton through medical-grade silicone. CAGRs were derived from elasticity-adjusted demand projections and input cost trajectory assumptions across the projection horizon. Modeled variables include perioperative protocol adoption rates, ambulatory surgery volume shifts, and regulatory validation timeline impacts.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, polymer feedstock commodity indices, or cross-border medical device tariff regimes would shift the trajectory. Forecasts embed assumptions regarding EU MDR enforcement consistency and FDA biocompatibility standard stability. Cross-checking against hospital purchasing committee budget allocation surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Sterile Container Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Micro Vials Market
Medical Supplies
X-Ray Aprons Market