
 Gouty Arthritis Market | 2026-2036
Gouty Arthritis Market Size, Share, and Industry Trends Forecast 2026-2036
Gouty Arthritis Market Foresight
Fixed-dose combination packaging of NSAIDs with gastroprotective agents is expanding as a preferred configuration for chronic gout patients requiring long-term therapy. Takeda Pharmaceutical Company Ltd. leverages its heritage in metabolic disease to sustain leadership in uric acid lowering innovation. Horizon Therapeutics differentiates through rare-disease commercial infrastructure that anchors premium positioning for refractory gout biologics. Novartis AG competes via global manufacturing scale that controls cost structures across oral and injectable portfolios.
Gouty arthritis constitutes a crystal-deposition arthropathy driven by persistent hyperuricemia, clinically defined by monosodium urate crystal formation in synovial fluid at serum urate concentrations exceeding saturation thresholds near 6.8 mg/dL, with primary therapeutic objectives encompassing acute flare resolution, chronic tophus regression, and long-term serum urate suppression below 6.0 mg/dL. Uric acid lowering agents command the deepest margin pools as patients require indefinite therapy, while injectable delivery modes represent the fastest-expanding configuration due to biologic penetration in refractory populations. Oral formulations retain volume dominance across outpatient clinics and homecare settings where patient self-administration reduces systemic healthcare utilization.
FDA bioequivalence standards and EMA biosimilar pathways jointly shape product development timelines and market access conditions for novel urate-lowering therapies across North America and Europe. The WHO Essential Medicines List inclusion criteria for colchicine and allopurinol influence procurement priorities in emerging health systems and generic substitution policies. Stakeholders must monitor evolving payer evidence requirements for cardiovascular outcomes data as the gout-hypertension-diabetes comorbidity burden intensifies scrutiny on chronic therapy value propositions.
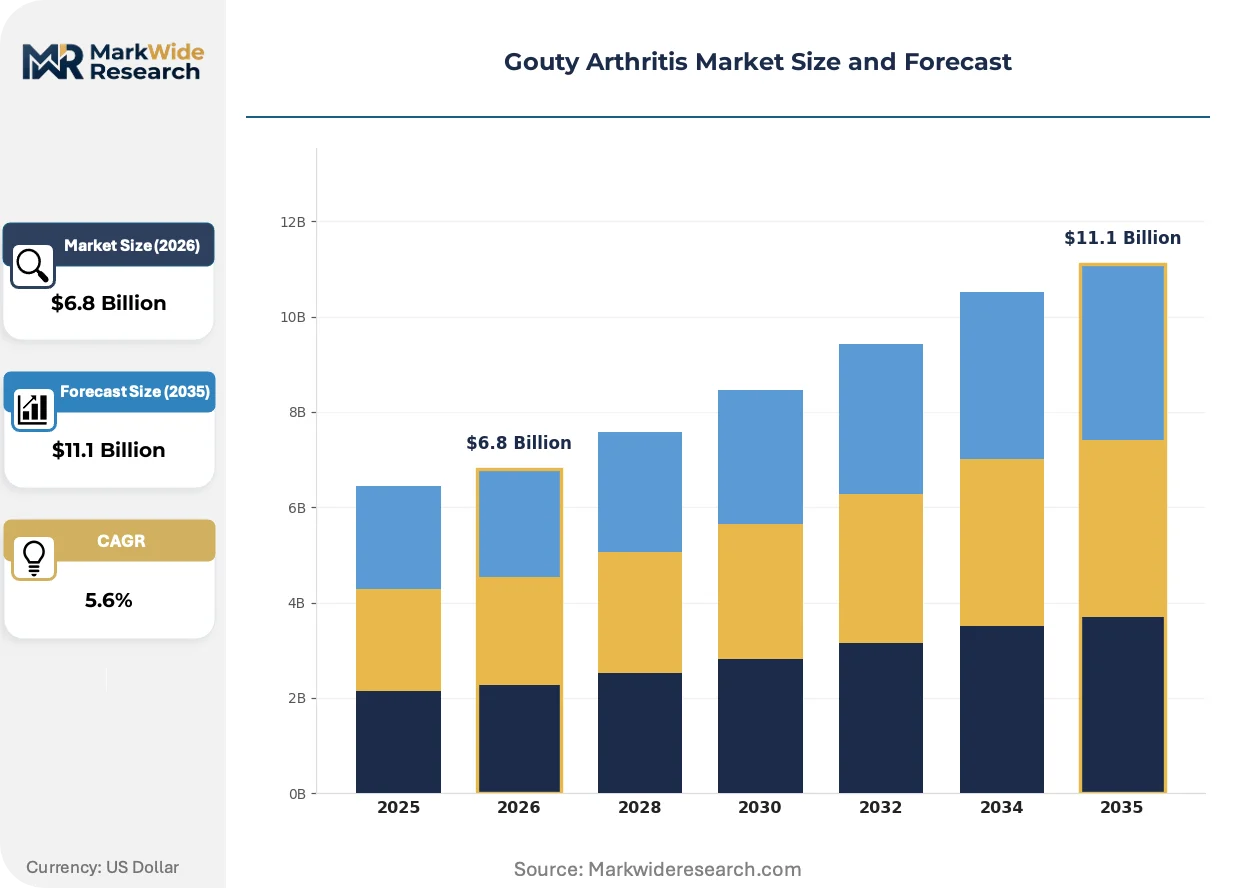
Market Dynamics
The FDA's evolving biosimilar interchangeability guidance is compressing brand exclusivity windows for biologic urate-lowering therapies while specialty pharmacies capture patient access control through integrated care models.
Growth Catalysts
- Cardiovascular outcomes data requirements:Payer evidence demands for gout-hypertension comorbidity management are expanding addressable patient pools through integrated chronic disease protocols.
- Japan's metabolic disease infrastructure:PMDA accelerated review pathways for uric acid lowering therapies are shortening time-to-market for novel mechanisms in refractory populations.
- Injectable biologic penetration:Self-administration training programs at specialty pharmacies are converting oral-intolerant patients to biologic regimens with higher persistence rates.
Market Restraints
- API concentration in China:Allopurinol and febuxostat active pharmaceutical ingredient manufacturing clusters in Zhejiang province create single-source vulnerability for generic supply continuity.
- Colchicine price volatility:Agricultural sourcing constraints for Colchicum autumnale cultivation in Turkey and Greece generate batch-to-batch cost instability for acute flare therapies.
- EMA biosimilar immunogenicity thresholds:Stringent anti-drug antibody monitoring requirements for pegloticase biosimilars are extending development timelines and elevating post-market surveillance burdens.
Strategic Opportunities
- Brazil's ANVISA rare disease pathway:Refractory gout biologics qualify for priority review and extended market exclusivity under the country's differentiated regulatory framework for unmet metabolic needs.
- Digital therapeutics convergence:Smartphone-connected dosing adherence platforms paired with wearable uric acid monitors are creating subscription revenue models alongside pharmaceutical sales.
- South Korea's MFDS fast-track:Orphan drug designation for tophaceous gout subpopulations unlocks tax incentives and waived registration fees for first-in-class urate-lowering mechanisms.
Industry Challenges
- Rheumatology-gastroenterology coordination:Cross-specialty patient handoff protocols for NSAID-gastroprotective combination therapy management require health system workflow redesign and EHR interoperability investment.
- Biosimilar switching liability:Pharmacy benefit managers face operational complexity in tracking nocebo response rates and attribution of adverse events across interchangeable biologic substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gouty Arthritis Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonsteroidal Anti-Inflammatory Drugs, Colchicine, Corticosteroids, Uric Acid Lowering Agents Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Outpatient Clinics, Homecare Settings, Specialty Pharmacies Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Takeda Pharmaceutical Company Ltd., Novartis AG, AstraZeneca, Horizon Therapeutics, Merck & Co. Inc., Pfizer Inc., AbbVie Inc., Teijin Pharma Ltd., JW Pharmaceutical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gouty Arthritis Market Shifts & Advancements
Fixed-dose combination packaging and digital adherence monitoring are converging to reshape chronic gout management economics, while regulatory pressure on cardiovascular safety data is elevating trial design complexity.
Subcutaneous pegloticase formulations with methotrexate co-therapy are integrating immunomodulation directly into biologic administration protocols. Rheumatology practices in the United States are adopting these regimens at accelerating pace to reduce infusion reaction rates. The technology is integrating infusion center capacity planning with pharmacy benefit pre-authorization workflows, compressing time-to-therapy initiation from weeks to days.
REACH authorization requirements for novel chemical entities in the European Union are mandating extended environmental fate studies for uricosuric agents with renal excretion pathways. Manufacturers must now demonstrate aquatic toxicity thresholds below 0.01 micrograms per liter in surface water monitoring. Oral formulation portfolios face the steepest compliance cost escalation, particularly for products targeting Germany's stringent wastewater discharge standards.
Self-insured employers are unbundling gout management from general pharmacy benefits to carve out specialty pharmacy networks with outcomes-based contracts. Third-party administrators in Texas and Florida are replacing traditional per-prescription reimbursement with annual total cost of care guarantees tied to flare frequency reduction. The shift is most visible in manufacturing sector health plans where gout prevalence among production workers drives measurable absenteeism costs.
Gouty Arthritis Market Segmentation
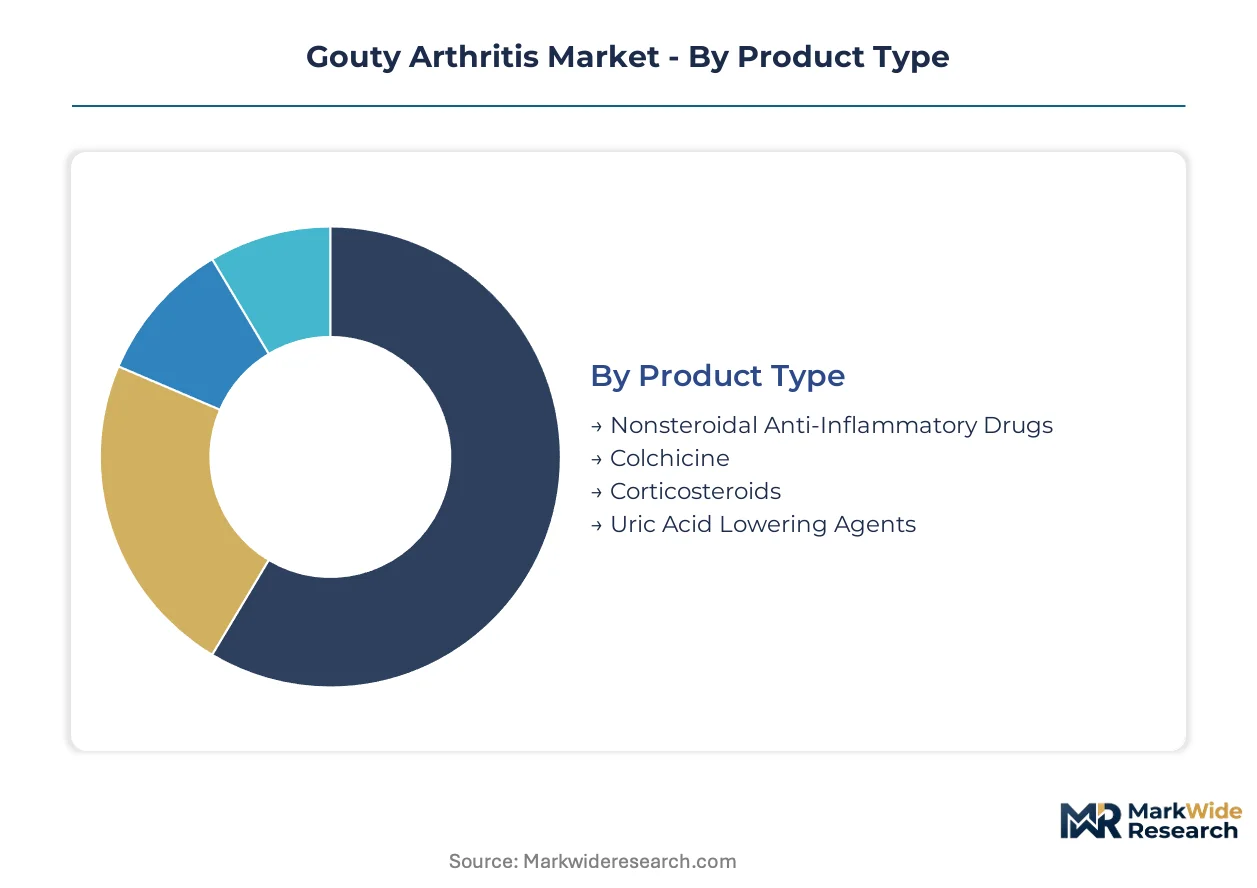
Therapeutic configuration and care setting determine margin capture and capital deployment intensity across the gouty arthritis market. Segmentation reveals where biologic innovation concentrates versus where generic commoditization erodes returns.
Product Type:
Capital intensity varies sharply by mechanism of action, with biologic manufacturing requiring dedicated fermentation capacity and immunogenicity testing infrastructure that small-molecule lines cannot accommodate.
- Uric Acid Lowering Agents:Enzymatic biologics and xanthine oxidase inhibitors dominate chronic therapy economics. Manufacturing scale-up for pegloticase biosimilars demands sterile fill-finish investment that only Takeda and Novartis AG currently maintain at commercial volume. Demand concentrates in refractory populations where serum urate targets below 6.0 mg/dL justify premium pricing.
- Nonsteroidal Anti-Inflammatory Drugs:Fixed-dose combinations with proton pump inhibitors represent the dominant acute flare configuration. API sourcing from Zhejiang province manufacturers keeps capital requirements minimal, though gastroprotective co-formulation adds coating line complexity at contract manufacturers.
- Colchicine:Agricultural extraction from Colchicum autumnale limits synthetic chemistry investment, with Turkish and Greek cultivation determining batch economics.
- Corticosteroids:Generic prednisone and triamcinolone formulations operate on depreciated oral solid dose capacity with minimal R&D burden.
Most installed capacity flows through Uric Acid Lowering Agents. Expansion is steepest in Nonsteroidal Anti-Inflammatory Drugs.
Delivery Mode:
Patient self-administration preference and reimbursement complexity create divergent margin profiles across administration routes.
- Oral:Allopurinol and febuxostat tablets sustain volume leadership through outpatient prescribing and homecare compliance. The configuration avoids cold-chain logistics entirely, though bioavailability constraints limit dosing flexibility in renal impairment populations.
- Injectable:Subcutaneous pegloticase with methotrexate co-therapy is converting infusion-center capacity to self-administration training models. Specialty pharmacy networks in the United States capture patient access control through these regimens.
- Intravenous:Hospital-based infusion maintains position for acute tophaceous presentations requiring monitored administration.
- Topical:Limited penetration for localized joint inflammation with minimal systemic exposure.
Oral formulations retain the largest patient base. Injectable configurations are gaining share fastest in refractory segments.
End User:
Care setting determines therapy persistence and the intensity of comorbidity management required for gout-hypertension-diabetes coordination.
- Specialty Pharmacies:Integrated care models with biologic pre-authorization workflows and adherence monitoring platforms concentrate high-value chronic therapy management. These sites capture outcomes-based contracts from self-insured employers seeking flare frequency guarantees.
- Outpatient Clinics:Rheumatology practices initiate most oral urate-lowering therapy and manage dose titration protocols. EHR interoperability investments here determine NSAID-gastroprotective combination prescribing efficiency.
- Hospitals:Acute flare presentation and tophaceous complications requiring surgical intervention.
- Homecare Settings:Self-administration of oral maintenance therapy with remote monitoring support.
Specialty Pharmacies command the highest revenue per patient. Outpatient Clinics handle the largest prescription volume.
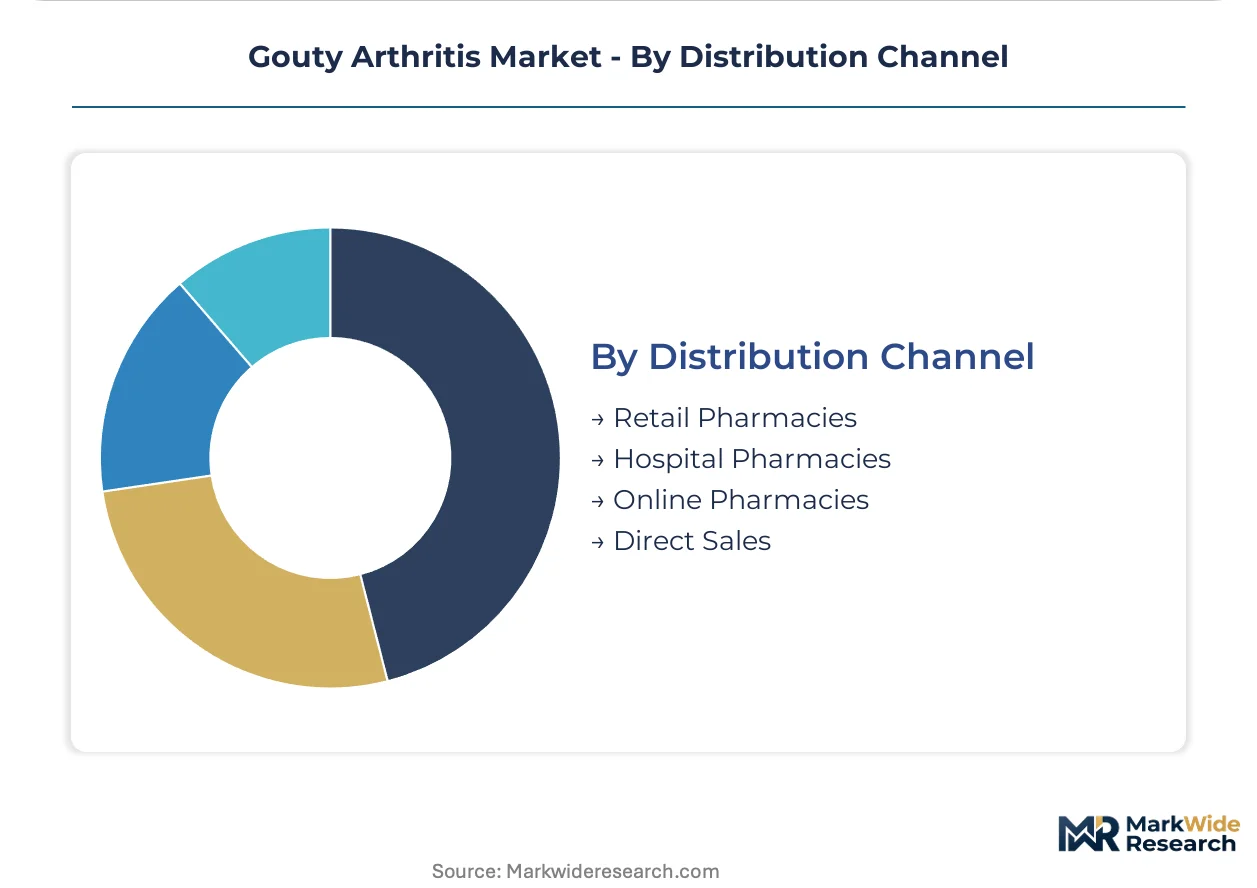
Distribution Channel:
Channel control determines formulary placement speed and the feasibility of outcomes-based contracting structures.
- Hospital Pharmacies:Intravenous biologic procurement through 340B pricing programs and group purchasing organizations. These sites manage pegloticase inventory with strict cold-chain protocols and infusion reaction rescue medication requirements.
- Retail Pharmacies:Generic allopurinol and colchicine dispensing with minimal clinical intervention. The channel faces margin compression from Medicare Part D price negotiation provisions.
- Online Pharmacies:90-day supply fulfillment for stable chronic patients with established urate targets.
- Direct Sales:Limited to institutional accounts with integrated specialty pharmacy carve-outs.
Hospital Pharmacies control biologic access. Online Pharmacies are expanding most quickly for maintenance therapy refills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern urate-lowering therapy originated in Japan's post-war metabolic disease research programs, with Takeda Pharmaceutical's 1960s allopurinol development establishing the therapeutic foundation that spread through North American and European rheumatology practices over subsequent decades.
United States
Self-insured employers in manufacturing and logistics sectors drive biologic adoption through outcomes-based contracts tied to absenteeism reduction. FDA biosimilar interchangeability guidance compresses brand exclusivity windows for pegloticase therapies. Specialty pharmacy networks in Texas and Florida anchor integrated care models with flare frequency guarantees.
Japan
Aging demographics and high metabolic disease prevalence sustain demand for novel uric acid lowering mechanisms. PMDA accelerated review pathways shorten time-to-market for refractory gout biologics. Tokyo-Osaka pharmaceutical corridors concentrate fermentation capacity and immunogenicity testing infrastructure.
Germany
REACH authorization mandates extended environmental fate studies for uricosuric agents with renal excretion pathways. Stringent wastewater discharge standards in Bavaria and North Rhine-Westphalia elevate compliance costs for oral formulation portfolios. Rheumatology-gastroenterology coordination protocols require EHR interoperability investment across hospital networks.
Brazil
Rising diagnosis rates among urban working populations expand addressable patient pools for chronic therapy. ANVISA rare disease pathways qualify refractory gout biologics for priority review and extended market exclusivity. São Paulo's metabolic disease research centers anchor clinical trial recruitment for novel mechanisms.
South Korea
Orphan drug designation for tophaceous gout subpopulations unlocks tax incentives and waived registration fees through MFDS fast-track procedures. Seoul Capital Area biotech clusters concentrate contract manufacturing for subcutaneous pegloticase formulations. Digital therapeutics convergence with smartphone-connected adherence platforms creates subscription revenue models.
Gouty Arthritis Market Competitive Landscape
Premium-margin players sit above commodity-margin players across therapeutic configuration, with biologic manufacturers commanding dedicated fermentation capacity while generic oral solid dose producers compete on depreciated lines. The market structures around three tiers: integrated pharmaceutical conglomerates with global manufacturing scale, specialty biotech firms with rare-disease commercial infrastructure, and regional generic manufacturers with API sourcing advantages. Two competitive moves dominate: strategic partnerships between specialty pharmacies and biologic developers for integrated care capture, and portfolio diversification into fixed-dose combination packaging with gastroprotective agents.
Within the integrated pharmaceutical tier, Takeda Pharmaceutical Company Ltd. and Novartis AG exemplify global manufacturing scale that controls cost structures across oral and injectable portfolios. Horizon Therapeutics occupies a position exemplifying specialty rare-disease commercial infrastructure that anchors premium positioning for refractory gout biologics.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Ltd. |
| Novartis AG |
| AstraZeneca |
| Horizon Therapeutics |
| Merck & Co. Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Teijin Pharma Ltd. |
| JW Pharmaceutical Corporation |
| Others |
Supply & Pricing Matrix
Specialty pharmacy networks in the United States anchor pricing power through outcomes-based contracts that tie reimbursement to flare frequency reduction rather than per-prescription margins. This buyer concentration forces manufacturers toward value-based pricing models while API sourcing geography determines cost floor flexibility.
Pricing Analysis
Three-tier pricing structure across biologic premium, branded oral standard, and generic economy levels dominates the gouty arthritis market. Price differentiation hinges on FDA bioequivalence certification status and specialty pharmacy distribution exclusivity. Cost compression in the generic allopurinol tier is intensifying because of Zhejiang province API oversupply. Self-insured employers demonstrate lowest price sensitivity for biologic regimens with absenteeism guarantees, while retail pharmacy channels face highest sensitivity under Medicare Part D negotiation.
Supply Chain Analysis
Reverse logistics for temperature-sensitive biologics requires cold-chain validation and infusion reaction rescue medication return protocols that add 12-15% to distribution overhead. Active pharmaceutical ingredient production concentrates in China's Zhejiang province for xanthine oxidase inhibitors, Turkey and Greece for colchicine agricultural extraction, and Japan's Tokyo-Osaka corridor for fermentation-based biologics. Supply chain risk centers on single-source vulnerability for pegloticase drug substance manufacturing. Distribution runs through specialty pharmacy networks with integrated patient adherence monitoring for biologics, while generic oral formulations flow through retail and online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gouty arthritis market functions as a stable compounder driven by indefinite therapy duration for chronic urate-lowering agents that generates recurring revenue streams resistant to economic cyclicality.
For Market Incumbents: Lock in specialty pharmacy partnerships with outcomes-based contracting infrastructure before biosimilar interchangeability guidance erodes brand exclusivity windows. Horizon Therapeutics and Takeda Pharmaceutical should expand backward integration into fermentation capacity for pegloticase drug substance to reduce single-source dependency on external API suppliers. Priority certification investment should target EMA immunogenicity monitoring compliance for European market defense. For New Entrants and Emerging Players: Digital therapeutics convergence with smartphone-connected uric acid monitoring represents the most penetrable white-space opportunity, particularly in South Korea's Seoul Capital Area where MFDS fast-track procedures accelerate regulatory pathways. Target tophaceous gout subpopulations in Brazil's São Paulo metropolitan region where ANVISA rare disease designation unlocks tax incentives and extended exclusivity. Go-to-market execution should anchor on specialty pharmacy adherence platform partnerships rather than traditional physician detailing. For Investors and Strategic Acquirers: Specialty pharmaceutical conglomerates with rare-disease commercial infrastructure are the most active acquirers in this space, seeking bolt-on biologic assets that leverage existing payer access relationships. Long-term viability over a 5-10 year horizon rests on cardiovascular outcomes data generation capabilities that satisfy evolving payer evidence requirements. Monitor FDA biosimilar interchangeability designation announcements for pegloticase candidates as the primary inflection indicator for brand revenue erosion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Takeda and Novartis AG expand sterile fill-finish capacity for pegloticase biosimilar production at commercial volume. |
| Regulatory Approval Pathway | PMDA accelerated review in Japan shortens time-to-market for novel uric acid lowering mechanisms in refractory populations. |
| Strategic Partnership | Specialty pharmacy networks in Texas and Florida anchor integrated care models with flare frequency guarantees for self-insured employers. |
| Pipeline Diversification | Fixed-dose combination packaging of NSAIDs with gastroprotective agents expands preferred configuration for chronic gout patients. |
| Reimbursement Strategy | Outcomes-based contracts replace per-prescription reimbursement in manufacturing sector health plans with absenteeism reduction metrics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply-side intelligence for the gouty arthritis market. Primary engagement captured perspectives from drug development executives at biologic manufacturers, regulatory affairs leads navigating FDA biosimilar pathways, formulary directors at national pharmacy benefit managers, and specialty pharmacy operations heads managing patient adherence platforms. Secondary validation drew from FDA Orange Book listings, EMA biosimilar assessment reports, ClinicalTrials.gov protocol registries, and CMS Medicare Part D utilization databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Comparable-period anchoring established baseline prevalence and treatment rates against historical diagnosis patterns and therapy penetration benchmarks before projecting forward. The analytical framework segmented by therapeutic mechanism, delivery mode, and care setting across the projection horizon, with regional regulatory clusters treated as distinct adoption curves. CAGRs emerged from fitted growth trajectories calibrated to epidemiological expansion, reimbursement evolution, and biosimilar entry timing. Forecast inputs incorporated serum urate target attainment rates, specialty pharmacy network expansion, and cardiovascular outcomes trial readouts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA biosimilar interchangeability determinations and colchicine agricultural supply disruptions. Practitioners should monitor EMA immunogenicity threshold revisions and REACH environmental fate study mandates for early signals of regulatory cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Schizophrenia Treatment Market