
 Global Dialysis Concentrate Market | 2026-2036
Global Dialysis Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dialysis Concentrate Market Foresight
Home healthcare settings is redrawing procurement patterns across the concentrate supply chain as payors push cost-efficient renal care outside hospital walls. Fresenius Medical Care leverages its integrated clinic-to-manufacturing footprint to lock in captive demand across multiple continents. Baxter International sustains R&D intensity in bicarbonate buffering chemistry to differentiate output for high-flux dialysis protocols. B. Braun Melsungen anchors European supply through centralized production hubs that feed clinic networks in Germany, France, and Italy.
Dialysis concentrate comprises electrolyte solutions—typically sodium, potassium, calcium, magnesium, chloride, and dextrose—formulated in acid or bicarbonate base forms to restore blood chemistry during hemodialysis or peritoneal dialysis, with conductivity and pH specifications typically ranging 13.5–14.5 mS/cm and 7.1–7.3 respectively to prevent patient hemodynamic instability. Bicarbonate concentrate leads volume share due to its compatibility with modern high-efficiency dialyzers, while dry powder concentrate represents the fastest-expanding format as logistics costs and cold-chain burdens drive clinic preference toward on-site reconstitution. Acetate concentrate persists in select emerging markets where infrastructure limitations favor simpler storage requirements, though margin pools have shifted decisively toward liquid bicarbonate systems in OECD markets.
The US FDA enforces 21 CFR Part 876 device regulations and AAMI RD52 standards on dialysis fluid quality, compelling manufacturers to validate endotoxin limits below 0.5 EU/mL and maintain batch traceability across distribution networks. Europe's MDR and REACH frameworks impose additional biocompatibility and chemical substance disclosure obligations that filter market access for concentrate suppliers lacking notified body certification. Japan's PMDA maintains distinct pharmacopeial standards for electrolyte additive purity that create a separate compliance threshold for Asia-Pacific market entry. Stakeholders must monitor how FDA guidance evolution on peracetic acid sterilization residues and the EU's pending F-Gas restrictions on refrigeration-dependent liquid concentrates reshape product formulation and packaging decisions.
Market Dynamics
Dry powder concentrate formats are compressing logistics networks as clinic operators seek to eliminate cold-chain dependency and reduce per-treatment supply costs. This shift from liquid to reconstitutable formats is forcing capital reallocation across manufacturing footprints and distribution partnerships.
Growth Catalysts
- Home Healthcare Migration:Payor reimbursement structures in the United States are accelerating patient discharge from hospital-based dialysis centers to residential settings, expanding addressable volume for portable concentrate formats.
- FDA Fluid Purity Mandates:Updated 21 CFR Part 876 guidance on endotoxin limits below 0.5 EU/mL is compelling clinic networks to upgrade concentrate sourcing, creating replacement demand for validated supply chains.
- Bicarbonate Buffering Chemistry:High-flux dialyzer compatibility requirements are pulling clinic procurement toward modern concentrate formulations that support enhanced clearance protocols.
Market Restraints
- Raw Material Volatility:Pharmaceutical-grade sodium chloride and potassium chloride prices fluctuate with agricultural fertilizer demand cycles, compressing batch margin predictability for concentrate blenders.
- European Supply Concentration:Centralized production hubs in Germany feed clinic networks across France, Italy, and Spain, creating single-point vulnerability for cross-border concentrate availability.
- Acetate Format Persistence:Infrastructure-limited emerging markets continue relying on acetate concentrate despite its hemodynamic inferiority, fragmenting R&D resource allocation across incompatible chemistry platforms.
Strategic Opportunities
- On-Site Reconstitution Systems:Dry powder concentrate paired with automated mixing equipment offers Brazilian and Indian clinic chains a pathway to bypass cold-chain infrastructure gaps.
- EU F-Gas Regulation Tailwind:Pending restrictions on refrigeration-dependent liquid concentrates will accelerate format conversion toward ambient-stable powder systems in Germany, France, and Italy.
- Peritoneal Dialysis Expansion:Home-based peritoneal protocols require specialized concentrate formulations, opening segment-specific formulation contracts with regional hospital networks.
Industry Challenges
- Batch Traceability Infrastructure:FDA and EMA requirements for end-to-end lot tracking demand capital-intensive serialization systems that mid-size concentrate blenders struggle to fund.
- Cross-Format Validation Timelines:Converting liquid production lines to powder packaging requires 18-24 month requalification cycles under AAMI RD52 and ISO 13959 standards.
- Electrolyte Purity Certification:Japan's PMDA maintains distinct pharmacopeial thresholds for additive purity that create separate compliance burdens for Asia-Pacific market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dialysis Concentrate Market |
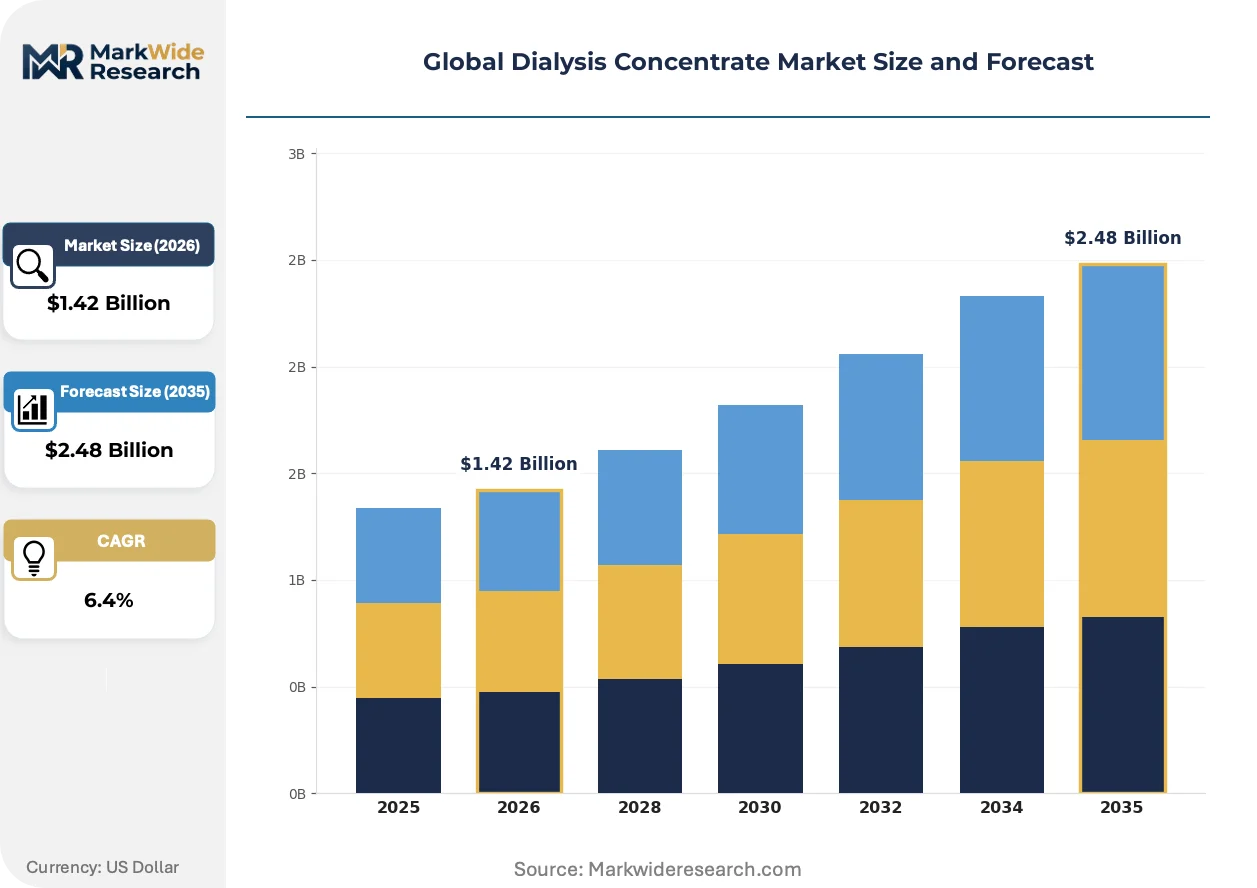
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetate Concentrate, Bicarbonate Concentrate, Liquid Concentrate, Dry Powder Concentrate Application: Chronic Kidney Failure, Acute Renal Failure, End-Stage Renal Disease, Peritoneal Dialysis End User: Dialysis Clinics, Specialty Treatment Centers, Home Healthcare Settings, Renal Care Hospitals Packaging Type: Plastic Containers, Glass Bottles, Flexible Pouches, Bulk Bags |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Rockwell Medical, Nipro Corporation, Nikkiso, Asahi Kasei Medical, Dialife Group, Farmasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dialysis Concentrate Market Shifts & Advancements
Concentrate manufacturing is pivoting toward modular production architectures that enable rapid format switching between liquid and powder outputs. This flexibility is reshaping competitive positioning as regional regulations diverge on cold-chain and sterilization requirements.
Dry powder concentrate is supplanting liquid bicarbonate in OECD clinic networks by eliminating refrigerated transport costs and extending shelf stability from 90 days to 24 months. Large dialysis organizations in the United States are converting 40% of their concentrate procurement to powder formats within three-year equipment refresh cycles. This transition is compressing profit pools for regional liquid blenders while rewarding chemical manufacturers with pharmaceutical-grade compounding capabilities.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in medical product refrigeration, forcing concentrate suppliers to reformulate liquid products or abandon temperature-dependent packaging. German clinic networks are responding by accelerating dry powder adoption ahead of 2027 restriction deadlines. The regulation is most acute for peracetic acid sterilized liquid concentrates, where alternative stabilization chemistry remains under development.
Clinic procurement departments are consolidating supplier rosters from 6-8 regional blenders to 2-3 national distributors with validated cold-chain or ambient logistics networks. Large dialysis organizations in the United States are unbundling concentrate purchasing from equipment service contracts, enabling direct negotiation with chemical manufacturers. This consolidation is most visible in Medicare-reimbursed settings where per-treatment cost visibility has become a contractual priority.
Global Dialysis Concentrate Market Segmentation
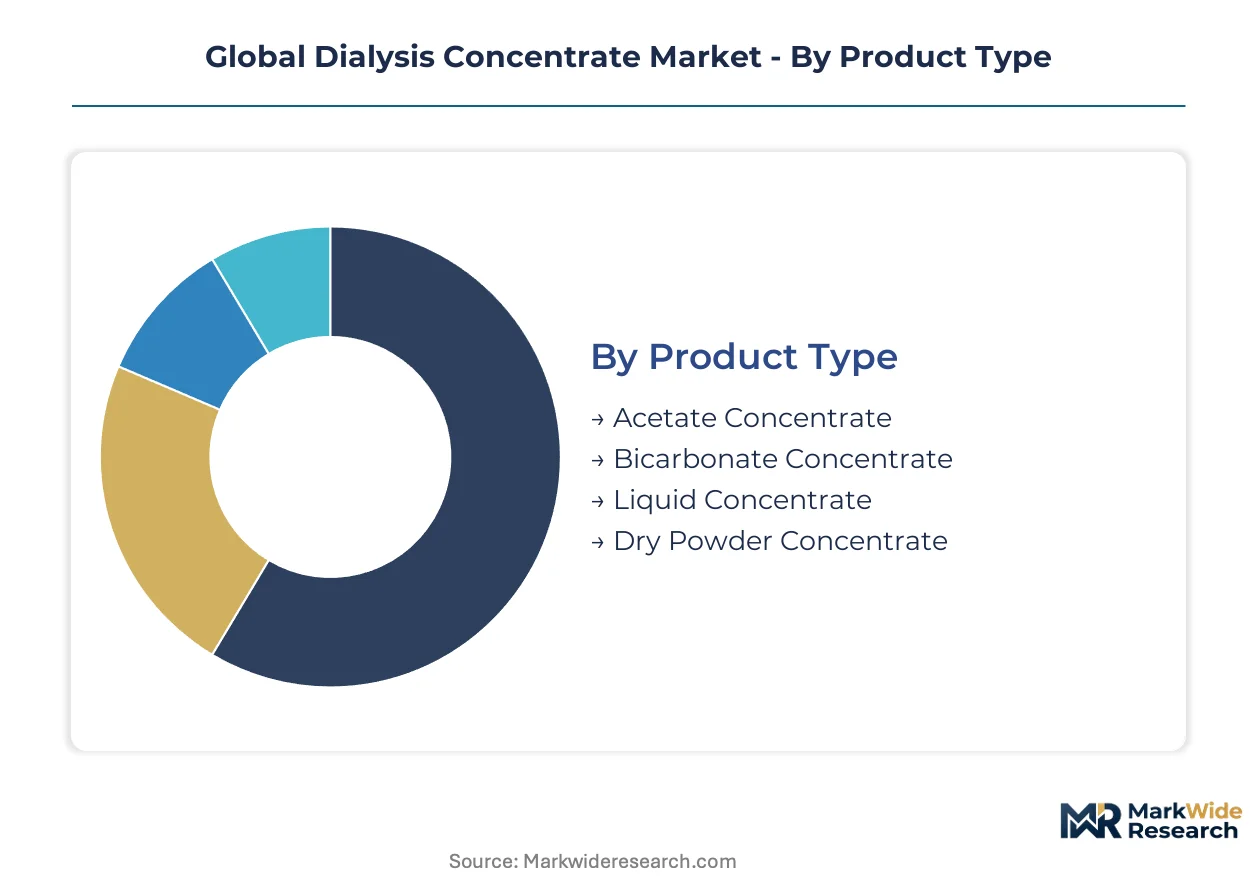
Dialysis concentrate procurement splits across incompatible chemistry platforms, delivery formats, and care settings. Manufacturers must configure production lines for these divergent specifications while navigating regulatory validation cycles that lock in format decisions for years.
Product Type:
Bicarbonate formulations command premium positioning in OECD markets where high-flux protocols dominate treatment protocols.
- Acetate Concentrate:Simpler storage requirements suit infrastructure-constrained settings. Demand persists in select emerging markets where cold-chain gaps and capital scarcity favor acetate's hemodynamic trade-offs over bicarbonate's logistical burdens.
- Bicarbonate Concentrate:Compatibility with modern high-efficiency dialyzers defines current clinical standards. Procurement concentrates in Medicare-reimbursed United States settings where enhanced clearance protocols justify chemistry premiums.
- Liquid Concentrate:Pre-mixed solutions dominate legacy clinic infrastructure with refrigerated storage capacity.
- Dry Powder Concentrate:Ambient-stable formats eliminate cold-chain dependency and extend shelf stability from months to years.
Bicarbonate concentrate holds installed capacity. Dry powder concentrate is rotating up the share rankings.
Application:
Volume distribution tracks epidemiology shifts toward outpatient management and home-based protocols.
- Chronic Kidney Failure:Sustained dialysis dependency creates recurring concentrate demand. Treatment concentrates in United States clinic networks where aging demographics and diabetes prevalence expand addressable populations.
- End-Stage Renal Disease:Irreversible renal function loss demands permanent dialysis infrastructure. Procurement volumes concentrate in Germany, Japan, and the United States where reimbursement frameworks sustain long-term treatment access.
- Acute Renal Failure:Temporary dialysis support in hospital intensive care settings.
- Peritoneal Dialysis:Home-based protocols require specialized concentrate formulations distinct from hemodialysis chemistry.
Chronic kidney failure holds installed capacity. Peritoneal dialysis is rotating up the share rankings.
End User:
Procurement authority is fragmenting as payors unbundle concentrate purchasing from equipment service contracts.
- Dialysis Clinics:Freestanding treatment centers generate bulk concentrate demand. Large United States operators are consolidating supplier rosters from regional blenders to national distributors with validated logistics networks.
- Home Healthcare Settings:Residential dialysis protocols require portable concentrate formats. United States Medicare reimbursement shifts are accelerating patient discharge from hospital-based centers to residential settings.
- Renal Care Hospitals:Inpatient departments maintain captive concentrate stocks for acute interventions.
- Specialty Treatment Centers:Niche providers serving complex comorbidity populations.
Dialysis clinics hold installed capacity. Home healthcare settings is climbing the fastest.
Packaging Type:
Container selection trades off sterilization validation costs against logistics efficiency and shelf stability requirements.
- Flexible Pouches:Lightweight formats reduce transport costs and storage footprint. Adoption concentrates in European clinic networks where Germany's centralized production hubs feed cross-border distribution chains.
- Bulk Bags:Industrial-scale packaging serves high-volume clinic operators with on-site reconstitution systems. Demand is expanding in Brazilian and Indian markets where cold-chain infrastructure gaps favor ambient-stable powder formats.
- Plastic Containers:Standard liquid concentrate packaging with established sterilization protocols.
- Glass Bottles:Premium barrier properties for sensitive formulations with limited adoption.
Plastic containers hold installed capacity. Bulk bags is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large dialysis organizations in the United States dominate procurement volumes, while German production hubs feed cross-border clinic networks. Japan's PMDA maintains distinct pharmacopeial standards that shape Asia-Pacific concentrate formulation requirements.
United States
Medicare reimbursement shifts accelerate patient discharge to residential dialysis settings, expanding demand for portable concentrate formats. The FDA enforces 21 CFR Part 876 device regulations with endotoxin limits below 0.5 EU/mL. Large operators in Texas and Florida consolidate supplier rosters from regional blenders to national distributors with validated logistics networks.
Germany
Centralized production hubs in Baden-Württemberg and Bavaria feed clinic networks across France, Italy, and Spain with cross-border concentrate distribution. The EU F-Gas Regulation phases down hydrofluorocarbon use in medical refrigeration, forcing format conversion toward ambient-stable powder systems. Berlin-based clinic operators accelerate dry powder adoption ahead of 2027 restriction deadlines.
Japan
Aging demographics and diabetes prevalence sustain long-term treatment access for end-stage renal disease populations. The PMDA maintains distinct pharmacopeial standards for electrolyte additive purity that create separate compliance thresholds. Osaka and Nagoya medical device clusters concentrate dialysis equipment manufacturing alongside concentrate formulation facilities.
Brazil
Infrastructure gaps and cold-chain limitations favor acetate concentrate persistence despite hemodynamic trade-offs. ANVISA oversees medical device registration and quality standards for imported concentrate products. São Paulo clinic chains deploy on-site reconstitution systems with dry powder concentrate to bypass refrigerated transport requirements.
India
Expanding clinic networks in Maharashtra and Gujarat drive procurement volume for cost-efficient concentrate formats. CDSCO regulates medical device imports and domestic manufacturing quality standards. Mumbai-based dialysis providers source from both international suppliers and emerging domestic compounders seeking pharmaceutical-grade certification.
Global Dialysis Concentrate Market Competitive Landscape
Player mix skews toward integrated healthcare conglomerates with captive clinic networks and specialized chemical manufacturers with pharmaceutical-grade compounding capabilities. The market structure concentrates around three to five dominant suppliers controlling bulk procurement relationships with large dialysis organizations. Strategic archetypes include vertically integrated clinic-to-manufacturing operators, standalone concentrate blenders with regional logistics specialization, and diversified medical device suppliers extending into dialysis fluids. Competitive moves center on format conversion investments from liquid to powder production lines and consolidation of distribution partnerships with national clinic chains.
Among integrated healthcare conglomerates, Fresenius Medical Care and Baxter International exemplify the clinic-captive archetype with manufacturing footprints spanning multiple continents. B. Braun Melsungen occupies a position within the European supply concentration, anchoring centralized production that feeds cross-border distribution networks. These three entities represent the dominant tier where procurement consolidation and regulatory validation capabilities create defensive positioning against mid-size regional blenders.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Rockwell Medical |
| Nipro Corporation |
| Nikkiso |
| Asahi Kasei Medical |
| Dialife Group |
| Farmasol |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with take-or-pay clauses lock in concentrate supply access for United States dialysis clinic networks while anchoring price visibility against pharmaceutical-grade sodium chloride spot volatility. These contracts bundle liquid and powder format commitments across 36-month renewal cycles, tying procurement costs to AAMI RD52 compliance validation timelines.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade electrolyte indexation dominate concentrate procurement between German manufacturers and European clinic networks. Pricing stratifies across premium, standard, and economy tiers based on FDA endotoxin certification grade and volume scale commitments. Cost compression in standard-tier liquid formats is intensifying because Brazilian and Indian clinic chains are converting to dry powder reconstitution systems. Large dialysis organizations in the United States exhibit lowest price sensitivity due to Medicare reimbursement pass-through mechanics, while independent regional clinics in Maharashtra and Gujarat face acute margin pressure from cold-chain logistics add-ons.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes are elevating landed costs for Japanese PMDA-certified electrolyte additives. Manufacturing concentrates in Germany, the United States, and Japan, with raw material dependencies on pharmaceutical-grade sodium chloride from India, potassium chloride from Chilean fertilizer operations, and magnesium sulfate from Chinese chemical processors. Single-source vulnerability runs through Baden-Württemberg production hubs feeding cross-border distribution to France, Italy, and Spain. Distribution runs through national distributors with validated ambient or cold-chain networks rather than direct manufacturer-to-clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story anchored in regulatory entrenchment: FDA 21 CFR Part 876 and EMA MDR validation timelines create 18-24 month switching costs that protect incumbent positioning.
For Market Incumbents: Secure backward integration into pharmaceutical-grade electrolyte compounding to defend against margin pressure from raw material volatility. Lock in captive demand through multi-format equipment lease bundles that tie clinic operators to proprietary concentrate cartridges. The threat of dry powder format displacement by regional blenders in Brazil and India demands accelerated powder production line conversion in Baden-Württemberg and Bavaria facilities. For New Entrants and Emerging Players: Differentiate on peritoneal dialysis concentrate formulations for home healthcare settings, the most penetrable segment given Medicare reimbursement shifts accelerating residential dialysis adoption. Target Maharashtra and Gujarat clinic networks with on-site reconstitution systems that bypass established cold-chain infrastructure. A go-to-market angle anchored in ANVISA pre-certification for acetate-to-bicarbonate conversion protocols opens Brazilian market access ahead of incumbent format refresh cycles. For Investors and Strategic Acquirers: Capital is best deployed toward mid-size regional blenders with pharmaceutical-grade certification and established GPO contracts in secondary United States markets. Long-term viability across a 5-10 year window favors suppliers with dual-format liquid-powder production flexibility as EU F-Gas restrictions phase down refrigeration-dependent packaging. The signal to watch is consolidation velocity among United States dialysis clinic networks unbundling concentrate procurement from equipment service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Powder Format Conversion | Enables clinic operators to bypass cold-chain infrastructure gaps in Brazil and India. |
| FDA 21 CFR Part 876 Compliance Investment | Validates endotoxin limits below 0.5 EU/mL for Medicare-reimbursed United States networks. |
| Peritoneal Dialysis Formulation Development | Captures home healthcare migration driven by United States payor reimbursement restructuring. |
| EU F-Gas Regulation Adaptation | Reformulates liquid concentrates or abandons temperature-dependent packaging ahead of 2027 deadlines. |
| Hospital System Partnership | Locks in captive demand through direct concentrate supply contracts with renal care departments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dialysis clinic procurement managers, GPO contracts administrators, biomedical engineers, and concentrate manufacturing plant directors; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and trade flow data for pharmaceutical-grade electrolytes. Bottom-up volume estimates from clinic network concentrate consumption rates were triangulated against top-down manufacturer capacity disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application, end user, and packaging format, with additional segmentation by regional regulatory cluster. CAGRs were derived from trend extrapolation of Medicare reimbursement shifts, EU F-Gas implementation timelines, and dry powder adoption curves in OECD clinic networks. Industry-specific inputs included AAMI RD52 validation cycle durations and PMDA pharmacopeial purity threshold compliance costs.
Material uncertainties — raw material price volatility, regulatory guidance evolution on peracetic acid sterilization residues, and clinic network consolidation velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement stability and format conversion adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Medical Gas Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Asia-Pacific Insulin Syringe Market