
 Contact Cast Systems Market | 2026-2036
Contact Cast Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Cast Systems Market Analytics
Medical-grade composite specifications are reorganizing procurement priorities across the contact cast systems value chain. Essity leverages its European manufacturing footprint to sustain supply security for fiberglass-based platforms. Integra LifeSciences differentiates through R&D intensity in thermoplastic formulations. Hollister Incorporated anchors North American distribution through specialized hospital contracts.
Contact cast systems are orthopedic immobilization devices manufactured from fiberglass, plaster, thermoplastics, or composite substrates, engineered to specific rigidity grades for fracture stabilization and soft tissue protection. The fabrication process involves resin-impregnated fabric layers molded to anatomical contours with cure times ranging from three to twenty minutes depending on material chemistry. Rigid product types occupy the largest installed base due to trauma protocol standardization, while functional variants represent the fastest-expanding margin pool as ambulatory surgery volumes rise. Home care end users are gaining share as payors push cost-bearing toward outpatient settings, though hospitals retain volume leadership in acute fracture management.
FDA biocompatibility standards and ISO 10993 testing protocols govern material approval pathways, with EPA oversight extending to resin chemical emissions during manufacturing. The EU Medical Device Regulation imposes additional clinical evidence requirements on thermoplastic innovators seeking CE marking. Stakeholders must monitor evolving reimbursement codes for functional cast systems as payors recalibrate coverage between inpatient and outpatient settings.
Market Dynamics
FDA biocompatibility scrutiny is compressing approval timelines for thermoplastic formulations while orthopedic trauma protocols in Germany and the United States drive specification divergence between rigid and functional cast categories.
Growth Catalysts
- EU Medical Device Regulation:Clinical evidence requirements for CE marking are elevating thermoplastic innovators above commodity fiberglass suppliers in European rehabilitation centers.
- Ambulatory surgery expansion:Rising outpatient fracture management volumes in US hospital networks are accelerating functional cast system procurement for same-day discharge protocols.
- Home care migration:Payor cost-bearing shifts toward outpatient settings are expanding addressable demand for patient-applied immobilization solutions.
Market Restraints
- Resin input volatility:Epoxy and polyurethane precursor costs fluctuate with petrochemical feedstock markets, squeezing margin stability for composite fabricators.
- German supply concentration:Advanced rehabilitation center demand clusters in Bavaria and North Rhine-Westphalia, creating geographic dependency risk for pan-European distributors.
- Plaster substitution ceiling:Developing-market cost constraints preserve gypsum-based casting in price-sensitive acute care, limiting composite penetration in trauma volume.
Strategic Opportunities
- Indian orthopedic expansion:CDSCO streamlined medical device registration is opening private hospital procurement channels for fiberglass platform suppliers.
- Pediatric functional segmentation:Anatomically adaptive thermoplastic designs address unmet need in ambulatory pediatric fracture management.
- Digital workflow integration:3D scanning and automated cutting convergence is enabling custom-contour fabrication at point-of-care in US orthopedic clinics.
Industry Challenges
- ISO 10993 testing backlog:Biocompatibility validation queues at notified bodies extend product launch timelines for novel resin chemistries.
- Legacy EHR integration:Cast system inventory management requires middleware development for hospital supply chain software compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Cast Systems Market |
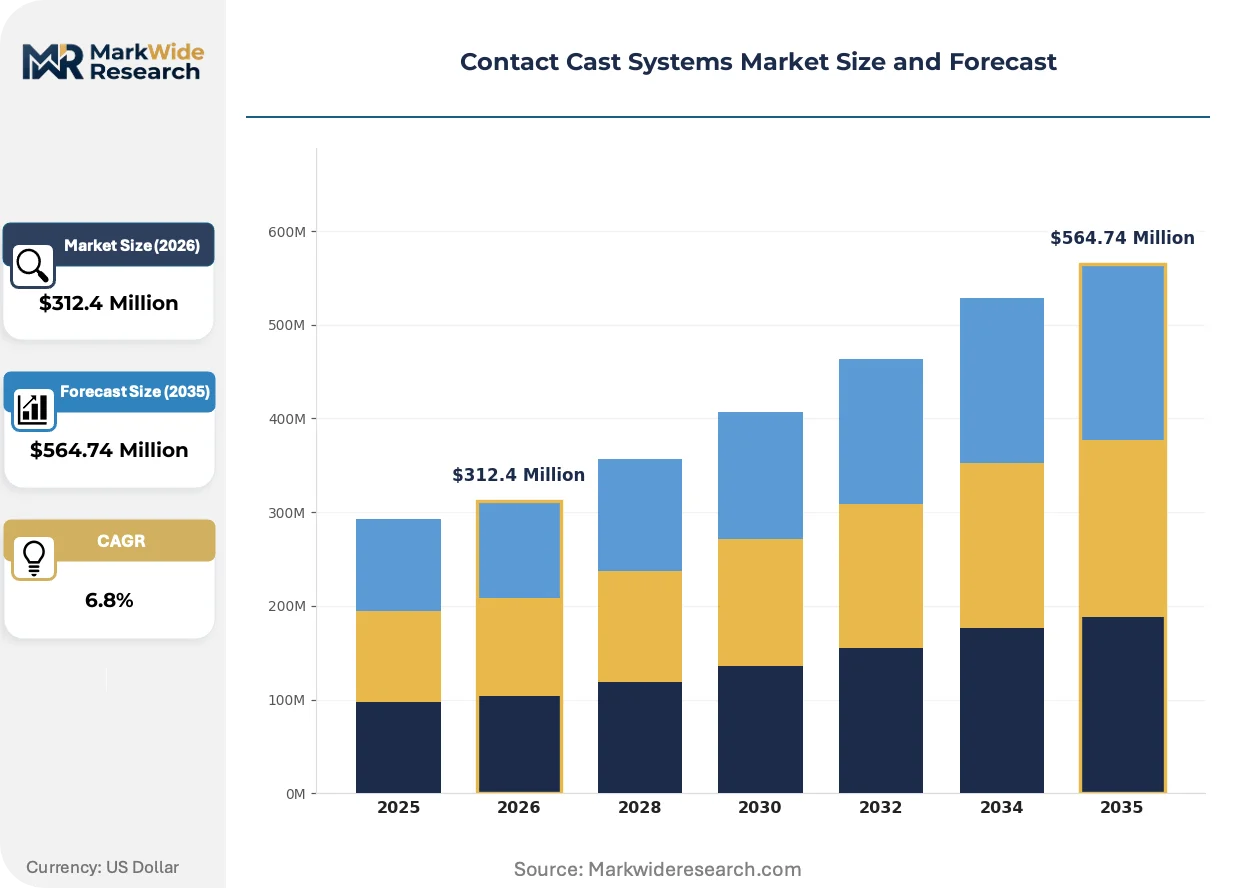
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Arm, Long Arm, Rigid, Functional End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Indication: Fractures, Soft Tissue Injuries, Post-Operative Care, Sports Injuries Material: Fiberglass, Plaster, Thermoplastics, Composite |
| Companies Covered | Essity, Integra LifeSciences, WoundKair Concepts, Derma Sciences, DARCO International, Hollister Incorporated, BSN medical, DM Systems, DeRoyal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Cast Systems Market Evolving Landscape
Material science advances and regulatory recalibration are fragmenting the traditional fiberglass-dominated installed base into specialized performance tiers.
Thermoplastic formulations with adjustable rigidity grades are bifurcating the trauma care market. Pediatric orthopedic departments in US academic medical centers are adopting these platforms for serial remolding without cast replacement. The technology is bifurcating procurement specifications between acute stabilization and subacute rehabilitation phases.
REACH chemical authorization requirements are restricting certain phthalate plasticizers in European-manufactured resin systems. Compounders must reformulate additive packages to maintain CE marking validity under evolving SVHC candidate list expansions. Thermoplastic innovators with pre-validated alternative chemistries are capturing specification share from incumbent fiberglass suppliers.
Hospital supply chain consolidation is compressing vendor panels for orthopedic consumables. Integrated delivery networks in the United States are mandating single-source contracts for cast materials across affiliated ambulatory surgery centers. Germany's rehabilitation center sector exhibits parallel concentration, with purchasing cooperatives standardizing on two-supplier frameworks.
Contact Cast Systems Market Segmentation
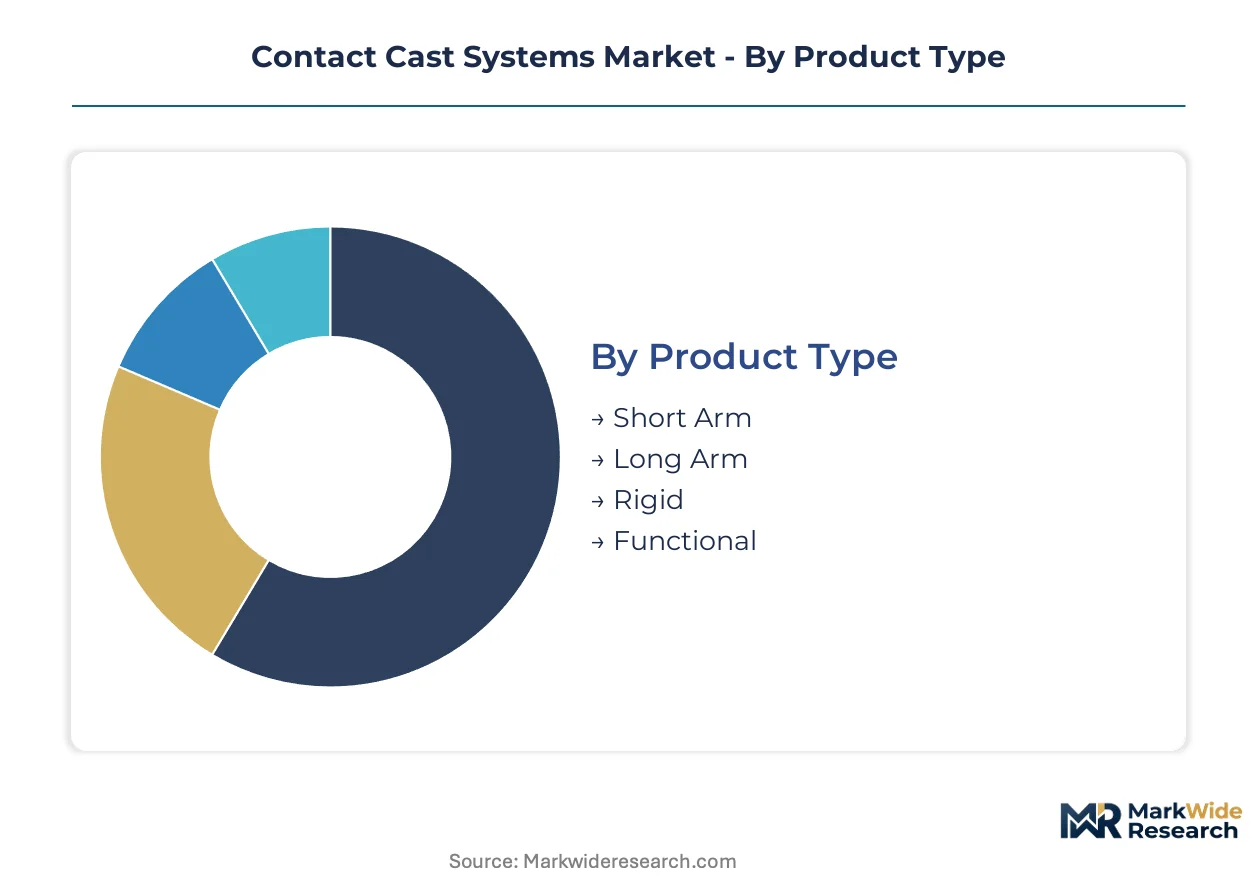
Contact cast systems fragment across four distinct classification axes, each carrying specific reimbursement and regulatory implications. Product type and material composition drive FDA and EU MDR pathway complexity, while end-user channel determines procurement contract structures.
Product Type:
FDA 510(k) clearance requirements diverge sharply between rigid immobilization platforms and adjustable functional systems, with the latter demanding extended biocompatibility validation under ISO 10993-5 and ISO 10993-10 protocols.
- Rigid:Conventional fiberglass-resin laminates deliver maximum stabilization for acute trauma protocols. German rehabilitation centers and US Level I trauma centers standardize procurement on these platforms for complex fracture management, though thermoplastic substitution is eroding share in subacute phases.
- Functional:Hinged or removable designs permit range-of-motion therapy during healing. Outpatient surgery networks in Texas and Florida are accelerating adoption for same-day discharge protocols, with pediatric orthopedic departments leading specification change.
- Short Arm:Distal radius and wrist fracture applications dominate hospital formularies.
- Long Arm:Elbow and proximal forearm stabilization retains plaster legacy share in cost-constrained settings.
Established volume favors Rigid; emerging adoption favors Functional.
End User:
Procurement concentration varies by care setting, with integrated delivery networks consolidating vendor panels while home care channels fragment across durable medical equipment distributors.
- Hospitals:Acute care facilities anchor composite material demand through trauma protocol standardization. Bavarian university hospitals and US academic medical centers specify medical-grade fiberglass with documented cure-time consistency for emergency department throughput.
- Home Care:Patient-applied immobilization solutions bypass clinical application labor costs. Medicare Advantage plans in Arizona and Pennsylvania are expanding prior authorization coverage for pre-cut splint kits delivered through DME channels.
- Clinics:Orthopedic urgent care settings prioritize rapid-application thermoplastic platforms.
- Rehabilitation Centers:German post-acute facilities in North Rhine-Westphalia drive functional cast specifications for mobilization protocols.
Volume leadership remains with Hospitals; Home Care exhibits steepest expansion trajectory.
Indication:
Clinical evidence requirements for reimbursement coding vary by injury category, with post-operative care commanding distinct procedural billing codes from trauma-managed fractures.
- Fractures:Diaphyseal and articular breaks require rigid stabilization through union confirmation. US orthopedic trauma associations publish algorithm-driven casting protocols that specify material rigidity by fracture pattern, concentrating demand in academic hospital networks.
- Sports Injuries:Ligamentous damage and stress fractures in athletic populations favor removable functional designs. Collegiate sports medicine programs in California and North Carolina are piloting thermoplastic platforms for serial imaging access without cast removal.
- Soft Tissue Injuries:Tendon and ligament protection drives splint procurement in hand surgery practices.
- Post-Operative Care:Surgical fixation protection commands premium material specifications in arthroplasty recovery protocols.
Trauma volume concentrates in Fractures; Sports Injuries gain specification share fastest.
Material:
REACH SVHC restrictions and FDA biocompatibility scrutiny are compressing approved resin chemistries, advantaging compounders with pre-validated alternative formulations.
- Fiberglass:Resin-impregnated glass fiber fabric dominates installed base through cost-performance balance. Essity's European manufacturing footprint supplies German rehabilitation cooperatives with REACH-compliant epoxy formulations exempt from recent phthalate restrictions.
- Thermoplastics:Moldable polymers enable remolding and radiolucency without cast replacement. Integra LifeSciences has secured CE marking under EU MDR Article 10 clinical evidence requirements, positioning ahead of fiberglass suppliers in premium European procurement.
- Plaster:Gypsum-based casting retains developing-market acute care share.
- Composite:Hybrid fiber-resin systems target performance-tier differentiation in specialized hand surgery.
Installed base concentration favors Fiberglass; Thermoplastics climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German rehabilitation centers absorb premium thermoplastic pricing, while Indian private hospitals prioritize cost-efficient fiberglass platforms. US integrated delivery networks negotiate single-source contracts that compress vendor margins regardless of material tier.
United States
Texas and Florida outpatient surgery networks are accelerating functional cast procurement for same-day discharge protocols. FDA biocompatibility scrutiny under ISO 10993-5 extends approval timelines for novel resin chemistries. Arizona and Pennsylvania Medicare Advantage plans are expanding prior authorization coverage for patient-applied splint kits through durable medical equipment channels.
Germany
Bavarian university hospitals specify medical-grade fiberglass with documented cure-time consistency for emergency department throughput. EU Medical Device Regulation clinical evidence requirements for CE marking elevate thermoplastic innovators above commodity suppliers. North Rhine-Westphalia post-acute facilities drive functional cast specifications for mobilization protocols through purchasing cooperatives.
India
Private hospital procurement channels in Maharashtra and Karnataka are opening to fiberglass platform suppliers following CDSCO streamlined medical device registration. The national pharmaceutical regulator has reduced documentation burdens for Class A and B orthopedic devices. Delhi-NCR and Tamil Nadu orthopedic centers are piloting thermoplastic platforms for pediatric ambulatory care.
Japan
Kanto region academic medical centers standardize on rigid immobilization platforms for trauma protocol consistency. PMDA biocompatibility validation aligns with ISO 10993 testing protocols, creating parallel approval pathways with European regulators. Osaka-based purchasing cooperatives are consolidating vendor panels for cast materials across affiliated orthopedic clinics.
United Kingdom
NHS supply chain consolidation is compressing vendor panels for orthopedic consumables into two-supplier frameworks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UKCA marking timelines. London and Southeast England integrated care systems are mandating single-source contracts for ambulatory surgery center networks.
Contact Cast Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across material tiers. The installed base concentrates around resin-impregnated fabric specialists with European manufacturing footprints, while thermoplastic innovators capture specification share in premium rehabilitation channels. Three archetypes dominate: integrated hygiene conglomerates with orthopedic divisions, pure-play wound care specialists, and diversified medical device manufacturers with trauma portfolios. Capacity expansion in REACH-compliant epoxy formulations and strategic partnerships for digital workflow integration represent the dominant competitive moves.
Among European fabricators, Essity AB and BSN medical exemplify scale-driven supply security archetypes, leveraging continental manufacturing networks to serve German purchasing cooperatives. Integra LifeSciences Corporation occupies a position within the R&D-intensive tier, representing thermoplastic innovators that have secured EU MDR Article 10 clinical evidence positioning. Hollister Incorporated anchors the North American distribution-focused archetype, sitting within the specialized hospital contract segment that dominates US procurement concentration.
| Leading Market Players |
|---|
| Essity |
| Integra LifeSciences |
| WoundKair Concepts |
| Derma Sciences |
| DARCO International |
| Hollister Incorporated |
| BSN medical |
| DM Systems |
| DeRoyal Industries |
| Others |
Value Network & Pricing Analysis
Three-to-five-day resin inventory buffers at European compounders compress margin recovery windows when epoxy feedstock costs spike, tethering pricing power to geographic proximity with REACH-compliant manufacturers and the procurement concentration of German purchasing cooperatives.
Pricing Analysis
After-sales service contracts for cast removal tools and remolding kits drive lifetime value capture beyond initial device sales. Three-tier pricing structure across premium thermoplastic, standard fiberglass, and economy plaster tiers separates procurement specifications by clinical setting complexity. FDA biocompatibility validation costs intensify price pressure at the premium tier as ISO 10993 testing queues extend. Hospital procurement committees exhibit highest price sensitivity, while German rehabilitation centers absorb premium positioning for functional mobilization protocols.
Supply Chain Analysis
Germany and the United States anchor medical-grade resin compounding and automated fabric impregnation lines. Belgium and the Netherlands supply specialized epoxy formulations. Raw material flows draw from Saudi petrochemical feedstocks, Chinese glass fiber production, and Belgian specialty additive manufacturing. Single-source vulnerability concentrates in REACH-compliant plasticizer alternatives following SVHC list expansions. Distribution runs through hospital purchasing cooperatives and durable medical equipment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks and rehabilitation purchasing cooperatives as procurement consolidation compresses vendor panels across US and European channels.
For Market Incumbents: Consolidate supply security through backward integration into REACH-compliant resin formulation capacity in Belgium or the Netherlands. Lock in multi-year contracts with Bavarian university hospital networks before thermoplastic substitution accelerates. Defend against functional cast entrants by embedding cure-time consistency guarantees into emergency department throughput protocols. For New Entrants and Emerging Players: CDSCO streamlined registration pathways for Class A and B orthopedic devices open Maharashtra and Karnataka private hospital procurement channels. Target pediatric ambulatory fracture management in Delhi-NCR with anatomically adaptive thermoplastic designs. Pursue GPO contracts with mid-tier US orthopedic urgent care chains lacking thermoplastic vendor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because thermoplastic innovators with validated EU MDR Article 10 positioning will absorb commodity fiberglass share as rehabilitation protocols bifurcate. Acquisition targets cluster around compounders with pre-validated alternative plasticizer chemistries. Watch ISO 10993 testing queue lengths at notified bodies as inflection signal for thermoplastic launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | Pre-validated alternative plasticizers secure CE marking continuity against SVHC list expansion. |
| Hospital System Partnership | Single-source contracts with Texas and Florida outpatient surgery networks lock in functional cast volume. |
| CDSCO Registration Fast-Track | Streamlined Class B orthopedic device pathways open Maharashtra private hospital procurement channels. |
| Digital Workflow Integration | 3D scanning and automated cutting convergence enables custom-contour fabrication at US orthopedic clinics. |
| Pediatric Functional Segmentation | Anatomically adaptive thermoplastic designs address unmet need in ambulatory pediatric fracture management. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and rehabilitation center purchasing directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU MDR Article 10 clinical evidence submissions, and hospital procurement database analysis. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type rigidity grade, material composition tier, end-user channel structure, and geographic regulatory cluster. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated ambulatory surgery volume shifts and payor reimbursement code evolution.
Underlying assumptions cover resin feedstock price stability and REACH authorization timelines, with deviation risk concentrated in ISO 10993 testing queue durations and EU MDR notified body capacity constraints. Recalibration cycles align with material shifts in regulatory authorization velocity and rehabilitation protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Biopsy Devices Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Hearing Aids Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Heated Humidifiers Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market