
 First Aid Kit Market | 2026-2036
First Aid Kit Market Size, Share, and Industry Trends Forecast 2026-2036
First Aid Kit Market Intelligence
Multi-source procurement for adhesive bandages, antiseptic wipes, and burn dressings is hardening as institutional buyers diversify supplier rosters to mitigate pandemic-era shortages. Johnson & Johnson leverages its consumer health infrastructure to sustain retail shelf presence across pharmacy chains. 3M Company anchors industrial channel dominance through direct corporate safety contracts. Medline Industries competes on hospital system procurement consolidation, offering private-label kit configurations at scale.
A first aid kit comprises a portable collection of medical supplies—including sterile gauze pads, adhesive strips, elastic wraps, antiseptic solutions, and single-use instruments—organized for immediate response to trauma, burns, or contamination incidents before professional medical intervention. Emergency kits lead product type demand due to regulatory mandates in commercial vehicles and industrial facilities, while sports kits represent the fastest-expanding category as youth athletics programs formalize concussion and fracture response protocols. Online retail channels capture margin pools through subscription replenishment models for corporate and household end users.
OSHA's workplace first aid standards, the FDA's medical device quality system regulations, and ISO 13485 certification requirements collectively shape product specifications and market access barriers for domestic and imported kits. The EPA's evolving antiseptic ingredient restrictions further constrain formulation choices for topical preparations included in standard configurations. Stakeholders must monitor pending state-level mandates for automated external defibrillator inclusion in commercial kits, as this would force component redesign and pricing recalibration across manufacturing lines.
Market Dynamics
OSHA workplace first aid standards and FDA medical device classification rules are compressing product development cycles while fragmenting supplier rosters as institutional buyers diversify away from pandemic-era single-source dependencies.
Growth Catalysts
- OSHA Compliance Audits:United States workplace safety mandates in construction and manufacturing sectors are accelerating replacement cycles for industrial-grade emergency kits.
- Youth Athletics Formalization:School districts and recreational leagues are mandating concussion and fracture response protocols, expanding sports kit procurement volumes.
- Subscription Replenishment Models:Corporate and household end users are adopting automated restocking for adhesive bandages, antiseptic wipes, and burn dressings through online retail channels.
Market Restraints
- EPA Antiseptic Ingredient Restrictions:Evolving limitations on topical preparation formulations are constraining standard kit configurations and forcing supplier reformulation investments.
- ISO 13485 Certification Barriers:Quality system requirements for medical device manufacturing are elevating compliance costs for imported kit assemblers seeking United States market access.
- Adhesive Raw Material Volatility:Petrochemical-derived backing materials and synthetic rubber adhesives are exposing margin structures to hydrocarbon price fluctuations.
Strategic Opportunities
- Automated External Defibrillator Inclusion:Pending state-level mandates for AED integration into commercial kits would force component redesign and create premium pricing tiers.
- Private-Label Hospital Consolidation:Health system procurement centralization is opening volume contracts for configurable kit assemblies tailored to emergency department specifications.
- Industrial Direct Safety Contracts:Corporate safety departments are bypassing distributors to negotiate direct sourcing agreements with manufacturers for facility-specific inventory.
Industry Challenges
- Multi-Source Supplier Coordination:Institutional buyers managing diversified rosters for gauze, instruments, and topical preparations face quality consistency verification across fragmented vendor bases.
- Regulatory Timeline Compression:FDA over-the-counter device reclassification proceedings are shortening registration pathways while demanding accelerated documentation submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | First Aid Kit Market |
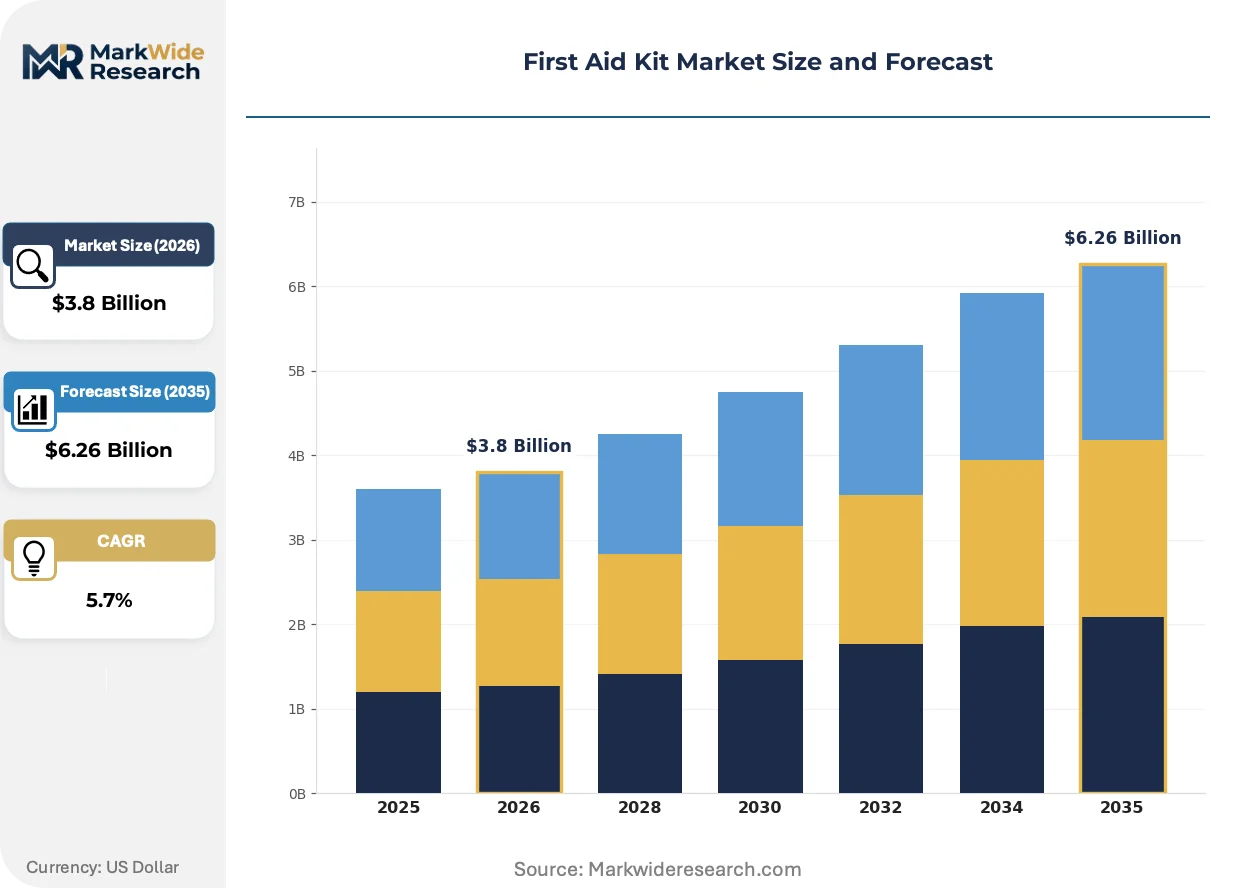
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Kits, Travel Kits, Sports Kits, Household Kits Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores End User: Individuals, Hospitals, Schools, Corporate Application: Workplace Safety, Outdoor Activities, Disaster Preparedness, Sports Injuries |
| Companies Covered | Honeywell International, Cintas Corporation, Johnson & Johnson, Certified Safety Manufacturing, First Aid Only, 3M Company, Acme United Corporation, St John Ambulance, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
First Aid Kit Market Strategic Shifts & Innovations
Smart inventory tracking and connected compliance monitoring are reshaping how organizations manage first aid readiness, shifting value capture from product sales toward assurance-based service relationships.
RFID-enabled kit management systems are integrating expiration date monitoring and automated reorder triggers into corporate safety software platforms. Large manufacturing facilities and logistics fleets are piloting these systems to reduce manual inspection labor. This technology is integrating compliance documentation directly into enterprise risk management dashboards, compressing audit preparation cycles.
Europe's MDR implementation is elevating clinical evidence requirements for sterile wound care products classified as medical devices. Manufacturers must now submit biocompatibility testing documentation previously exempt under legacy directives. Class IIa kit configurations containing sutures and invasive instruments face the steepest compliance cost increases, with smaller assemblers exiting the category.
Corporate safety departments are consolidating vendor relationships through integrated personal protective equipment and first aid procurement contracts. Industrial distributors are responding by bundling respiratory protection, eyewear, and emergency response kits into single-source agreements. This pattern is most visible in United States manufacturing regions where OSHA Voluntary Protection Program participants prioritize audit-ready documentation over unit cost minimization.
First Aid Kit Market Segmentation
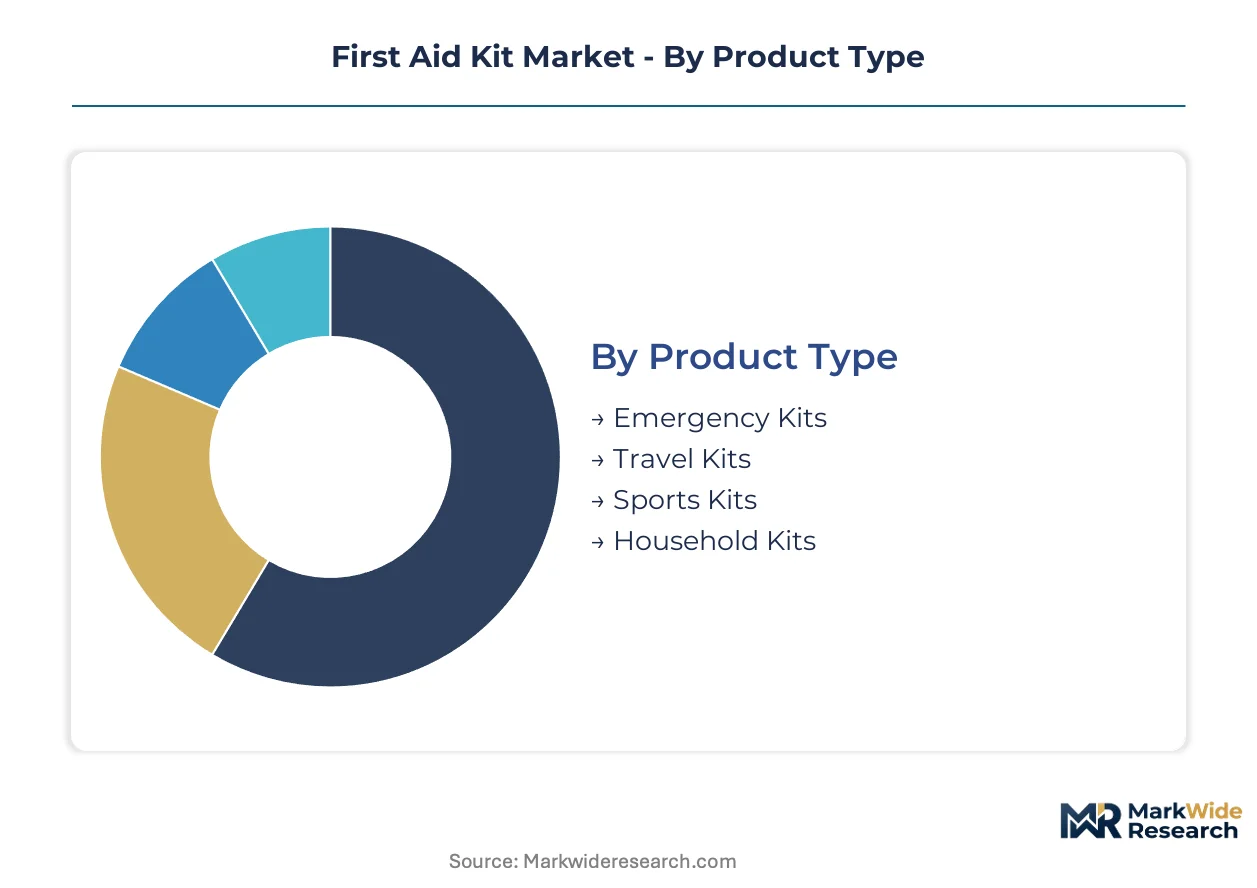
First aid kit procurement patterns diverge sharply across use contexts, with regulatory mandates driving standardization in industrial and institutional channels while consumer segments prioritize portability and retail accessibility. Manufacturers must configure component mixes, packaging formats, and compliance documentation to match the verification requirements of each distinct buyer category.
Product Type:
Supply concentration tilts toward emergency kit configurations as industrial procurement volumes dominate manufacturing line allocation.
- Emergency Kits:Comprehensive configurations containing sterile gauze, tourniquets, burn dressings, and resuscitation barriers for trauma response. OSHA-mandated commercial vehicle and industrial facility stocking in the United States sustains high-volume replacement cycles.
- Sports Kits:Compact assemblies with instant cold packs, elastic wraps, and fracture splints designed for field-side deployment. Youth athletics program formalization across school districts is accelerating procurement for concussion and musculoskeletal injury response.
- Travel Kits:Lightweight, TSA-compliant configurations with adhesive strips, antiseptic wipes, and blister care for individual mobility.
- Household Kits:General-purpose collections scaled for family size with burn gel, thermometer, and basic wound closure supplies.
Emergency kits absorb the bulk of installed capacity; sports kits are expanding most quickly.
Distribution Channel:
Cost tier stratification separates premium direct-contract industrial supply from price-sensitive retail replenishment.
- Online Retail:Subscription-based replenishment models with automated expiration tracking and bulk corporate purchasing portals. Corporate safety departments and household end users in the United States are migrating procurement to these channels for inventory visibility.
- Pharmacies:Immediate-need retail access with pharmacist consultation for component selection. Retail shelf presence here requires compliance with FDA over-the-counter device classification for topical preparations.
- Supermarkets:Impulse and seasonal purchasing for household kit replacement and travel preparation.
- Specialty Stores:Curated selections for outdoor recreation and extreme environment applications with specialized hypothermia and hydration components.
Online retail is capturing the steepest expansion trajectory as procurement digitizes; pharmacies retain the largest installed base.
End User:
Customer type determines specification rigor, with institutional buyers demanding ISO 13485 certification and audit-ready documentation.
- Corporate:Industrial safety departments negotiating direct manufacturer contracts for facility-specific configurations. OSHA Voluntary Protection Program participants in United States manufacturing regions prioritize compliance documentation over unit cost.
- Hospitals:Health system procurement consolidation driving private-label kit assemblies with emergency department-specific component mixes.
- Schools:District-level mandates for athletics and general campus safety with standardized concussion response protocols.
- Individuals:Price-sensitive retail purchasing with minimal regulatory overlay beyond basic FDA registration.
Corporate end users command the largest contract values; hospital consolidation is restructuring supplier relationships fastest.
Application:
Volume concentration aligns with regulatory enforcement intensity, creating procurement gravity in mandated workplace safety.
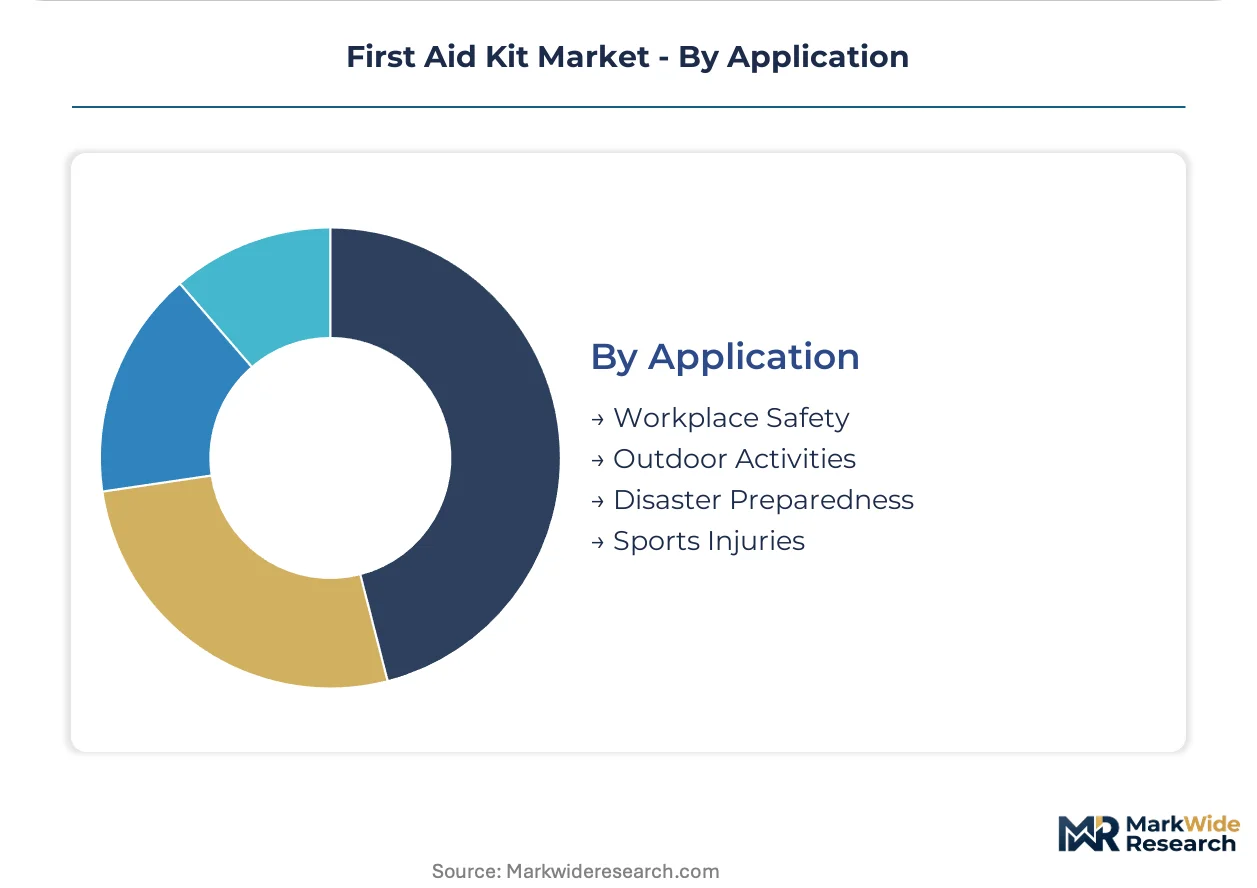
- Workplace Safety:Construction and manufacturing facility stocking with OSHA-compliant component minimums and inspection documentation. United States regulatory audits enforce replacement cycles and accessibility standards.
- Sports Injuries:Formalized response protocols for concussion, fracture, and soft tissue trauma in organized athletics. School district and recreational league mandates are standardizing kit contents across state-level athletic associations.
- Outdoor Activities:Wilderness and remote environment configurations with extended-care supplies for delayed evacuation scenarios.
- Disaster Preparedness:Multi-day autonomy kits for household and community shelter stocking with water purification and emergency communication components.
Workplace safety absorbs the bulk of institutional procurement; sports injury applications are climbing the fastest as youth program formalization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States workplace safety mandates concentrate procurement volumes, with OSHA compliance audits sustaining replacement cycles across construction and manufacturing sectors. Corporate liability frameworks and state-level automated external defibrillator proposals are reshaping kit specifications.
United States
Construction and manufacturing facility managers drive institutional procurement through OSHA Voluntary Protection Program requirements. The FDA's updated over-the-counter device classification rules compress product registration timelines for topical preparations. Industrial corridors in Ohio and Michigan host concentrated safety supply distribution serving automotive and heavy equipment manufacturers.
Germany
Industrial Mittelstand firms sustain demand for workplace emergency configurations with audit-ready documentation. The EU Medical Device Regulation elevates clinical evidence requirements for sterile wound care components. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia anchor procurement consolidation through employer liability insurance frameworks.
China
State-owned enterprise safety standardization campaigns expand kit deployment across construction and mining operations. The National Medical Products Administration tightens quality system oversight for imported device assemblies. Yangtze River Delta manufacturing hubs generate procurement scale through export-oriented industrial park safety mandates.
United Kingdom
Corporate health and safety compliance drives kit replacement in logistics and warehouse operations. The Health and Safety Executive maintains strict workplace first aid provision requirements with penalty enforcement. London and Southeast England concentrate financial services sector procurement for office-based emergency readiness.
Japan
Aging workforce demographics elevate workplace injury response preparedness in manufacturing and logistics. The Ministry of Economy, Trade and Industry promotes standardized safety equipment procurement through industrial association guidelines. Kanto region automotive and electronics manufacturers anchor premium kit demand with ISO 13485 certification requirements.
First Aid Kit Market Key Industry Players
Direct corporate safety contracting dominates the current landscape as industrial buyers bypass distributors for manufacturer relationships. The vendor base separates into three tiers: diversified conglomerates with consumer health infrastructure, industrial safety specialists with channel integration capabilities, and private-label assemblers serving health system consolidation. Strategic archetypes include compliance-focused documentation providers, scale-driven component integrators, and subscription-enabled replenishment platforms. Capacity expansion in automated kit assembly and geographic licensing partnerships represent the dominant competitive moves.
Among diversified health and safety conglomerates, Johnson & Johnson and 3M Company exemplify archetypes leveraging consumer and industrial channel infrastructure respectively. Medline Industries occupies a position within the private-label health system tier. These entities anchor competitive positioning through distinct channel access models rather than product differentiation alone.
| Leading Market Players |
|---|
| Honeywell International |
| Cintas Corporation |
| Johnson & Johnson |
| Certified Safety Manufacturing |
| First Aid Only |
| 3M Company |
| Acme United Corporation |
| St John Ambulance |
| Medline Industries |
| Others |
Cost & Logistics Intelligence
Captive supply of sterile gauze and adhesive components anchors margin control for domestic manufacturers while exposing importers to tariff-adjusted cost structures. ISO 13485-certified assemblers in the United States leverage backward integration into medical-grade packaging to defend premium positioning against private-label competitors sourcing from fragmented Asian component markets.
Pricing Analysis
Service bundling separates audit-ready documentation packages from bare-product transactions, with OSHA Voluntary Protection Program participants paying compliance premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and replenishment automation. Cost compression in economy tiers intensifies because petrochemical-derived adhesive inputs track hydrocarbon volatility. Household retail channels exhibit highest price sensitivity; hospital GPO contracts show lowest.
Supply Chain Analysis
Certification gating funnels component sourcing through FDA-registered and ISO 13485-qualified facilities in the United States, Germany, and China. Supply chains draw from synthetic rubber adhesive producers, medical-grade nonwoven textile mills, and sterilization service providers. Single-source vulnerability concentrates in gamma sterilization capacity for pre-packaged wound care items. Distribution runs through industrial safety distributors, hospital GPOs, and direct manufacturer contracts to corporate safety departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First aid kit procurement operates as a cost-of-compliance market where FDA over-the-counter device reclassification erects registration barriers that favor incumbent documentation capabilities.
For Market Incumbents: To counter private-label erosion in hospital consolidation, deepen ISO 13485 audit infrastructure and secure direct corporate safety contracts bypassing distributor markups. Expand captive sterilization capacity to reduce single-source dependency in gamma treatment services. For New Entrants and Emerging Players: Capture sports kit white space in school district RFPs by targeting concussion-protocol compliance as the entry wedge. Lead with subscription replenishment platforms for youth athletics leagues lacking inventory management systems, then ladder into institutional contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified health and safety conglomerates seeking OSHA compliance service bundling. Five-to-ten year viability hinges on automated external defibrillator integration mandates spreading across state legislatures. Watch California and New York legislative dockets for AED inclusion triggers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks hospital GPO access and FDA registration pathways for sterile device configurations. |
| Direct Corporate Safety Contracting | Bypasses industrial distributor margins while capturing OSHA Voluntary Protection Program audit demand. |
| Subscription Replenishment Platform | Automates expiration tracking for corporate safety departments and household end users. |
| AED Integration Engineering | Positions for pending state mandates requiring defibrillator inclusion in commercial kit configurations. |
| RFID-Enabled Inventory Tracking | Integrates kit compliance data into enterprise risk management dashboards for manufacturing facilities. |
Research Approach
Multi-period observation of OSHA audit enforcement patterns, FDA registration timelines, and hospital GPO contract awards anchored the trend analysis, supplemented by interviews with corporate safety directors, hospital procurement managers, biomedical engineers, and industrial distributor account executives. Secondary validation drew from FDA 510(k) filings, OSHA inspection databases, hospital supply chain disclosures, and customs import records. Bottom-up component demand modeling and top-down institutional procurement surveys were triangulated.
Input-output matrices mapped sterile gauze, adhesive, and topical preparation volumes to end-use segments across the projection horizon. Modeled dimensions included product type, distribution channel, end user category, and application context. CAGRs were derived from regression analysis against regulatory enforcement intensity and procurement digitization indices. Forecast inputs incorporated youth athletics program formalization rates and state-level AED mandate propagation.
The model holds under stable FDA device classification rules and OSHA audit staffing levels; deviation in antiseptic ingredient restrictions or tariff structures on Chinese medical textiles would shift component cost assumptions and import penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Gloves Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global Syringe Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
South America Syringe Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Filter Needles Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Face Mask Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Empty IV Bags Market