
 Autoclaving Trays Market | 2026-2036
Autoclaving Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Autoclaving Trays Market Outlook
Consolidation among hospital networks into multi-facility integrated delivery networks is repositioning procurement power toward centralized sterile processing departments. Steris plc leverages its installed base of sterilization equipment to cross-sell proprietary tray configurations. Getinge Group anchors its position through comprehensive sterile workflow solutions spanning washers, sterilizers, and containment accessories.
Autoclaving trays are rigid containment devices engineered from stainless steel, aluminum, or medical-grade polymers to withstand saturated steam sterilization cycles at 121°C to 134°C while maintaining instrument organization and sterility barrier integrity. Stainless steel variants dominate installed bases due to durability and thermal conductivity, though silicone-lined configurations are gaining traction in ophthalmic and microsurgical sets where instrument tip protection is critical. Healthcare facilities represent the largest application segment by volume, while dental clinics and veterinary services are emerging as faster-growing channels as outpatient sterilization standards tighten.
FDA 510(k) clearance requirements for reusable medical device accessories, ISO 17665 steam sterilization validation standards, and EU MDR technical documentation obligations collectively elevate barrier-to-entry for non-validated tray suppliers. CE marking under the EU Medical Device Regulation now demands clinical evidence of sterility maintenance for tray-lid systems used in Class IIa and higher devices. Stakeholders must monitor evolving sterilization assurance level expectations as healthcare systems shift toward single-use-duplicating sterility claims for reusable containment systems.
Market Dynamics
Hospital network consolidation into integrated delivery networks is concentrating sterile processing procurement decisions at regional hub facilities, forcing tray suppliers to reconfigure distribution and service models around centralized sterilization infrastructure rather than individual facility relationships.
Growth Catalysts
- FDA 510(k) clearance pathways:Reusable medical device accessory regulations are elevating validated tray systems above commodity alternatives in US hospital purchasing criteria.
- Steam sterilization validation protocols:ISO 17665 compliance requirements are mandating traceable instrument containment across Western European central sterile supply departments.
- Silicone-lined configurations:Microsurgical instrument protection demands in ophthalmic suites are driving premium tray adoption in specialized surgical centers.
Market Restraints
- Medical-grade polymer input costs:Specialized high-temperature thermoplastics exhibit price volatility tied to petrochemical feedstock fluctuations and limited qualified resin suppliers.
- Stainless steel supply concentration:Surgical-grade 316L stainless sourcing clusters in specific metallurgical regions, creating geographic vulnerability in raw material security.
- EU MDR technical documentation:Clinical evidence requirements for Class IIa tray-lid systems extend regulatory timelines and compliance expenditures for market entry.
Strategic Opportunities
- Veterinary services channel:Companion animal surgical volume expansion and tightening outpatient sterilization standards are opening faster-growing demand outside traditional healthcare.
- Dental clinic sterilization mandates:Infection control protocol upgrades in oral surgery practices are creating instrument containment requirements previously concentrated in hospital settings.
- RFID-enabled traceability convergence:Integration of wireless identification with tray systems is enabling real-time sterile processing workflow optimization.
Industry Challenges
- Biocompatibility validation expertise:ISO 10993 testing protocols for polymer tray surfaces require specialized toxicology and materials science capabilities scarce among mid-tier manufacturers.
- Legacy sterilizer compatibility:Tray dimensional standards must accommodate installed bases of varying chamber geometries across multi-facility health systems, complicating standard product development.
- Steam penetration certification timelines:Biological indicator testing cycles for new tray designs extend product launch schedules and tie up R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoclaving Trays Market |
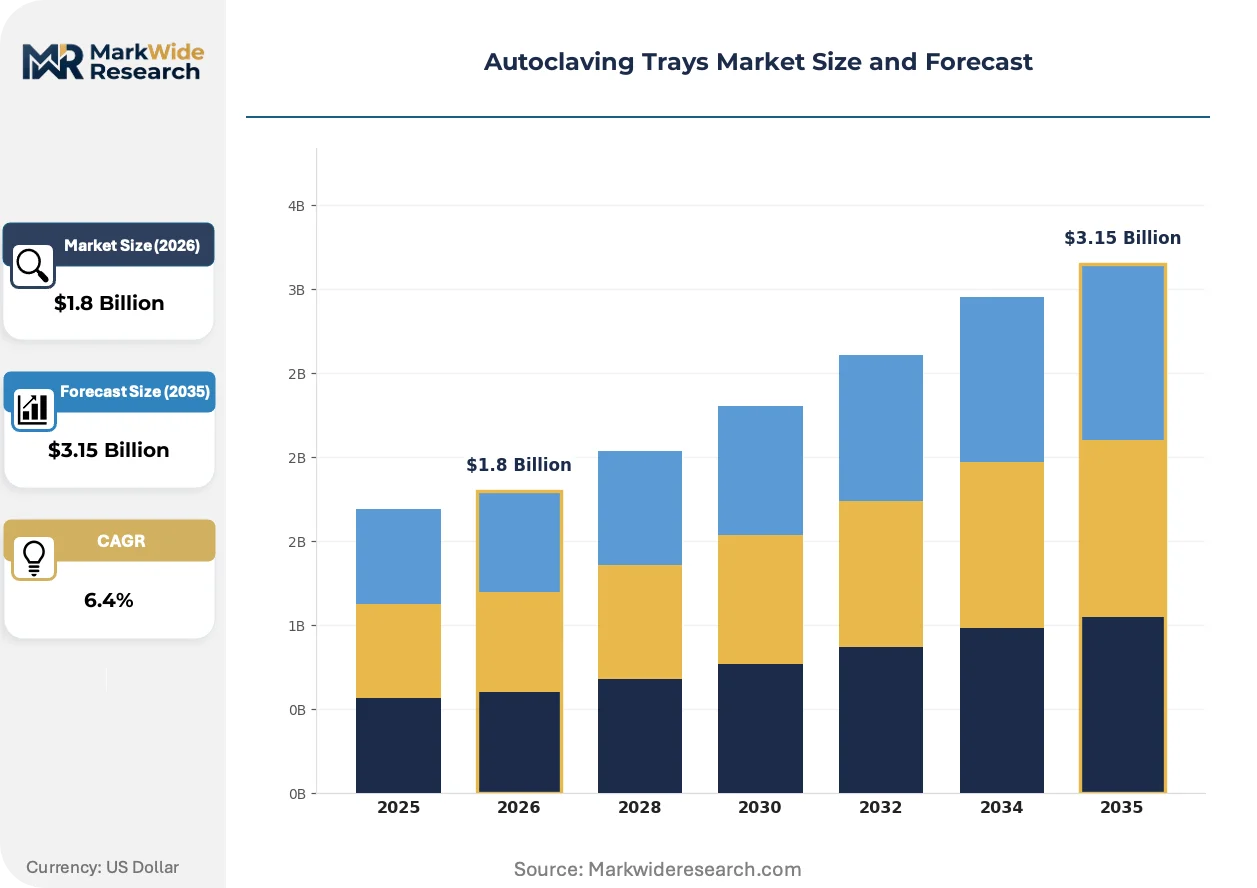
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Plastic, Silicone Application: Healthcare Facilities, Laboratories, Dental Clinics, Veterinary Services Size: Standard, Custom, Mini, Large Certification: ISO, FDA, CE, GMP |
| Companies Covered | Duraline Systems, Kirwan Surgical Products, Terumo Cardiovascular Systems Corporation, Thomas Scientific, InstruSafe, Steris plc, Getinge Group, Belimed AG, Tuttnauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoclaving Trays Market Strategic Shifts
Autoclaving tray development is pivoting from passive containment toward active traceability and instrument protection, with material science and digital integration converging to redefine value propositions in sterile processing workflows.
Polyetherimide and polyphenylsulfone formulations are displacing traditional metals in specific surgical sets by combining steam resistance with reduced instrument abrasion. Outpatient surgical centers in Germany and France are adopting these polymer configurations for high-turnover ophthalmic procedures. This material transition is decentralizing tray manufacturing from metalworking regions toward polymer injection molding clusters with medical device expertise.
EU MDR sterility maintenance documentation requirements are compressing supplier margins through expanded clinical evidence obligations. Tray-lid system manufacturers must now demonstrate performance across validated sterilization cycles rather than relying on material specifications alone. German notified bodies are enforcing the strictest interpretations, creating competitive differentiation for suppliers with established technical file capabilities.
Central sterile supply departments are unbundling tray procurement from sterilization equipment purchasing, reversing decades of bundled equipment-containment contracts. US integrated delivery networks now run competitive tenders for tray standardization across multiple facilities, displacing historical single-source relationships. This purchasing transformation is most advanced in Texas and California health systems with the largest multi-hospital footprints.
Autoclaving Trays Market Segmentation
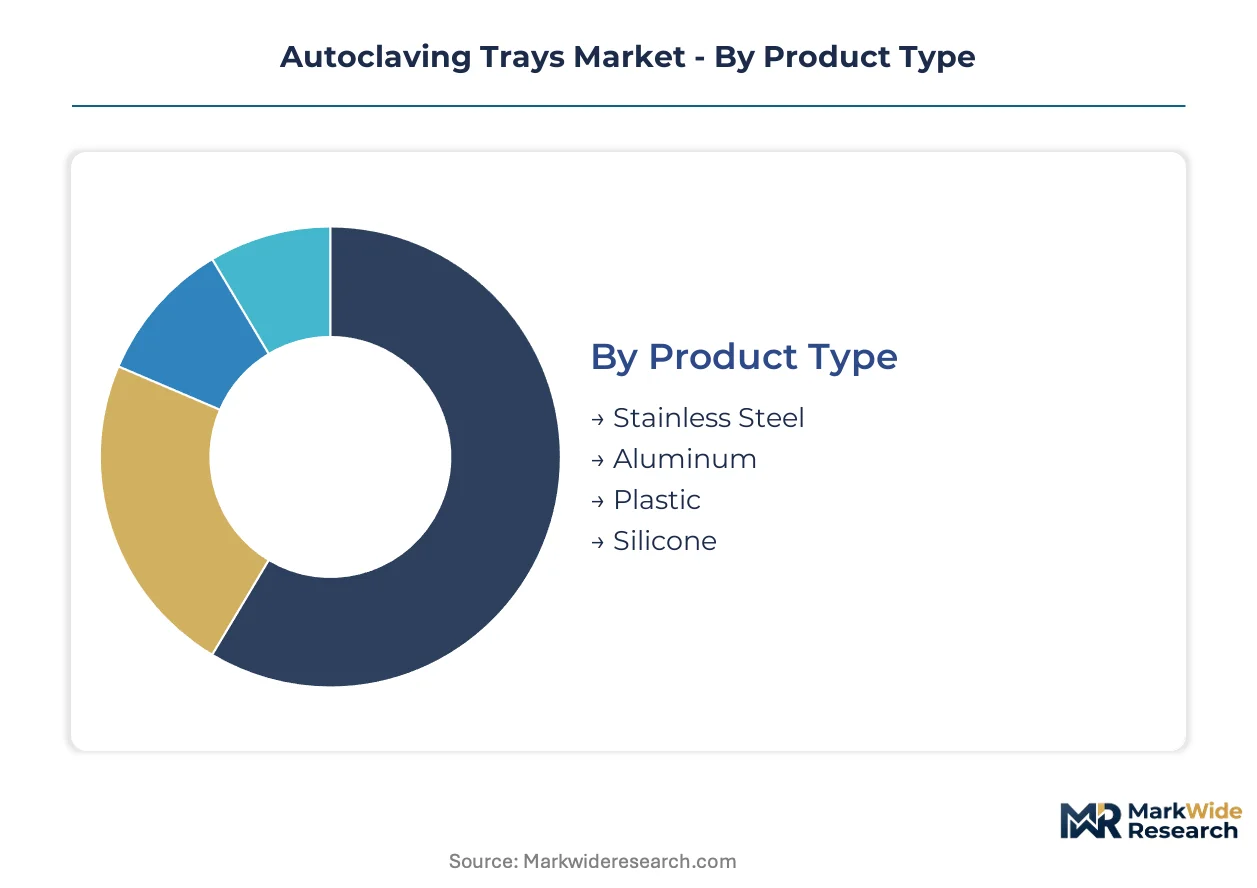
Tray specifications diverge sharply between embedded sterile processing workflows and standalone instrument sets. Procurement officers balance thermal performance, instrument protection, and regulatory compliance across four structural dimensions.
Product Type:
Stainless steel configurations anchor centralized sterile processing departments where durability and steam conductivity dominate specifications. Aluminum and polymer variants serve decentralized or specialized settings where weight reduction and instrument cushioning take priority.
- Stainless Steel:Surgical-grade 316L construction withstands saturated steam cycles at 134°C across thousands of reprocessing events. North American hospital networks specify these for high-turnover orthopedic and general surgery instrument sets where replacement costs must be minimized.
- Aluminum:Lightweight anodized formulations reduce handling strain in mobile sterilization units and field medical deployments. Demand clusters in military medical logistics and remote clinic networks across Germany and France where transport efficiency governs procurement.
- Plastic:High-temperature thermoplastics including polyetherimide and polyphenylsulfone offer steam resistance with reduced instrument abrasion.
- Silicone:Elastomer-lined configurations protect microsurgical instrument tips in ophthalmic and neurosurgical applications.
Volume placements concentrate in stainless steel configurations; the faster expansion belongs to silicone-lined specialty variants.
Application:
End-use requirements scale from high-volume central sterile supply departments to emerging outpatient channels where protocol standardization lags hospital benchmarks.
- Healthcare Facilities:Central sterile supply departments in acute care hospitals process thousands of trays daily through validated steam sterilization cycles. These installations demand FDA 510(k) cleared or CE marked systems with complete traceability documentation.
- Dental Clinics:Oral surgery practices in the United States and Western Europe are adopting hospital-grade containment as state dental boards tighten infection control mandates. California and Texas lead regulatory tightening.
- Laboratories:Research and diagnostic facilities require sterilization of glassware and media preparation equipment.
- Veterinary Services:Companion animal surgical volume is climbing fastest outside traditional healthcare channels.
Procurement scale peaks in healthcare facilities; dental clinics are gaining share fastest as outpatient standards converge with hospital protocols.
Size:
Dimensional specifications must accommodate legacy sterilizer chamber geometries while enabling standardization across multi-facility networks.
- Standard:Dimensions align with ISO tray standards for compatibility across sterilizer brands. These configurations dominate replacement purchasing in established hospital sterile processing departments.
- Custom:Proprietary instrument sets for robotic surgery and specialized orthopedic procedures require tailored compartment layouts. German and Swiss medical device manufacturers drive specification complexity.
- Mini:Compact formats suit dental handpiece sets and ophthalmic micro-instrument collections.
- Large:Extended dimensions accommodate laparoscopic instrument arrays and power equipment sterilization.
Standard sizes capture the highest shipment volumes; custom configurations command the steepest expansion trajectory as robotic surgery penetrates surgical suites.
Certification:
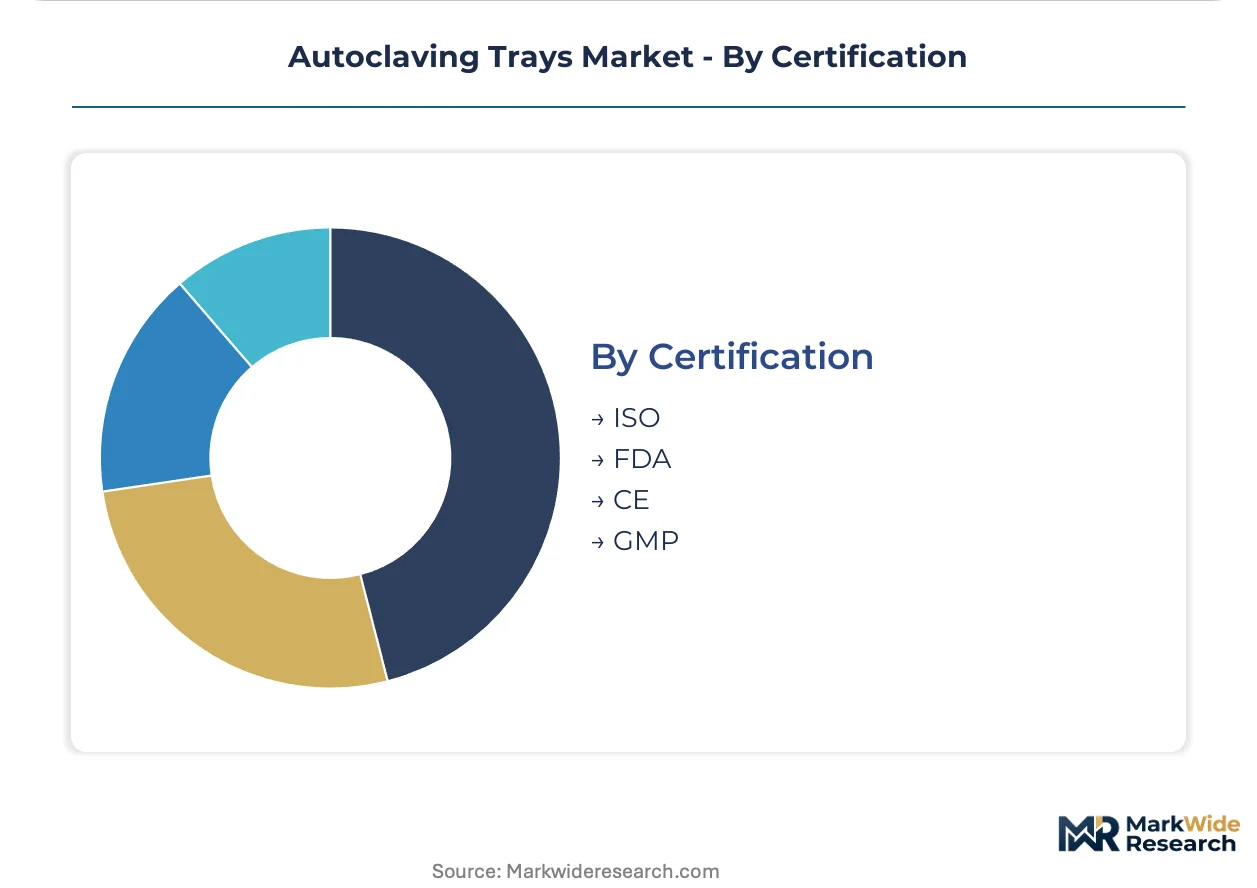
Regulatory documentation requirements now separate validated tray suppliers from commodity alternatives in procurement evaluations.
- ISO:ISO 17665 steam sterilization validation and ISO 10993 biocompatibility testing form baseline requirements for Western European and Asia-Pacific market entry. Notified bodies in Germany apply the strictest technical file interpretations.
- FDA:510(k) clearance for reusable medical device accessories elevates tray systems above unvalidated competitors in United States hospital purchasing criteria.
- CE:EU MDR Class IIa technical documentation demands clinical evidence of sterility maintenance for tray-lid systems.
- GMP:Good Manufacturing Practice compliance governs pharmaceutical and biotechnology laboratory applications.
ISO certification underpins the broadest installed base; FDA clearance requirements are tightening fastest as United States hospital networks consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical-grade 316L stainless steel sourcing clusters in specific metallurgical regions shape geographic production patterns. Hospital network consolidation and sterile processing centralization drive demand concentration across mature healthcare infrastructure markets.
United States
Integrated delivery networks in Texas and California run competitive tenders for tray standardization across multi-facility footprints. FDA 510(k) clearance requirements elevate validated systems above commodity alternatives in purchasing criteria. Minneapolis and Cleveland anchor sterile processing equipment manufacturing clusters where cross-selling relationships bundle trays with sterilizers.
Germany
Notified bodies enforce strictest EU MDR technical file interpretations for Class IIa tray-lid systems. ISO 17665 validation mandates concentrate procurement authority in central sterile supply departments. Stuttgart and Tuttlingen medical device manufacturing corridors drive specification complexity for custom robotic surgery configurations.
France
Outpatient surgical centers in Paris and Lyon adopt polymer configurations for high-turnover ophthalmic procedures. ANSM oversight tightens clinical evidence requirements for sterility maintenance claims. Strasbourg and Grenoble polymer injection molding clusters with medical device expertise decentralize manufacturing from traditional metalworking regions.
United Kingdom
NHS centralization of sterile processing procurement shifts purchasing decisions toward regional hub facilities. MHRA alignment with EU MDR extends regulatory timelines for market entry. Birmingham and Manchester medical technology corridors concentrate tray distribution logistics for multi-hospital networks.
Japan
PMDA medical device regulations mandate biocompatibility validation for polymer tray surfaces. METI industrial policy supports domestic manufacturing of high-temperature thermoplastics. Osaka and Tokyo surgical instrument clusters drive demand for silicone-lined microsurgical protection configurations.
Autoclaving Trays Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized protection configurations and digital traceability integration. The vendor base stratifies across sterilization equipment incumbents with captive tray offerings, independent metal fabricators with ISO-certified production, and polymer specialists targeting outpatient channels. Three archetypes dominate: integrated sterilization workflow providers, standalone tray manufacturers with regulatory documentation capabilities, and regional fabricators serving veterinary and dental price-sensitive segments. Capacity expansion and portfolio diversification toward RFID-enabled traceability represent the dominant competitive vectors.
Among integrated workflow providers, Steris plc and Getinge Group exemplify equipment-to-containment cross-selling strategies that leverage installed sterilizer bases. Steris plc occupies a position anchoring the North American hospital procurement landscape through bundled contracts. Getinge Group represents the European comprehensive sterile processing solutions archetype spanning washers through containment accessories. Belimed AG sits within the Swiss precision manufacturing tier serving premium clinical segments with validated system documentation.
| Leading Market Players |
|---|
| Duraline Systems |
| Kirwan Surgical Products |
| Terumo Cardiovascular Systems Corporation |
| Thomas Scientific |
| InstruSafe |
| Steris plc |
| Getinge Group |
| Belimed AG |
| Tuttnauer |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery network procurement officers in Texas and California health systems wield concentrated volume leverage, compressing margins for unvalidated tray suppliers while rewarding FDA-cleared systems with contract stability and multi-facility standardization premiums.
Pricing Analysis
High-volume stainless steel configurations trade on thin margins anchored to surgical-grade 316L metal costs, while silicone-lined specialty variants and polymer formulations capture premium pricing through instrument protection differentiation and biocompatibility certification investment. Price differentiation rests on FDA 510(k) clearance tier and ISO 17665 validation status, with unvalidated commodity alternatives facing steepest cost compression as hospital networks consolidate procurement authority. Pricing pressure intensifies from EU MDR clinical evidence requirements extending supplier compliance expenditures. Dental clinics and veterinary services exhibit highest price sensitivity; academic medical centers with GPO contracts demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Cleveland, and Stuttgart anchor hub-and-spoke fulfillment patterns serving multi-facility hospital networks with just-in-time sterile processing replenishment. Manufacturing concentrates in Germany, Switzerland, and the United States, with polymer injection molding capabilities decentralizing toward Strasbourg and Grenoble clusters. Raw material dependencies include surgical-grade 316L stainless steel from specialized metallurgical regions, medical-grade polyetherimide resins, and high-temperature silicone elastomers. Single-source vulnerability in qualified resin suppliers creates structural exposure. Distribution runs through sterilization equipment OEM captive channels and independent medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation burdens and FDA 510(k) clearance timelines are forcing mid-tier fabricators without validation capabilities toward exit or acquisition, consolidating viable supplier ranks around documented sterile workflow specialists.
For Market Incumbents: Lock in multi-facility IDN contracts through bundled sterilization equipment-tray service agreements before competitive tendering accelerates in Texas and California health systems. Deepen backward integration into surgical-grade 316L stainless sourcing to offset raw material geographic concentration risk. Prioritize RFID-enabled traceability R&D to capture central sterile supply department workflow optimization budgets. For New Entrants and Emerging Players: Enter via veterinary services and dental clinic channels where hospital-grade containment standards are newly mandated but validated supplier penetration remains sparse. Target companion animal surgical centers in Germany and France with lightweight aluminum configurations. Pursue private-label partnerships with regional sterilization equipment distributors lacking captive tray offerings. For Investors and Strategic Acquirers: The window for entry favors ISO 17665-validated mid-tier manufacturers with established EU MDR technical files and underutilized polymer molding capacity. Long-term viability hinges on regulatory documentation capabilities rather than metalworking scale alone. Watch for FDA warning letters targeting unvalidated tray suppliers as inflection signal accelerating replacement demand toward cleared systems.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Expansion | Clinical evidence investment separates validated suppliers from commodity competitors in German notified body assessments. |
| RFID Traceability Integration | Wireless identification convergence enables real-time sterile processing workflow optimization for IDN centralization. |
| Veterinary Channel Penetration | Companion animal surgical volume expansion opens faster-growing demand outside traditional healthcare procurement. |
| Polymer Formulation Development | Polyetherimide and polyphenylsulfone configurations reduce instrument abrasion in high-turnover ophthalmic procedures. |
| Hospital System Partnership | GPO contract alignment secures multi-facility standardization mandates in consolidating Texas and California networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across sterile processing directors, biomedical engineers, GPO contracts managers, and veterinary clinic procurement leads. FDA 510(k) clearances, EU MDR technical files, and ISO 17665 validation databases provided compliance benchmarking. Hospital procurement databases and sterilization equipment installed base records supplied demand-side calibration. Bottom-up tray shipment analysis and top-down healthcare capital expenditure triangulation validated volume estimates.
Segment-level modeling addressed product type, application, size, and certification dimensions across the projection horizon, with geographic granularity at country level for United States, Germany, France, United Kingdom, and Japan. CAGRs derived from sterilization cycle volume growth, hospital network consolidation pace, and outpatient surgical center expansion trajectories. Forecast inputs incorporated surgical procedure volume projections, EU MDR implementation timelines, and polymer raw material supply elasticity assumptions.
Revisions become necessary when FDA enforcement priorities shift toward reusable medical device accessories, EU MDR notified body capacity constraints extend clearance timelines, or stainless steel supply disruptions materialize from metallurgical region concentration. Periodic stress-testing of base assumptions against central sterile supply department budget cycles and IDN merger activity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Face Mask Market
Medical Supplies
Finger Splint Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Yankauer Suction Tips Market