
 India Hospital Supplies Market | 2026-2036
India Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
India Hospital Supplies Market Outlook
Urgent care facilities is pivoting toward advanced diagnostic equipment as India's healthcare infrastructure diversifies beyond traditional hospital settings. Cardinal Health leverages its distribution network to anchor supply chain reach into tier-2 cities. B. Braun SE specializes in surgical instruments and competes on sterilization technology standards. Johnson & Johnson sustains brand strength across wound care and sutures through decades of clinical presence.
Hospital supplies encompass the consumables, instruments, and equipment required for patient treatment, surgical intervention, and clinical diagnostics, typically manufactured from medical-grade polymers, stainless steel, or electronic sensor arrays subject to biocompatibility testing. Their primary purpose is to enable safe, standardized care delivery across acute and ambulatory settings. Medical disposables and diagnostic equipment command expanding share as infection control protocols intensify and point-of-care testing proliferates; surgical instruments remains a mature margin pool where domestic manufacturers under BIS standards challenge multinational pricing. Patient monitors integrates telehealth-ready electronics as hospitals upgrade ICU infrastructure.
CDSCO enforces Medical Device Rules that classify supplies by risk tier and mandate post-market surveillance, while BIS standards govern material specifications for domestic production. The PLI scheme for medical devices redirects procurement toward local manufacturing capacity. Stakeholders must monitor how state-level tender rationalization and Ayushman Bharat reimbursement tiers reshape vendor selection criteria.
Market Dynamics
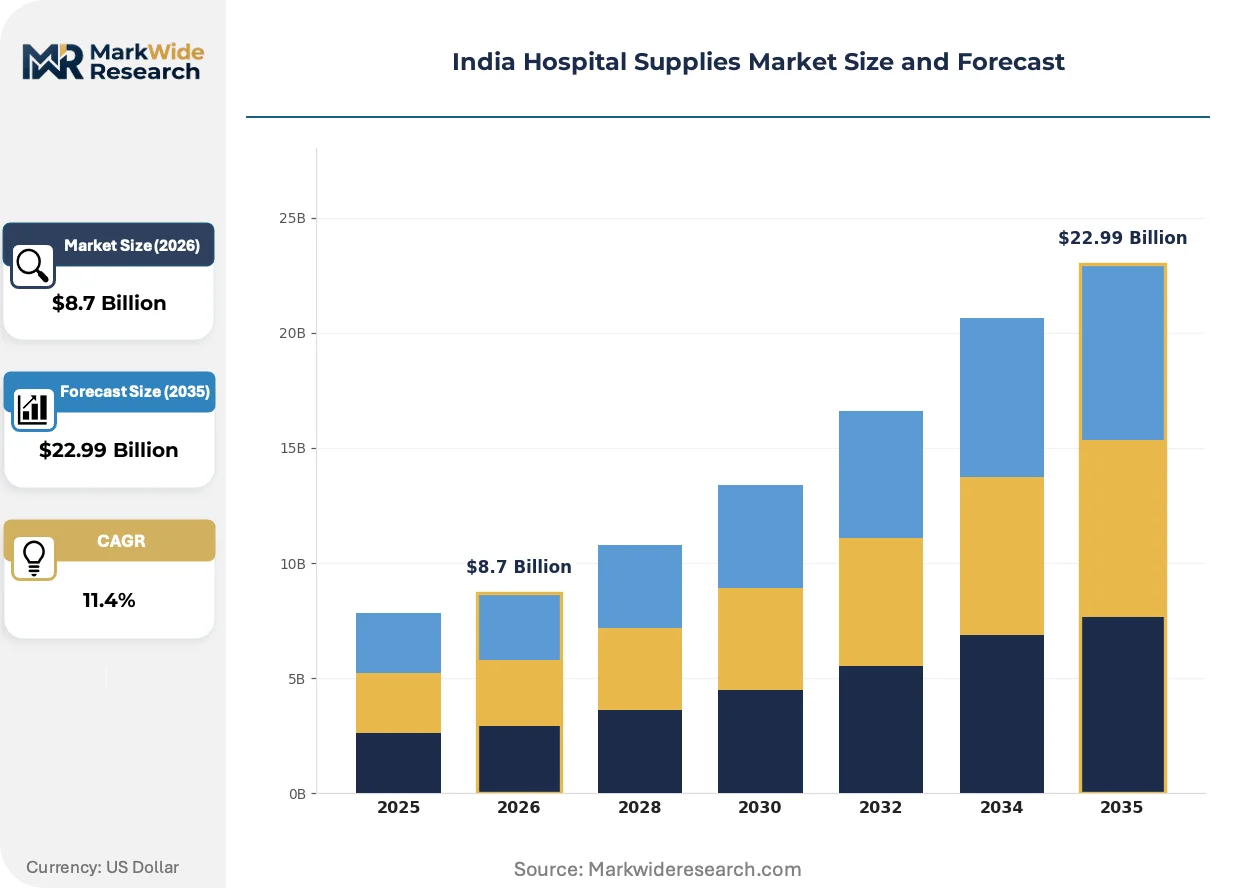
CDSCO Medical Device Rules and BIS certification mandates are compressing vendor timelines while PLI scheme incentives redirect procurement toward domestic manufacturing capacity, forcing supply chain reconfiguration across Maharashtra and Karnataka hospital clusters.
Growth Catalysts
- Ayushman Bharat reimbursement tiers:Tiered coverage expansion is pulling surgical consumables and diagnostic equipment into accredited facilities across South India's corporate hospital chains.
- Telehealth-ready ICU infrastructure:Patient monitoring systems with integrated sensor arrays are penetrating tertiary care settings as infection control protocols intensify post-pandemic.
- Point-of-care testing proliferation:Diagnostic equipment manufacturers are scaling portable analyzer production to serve urgent care facilities diversifying beyond traditional hospital footprints.
Market Restraints
- Medical-grade polymer import dependency:Raw material concentration in Southeast Asian petrochemical suppliers exposes domestic converters to freight volatility and currency fluctuation.
- BIS certification timeline friction:Stainless steel surgical instrument manufacturers face 8-14 month approval windows that compress working capital cycles and delay market entry.
- Reusable sterilization equipment substitution:Autoclave and plasma sterilizer refurbishment services are cannibalizing disposable instrument demand in cost-constrained government hospitals.
Strategic Opportunities
- Tier-2 city distribution gaps:Hub-and-spoke logistics networks anchored in Nagpur and Coimbatore remain underserved by multinational distributors, creating white space for regional players.
- CDSCO post-market surveillance mandates:Real-world performance tracking requirements are opening service contracts for data analytics and device registry management.
- Wearable sensor convergence with hospital IT:Continuous glucose monitors and cardiac patches integrating with EMR systems are creating new procurement categories for ambulatory surgical centers.
Industry Challenges
- Biocompatibility testing capacity bottleneck:CDSCO-recognized laboratories in Mumbai and Bengaluru face 6-month queues for cytotoxicity and sensitization assays, throttling product launch cadence.
- Legacy sterilization infrastructure integration:Steam autoclave systems in district hospitals require mechanical retrofitting to accommodate polymer-based single-use instrument trays, complicating rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hospital Supplies Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Medical Disposable, Diagnostic Equipment, Patient Monitors End User: Hospitals, Clinics, Rehabilitation Centers, Urgent Care Facilities Technology: Electronics, Robotics, Digital Imaging, Telehealth Solutions Application: Emergency Care, Routine Surgery, Patient Monitoring, Infection Control |
| Companies Covered | Cardinal Health, 3M, Baxter, Medtronic, B. Braun SE, Johnson & Johnson, Becton Dickinson and Company, GE Healthcare, Boston Scientific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hospital Supplies Market Strategic Shifts
Disposable instrument platforms and connected monitoring hardware are displacing capital-intensive reusable equipment, while regulatory data requirements and procurement centralization reshape how vendors compete for hospital contracts.
Single-use surgical instrument kits fabricated from medical-grade polymers are decentralizing sterilization workflows from centralized CSSD departments to point-of-procedure consumption. Corporate hospital chains in Bengaluru and Hyderabad are adopting these kits for orthopedic and laparoscopic procedures at 40% annual volume expansion. This shift is compressing capital expenditure requirements for sterilization infrastructure while elevating consumables procurement to strategic priority status.
CDSCO's 2022 Medical Device Rules amendment mandating Unique Device Identification traceability is restructuring supplier qualification protocols. Domestic manufacturers must embed GS1-compliant barcoding and maintain post-market adverse event registries to retain tender eligibility. Surgical suture and wound dressing producers face the steepest compliance curve, with state-level procurement bodies in Maharashtra already rejecting non-UDI-compliant bids.
State-level tender rationalization is consolidating vendor pools as Karnataka and Tamil Nadu shift from hospital-specific purchasing to centralized medical supplies corporations. District hospital clusters now negotiate through pooled procurement platforms that disintermediate traditional distributor relationships. This concentration is most visible in Kerala's public health system, where 47 facilities now route diagnostic equipment and disposables through a single e-tender portal with pre-qualified vendor shortlists.
India Hospital Supplies Market Segmentation
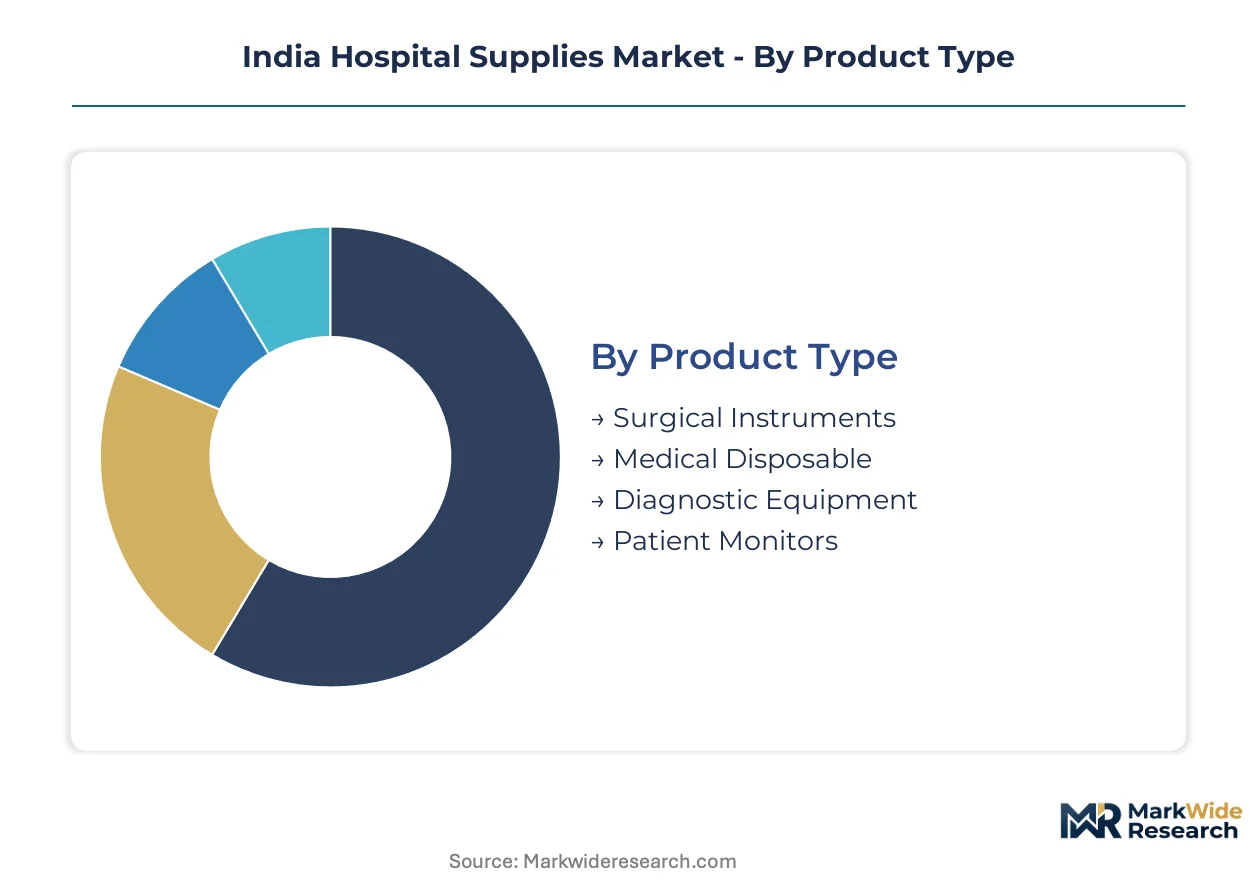
Hospital supplies in India fragment across capital equipment and consumable categories with divergent investment profiles, procurement cycles, and regulatory exposure. Understanding these divides reveals where domestic manufacturing incentives under the PLI scheme redirect capacity, and which segments multinational incumbents still dominate through technology gaps.
Product Type:
Capital intensity varies sharply across this category, with diagnostic equipment and patient monitors demanding heavy upfront outlays for sensor arrays and embedded software development, while disposables and surgical instruments scale through manufacturing volume rather than R&D expenditure.
- Surgical Instruments:Stainless steel and polymer-based implements ranging from scalpels to laparoscopic graspers, subject to BIS material certification and CDSCO risk classification. Maharashtra's tertiary care clusters in Mumbai and Pune are expanding procurement of single-use instrument kits as sterilization infrastructure constraints persist in district hospitals.
- Medical Disposable:Gowns, drapes, syringes, and wound dressings fabricated from medical-grade polymers and non-woven fabrics, governed by biocompatibility testing mandates. Karnataka's corporate hospital chains are driving 40% annual volume expansion in infection control disposables as post-pandemic protocols harden.
- Diagnostic Equipment:Imaging systems, analyzers, and portable testing platforms integrating optical and electronic sensor modules.
- Patient Monitors:Multi-parameter bedside and telemetry units with telehealth-ready connectivity for ICU infrastructure upgrades.
Diagnostic equipment absorbs the bulk of installed capital value; medical disposables are expanding most quickly as procurement shifts toward consumable-heavy care models.
End User:
Procurement authority concentrates differently across these settings, with corporate hospital chains centralizing purchasing through dedicated supply companies while government facilities route through state-level tender portals with pre-qualified vendor shortlists.
- Hospitals:Acute care facilities spanning tertiary referral centers to district hospitals, representing the dominant procurement volume for capital equipment and high-value consumables. South India's corporate chains in Bengaluru and Hyderabad are consolidating vendor relationships through multi-year surgical instrument and monitoring equipment contracts.
- Clinics:Outpatient-focused primary care and specialty practices with limited capital budgets and higher price sensitivity on disposables.
- Rehabilitation Centers:Post-acute and long-term care facilities with specialized demand for patient monitoring and mobility-assist equipment.
- Urgent Care Facilities:Standalone emergency and ambulatory surgical centers diversifying beyond traditional hospital footprints, pivoting toward point-of-care diagnostic equipment and rapid-turn consumables.
Hospitals command the deepest procurement relationships; urgent care facilities are climbing the fastest as healthcare infrastructure decentralizes.
Technology:
Technology differentiation determines margin structure and vendor lock-in potential, with electronics and digital imaging requiring continuous firmware development while robotics demands the steepest integration investment.
- Electronics:Sensor arrays, signal processing modules, and embedded systems powering patient monitors and diagnostic analyzers. CDSCO post-market surveillance mandates for software-updatable devices are creating compliance service opportunities around Bengaluru's medical device engineering clusters.
- Robotics:Surgical assistance and automated dispensing systems with the highest capital intensity and longest sales cycles.
- Digital Imaging:Computed radiography, ultrasound, and endoscopic visualization systems with compressed replacement demand as AI-assisted diagnostics penetrate tier-2 cities.
- Telehealth Solutions:Remote monitoring platforms and video consultation infrastructure integrating with hospital EMR systems.
Electronics platforms underpin the widest installed base; telehealth solutions are gaining share fastest as ICU infrastructure upgrades accelerate.
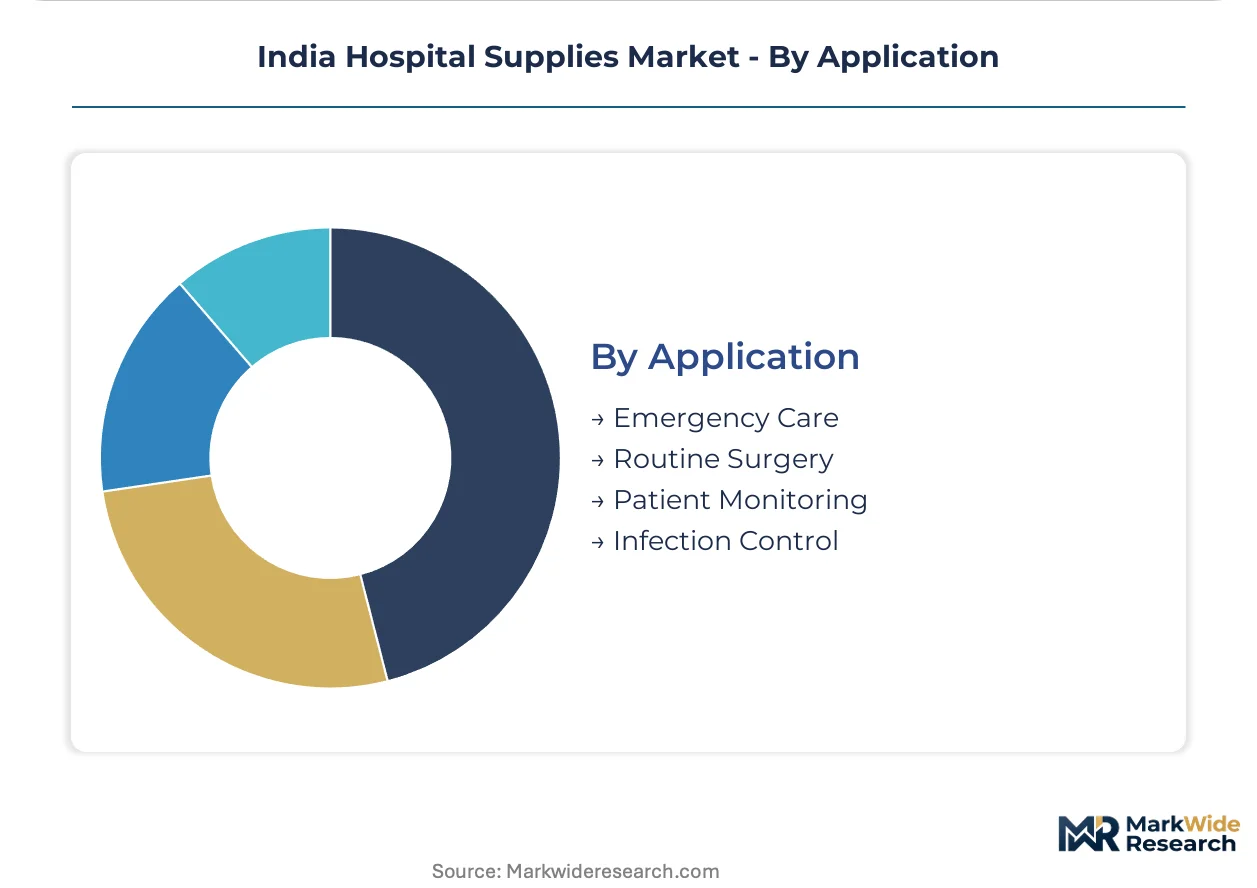
Application:
Application focus shapes product specification requirements and procurement frequency, with emergency care demanding rapid-turn disposables and infection control driving the most stringent material certification standards.
- Emergency Care:Trauma and resuscitation supplies including airway management, hemorrhage control, and cardiac support devices. Maharashtra's government hospital clusters are expanding centralized procurement of emergency disposable kits through the state medical supplies corporation.
- Routine Surgery:General, orthopedic, and minimally invasive procedure consumables with predictable demand patterns and established vendor relationships.
- Patient Monitoring:Continuous vital signs tracking across acute and step-down care settings, with telemetry integration becoming standard in Karnataka's tertiary facilities.
- Infection Control:Sterilization supplies, barrier products, and environmental disinfection systems subject to the tightest CDSCO quality thresholds and BIS material specifications.
Routine surgery captures the steadiest volume base; infection control is expanding most steeply as regulatory scrutiny intensifies and hospital-acquired infection liability rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical Special Economic Zones in Telangana and Andhra Pradesh are concentrating medical device manufacturing capacity, with the Visakhapatnam SEZ offering 15-year tax holidays for export-oriented units.
Maharashtra
Mumbai's tertiary care clusters drive procurement of single-use surgical instrument kits as sterilization infrastructure constraints persist in district hospitals. The state's medical supplies corporation now mandates CDSCO UDI compliance for all tender submissions. Pune's medical device manufacturing corridor is expanding polymer-based disposable production to serve western India hospital networks.
Karnataka
Corporate hospital chains in Bengaluru are consolidating multi-year contracts for patient monitoring equipment with telehealth integration capabilities. The Karnataka State Medical Supplies Corporation has centralized procurement for 47 public facilities through a single e-tender portal. Hyderabad's medtech engineering clusters are developing firmware-updatable diagnostic analyzers to meet post-market surveillance mandates.
Tamil Nadu
Chennai's corporate hospital networks are scaling infection control disposable procurement at 40% annual volume expansion post-pandemic. The Tamil Nadu Medical Services Corporation has shifted from hospital-specific purchasing to pooled procurement platforms. Coimbatore's hub-and-spoke logistics networks remain underserved by multinational distributors, creating white space for regional players.
Telangana
Hyderabad's ambulatory surgical centers are diversifying procurement toward point-of-care diagnostic equipment and rapid-turn consumables. The state's PLI scheme for medical devices is redirecting capacity toward domestic manufacturing of surgical sutures and wound dressings. The Genome Valley life sciences cluster is attracting CDSCO-recognized biocompatibility testing laboratories to reduce 6-month assay queues.
Kerala
Kochi's urgent care facilities are pivoting toward portable analyzer production for decentralized diagnostic workflows. The Kerala Medical Services Corporation routes all diagnostic equipment and disposables through pre-qualified vendor shortlists. Thiruvananthapuram's public health system is retrofitting legacy steam autoclave infrastructure to accommodate polymer-based single-use instrument trays.
India Hospital Supplies Market Competitive Environment
Top-tier vendors anchor the premium equipment segment, while domestic converters and regional distributors occupy the mid-market tier. The vendor structure fragments across multinational technology licensors, BIS-certified domestic manufacturers, and state-level tender specialists. Three archetypes dominate: sterilization technology specialists, distribution network anchors, and PLI scheme beneficiaries building backward integration into medical-grade polymers. Competitive moves concentrate on strategic partnerships with corporate hospital chains and geographic expansion into tier-2 hub cities.
Within the distribution anchor archetype, Cardinal Health exemplifies supply chain reach into underserved secondary cities. Among sterilization technology specialists, B. Braun SE occupies a position reflecting European engineering standards in surgical instrument fabrication. Johnson & Johnson represents the clinical heritage archetype, with decades of presence across wound care and suture categories. These three entities collectively illustrate how brand equity, regulatory compliance depth, and logistics infrastructure determine tender eligibility in state-level procurement rationalization.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M |
| Baxter |
| Medtronic |
| B. Braun SE |
| Johnson & Johnson |
| Becton Dickinson and Company |
| GE Healthcare |
| Boston Scientific |
| Others |
Value Chain & Pricing Dynamics
BIS certification timelines for medical-grade stainless steel and polymer inputs gate qualified supply access and premium-tier pricing power for surgical instrument vendors serving Maharashtra's tertiary care clusters. CDSCO UDI compliance mandates further stratify vendor tiers, compressing margins for non-certified converters while rewarding BIS-accredited domestic manufacturers with tender eligibility premiums.
Pricing Analysis
Short lead-time premiums dominate surgical instrument procurement as Maharashtra's medical supplies corporation penalizes 8-14 month BIS certification delays with spot-inventory discounts. Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-UDI compliant multinationals from BIS-certified domestic players and uncertified regional converters. Cost compression in economy-tier disposables intensifies as Karnataka's centralized e-tender portals pool demand and disintermediate distributor markups. Government hospital clusters exhibit highest price sensitivity; corporate hospital chains in Bengaluru absorb premium telemetry-integrated monitoring equipment with lower elasticity.
Supply Chain Analysis
Reverse-logistics flows for steam autoclave refurbishment and plasma sterilizer redeployment cannibalize disposable instrument demand in Kerala's district hospitals, compressing new equipment procurement cycles. Raw material concentration in China, South Korea, and Japan for medical-grade polymers and electronic sensor arrays exposes domestic converters to freight volatility and currency fluctuation. Single-source vulnerability concentrates in Southeast Asian petrochemical suppliers feeding Maharashtra's polymer-based disposable production. Distribution runs through hub-and-spoke networks anchored in Nagpur and Coimbatore, with multinational distributors underserving tier-2 city clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's hospital supplies sector sits in a technology-transition phase where polymer-based single-use instrument kits displace capital-intensive reusable sterilization infrastructure across corporate hospital chains.
For Market Incumbents: Hedge against BIS certification timeline friction by building captive biocompatibility testing capacity or partnering with CDSCO-recognized laboratories in Mumbai and Bengaluru. Deepen backward integration into medical-grade polymer compounding to offset Southeast Asian import dependency and defend margin position against domestic PLI scheme beneficiaries. For New Entrants and Emerging Players: Enter via Coimbatore's underserved hub-and-spoke logistics networks where multinational distributor gaps create white space for regional sterilization technology specialists. Target urgent care facilities diversifying into point-of-care diagnostic equipment with portable analyzer platforms that bypass centralized CSSD infrastructure requirements. For Investors and Strategic Acquirers: CDSCO's post-market surveillance mandate enforcement is the leading indicator that real-world performance tracking and device registry management service contracts will command premium valuations. Acquisition focus should center on firmware-updatable diagnostic analyzer developers with Bengaluru engineering clusters and established hospital IT integration capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO UDI Compliance Investment | BIS-certified domestic manufacturers secure tender eligibility in Maharashtra's centralized procurement portals. |
| Biocompatibility Testing Laboratory Partnership | Reduces 6-month assay queues that throttle product launch cadence for polymer-based disposables. |
| Telehealth-Ready ICU Infrastructure Upgrade | Karnataka's corporate hospital chains consolidate multi-year contracts for telemetry-integrated patient monitors. |
| Backward Integration into Polymer Compounding | PLI scheme incentives redirect capacity toward domestic manufacturing of surgical sutures and wound dressings. |
| Hub-and-Spoke Distribution Network Expansion | Regional distributors capture tier-2 city gaps in Nagpur and Coimbatore underserved by multinational anchors. |
Study Parameters
Hospital procurement databases, CDSCO Medical Device Rules filings, and BIS certification records formed the secondary backbone, cross-referenced with primary interviews involving hospital purchasing committees, biomedical engineers, GPO contracts managers, and sterilization technology specialists. Bottom-up triangulation across state-level tender portals in Maharashtra, Karnataka, and Tamil Nadu validated top-down market sizing from import-export customs data and PLI scheme disbursement disclosures.
Historical trendline analysis of surgical instrument and diagnostic equipment procurement volumes informed projection modeling across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis of accredited facility expansion under Ayushman Bharat reimbursement tiers and infection control protocol intensification post-pandemic, with segment-specific adjustments for BIS certification timeline friction and biocompatibility testing capacity constraints.
Revisions become necessary when CDSCO regulatory amendments, BIS standard updates, or PLI scheme incentive restructuring materialize outside baseline assumptions. Practitioners should monitor state-level tender rationalization announcements and Ayushman Bharat accreditation thresholds for early signals of demand reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Microcarrier Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Specimen Collection Cards Market