
 Middle East and Africa Medical Rubber and Balloon Products Market | 2026-2036
Middle East and Africa Medical Rubber and Balloon Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medical Rubber and Balloon Products Market Analytics
Market Context
The divergence between premium silicone-based balloon systems and commodity latex catheters is hardening across Middle East and Africa procurement channels. Abbott Laboratories leverages vertical integration in cardiovascular balloon manufacturing to sustain pricing power in Gulf Cooperation Council tenders. Medtronic anchors its position through R&D intensity in drug-eluting balloon technologies, while B. Braun SE competes on sterile manufacturing scale for single-use rubber seals.
Technical Definition and Structural Segments
Middle East and Africa medical rubber and balloon products encompass elastomeric devices manufactured from latex, silicone, or thermoplastic polymers, typically exhibiting tensile strengths of 7-25 MPa and sterilization compatibility with gamma irradiation or ethylene oxide, serving functions ranging from vessel dilation to fluid containment in minimally invasive procedures. Catheters and balloons command the largest revenue pool due to interventional cardiology expansion across Gulf state hospital networks, while silicone-based segments outpace latex alternatives on biocompatibility premiums and regulatory migration away from allergenic natural rubber. Gaskets and seals occupy a mature, volume-driven position where margin compression from Asian imports shapes competitive dynamics for regional distributors.
Regulatory Frame and Outlook
Saudi Food and Drug Authority and South African Health Products Regulatory Authority enforce ISO 13485 and EU MDR-aligned conformity assessments on imported devices, while Gulf Standardization Organization technical regulations harmonize labeling and sterilization validation across six member states. These frameworks elevate compliance costs for commodity latex suppliers while creating market access advantages for manufacturers with established quality management systems. Stakeholders must monitor evolving premarket submission requirements as national regulators transition from reliance on foreign approvals toward sovereign review pathways.
Market Dynamics
Interventional cardiology expansion across Gulf state hospital networks is pulling specialized balloon catheter procurement toward centralized tender systems, compressing distributor margins while elevating technical specification requirements for silicone-based devices.
Growth Catalysts
- SFDA Localization Mandates:Saudi Food and Drug Authority procurement preferences for domestically manufactured devices are redirecting foreign supplier investment toward Jeddah and Riyadh production facilities.
- Drug-Eluting Balloon Adoption:Tertiary hospitals in the UAE and Qatar are upgrading catheterization laboratories with next-generation drug-eluting platforms for peripheral artery disease interventions.
- South Africa's NHI Procurement Centralization:The national health insurance framework is consolidating hospital purchasing power, creating volume opportunities for ISO 13485-certified manufacturers.
Market Restraints
- Silicone Raw Material Concentration:Specialty medical-grade silicone feedstock supply concentrates among three multinational chemical suppliers, exposing balloon manufacturers to input cost volatility.
- SFDA Sovereign Review Pathways:Transition from reliance on FDA/CE approvals toward independent Saudi premarket submissions extends product registration timelines by 12-18 months.
- Latex Allergy Substitution:Synthetic polyisoprene and thermoplastic elastomers are displacing natural rubber latex in glove and seal applications, eroding traditional latex processor revenue pools.
Strategic Opportunities
- Egyptian Manufacturing Zones:Suez Canal Economic Zone incentives for medical device production offer tariff-advantaged export platforms serving Sub-Saharan African markets.
- Bioresorbable Stent Delivery Systems:Convergence of bioresorbable scaffold technology with balloon catheter platforms opens premium positioning in pediatric and coronary applications.
- MOHAP Digital Procurement Platforms:UAE Ministry of Health and Prevention's centralized e-tender systems enable direct manufacturer access to federal hospital networks, bypassing traditional distributor layers.
Industry Challenges
- Gamma Sterilization Capacity Constraints:Contract sterilization providers in the Gulf region face backlog pressures, delaying product release timelines for single-use balloon devices.
- Polymer Compounding Expertise Scarcity:Medical-grade elastomer formulation capabilities remain concentrated among European and North American compounders, limiting regional vertical integration.
- Legacy ERP Integration Friction:Hospital procurement networks migrating to centralized digital platforms face interoperability challenges with existing supplier order management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medical Rubber and Balloon Products Market |
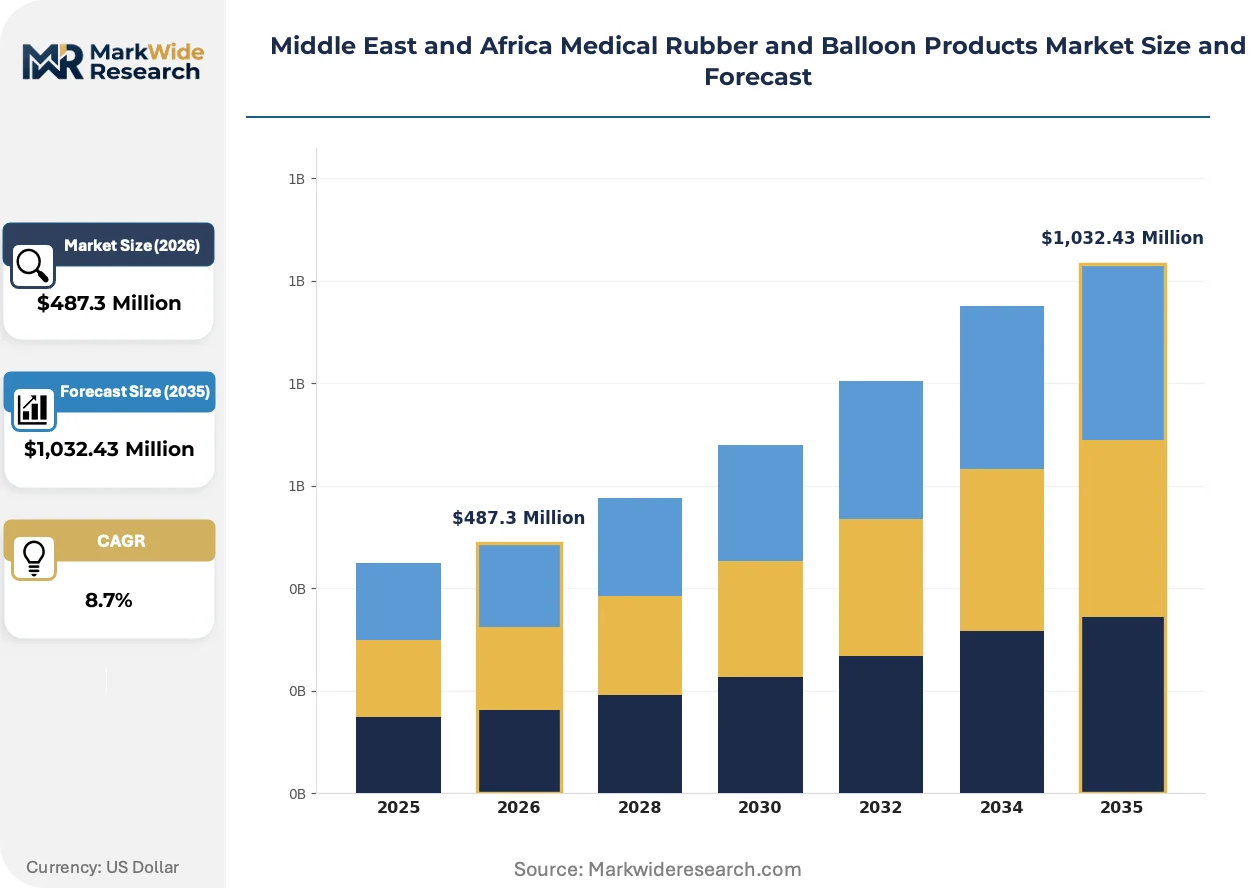
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Balloons, Gaskets, Seals Application: Cardiology, Urology, Gastroenterology, Respiratory Material: Latex, Silicone, Thermoplastic, Polyvinyl Chloride End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare |
| Companies Covered | Abbott Laboratories, AngioDynamics, Adventa Berhad, Saint-Gobain, Parker Hannifin Corp, Medtronic, Koninklijke Philips, GE HealthCare, B. Braun SE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medical Rubber and Balloon Products Market Evolving Landscape
Material science advances and regulatory digitization are restructuring competitive advantage around biocompatibility certification and supply chain traceability rather than commodity manufacturing scale.
Silicone balloon catheter technology is converging with embedded sensor platforms for real-time pressure monitoring during angioplasty procedures. Tertiary cardiac centers in Saudi Arabia and the UAE are piloting these integrated devices for complex lesion interventions. This convergence is compressing the addressable market for conventional non-sensing balloon systems while opening premium pricing tiers for smart catheter platforms.
South African Health Products Regulatory Authority is aligning premarket submission requirements with EU MDR technical documentation standards, including enhanced clinical evidence and post-market surveillance obligations. Medical device importers face expanded quality management system audit scopes and extended conformity assessment timelines. Balloon catheter and elastomeric seal manufacturers with existing MDR certifications capture first-mover advantage in streamlined SAHPRA registration pathways.
Hospital procurement consolidation across Gulf Cooperation Council states is compressing supplier bases toward manufacturers offering comprehensive catheter and accessory portfolios. Single-product specialists face exclusion from integrated tender awards covering interventional cardiology procedure kits. This concentration is most visible in Saudi Arabia's National Unified Procurement Company framework, where multi-year supply agreements favor vendors with sterile manufacturing scale across balloon, guide wire, and introducer sheath categories.
Middle East and Africa Medical Rubber and Balloon Products Market Segmentation
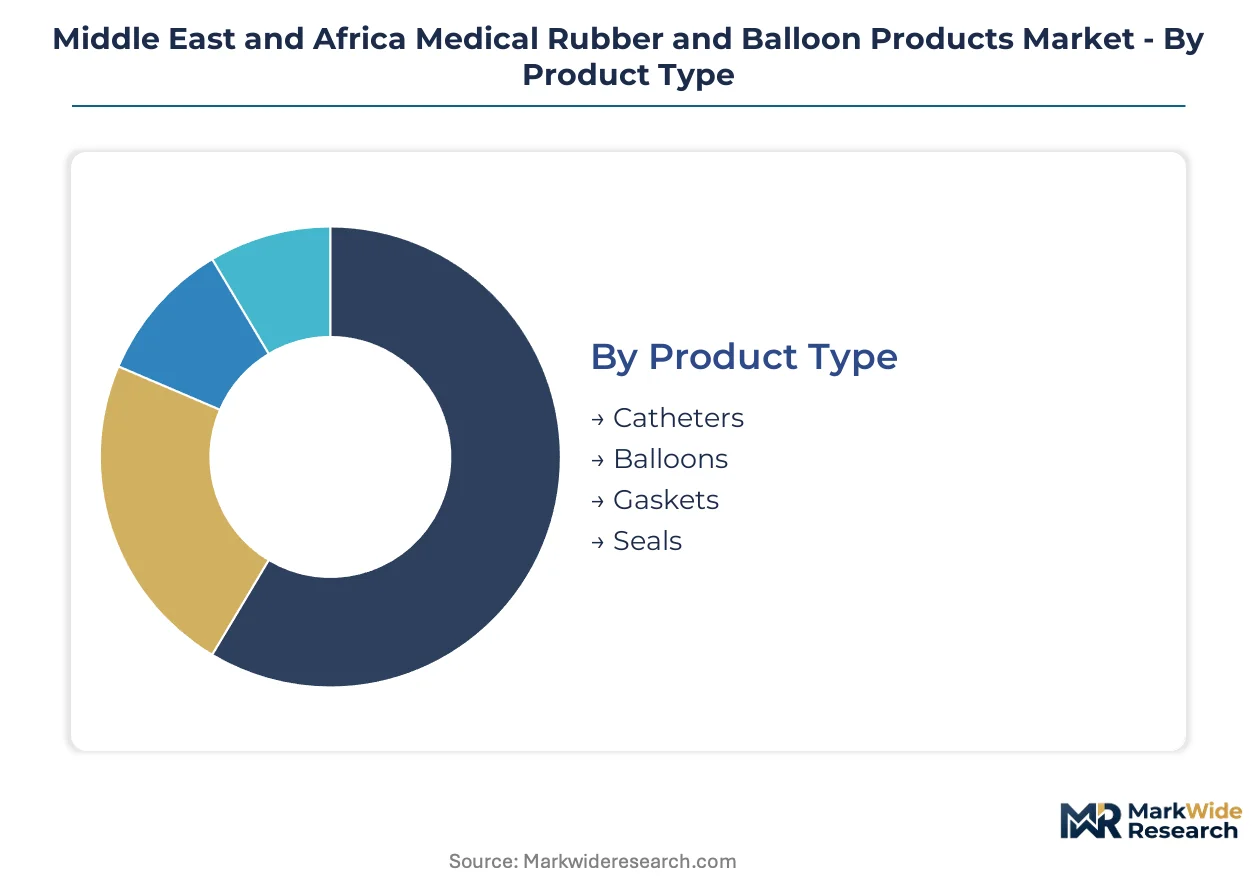
Procurement patterns across Middle East and Africa medical rubber and balloon products diverge sharply between high-value interventional devices and commodity elastomeric components. Understanding these segment boundaries clarifies where margin compression versus pricing power concentrates for manufacturers and distributors.
Product Type:
Hospital procurement officers weight technical specifications against total procedure cost when selecting between premium balloon systems and standard catheter configurations.
- Catheters:Elastomeric tubes manufactured from silicone or thermoplastic polymers with lumen diameters calibrated for fluid delivery or guidewire passage. Saudi Arabia's National Unified Procurement Company bundles these into interventional cardiology procedure kits, favoring suppliers with sterile manufacturing scale across multiple device categories.
- Balloons:Inflatable elastomeric membranes engineered for precise pressure compliance and burst resistance during vessel dilation. Tertiary cardiac centers in the UAE and Qatar prioritize drug-eluting platforms for peripheral artery disease interventions, pulling procurement toward next-generation silicone-based systems.
- Gaskets:Compression seals for fluid containment in diagnostic equipment and fluid management systems.
- Seals:Elastomeric barriers preventing contamination in single-use device assemblies and sterile packaging.
Volume sits with catheters; growth tilts toward balloons.
Application:
Clinical outcome requirements and reimbursement levels determine material selection and regulatory pathway complexity across therapeutic areas.
- Cardiology:Balloon catheter applications demanding burst pressures above 15 atmospheres and precise compliance curves for coronary and peripheral interventions. South Africa's hospital networks concentrate demand as the national health insurance framework consolidates purchasing power toward ISO 13485-certified manufacturers.
- Urology:Latex and silicone balloon systems for catheterization and stone management procedures. Egyptian public hospitals drive volume procurement through centralized Ministry of Health tenders, compressing distributor margins on commodity latex devices.
- Gastroenterology:Balloon dilators and occlusion devices for endoscopic procedures.
- Respiratory:Elastomeric seals and valve components for ventilation and airway management systems.
Cardiology commands premium pricing; urology delivers volume scale.
Material:
Biocompatibility certification and allergen liability exposure separate procurement tiers across hospital networks.
- Silicone:Medical-grade platinum-cured elastomers with tensile strengths of 7-15 MPa and gamma sterilization compatibility. SFDA procurement preferences for advanced interventional devices accelerate substitution away from natural rubber in Saudi tertiary hospitals.
- Latex:Natural rubber formulations facing displacement from glove and seal applications due to Type I hypersensitivity liability. South African Health Products Regulatory Authority alignment with EU MDR standards hastens this transition in hospital procurement specifications.
- Thermoplastic:Processable polymers enabling complex geometries for specialized catheter shafts.
- Polyvinyl Chloride:Cost-competitive material for non-compliant balloon applications and fluid management tubing.
Silicone captures margin expansion; thermoplastic gains share fastest.
End User:
Capital equipment access and procedure complexity stratify demand across care settings.
- Hospitals:Tertiary medical centers with catheterization laboratories and sterile processing infrastructure. Saudi Arabia's hospital procurement networks concentrate demand as the Kingdom expands domestic manufacturing capacity under SFDA localization mandates.
- Clinics:Outpatient facilities performing diagnostic and minor interventional procedures. UAE Ministry of Health and Prevention digital procurement platforms enable direct manufacturer access, bypassing traditional distributor layers for mid-volume orders.
- Ambulatory Surgical Centers:Same-day procedure venues requiring single-use sterile device configurations.
- Homecare:Patient-directed settings for chronic catheter management and respiratory support.
Hospitals anchor procurement volume; ambulatory surgical centers present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah and Riyadh anchor procurement concentration as Saudi Arabia's National Unified Procurement Company consolidates hospital purchasing power toward domestic manufacturing zones.
Saudi Arabia
SFDA localization mandates redirect foreign supplier investment toward Jeddah and Riyadh production facilities. The National Unified Procurement Company bundles interventional cardiology procedure kits, favoring vendors with sterile manufacturing scale across multiple device categories. King Abdullah Economic City hosts emerging medical device clusters serving Gulf Cooperation Council export markets.
United Arab Emirates
MOHAP digital procurement platforms enable direct manufacturer access to federal hospital networks, bypassing traditional distributor layers. Tertiary cardiac centers in Dubai and Abu Dhabi pilot integrated sensor-embedded balloon systems for complex lesion interventions. Dubai Science Park attracts regional headquarters for multinational catheter manufacturers seeking Gulf market access.
South Africa
SAHPRA alignment with EU MDR technical documentation standards streamlines registration pathways for certified manufacturers. The national health insurance framework consolidates hospital purchasing power toward ISO 13485-certified suppliers. Gauteng Province concentrates demand through centralized tender systems serving public hospital networks.
Egypt
Suez Canal Economic Zone incentives offer tariff-advantaged export platforms serving Sub-Saharan African markets. Ministry of Health tenders drive volume procurement for public hospitals, compressing distributor margins on commodity latex devices. Cairo-Alexandria corridor hosts regional distribution hubs for North African medical device trade.
Qatar
Hamad Medical Corporation procurement specifications prioritize drug-eluting balloon platforms for peripheral artery disease interventions. Sidra Medicine anchors specialized pediatric interventional device demand in Doha's healthcare cluster. Qatar Free Zones Authority medical device licensing attracts European manufacturers seeking Gulf market presence.
Middle East and Africa Medical Rubber and Balloon Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and sterile manufacturing scale. The vendor base stratifies between multinational corporations with integrated catheter portfolios and regional distributors serving volume-driven gasket and seal segments. Three archetypes dominate: vertically integrated device manufacturers, specialized balloon technology developers, and sterile component fabricators. Competitive moves concentrate on backward integration into polymer compounding and strategic positioning within centralized Gulf procurement frameworks.
Among diversified healthcare conglomerates, Abbott Laboratories and Medtronic exemplify premium-tier positioning through cardiovascular device portfolios, while B. Braun SE occupies a position emphasizing sterile manufacturing scale for single-use components. These anchors represent contrasting strategic postures: integrated procedure kit bundling versus specialized component supply.
| Leading Market Players |
|---|
| Abbott Laboratories |
| AngioDynamics |
| Adventa Berhad |
| Saint-Gobain |
| Parker Hannifin Corp |
| Medtronic |
| Koninklijke Philips |
| GE HealthCare |
| B. Braun SE |
| Others |
Value Network & Pricing Analysis
EU MDR-aligned conformity requirements now gate qualified supply access for balloon catheter and elastomeric seal manufacturers serving Saudi Arabia and South Africa, simultaneously compressing commodity-tier margins and elevating premium-tier pricing power for ISO 13485-certified producers with established quality management systems.
Pricing Analysis
Value-based pricing anchored to clinical throughput outcomes dominates interventional cardiology procurement across Gulf Cooperation Council hospital networks. Three-tier pricing structure across premium silicone-based drug-eluting platforms, standard thermoplastic catheters, and economy latex devices separates procurement tiers by biocompatibility certification and sterilization validation. Pricing pressure stems from centralized tender compression as Saudi Arabia's National Unified Procurement Company bundles procedure kits, forcing single-product specialists toward margin erosion. Public hospital procurement committees exhibit highest price sensitivity, while private tertiary cardiac centers in Dubai and Abu Dhabi prioritize performance premiums over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for device returns and refurbishment remains underdeveloped across Middle East and Africa distribution networks, creating compliance gaps for expired or recalled inventory. Medical-grade silicone feedstock concentrates among German, Japanese, and American chemical compounders, while sterile component fabrication clusters in Malaysia and China supply catheter assemblies. Raw material dependencies on platinum-cured elastomers, gamma-irradiation packaging, and precision extrusion equipment tether regional manufacturers to European and Asian suppliers. Single-source vulnerability in gamma sterilization capacity across Gulf contract providers poses release-timeline risks. Distribution runs through Jeddah, Dubai, and Cairo distribution hubs serving hospital procurement networks and regional re-export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA sovereign review pathways function as a cost-of-compliance moat, extending registration timelines and capital requirements in ways that favor incumbent manufacturers with established Jeddah and Riyadh quality infrastructure over undercapitalized challengers.
For Market Incumbents: Cement sterile manufacturing scale across balloon, guide wire, and introducer sheath categories to defend position within Saudi Arabia's National Unified Procurement Company bundled tender framework. Prioritize backward integration into medical-grade silicone compounding to reduce exposure to three-supplier feedstock concentration. Counter emerging Asian commodity latex competitors through MDR certification leverage in South African Health Products Regulatory Authority pathways. For New Entrants and Emerging Players: MOHAP digital procurement platforms in the UAE open a window for direct manufacturer access to federal hospital networks, bypassing traditional distributor margin layers. Target Egyptian Suez Canal Economic Zone production incentives as a tariff-advantaged export platform serving Sub-Saharan African markets. Pursue bioresorbable stent delivery system partnerships with European technology licensors as a premium-positioning go-to-market angle. For Investors and Strategic Acquirers: SFDA localization mandate acceleration is the leading indicator that domestic manufacturing capacity valuations will detach from pure import-distributor multiples. Frame long-term viability around 5-10 year regulatory sovereignty trends favoring in-region sterile production. Prioritize acquisition targets with existing ISO 13485 infrastructure and Gulf hospital network contracts over pure technology plays. Monitor gamma sterilization capacity buildout announcements as the inflection signal for supply-chain bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Premarket Submission | Sovereign registration pathways in Saudi Arabia create first-mover advantage for compliant manufacturers. |
| Silicone Compounding Backward Integration | In-house production of medical-grade elastomers reduces feedstock volatility exposure from chemical suppliers. |
| MOHAP Digital Platform Registration | Direct access to UAE federal hospital networks compresses distributor layers and improves margin capture. |
| Drug-Eluting Balloon R&D Partnership | Collaboration with European technology holders positions manufacturers for next-generation catheter tenders. |
| Suez Canal Economic Zone Facility | Tariff-advantaged production enables competitive export positioning into Sub-Saharan African procurement networks. |
Research Methodology
Multi-period observation of SFDA registration timelines, MOHAP tender award patterns, and SAHPRA conformity assessment flows anchored the trend analysis, supplemented by interviews with hospital procurement officers, biomedical engineers at tertiary cardiac centers, GPO contracts managers, and regulatory affairs leads at multinational device manufacturers. Secondary validation drew from Saudi Food and Drug Authority premarket submission databases, UAE Ministry of Health and Prevention e-tender platforms, South African Health Products Regulatory Authority guidance documents, and Gulf Standardization Organization technical regulations. Bottom-up segmentation modeling triangulated against top-down macroeconomic healthcare expenditure projections.
The input-output matrix framed demand drivers across product type, application, material, and end-user dimensions, with cross-segment elasticity testing for substitution effects between silicone and latex formulations. CAGRs were derived from iterative convergence of procedure volume forecasts, pricing trajectory assumptions, and technology adoption curves across the projection horizon. Industry-specific forecast inputs incorporated interventional cardiology laboratory expansion pipelines in Saudi Arabia and Qatar, plus National Health Insurance procurement centralization timelines in South Africa.
The model assumes a particular technology adoption path; alternative pathways for bioresorbable scaffold integration with balloon delivery systems would alter the outlook for conventional silicone platform demand. Forecasts reflect assumptions around SFDA localization enforcement intensity and gamma sterilization capacity expansion schedules. Practitioners should monitor sovereign review pathway processing times and Suez Canal Economic Zone incentive renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Micro Vials Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Lumbar Puncture Trays and Needles Market