
 Evacuated Drainage Bottles Market | 2026-2036
Evacuated Drainage Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Evacuated Drainage Bottles Market Insights
Polypropylene is shifting from conventional PVC in evacuated drainage bottle construction as hospitals prioritize phthalate-free fluid pathways and lighter transport logistics. BD sustains one of the broadest sterile disposable portfolios across acute care networks. B. Braun Melsungen AG anchors European manufacturing with vertically integrated polymer compounding capabilities. Merit Medical Systems differentiates through interventional radiology-specific drainage configurations.
Evacuated drainage bottles are rigid or semi-rigid fluid collection reservoirs engineered to negative pressure specifications, typically molded from polypropylene or PVC and fitted with vacuum-sealed ports for closed-suction wound drainage following surgery or trauma intervention. Single-use sterile configurations command the dominant volume share given infection control protocols, while reusable systems retain niche positioning in cost-constrained long-term care facilities. Material segmentation reveals polypropylene outpacing PVC growth rates as healthcare systems phase out plasticizers under biocompatibility directives.
FDA 510(k) clearance pathways and EU MDR Class IIa device classifications govern sterilization validation, biocompatibility testing, and clinical performance documentation for market entry. ISO 13485 quality management systems and USP Class VI material standards further constrain supplier qualification timelines. Stakeholders must monitor evolving EPA polymer recycling mandates and EU Green Deal medical waste reduction targets that will reshape material selection and end-of-life disposal economics.
Market Dynamics
EU MDR sterilization validation timelines are compressing supplier qualification windows, forcing manufacturers to consolidate polymer sourcing and accelerate biocompatibility documentation ahead of notified body audits.
Growth Catalysts
- Aging surgical volumes:Japan's super-aged population and Germany's orthopedic procedure backlogs sustain institutional procurement of closed-wound systems in tertiary hospitals.
- Phthalate phase-out mandates:REACH restrictions on plasticizers in medical devices are accelerating polypropylene adoption across European acute care networks.
- Interventional radiology expansion:Percutaneous drainage procedures are creating dedicated product configurations for image-guided fluid management.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer supply disruptions in the US Gulf Coast and Rotterdam clusters compress margin predictability for molders.
- Notified body capacity bottlenecks:EU MDR Class IIa certification queues extend 14-18 months, freezing new product introductions.
- Reusable system substitution:Long-term care facilities in cost-constrained markets retain sterilizable glass-and-rubber configurations.
Strategic Opportunities
- Home care transition:Post-discharge wound management protocols in the United States are opening ambulatory suction device attachments.
- EU Green Deal alignment:Medical waste reduction targets incentivize mono-material polypropylene designs for streamlined recycling.
- Emerging market hospital buildouts:Greenfield surgical capacity in Vietnam and Indonesia lacks established supplier relationships.
Industry Challenges
- Polymer compounding expertise scarcity:USP Class VI validation chemists command premium salaries as FDA 510(k) resubmission rates climb.
- Legacy ERP integration friction:Sterile device track-and-trace mandates require expensive MES layer deployment at mid-cap molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evacuated Drainage Bottles Market |
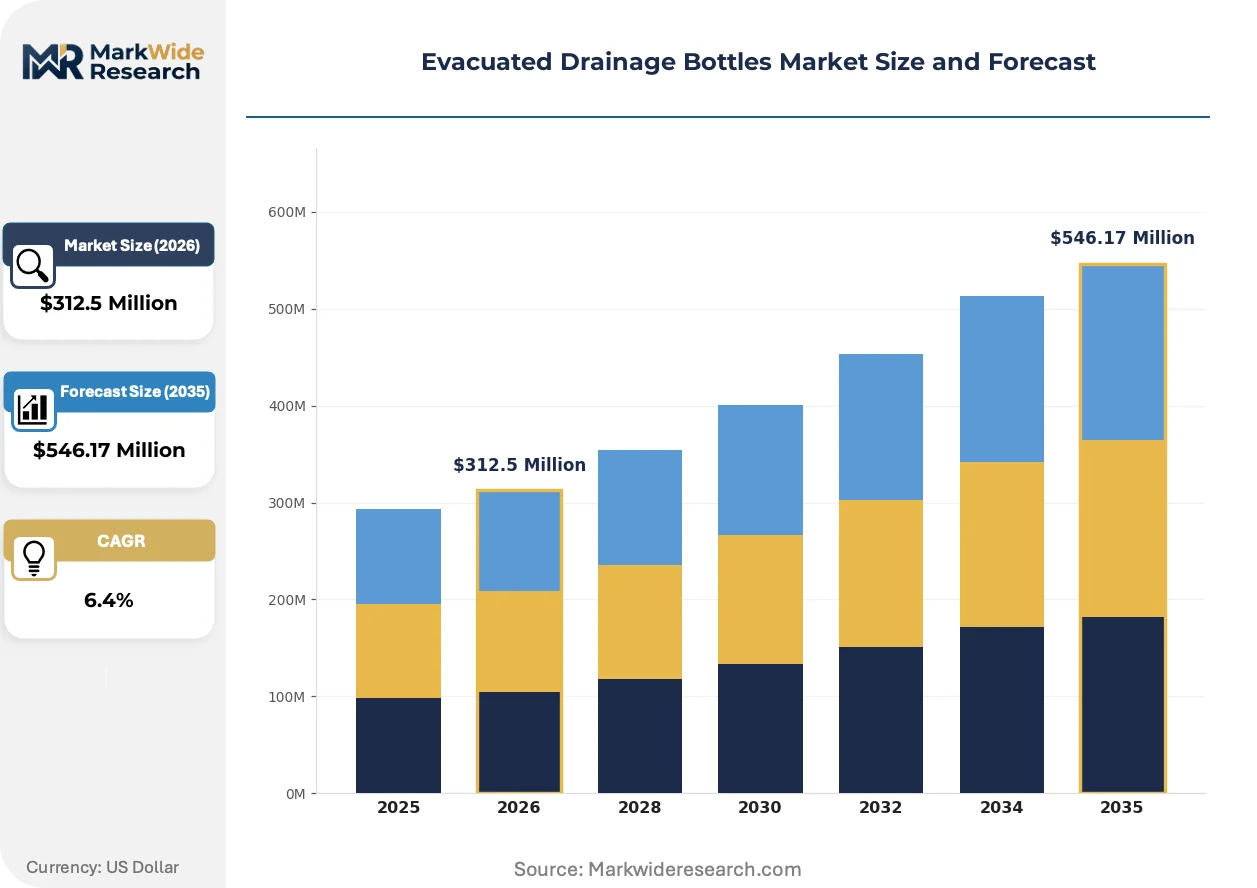
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Reusable, Sterile, Non-Sterile End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Material: Polypropylene, Glass, Silicone, PVC Capacity: 500ml, 1L, 2L, 3L |
| Companies Covered | B. Braun Melsungen AG, BD, Merit Medical Systems, PFM Medical, Jigsaw Medical, Rocket Medical, Sterimed Group, Hospitech, Medinorm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evacuated Drainage Bottles Market Trends and Innovations
Material science advances and regulatory documentation automation are compressing product development cycles while reshaping competitive differentiation around sterilization assurance and sustainability credentials.
Antimicrobial-infused polypropylene formulations are electrifying the barrier properties of fluid pathways. Tertiary hospital procurement committees in the United States and Japan are fast-tracking evaluations of silver-ion or copper-additive grades. This chemistry shift is compressing competitive parity around infection control performance rather than base mechanical specifications.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence for fluid capacity claims. Manufacturers must now commission bioburden studies and shelf-life validation beyond prior technical file norms. Class IIa drainage devices face the steepest documentation burden, with German and French notified bodies issuing major non-conformities on sterilization residuals.
Consolidated purchasing by US hospital networks is unbundling device procurement from traditional distributor markups. IDN supply chain directors in Texas and Florida are negotiating direct sterile disposable contracts with polymer molders. This channel compression is most visible in cardiovascular service lines where procedure volume justifies dedicated SKU rationalization.
Evacuated Drainage Bottles Market Segmentation
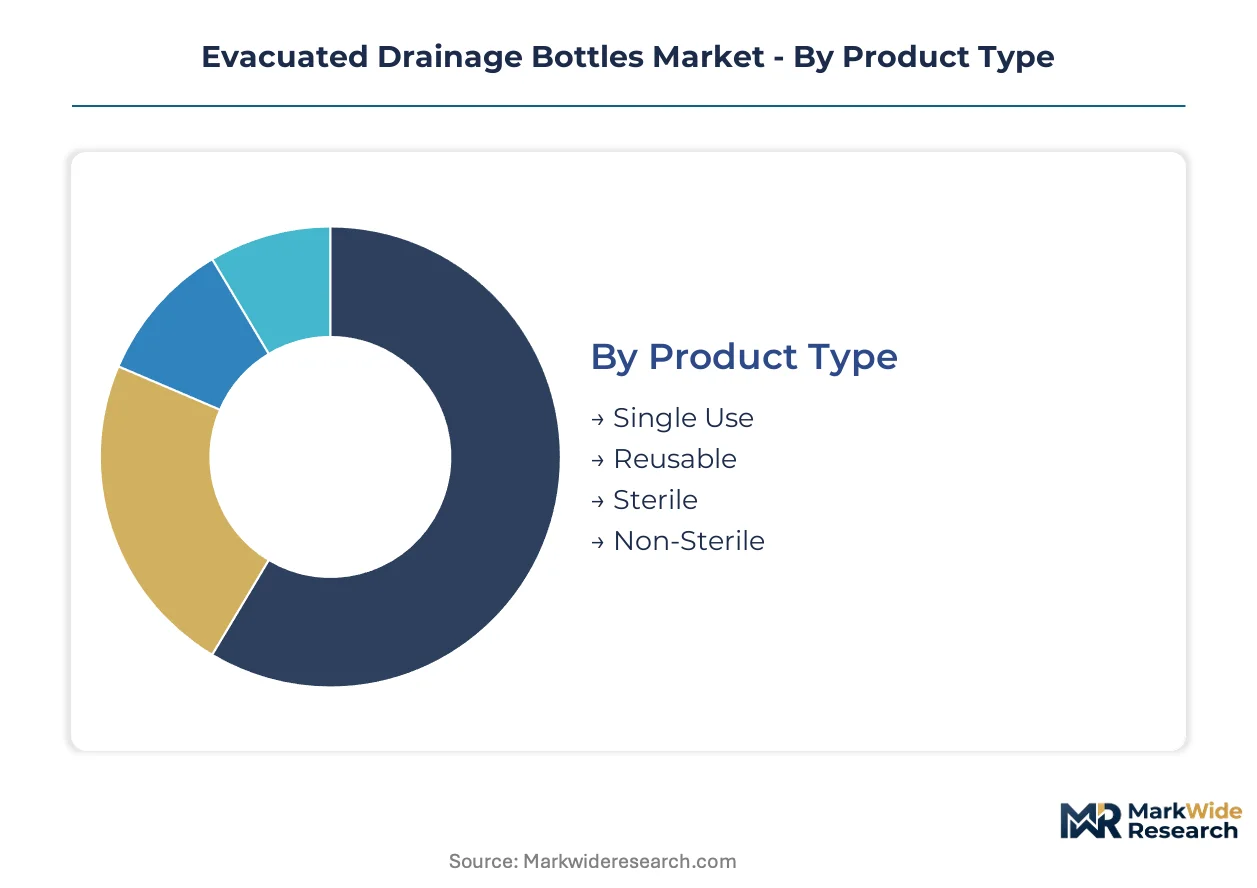
Evacuated drainage bottles segment across multiple dimensions that determine sterilization protocols, procurement economics, and end-use suitability. Material composition and product lifecycle classification drive the steepest price differentials, while capacity specifications align with procedural intensity and patient acuity.
Product Type:
Single-use configurations dominate procurement volumes in tertiary surgical centers where infection control protocols eliminate cross-contamination risk. Reusable systems command premium pricing in cost-constrained settings with validated sterilization infrastructure.
- Single Use:Polypropylene reservoirs sealed at negative pressure specifications eliminate terminal sterilization burden for operating room staff. Demand concentrates in United States cardiovascular service lines where Joint Commission audit frequency makes disposable economics favorable.
- Reusable:Glass-and-rubber assemblies withstand autoclave cycling for 50+ uses in German long-term care networks where municipal waste levies on medical plastics alter total cost calculations.
- Sterile:Gamma-irradiated or ethylene oxide-processed units arrive in peel-pouch packaging for immediate deployment in interventional suites.
- Non-Sterile:Bulk-packaged reservoirs serve institutional sterilization departments with captive ethylene oxide or steam facilities.
Today's leader: Single Use. Tomorrow's challenger: Reusable.
End User:
Acute care institutions generate the highest throughput per bed, while ambulatory and post-acute settings reshape volume distribution through episode-based reimbursement models.
- Hospitals:Tertiary surgical units in Japan and Germany drive bulk procurement of 2L and 3L configurations for orthopedic and thoracic procedures with high expected drainage volumes.
- Clinics:Ambulatory surgery centers in Texas and Florida negotiate direct contracts with polymer molders for procedure-specific SKU rationalization.
- Home Care:Portable suction device attachments enable post-discharge wound management under United States Medicare transitional care protocols.
- Long-Term Care Facilities:Cost-constrained operators in rural markets retain sterilizable glass systems to avoid per-procedure disposable expenditure.
Hospitals anchor current procurement volumes. Home Care represents the steepest expansion trajectory.
Material:
Polymer selection determines biocompatibility certification burden, transport weight, and end-of-life disposal pathways under tightening environmental mandates.
- Polypropylene:Phthalate-free homopolymer grades achieve USP Class VI validation for fluid contact surfaces. REACH restrictions on plasticizers in European medical devices accelerate substitution away from legacy formulations.
- PVC:Plasticized formulations face phase-out pressure from ECHA restrictions while retaining cost advantage in price-sensitive emerging markets.
- Glass:Borosilicate reservoirs withstand repeated autoclaving in German and Japanese facilities with established central sterile supply departments.
- Silicone:Elastomeric tubing and gasket components provide compliance in peristaltic pump interfaces for interventional radiology configurations.
Polypropylene leads material transition. Glass holds defensive position in sterilization-capable installations.
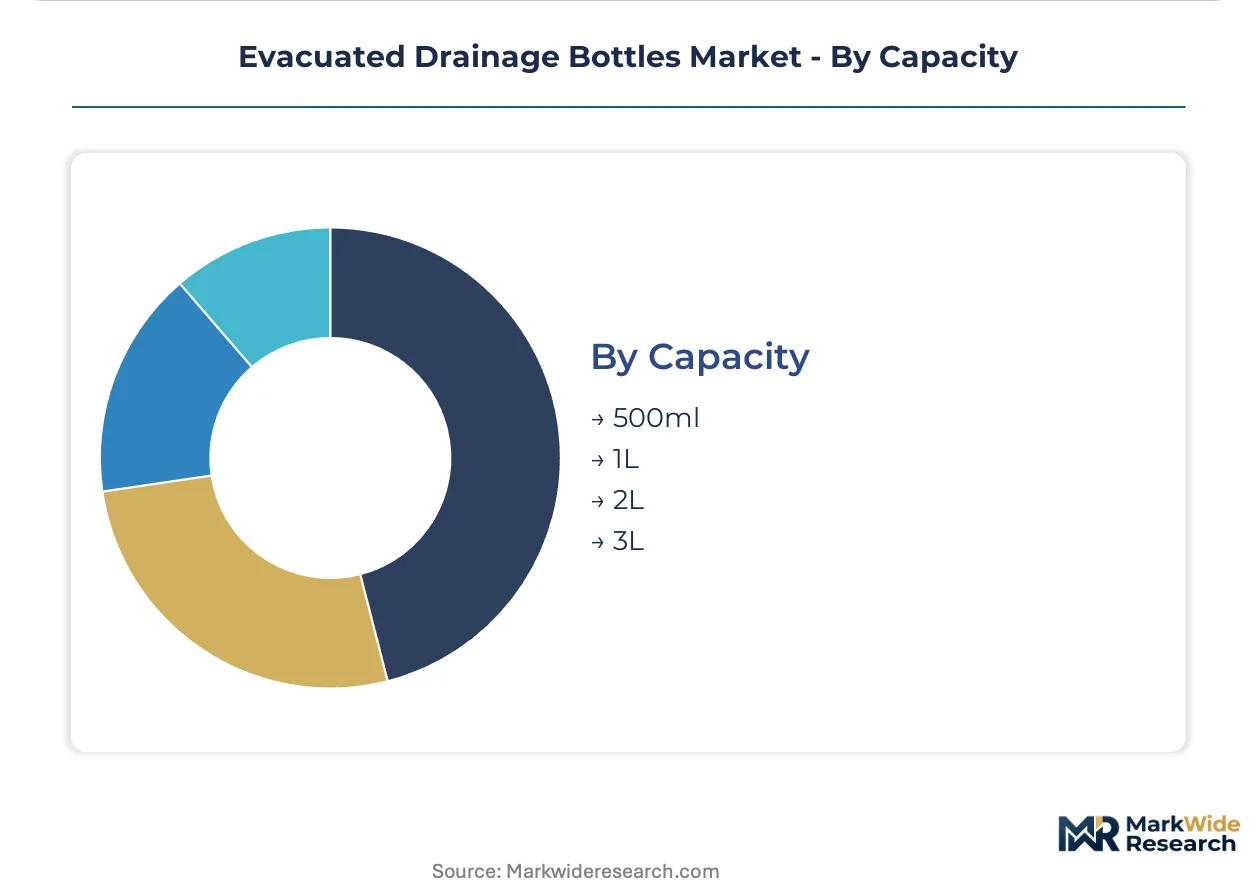
Capacity:
Reservoir sizing aligns with procedural category, expected drainage duration, and nursing workflow optimization for change-out frequency.
- 500ml:Compact reservoirs serve outpatient arthroscopy and breast biopsy procedures with limited expected fluid accumulation.
- 1L:Standard configuration for general surgery wards balancing change-out labor against premature replacement cost.
- 2L:Preferred capacity for orthopedic joint replacement protocols in Japanese super-aged patient populations with higher bleeding risk profiles.
- 3L:Maximum-volume reservoirs address thoracic and cardiovascular procedures with extensive post-operative drainage requirements.
1L specifications dominate current procurement. 2L configurations gain share fastest in aging surgical populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor supplies propylene feedstock to medical-grade polymer molders serving North American hospital networks. Tertiary surgical centers in Texas and Florida anchor procurement volumes for closed-wound drainage systems. Regulatory divergence across FDA, EU MDR, and Japan's PMDA shapes material certification timelines and sterilization validation requirements.
United States
Joint Commission audit frequency drives disposable economics in cardiovascular service lines across Texas and Florida hospital networks. FDA 510(k) clearance pathways govern sterilization validation and biocompatibility documentation for new product introductions. The Houston polymer compounding cluster supplies USP Class VI validated resins to domestic molders serving IDN supply chain directors.
Germany
Orthopedic procedure backlogs in Bavaria and North Rhine-Westphalia sustain institutional procurement of 2L and 3L configurations. EU MDR Class IIa certification queues extend 14-18 months through German and French notified bodies, freezing new product timelines. The Frankfurt-Rhine-Main medical technology corridor hosts vertically integrated polymer operations with captive ethylene oxide sterilization capacity.
Japan
Super-aged patient populations in Kanto and Kansai regions drive higher bleeding risk profiles requiring expanded drainage capacity. PMDA quality management system inspections enforce ISO 13485 compliance for sterile disposable manufacturers. The Osaka medical device manufacturing cluster specializes in precision-molded polypropylene reservoirs for domestic orthopedic procedure volumes.
United Kingdom
NHS procurement frameworks in London and the Midlands consolidate purchasing for closed-wound drainage systems across cardiovascular and thoracic service lines. MHRA post-Brexit regulatory alignment with EU MDR extends sterilization validation documentation requirements for UK manufacturers. The Cambridge-Leicester medical technology corridor hosts specialty molders serving NHS supply chain optimization initiatives.
China
Greenfield surgical capacity expansion in the Yangtze River Delta and Pearl River Delta creates demand for cost-optimized drainage configurations. NMPA Class II medical device registration requires domestic clinical trial data for imported sterile disposable systems. The Shanghai-Suzhou polymer processing corridor supplies phthalate-free polypropylene grades to regional hospital procurement networks.
Evacuated Drainage Bottles Market Competitive Landscape
Global majors compete with regional champions across sterile disposable portfolios and polymer compounding capabilities. The vendor base separates into three tiers: multinational acute care suppliers with broad sterile disposable portfolios, European mid-cap molders with vertically integrated polymer operations, and specialty interventional radiology configuration providers. Strategic differentiation concentrates on sterilization assurance documentation, material sustainability credentials, and direct hospital network contracting relationships.
Among the diversified medical technology majors, BD and B. Braun Melsungen AG exemplify contrasting geographic anchoring strategies. BD represents the North American acute care network penetration archetype through extensive sterile disposable portfolio breadth. B. Braun Melsungen AG occupies the European vertical integration position with captive polymer compounding and sterilization infrastructure. Merit Medical Systems sits within the interventional specialty tier, differentiated through procedure-specific drainage configurations for image-guided fluid management rather than general surgery ward economics.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| BD |
| Merit Medical Systems |
| PFM Medical |
| Jigsaw Medical |
| Rocket Medical |
| Sterimed Group |
| Hospitech |
| Medinorm |
| Others |
Pricing and Supply Chain Analysis
Polypropylene homopolymer adoption in fluid contact surfaces simultaneously compresses per-unit material costs and concentrates molding capacity among USP Class VI validated suppliers. REACH-driven phthalate phase-outs in European acute care networks force hospital procurement committees toward premium-certified configurations, reshaping competitive economics around sterilization documentation rather than base resin pricing.
Pricing Analysis
Propylene monomer cost pass-through from US Gulf Coast and Rotterdam petrochemical clusters governs margin predictability for medical-grade molders. Three-tier pricing structure across premium-certified, standard-validated, and economy-grade tiers separates EU MDR-compliant suppliers from legacy PVC formulators. Cost compression in standard tiers intensifies because IDN supply chain directors negotiate direct contracts bypassing distributor markups. Long-term care facilities in rural markets exhibit highest price sensitivity, while Japanese tertiary surgical centers prioritize infection control performance over per-unit expenditure.
Supply Chain Analysis
USP Class VI and ISO 13485 certification gating restricts qualified polymer compounders to the Houston corridor, Frankfurt-Rhine-Main medical technology cluster, and Osaka precision molding hub. Medical-grade polypropylene feedstock draws from propylene monomer supplies anchored in US Gulf Coast petrochemical infrastructure and Rotterdam refining complexes. Single-source vulnerability concentrates in gamma irradiation sterilization capacity controlled by limited notified body-approved facilities. Distribution runs through IDN central procurement offices and GPO contract frameworks rather than traditional medical-surgical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Evacuated drainage bottles constitute a late-cycle quality story as post-operative infection control protocols harden around antimicrobial-infused polypropylene specifications. Japanese super-aged surgical populations and German orthopedic backlogs sustain premium procurement of 2L and 3L validated configurations.
For Market Incumbents: Anticipate EU MDR sterilization residual scrutiny by accelerating bioburden study commissioning ahead of notified body audits. Consolidate polymer sourcing relationships with Houston and Frankfurt-Rhine-Main compounders to compress qualification timelines. Defensive positioning requires backward integration into captive ethylene oxide sterilization capacity or strategic partnerships with gamma irradiation facilities facing 14-18 month certification queues. For New Entrants and Emerging Players: Enter via home care portable suction device attachments for post-discharge wound management under United States Medicare transitional care protocols. Target ambulatory surgery centers in Texas and Florida negotiating direct sterile disposable contracts outside traditional GPO frameworks. White-space concentration exists in interventional radiology-specific configurations for image-guided percutaneous drainage procedures. For Investors and Strategic Acquirers: Valuations sit cheapest among European mid-cap molders with vertically integrated polymer compounding capabilities and pending EU MDR Class IIa certifications. Long-term viability over the analysis window hinges on mono-material polypropylene designs aligned with EU Green Deal medical waste reduction targets. Monitor antimicrobial additive regulatory approval timelines as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses sterilization validation timelines ahead of notified body capacity constraints. |
| CE Marking Pathway Investment | Secures EU MDR Class IIa certification for antimicrobial-infused polypropylene configurations. |
| Hospital System Partnership | Enables direct IDN contracting in Texas and Florida cardiovascular service lines. |
| Backward Integration into Polymer Compounding | Captures USP Class VI resin supply security against propylene monomer volatility. |
| Reimbursement Strategy Development | Aligns home care portable device attachments with Medicare transitional care protocols. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down polymer compounding capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sterile supply department directors combined with secondary validation from FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and propylene monomer trade flow data. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrix framing connects procedural volume assumptions to material consumption coefficients across single-use, reusable, sterile, and non-sterile product configurations. Segmentation dimensions modeled include material composition, capacity specification, end-user setting, and regional regulatory cluster throughout the projection horizon. CAGRs derive from surgical procedure volume trajectories, aging demographic profiles, and polymer substitution elasticity parameters rather than extrapolated historical trends.
Inputs from hospital procurement databases and polymer compounding facility records were available through the study window; gaps in real-time notified body queue length data introduce uncertainty bands around EU MDR certification timeline assumptions. Forecasts reflect documented sterilization validation requirements, REACH plasticizer restriction implementation schedules, and IDN consolidation patterns. A model refresh is warranted upon material change in FDA 510(k) clearance velocity or EU MDR notified body capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Autoclaving Trays Market