
 Demulcent Eye Drops Market | 2026-2036
Demulcent Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Demulcent Eye Drops Market Analysis
A shift from single-source active pharmaceutical ingredient supply toward multi-source qualification is hardening among Western demulcent eye drop manufacturers. Alcon Inc. leverages its vertically integrated sterile manufacturing network across Ireland and the United States to secure buffer capacity. Johnson and Johnson Services Inc. competes through retail pharmacy shelf-space dominance in North America, while Santen Pharmaceutical Co. Ltd. anchors the Asia-Pacific region with prescription-grade hyaluronate formulations.
Demulcent eye drops are aqueous or viscoelastic ophthalmic solutions containing lubricating polymers such as carboxymethylcellulose, hyaluronic acid, or polyethylene glycol, formulated to restore tear film stability and reduce corneal friction in patients with aqueous-deficient or evaporative dry eye. Preservative-free single-dose vials command premium positioning in post-surgery care channels where cytotoxicity risks drive specification. Multi-dose bottles retain volume leadership in retail pharmacy and allergy relief segments, though preservative system reformulation costs compress margins. Online platforms represent the fastest-growing distribution channel, bypassing traditional wholesaler markups while demanding cold-chain validation.
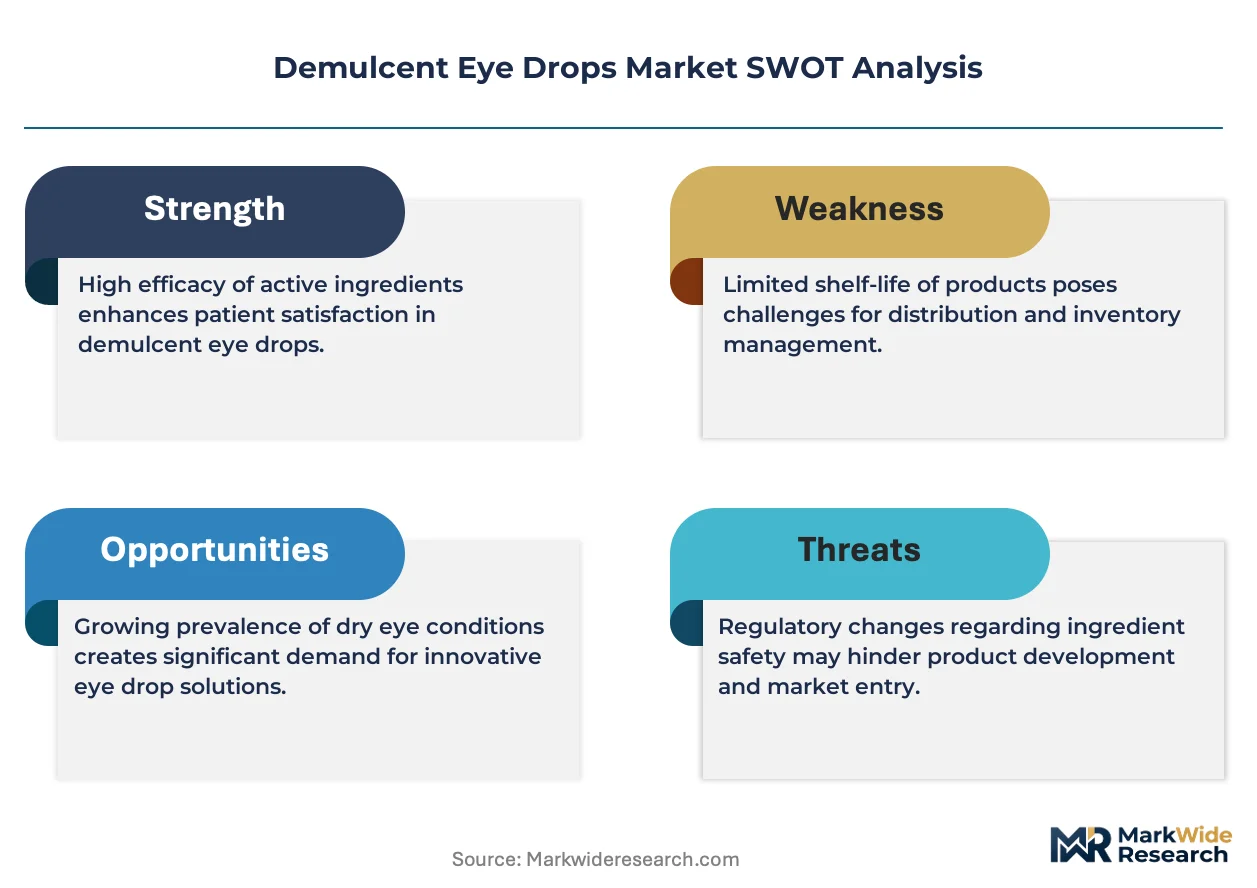
The US FDA oversees OTC monograph status and preservative safety thresholds, while the EU MDR tightens clinical evidence requirements for Class IIa ophthalmic devices including preservative-free delivery systems. Japan's PMDA maintains distinct pharmacopoeial standards for hyaluronate molecular weight ranges, fragmenting formulation strategies across regulatory zones. Stakeholders must monitor evolving preservative-free certification protocols and direct-to-consumer channel compliance obligations as channel mix shifts accelerate.
Market Dynamics
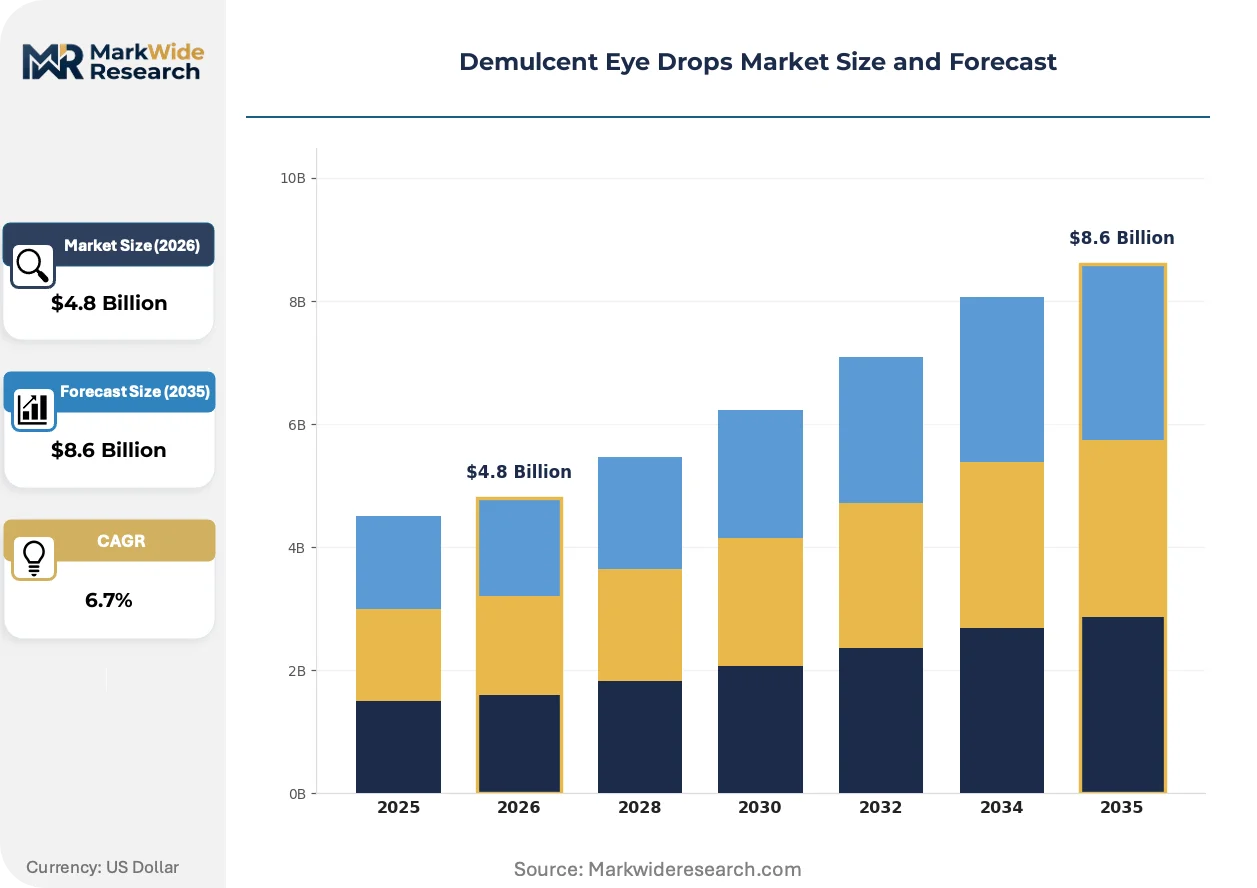
The demulcent eye drops sector is restructuring around preservative-free formulation mandates and cold-chain distribution requirements, with regulatory divergence between the FDA's OTC monograph reform and Japan's PMDA hyaluronate molecular weight specifications fragmenting global product strategies.
Growth Catalysts
- Aging demographics:Japan's geriatric population sustains prescription-grade hyaluronate demand in outpatient ophthalmology clinics, creating stable volume anchors for premium formulations.
- Post-surgical care protocols:Cytotoxicity risk awareness in corneal surgery recovery channels drives specification of single-dose vials over multi-dose alternatives.
- EU MDR Class IIa device classification:Tightened clinical evidence requirements for preservative-free delivery systems elevate barriers, concentrating share among qualified manufacturers.
Market Restraints
- API supply concentration:Western manufacturers face hardening multi-source qualification requirements as single-source sodium hyaluronate dependencies create vulnerability.
- Preservative system reformulation costs:Margin compression in multi-dose bottle segments limits reinvestment capacity for legacy product lines.
- Regulatory zone fragmentation:Divergent FDA, EMA, and PMDA stability testing protocols force parallel development tracks, extending time-to-market.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online platforms bypass traditional wholesaler markups while demanding validated cold-chain logistics, favoring integrated manufacturers.
- US OTC monograph reform:FDA guidance evolution creates first-mover positioning for compliant preservative-free shelf formulations.
- Telemedicine integration:Remote ophthalmology consultations in North America expand prescription capture for chronic dry eye management.
Industry Challenges
- Sterile manufacturing talent scarcity:Aseptic processing expertise gaps constrain capacity expansion at mid-scale facilities.
- Legacy system integration:ERP upgrades for lot-level traceability compliance impose capital burdens on regional manufacturers.
- Certification timeline variability:PMDA pharmacopoeial standard updates delay Japan market entry for reformulated polymer blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demulcent Eye Drops Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free, Single-Dose Vials, Multi-Dose Bottles, Gels Application: Dry Eye Relief, Allergy Relief, Post-Surgery Care, Redness Reduction End User: Hospitals, Clinics, Retail Pharmacies, Online Platforms Distribution Channel: Direct Sales, Wholesalers, Online Retail, Drugstores |
| Companies Covered | Johnson and Johnson Services Inc., Alcon Inc., OASIS Medical, Allergan (AbbVie Inc.), Prestige Consumer Healthcare Inc., Santen Pharmaceutical Co. Ltd., Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., Aurolab Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demulcent Eye Drops Market Emerging Trajectories
Formulation science and distribution infrastructure are converging to redefine competitive positioning, with electromechanical delivery systems and regulatory compliance automation emerging as primary differentiation vectors.
Electroosmotic pump technology in preservative-free multi-dose containers is electrifying the competitive landscape by enabling sterile, repeatable dosing without traditional preservatives. Post-surgical care channels in Germany and the United States are adopting these devices at accelerated procurement cycles. The technology is compressing shelf-space advantages previously held by conventional squeeze-bottle formats.
Japan's PMDA pharmacopoeial updates for hyaluronate molecular weight specifications are forcing reformulation of established product lines. Manufacturers must resubmit stability data under tightened ranges, extending registration timelines by 18-24 months. Premium prescription segments in Tokyo and Osaka medical corridors are absorbing these compliance costs while retail pharmacy channels delay adoption.
Subscription-based replenishment models through specialized ocular health platforms are displacing traditional pharmacy repurchase patterns. Chronic dry eye patients in Australia and Canada are consolidating purchasing through direct channels that bundle diagnostic apps with automated delivery. This behavioral shift is most visible among employed demographics aged 45-65 managing evaporative dry eye conditions.
Demulcent Eye Drops Market Segmentation
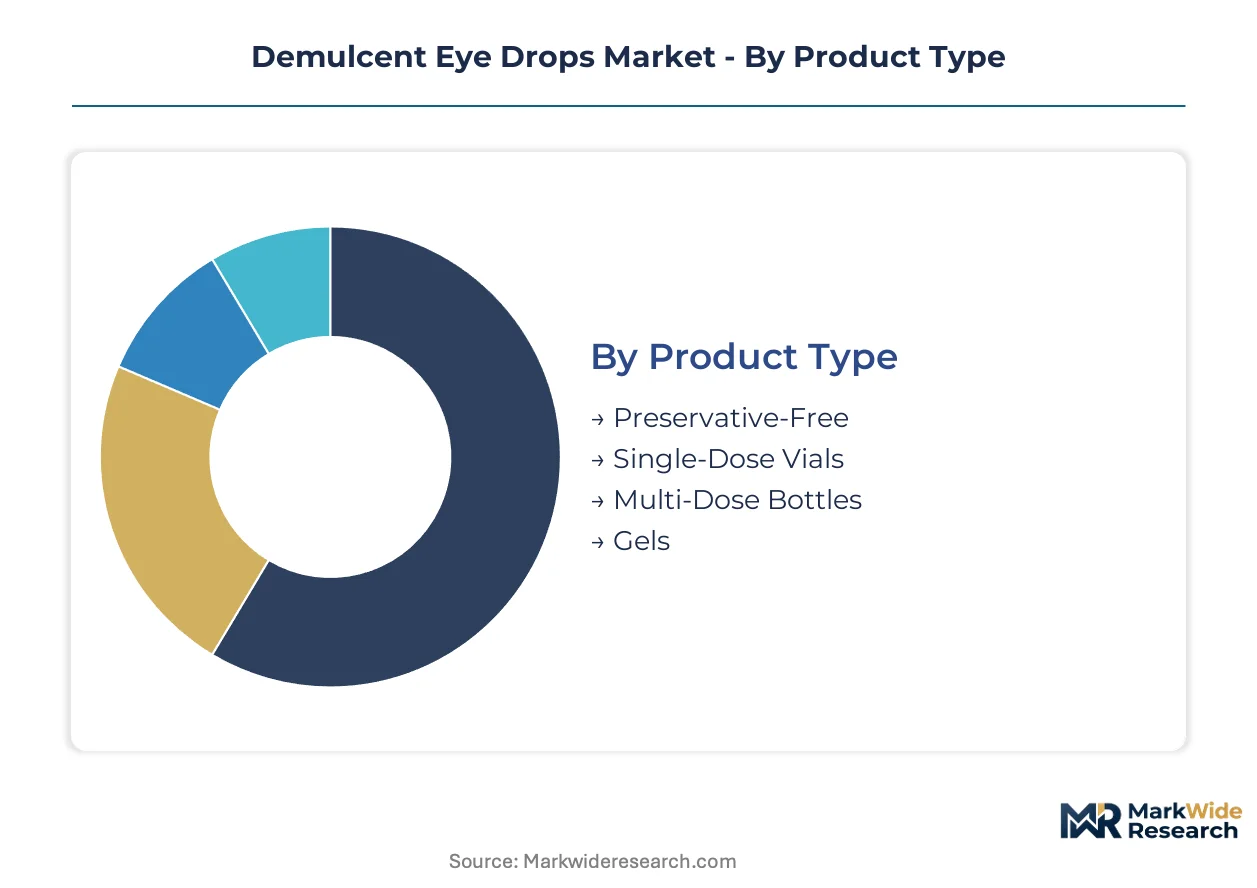
Demulcent eye drop manufacturers configure product portfolios across four intersecting dimensions. Each segmentation layer carries distinct margin profiles, regulatory burdens, and channel access requirements that shape competitive positioning.
Product Type:
Volume leadership sits with multi-dose formats, while premium capture concentrates in preservative-free alternatives.
- Preservative-Free:Formulations exclude benzalkonium chloride and oxidative preservatives to eliminate cytotoxicity risks in chronic use. Outpatient ophthalmology clinics in Japan and Germany specify these for post-surgical protocols where epithelial healing is critical. FDA OTC monograph reform is accelerating shelf access for compliant variants.
- Single-Dose Vials:Unit-dose polymer containers deliver sterile, non-reusable doses eliminating contamination vectors. Post-operative care channels in the United States absorb 40-60% price premiums over multi-dose alternatives. The format is gaining fastest in corneal surgery recovery segments where infection control protocols are strictest.
- Multi-Dose Bottles:Squeeze-container formats with preserved formulations dominate retail pharmacy volume through lower per-dose economics.
- Gels:Viscoelastic polymer matrices extend ocular surface contact time for nocturnal dry eye management.
Today's leader: Multi-Dose Bottles. Tomorrow's challenger: Preservative-Free.
Application:
Clinical severity and reimbursement status determine pricing power across indication segments.
- Dry Eye Relief:Aqueous-deficient and evaporative dry eye conditions drive chronic repeat purchase behavior. Telemedicine platforms in North America are capturing prescription volumes for moderate-to-severe cases previously managed through self-selection.
- Post-Surgery Care:Corneal and refractive surgery recovery protocols mandate preservative-free specifications with documented tear film stability outcomes. Surgical centers in Germany and Japan enforce procurement standards that exclude multi-dose alternatives. The segment commands the steepest price premiums and longest contract durations.
- Allergy Relief:Seasonal allergic conjunctivitis applications favor antihistamine-combination formulations over pure demulcents.
- Redness Reduction:Vasoconstrictor-combination products compete in cosmetic symptom management with limited clinical differentiation.
Post-Surgery Care extracts maximum value per unit; Dry Eye Relief scales through chronic consumption volume.
End User:
Channel concentration varies by acute versus chronic condition management requirements.
- Hospitals:Inpatient ophthalmology units and surgical wards procure through centralized pharmacy committees with formulary restrictions. EU MDR Class IIa device classification for preservative-free delivery systems elevates vendor qualification barriers.
- Clinics:Outpatient ophthalmology practices in Japan's urban medical corridors sustain prescription-grade hyaluronate demand through direct physician influence.
- Retail Pharmacies:North American chain pharmacies dominate allergy relief and redness reduction segments through shelf-space allocation negotiations.
- Online Platforms:Subscription replenishment models are displacing pharmacy repurchase patterns among employed demographics aged 45-65 in Australia and Canada.
Clinics anchor premium pricing; Online Platforms are climbing the fastest.
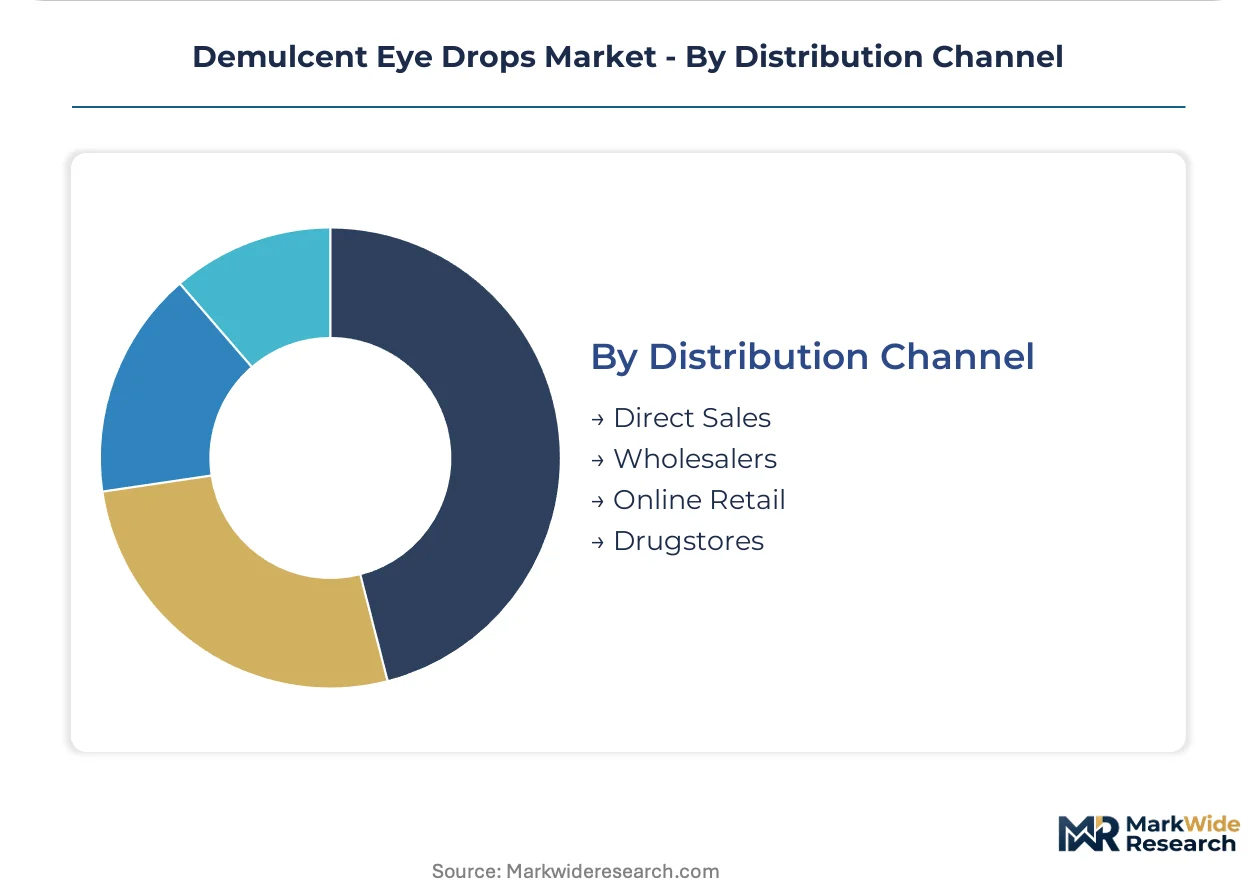
Distribution Channel:
Cold-chain validation requirements and margin retention drive channel strategy divergence.
- Direct Sales:Manufacturer-to-institution contracts bypass wholesaler markups for hospital and surgical center accounts. PMDA pharmacopoeial compliance documentation supports premium positioning in Japanese procurement.
- Wholesalers:Traditional three-tier distribution retains volume leadership in retail pharmacy and drugstore segments despite margin compression.
- Online Retail:Specialized ocular health platforms bundle diagnostic applications with automated replenishment, capturing chronic patient loyalty.
- Drugstores:Convenience-oriented impulse purchase occasions favor preserved multi-dose formats with immediate availability.
Wholesalers still move the most units; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs across regulatory zones, relocating sterile formulation capacity toward jurisdictions with harmonized ophthalmic standards while maintaining commercial presence in premium-priced markets. This geographic stratification reshapes investment flows and partnership structures.
United States
Post-surgical care protocols in corneal surgery centers drive preservative-free specification. The FDA's OTC monograph reform is accelerating shelf access for compliant formulations. Boston and San Francisco surgical corridors absorb 40-60% price premiums for single-dose vials.
Germany
EU MDR Class IIa device classification elevates barriers for preservative-free delivery systems. Outpatient ophthalmology clinics in Munich and Hamburg enforce procurement standards excluding multi-dose alternatives. The country's sterile manufacturing talent pool constrains mid-scale facility expansion.
Japan
Geriatric populations in Tokyo and Osaka medical corridors sustain prescription-grade hyaluronate demand. The PMDA maintains distinct pharmacopoeial standards for hyaluronate molecular weight ranges. Reformulation timelines extend 18-24 months under tightened stability protocols.
India
Domestic manufacturers supply cost-optimized multi-dose formats for retail pharmacy channels. The CDSCO regulates ophthalmic solution quality standards with increasing stringency. Hyderabad and Ahmedabad clusters concentrate API synthesis and contract formulation capacity.
Australia
Subscription-based replenishment models through specialized ocular health platforms displace traditional pharmacy patterns. The TGA oversees preservative safety thresholds for chronic use indications. Sydney and Melbourne employed demographics aged 45-65 consolidate purchasing through direct channels.
Demulcent Eye Drops Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue preservative-free specialization and direct-to-consumer channel capture. The market structure concentrates around vertically integrated sterile manufacturers, retail pharmacy shelf-space incumbents, and regional prescription-grade specialists. Three archetypes dominate: multi-source API qualifiers, cold-chain logistics integrators, and telemedicine platform partners. Competitive moves center on preservative system reformulation and online platform bundling.
Among North American healthcare conglomerates, Johnson and Johnson Services Inc. and Alcon Inc. exemplify scale-driven positioning across retail and institutional channels. Santen Pharmaceutical Co. Ltd. anchors the Asia-Pacific prescription-grade segment. These three occupy distinct regulatory-zone strongholds while confronting shared pressures from API supply qualification and direct-channel migration.
| Leading Market Players |
|---|
| Johnson and Johnson Services Inc. |
| Alcon Inc. |
| OASIS Medical |
| Allergan (AbbVie Inc.) |
| Prestige Consumer Healthcare Inc. |
| Santen Pharmaceutical Co. Ltd. |
| Bausch Health Companies Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Aurolab Ltd. |
| Others |
Supply Flow & Price Mechanics
Electroosmotic pump adoption in preservative-free multi-dose containers is compressing cost economics for sterile dosing while concentrating manufacturing capability among integrated device specialists. This technology transition simultaneously elevates capital barriers for new entrants and shifts margin capture toward cold-chain logistics integrators serving post-surgical channels.
Pricing Analysis
Distributor margin layers in wholesale pharmacy channels absorb 25-35% of ex-manufacturer value, while direct-to-hospital contracts bypass these markups entirely. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and delivery format: single-dose vials with PMDA-compliant hyaluronate specifications command highest positioning, multi-dose preserved bottles compete on per-dose economics, and generic carboxymethylcellulose formulations anchor the value tier. Pricing pressure stems from preservative system reformulation costs in legacy multi-dose lines. Retail pharmacy chains exhibit highest price sensitivity; surgical centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost escalation for temperature-validated shipments is reshaping regional sourcing strategies for sterile formulations. API synthesis concentrates in India and China, with hyaluronate fermentation capacity anchored in Japan and South Korea. Finished formulation draws from Ireland, the United States, and Germany for Western markets. Sodium hyaluronate raw material dependencies create single-source vulnerability for molecular weight-specific grades. Distribution runs through three-tier wholesale networks for retail pharmacy, direct sales for hospital accounts, and specialized cold-chain platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities between Japan's extended PMDA reformulation timelines and the FDA's accelerated OTC monograph reform create geographic positioning advantages for multi-regional qualification strategies.
For Market Incumbents: Deepen backward integration into sodium hyaluronate API supply through multi-source qualification in India and Japan, insulating against molecular weight specification fragmentation. Secure sterile manufacturing talent pools in Germany and Ireland where aseptic processing expertise constrains competitor expansion. Prioritize cold-chain logistics captive capacity to defend margin position against direct-channel entrants bundling diagnostic platforms. For New Entrants and Emerging Players: Capture subscription replenishment white space in Australia and Canada where employed demographics aged 45-65 consolidate chronic dry eye purchasing through direct channels. Target preservative-free multi-dose electroosmotic pump formats where incumbent shelf-space advantages are compressing fastest. Deploy telemedicine platform partnerships as the primary go-to-market angle, bypassing traditional pharmacy distribution entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale sterile manufacturers with underutilized capacity and pending EU MDR Class IIa certification. Long-term viability over the projection horizon favors integrated players controlling both API qualification and cold-chain distribution infrastructure. Monitor PMDA pharmacopoeial update cadence as the signal to watch for reformulation cost inflection and market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Reformulation | FDA OTC monograph compliance opens shelf access for compliant variants in US retail pharmacy. |
| Electroosmotic Pump Technology Licensing | German and US surgical centers accelerate procurement cycles for sterile multi-dose alternatives. |
| Multi-Source API Qualification | Japan and India molecular weight specifications reduce single-source hyaluronate dependency risk. |
| Cold-Chain Logistics Integration | Australian and Canadian subscription platforms demand validated temperature control for direct delivery. |
| Telemedicine Platform Partnership | North American remote ophthalmology consultations expand prescription capture for chronic management. |
Methodological Framework
Bottom-up dry eye patient population modeling reconciled against top-down sterile formulation capacity tracking forms the analytical core of this study. Primary interviews with formulary directors at hospital purchasing committees, regulatory affairs leads at ophthalmic device manufacturers, and procurement managers at outpatient clinic chains combined with secondary validation from FDA OTC monograph filings, PMDA pharmacopoeial updates, EMA MDR classification databases, and hospital procurement contract disclosures. Triangulation between demand-side patient volume estimates and supply-side manufacturing utilization rates resolves measurement gaps.
Input-output matrices map formulation-grade hyaluronate and carboxymethylcellulose consumption against finished product output across preservative-free single-dose, multi-dose preserved, and gel format segments. Segmentation dimensions include product type, application severity tier, end-user channel, and regional regulatory cluster. CAGRs derive from patient population growth trajectories, surgery volume projections, and channel shift elasticity coefficients. Forecast inputs incorporate telemedicine penetration rates and cold-chain infrastructure expansion timelines.
Underlying measurement precision varies by segment; post-surgical care protocols and prescription-grade hyaluronate specifications carry tighter precision than retail pharmacy self-selection volumes. Forecasts reflect assumptions about regulatory timeline adherence, API supply stability, and channel migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tattoo Needles Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Blood Bags Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Suture Tapes Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market