
 Global Povidone Iodine Market | 2026-2036
Global Povidone Iodine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Povidone Iodine Market Foresight
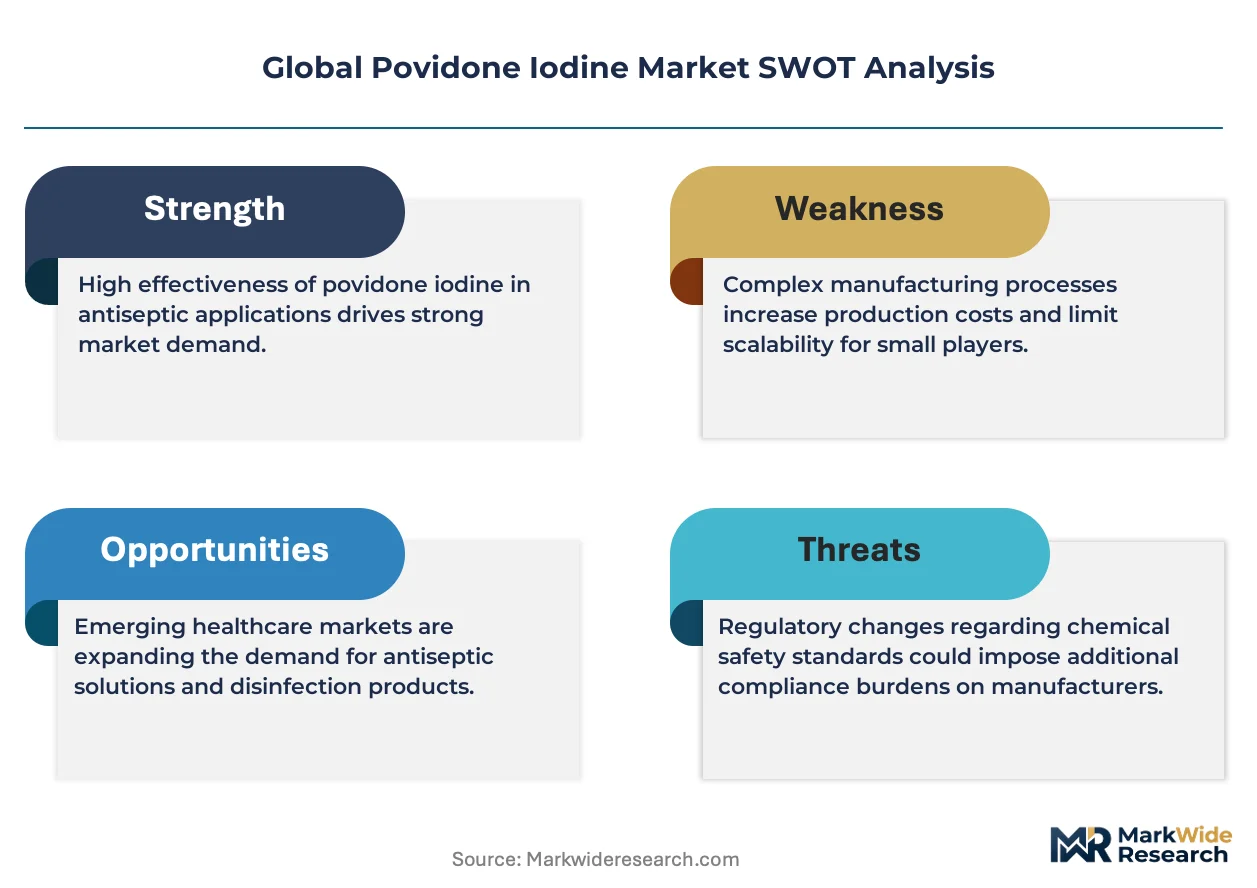
Aftermarket service revenue for infection control protocols is tilting toward integrated supply contracts that bundle povidone iodine products with compliance auditing. BASF leverages its backward integration into pharmaceutical-grade polymer supply to secure raw material cost advantages across European hospital networks. Evonik Industries AG sustains R&D intensity in high-purity povidone formulations for ophthalmic and surgical applications where contamination thresholds sit below standard grades.
Povidone iodine is a water-soluble complex formed from the polymer polyvinylpyrrolidone and elemental iodine, typically containing 9.0% to 12.0% available iodine that releases gradually upon contact with skin or mucous membranes to exert broad-spectrum microbicidal activity. The compound serves as a topical antiseptic in preoperative skin preparation, wound irrigation, and mucosal disinfection where sustained iodine release balances efficacy against tissue irritation. Among product types, surgical scrub formulations dominate hospital procurement volumes while wound dressing segments capture expanding margin pools as advanced hydrogel-iodine combinations displace conventional gauze. On the application side, antiseptic treatment anchors current demand but oral care applications are gaining fastest as dental clinics adopt povidone iodine rinses for peri-implantitis management.
The FDA regulates povidone iodine as an over-the-counter topical antiseptic under its monograph system, while the EPA oversees environmental release thresholds for iodine-based biocides in manufacturing effluent. EMA's Medical Device Regulation and REACH compliance requirements in Europe are raising barriers for non-certified suppliers and redirecting procurement toward documented purity grades. Stakeholders must monitor evolving biocidal product authorizations under the EU BPR and state-level antiseptic formularies in the United States, as regulatory divergence between jurisdictions threatens to fragment formulation standards and complicate multinational supply strategies.
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks, forcing povidone iodine suppliers to bundle antiseptic formulations with compliance documentation and staff training services to retain contract access.
Growth Catalysts
- Surgical volume expansion:Rising procedure counts in ambulatory surgery centers across the United States and Germany are amplifying preoperative skin preparation demand.
- REACH compliance escalation:ECHA's tightening biocidal substance authorization timelines are filtering out non-compliant suppliers and redirecting hospital procurement toward documented purity grades.
- Polymer science advances:Controlled-release hydrogel matrices are extending iodine availability windows in wound dressings, opening premium positioning in post-acute care settings.
Market Restraints
- Elemental iodine price volatility:Chilean and Japanese iodine extraction concentration exposes formulators to raw material cost swings that compress margin pools.
- Chlorhexidine substitution:Surgical scrub segments in NHS England procurement are experiencing protocol-level displacement by alcohol-chlorhexidine combinations in specific procedure categories.
- EPA effluent thresholds:Manufacturing discharge limits for iodine-bearing wastewater are raising capital requirements for US-based production facilities.
Strategic Opportunities
- Tier-two Indian cities:Government healthcare infrastructure investments under the Ayushman Bharat scheme are creating first-time institutional antiseptic demand in previously underserved urban corridors.
- Peri-implantitis protocols:Dental clinic adoption of povidone iodine rinses for implant maintenance is opening a high-margin consumption channel with recurring revenue characteristics.
- WHO prequalification pathway:Inclusion on the Essential Medicines List for topical antiseptics is enabling access to multilateral procurement pools for humanitarian and developing country supply.
Industry Challenges
- Pharmaceutical-grade polymer sourcing:Securing consistent polyvinylpyrrolidone supply meeting USP-NF and EP monograph specifications requires multi-year supplier qualification timelines.
- EU MDR technical documentation:Medical device classification for advanced wound dressings demands clinical evidence packages that extend time-to-market by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Povidone Iodine Market |
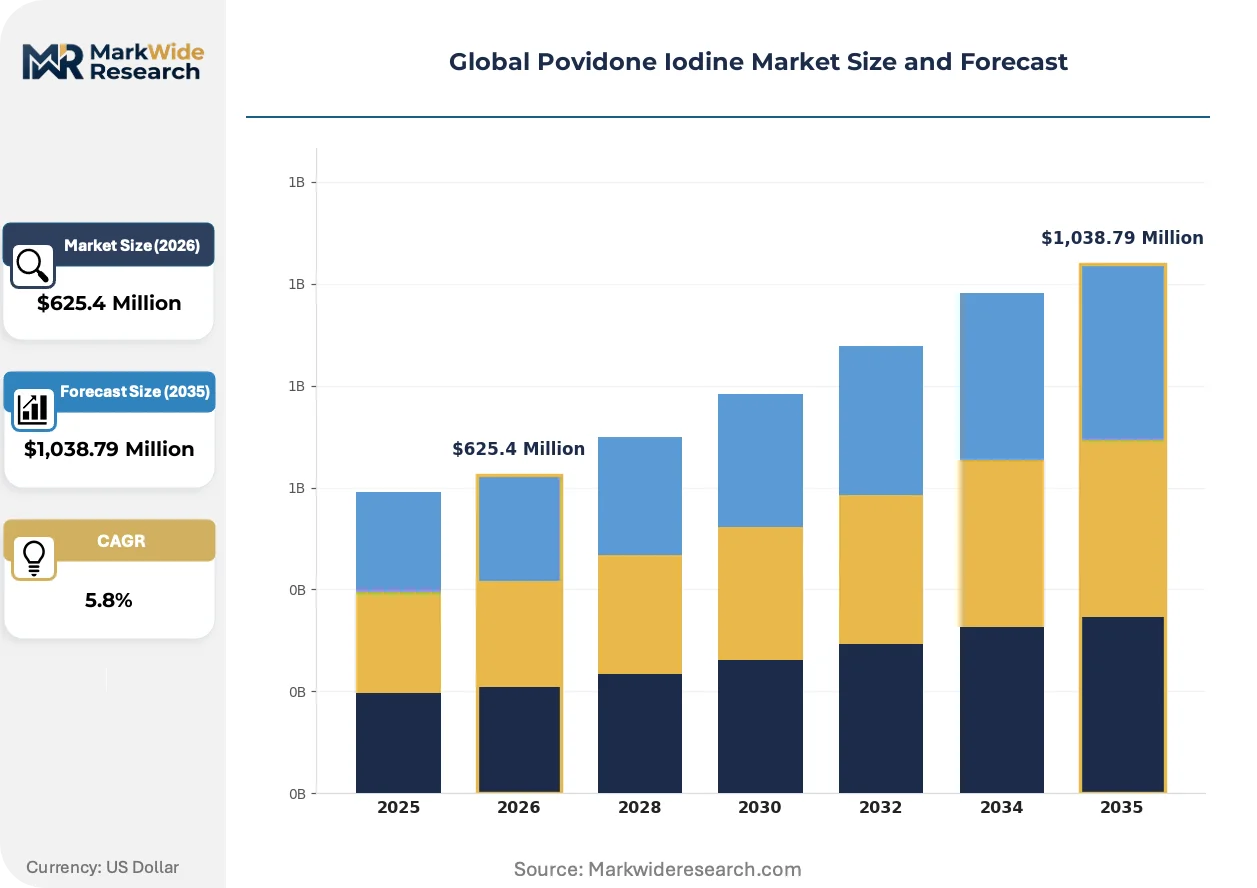
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,038.79 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solution, Surgical Scrub, Wound Dressing, Ointment, Surgical Packs Application: Antiseptic Treatment, Skin Disinfection, Oral Care, Surgical Procedures, Gynecological Care End User: Hospitals, Clinics, Ambulatory Care Centers, Dental Clinics, Nursing Homes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Medical Stores, Wholesale Distributors |
| Companies Covered | Avrio Health L.P., 3M, BASF, Boai NKY Pharmaceuticals Ltd., Glide Chem Private Limited, Lasa Supergenerics Ltd., Samrat Pharmachem Limited, Evonik Industries AG, Nippon Shokubai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Povidone Iodine Market Shifts & Advancements
Formulation science and procurement digitization are converging to reshape how antiseptic efficacy is verified, priced, and delivered across institutional channels.
Smart packaging embedded with temperature and exposure sensors is digitizing supply chain visibility for povidone iodine products requiring cold-chain integrity. Hospital pharmacy directors in Germany and the Netherlands are piloting these systems to reduce waste from degraded inventory. Real-time tracking is digitizing compliance documentation for joint commission audits and reducing liability exposure from out-of-specification product use.
EMA's Medical Device Regulation implementation is forcing wound dressing manufacturers to reclassify combination products and submit clinical performance data. This regulatory burden is compressing the supplier base toward entities with established quality management systems. Ophthalmic and surgical irrigation segments are experiencing the most acute documentation requirements, with notified body backlogs extending certification timelines.
Integrated supply contracts are replacing transactional purchasing as dominant hospital procurement modality. Group purchasing organizations in the United States are bundling povidone iodine formulations with infection control auditing and staff certification programs. This service-layer attachment is most advanced in California and Texas health systems, where value-based reimbursement metrics reward documented compliance over unit cost minimization.
Global Povidone Iodine Market Segmentation
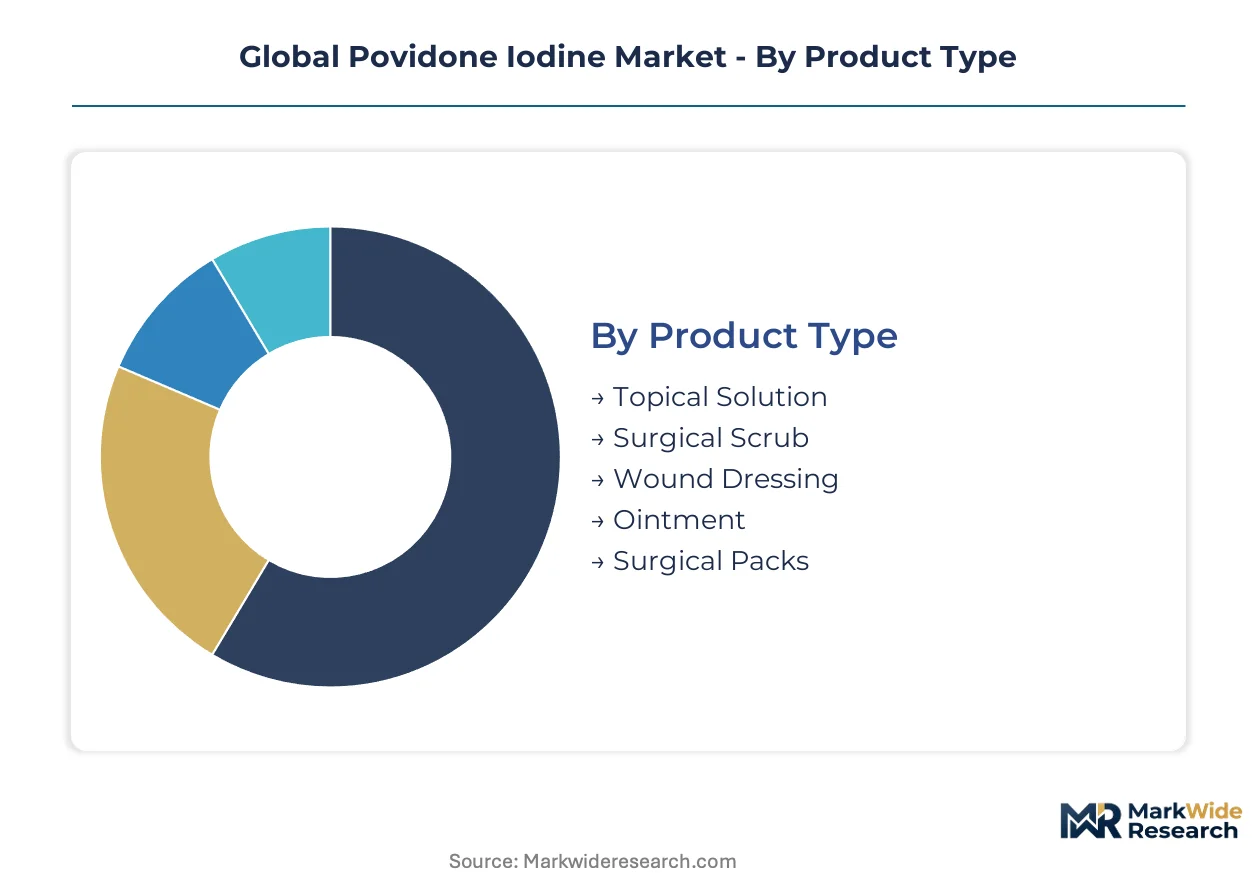
Povidone iodine formulations vary significantly in iodine concentration, viscosity, and delivery mechanism, creating distinct commercial segments that align with specific clinical protocols and procurement channels. Understanding these divisions reveals where margin pools concentrate and which product architectures command pricing power across institutional and retail channels.
Product Type:
Surgical protocols demand graduated iodine release profiles, from rapid-acting skin preparations to sustained-release wound matrices.
- Surgical Scrub:Aqueous or detergent-based formulations containing 7.5% to 10% povidone iodine designed for preoperative hand and forearm antisepsis with persistent antimicrobial activity. Hospital procurement in the United States and Germany concentrates volume here as ambulatory surgery centers multiply and infection control audits intensify.
- Wound Dressing:Hydrogel, foam, or alginate matrices impregnated with povidone iodine for sustained antimicrobial release over 24 to 72 hours in exuding wounds. Post-acute care settings in the United Kingdom and Japan are displacing conventional gauze with these advanced combinations, capturing premium positioning through reduced dressing change frequency.
- Topical Solution:Standard 10% aqueous preparation for general antiseptic application across outpatient and home care settings.
- Ointment:Semisolid petrolatum-based formulation for dry or minimally exuding wounds requiring occlusive coverage.
- Surgical Packs:Pre-sterilized kits bundling povidone iodine products with drapes, gowns, and ancillary supplies for procedural efficiency.
The dominant share belongs to Surgical Scrub, while Wound Dressing is closing the gap fastest.
Application:
Clinical use cases span acute intervention through chronic maintenance, with reimbursement pathways determining commercial priority.
- Antiseptic Treatment:General wound cleansing and minor injury management across emergency departments, urgent care facilities, and home settings. Volume concentrates in India where government healthcare infrastructure investments under Ayushman Bharat are expanding first-time institutional access in tier-two cities.
- Oral Care:Peri-implantitis management and pre-procedural rinsing in dental clinics utilizing 0.5% to 1% povidone iodine solutions. Dental practices in Germany and South Korea are adopting these protocols for implant maintenance, opening recurring revenue channels with above-average margin structures.
- Skin Disinfection:Preoperative preparation of intact skin across surgical and invasive procedure categories.
- Surgical Procedures:Intraoperative irrigation and instrument disinfection in operating theater environments.
- Gynecological Care:Vaginal antisepsis and prenatal perineal preparation in obstetric and gynecological practice.
Antiseptic Treatment retains the largest volume footprint, though Oral Care demonstrates the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply across facility types, from centralized hospital pharmacy systems to fragmented retail clinic purchasing.
- Hospitals:Integrated delivery networks with formulary committees, group purchasing organization contracts, and compliance documentation requirements. NHS England and United States health systems are consolidating purchasing power and demanding bundled supply contracts with audit services attached.
- Dental Clinics:Independent and group practices with direct purchasing authority for specialty antiseptic protocols. Practices in urban Japan and metropolitan India are driving peri-implantitis application growth through continuing education and specialist society recommendations.
- Clinics:Primary care and specialty outpatient facilities with intermediate procurement scale.
- Ambulatory Care Centers:Freestanding surgical and procedural facilities with focused antiseptic needs.
- Nursing Homes:Long-term care facilities managing chronic wound populations with cost-constrained purchasing.
Hospitals command the dominant procurement volume, while Dental Clinics are gaining share fastest.
Distribution Channel:
Channel selection reflects product registration status, cold-chain requirements, and institutional versus consumer end points.
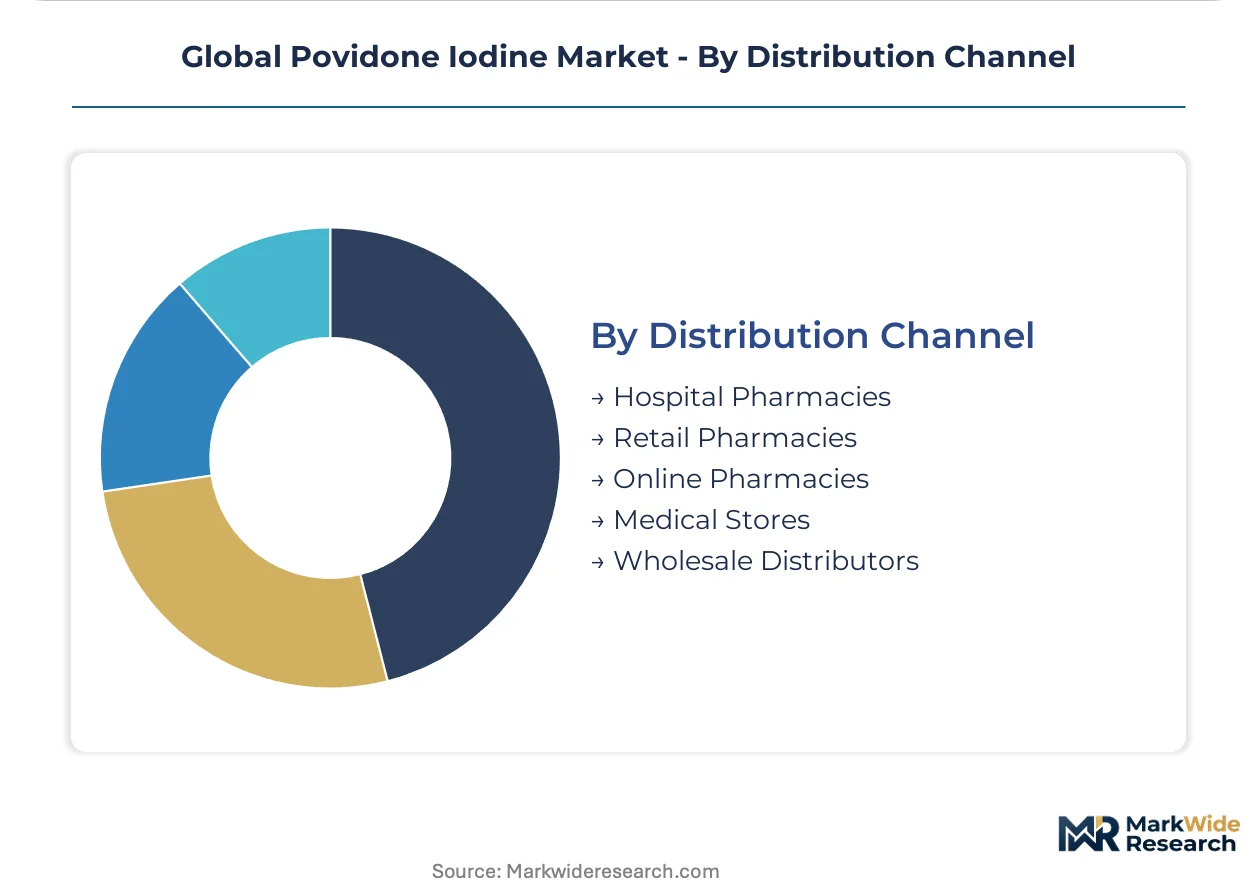
- Hospital Pharmacies:Centralized distribution within health systems managing formulary compliance and inventory tracking. German hospital pharmacy directors are piloting smart packaging with temperature sensors to reduce waste from degraded stock.
- Wholesale Distributors:Regional and national logistics networks serving fragmented retail and institutional accounts. Distributors in India are expanding cold-chain capabilities to reach tier-three cities as government healthcare infrastructure investments accelerate.
- Retail Pharmacies:Community-based outlets serving outpatient prescriptions and over-the-counter demand.
- Online Pharmacies:E-commerce platforms with growing share in consumer-directed topical solution and ointment purchases.
- Medical Stores:Specialized surgical supply retailers serving small clinics and independent practitioners.
Hospital Pharmacies retain the largest channel share, while Wholesale Distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany tolerate premium pricing for documented purity grades, while nursing homes in India prioritize unit cost minimization. This elasticity gap shapes where suppliers invest in compliance documentation versus volume manufacturing.
United States
Ambulatory surgery centers in Texas and Florida are multiplying preoperative skin preparation volumes as outpatient procedure migration accelerates. FDA monograph enforcement and EPA effluent thresholds for iodine-bearing wastewater are raising capital requirements for domestic manufacturers. BASF leverages backward integration into pharmaceutical-grade polymer supply to secure raw material cost advantages across Midwest hospital networks.
Germany
Hospital pharmacy directors in Bavaria and North Rhine-Westphalia pilot smart packaging with temperature sensors to reduce waste from degraded inventory. EMA Medical Device Regulation implementation is compressing the wound dressing supplier base toward entities with established quality management systems. Evonik Industries AG sustains R&D intensity in high-purity povidone formulations for ophthalmic applications where contamination thresholds sit below standard grades.
India
Government healthcare infrastructure investments under Ayushman Bharat are creating first-time institutional antiseptic demand in tier-two cities like Indore and Coimbatore. CDSCO tightening of antiseptic efficacy standards is filtering weaker formulations from government procurement channels. Domestic API production clusters in Gujarat and Maharashtra are accelerating povidone iodine consumption as import substitution policies mature.
Japan
Dental clinics in Osaka and Tokyo are adopting povidone iodine rinses for peri-implantitis management, opening recurring revenue channels with above-average margin structures. PMDA documentation requirements for combination wound dressings are extending certification timelines for foreign suppliers. Nippon Shokubai Co., Ltd. anchors domestic polymer supply chains serving surgical irrigation segments with acute purity specifications.
United Kingdom
NHS England procurement consolidation is experiencing protocol-level displacement of surgical scrubs by alcohol-chlorhexidine combinations in specific procedure categories. MHRA post-Brexit regulatory divergence from EU MDR is complicating multinational supply strategies for wound dressing manufacturers. Post-acute care settings in Greater Manchester and Birmingham are displacing conventional gauze with hydrogel-iodine combinations through reduced dressing change frequency.
Global Povidone Iodine Market Competitive Landscape
Capability concentration sits with specialized polymer-science players; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: integrated chemical majors with captive iodine sourcing, pharmaceutical-grade polymer specialists with formulation expertise, and regional API manufacturers serving price-sensitive procurement channels. Dominant competitive moves include backward integration into pharmaceutical-grade polymer supply and bundling antiseptic products with compliance auditing services to secure hospital contract access.
Among Germany-based diversified chemical producers, BASF and Evonik Industries AG exemplify the capability-intensive tier where polymer science and regulatory documentation converge. BASF occupies a position anchored in backward integration advantages across European hospital networks, while Evonik Industries AG sits within the high-purity formulation specialization serving ophthalmic and surgical irrigation segments. Chinese pharmaceutical manufacturers including Boai NKY Pharmaceuticals Ltd. represent the scale-driven API production tier supplying cost-optimized grades to emerging market procurement channels.
| Leading Market Players |
|---|
| Avrio Health L.P. |
| 3M |
| BASF |
| Boai NKY Pharmaceuticals Ltd. |
| Glide Chem Private Limited |
| Lasa Supergenerics Ltd. |
| Samrat Pharmachem Limited |
| Evonik Industries AG |
| Nippon Shokubai Co., Ltd. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp chemical corridor moves pharmaceutical-grade polyvinylpyrrolidone from European polymer plants to Indian formulation facilities, with freight cost volatility amplifying margin pressure on standard-grade producers while premium-grade suppliers in Germany and Japan capture pricing power through documented purity certifications.
Pricing Analysis
Aftermarket service revenue from compliance auditing and staff training contracts now drives lifetime value more than unit sales. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels separates hospital procurement in Germany from nursing home purchasing in India. Cost compression in standard surgical scrub formulations is intensifying because Chilean and Japanese iodine extraction concentration exposes formulators to raw material cost swings. Dental clinics in Osaka demonstrate the least price sensitivity due to recurring peri-implantitis protocol revenue, while government procurement channels under Ayushman Bharat in tier-two Indian cities exhibit acute unit cost minimization behavior.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing arrangements as integrated delivery networks in the United States and NHS England consolidate purchasing power. Pharmaceutical-grade polymer production concentrates in Germany, Japan, and the United States, with iodine extraction anchored in Chile and Japan. The supply chain draws from elemental iodine, polyvinylpyrrolidone resin, and hydrogel matrix precursors as core inputs. Single-source vulnerability from Japanese iodine extraction concentration poses structural risk. Distribution runs through hospital pharmacies and wholesale distributors serving fragmented retail and institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated supply contracts bundling povidone iodine products with compliance auditing services are expanding faster than standalone product sales, transforming antiseptic procurement from transactional purchasing to recurring-revenue relationships.
For Market Incumbents: Insulate formulation margins by deepening backward integration into pharmaceutical-grade polymer supply and securing multi-year supplier qualification timelines with USP-NF and EP monograph specifications. Chlorhexidine-alcohol substitution in NHS England surgical scrub procurement threatens volume erosion in standardized hospital segments. Certification investment for EMA Medical Device Regulation compliance creates defensive moats in advanced wound dressing categories where notified body backlogs extend competitor time-to-market.
For New Entrants and Emerging Players: Establish a beachhead in peri-implantitis oral care protocols where dental clinic adoption of povidone iodine rinses remains underpenetrated outside Germany, Japan, and South Korea. Tier-two Indian cities under Ayushman Bharat infrastructure investments represent the most penetrable geography for first-time institutional antiseptic demand. A specialist go-to-market angle through continuing dental education partnerships and implant specialist society recommendations accelerates recurring revenue capture.
For Investors and Strategic Acquirers: Polymer-science specialists with captive iodine sourcing and established quality management systems represent the optimal acquisition target archetype for capability consolidation. Long-term viability in this market hinges on regulatory documentation depth and backward integration into raw material supply. Watch WHO prequalification pathway momentum for povidone iodine inclusion on the Essential Medicines List as the signal indicating accelerated access to multilateral procurement pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical-Grade Polymer Supply | BASF secures raw material cost advantages across European hospital networks through captive polyvinylpyrrolidone production. |
| EMA Medical Device Regulation Certification Investment | Evonik Industries AG extends competitive moats in ophthalmic applications where contamination thresholds sit below standard grades. |
| Integrated Supply Contract Bundling with Compliance Auditing | Group purchasing organizations in California and Texas health systems attach service-layer revenue to antiseptic product sales. |
| Smart Packaging with Temperature Sensor Deployment | German hospital pharmacy directors pilot digitized supply chain visibility to reduce waste from degraded povidone iodine inventory. |
| WHO Prequalification Pathway Pursuit | Essential Medicines List inclusion enables access to multilateral procurement pools for humanitarian and developing country supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA monograph filings, EMA Medical Device Regulation submissions, CDSCO antiseptic efficacy standards, and hospital procurement databases. Primary interviews engaged formulation scientists at polymer manufacturers, regulatory affairs leads at wound dressing producers, hospital pharmacy directors in Germany and the United States, and procurement managers at Indian group purchasing organizations. Secondary validation drew from EPA effluent threshold documentation, REACH biocidal substance authorization timelines, and WHO Essential Medicines List inclusion criteria. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Forecast inputs considered surgical volume expansion in ambulatory surgery centers, polymer science advances in controlled-release hydrogel matrices, and regulatory divergence between FDA monograph enforcement and EMA MDR implementation. Segmentation dimensions modeled include product type concentration, application use case, end-user procurement sophistication, and distribution channel structure across the analysis window. CAGRs were derived from procedure volume trajectories, infrastructure investment flows, and substitution elasticity estimates for chlorhexidine-alcohol combinations.
Stress conditions across elemental iodine price volatility, REACH authorization timeline compression, and NHS England procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and raw material supply concentration. Macroeconomic contraction, accelerated chlorhexidine substitution, or iodine extraction disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Mortuary Bags Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Filter Needles Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Empty IV Bags Market