
 Polymer Exam Gloves Market | 2026-2036
Polymer Exam Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Exam Gloves Market Insights
Malaysia is reconfiguring global polymer exam glove supply chains through sustained capacity expansion in Selangor and Perak. Top Glove Corporation Bhd leverages integrated nitrile production from petrochemical feedstock to finished goods. Hartalega Holdings Berhad differentiates through automated, high-speed manufacturing lines that reduce labor dependency. Kossan Rubber Industries Bhd anchors its position in specialty formulations for chemical-resistant applications.
Polymer exam gloves are disposable protective barriers manufactured from synthetic elastomers or natural rubber latex, typically measuring 240-300 mm in length with thickness ranging from 0.05 mm to 0.15 mm, designed to prevent pathogen transmission and chemical exposure in clinical and laboratory settings. Nitrile dominates value generation due to latex allergy mitigation and superior puncture resistance, while vinyl occupies the economy tier where cost sensitivity governs procurement. Hospitals represent the deepest margin pool, though dental offices are expanding fastest as infection control protocols broaden beyond surgical suites.
FDA clearance requirements and ASTM D6319 standards govern United States market access, while the EU Medical Device Regulation imposes post-market surveillance obligations on European suppliers. Malaysia's MDA and Thailand's TFDA administer parallel conformity frameworks that shape export eligibility for Southeast Asian manufacturers. Stakeholders must monitor regulatory divergence between nitrile chemical migration limits and emerging biodegradability certifications that could fragment compliance costs across destination markets.
Market Dynamics
Malaysian production concentration and nitrile feedstock integration are restructuring competitive economics, while FDA and EU MDR compliance costs are filtering marginal producers from export eligibility.
Growth Catalysts
- Hospital infection control mandates:India's expanding tertiary care network under Ayushman Bharat is mandating single-use barrier protocols in surgical and diagnostic settings, tightening glove consumption standards.
- REACH chemical migration limits:The EU's tightening nitrile oligomer thresholds are accelerating reformulation investments that favor integrated petrochemical-to-glove manufacturers with in-house polymerization control.
- Latex allergy prevalence:Rising documented sensitization rates among healthcare workers in Japan and South Korea are rendering natural rubber latex uncompetitive in premium clinical procurement.
Market Restraints
- Acrylonitrile price volatility:Nitrile glove margins compress when butadiene and acrylonitrile feedstock costs spike, exposing non-integrated manufacturers to raw material cyclicality without captive supply buffers.
- Selangor-Perak supply concentration:Over 60 percent of global nitrile glove capacity sits within 200 kilometers in Malaysia's Klang Valley, creating systemic disruption risk from localized energy shortages or labor actions.
- Biodegradability certification gaps:Absence of harmonized ASTM or ISO standards for polymer glove decomposition creates regulatory friction in markets advancing circular economy mandates.
Strategic Opportunities
- Vietnam manufacturing relocation:Thai and Malaysian producers are establishing satellite plants in Bac Ninh and Hai Phong to diversify geographic risk and access EU-Vietnam FTA tariff advantages.
- Dental clinic vertical expansion:Outpatient dental chains in Indonesia and Philippines are adopting surgical-grade barrier protocols previously limited to hospital settings, opening mid-premium volume tiers.
- Automated production technology:High-speed dipping lines with AI-driven quality inspection are compressing unit labor costs and enabling 24-hour continuous output that manual processes cannot match.
Industry Challenges
- Process engineering talent scarcity:Selangor manufacturers face recruitment gaps for polymer chemists capable of optimizing nitrile formulation for both chemical resistance and tactile sensitivity specifications.
- FDA 510(k) clearance timelines:Extended review periods for novel glove coatings or thickness profiles delay product launches by 12-18 months, compressing revenue windows before specification shifts.
- Legacy vinyl capacity stranding:Southeast Asian producers with depreciated PVC glove lines confront asset write-down pressures as hospital procurement shifts decisively toward nitrile.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Exam Gloves Market |
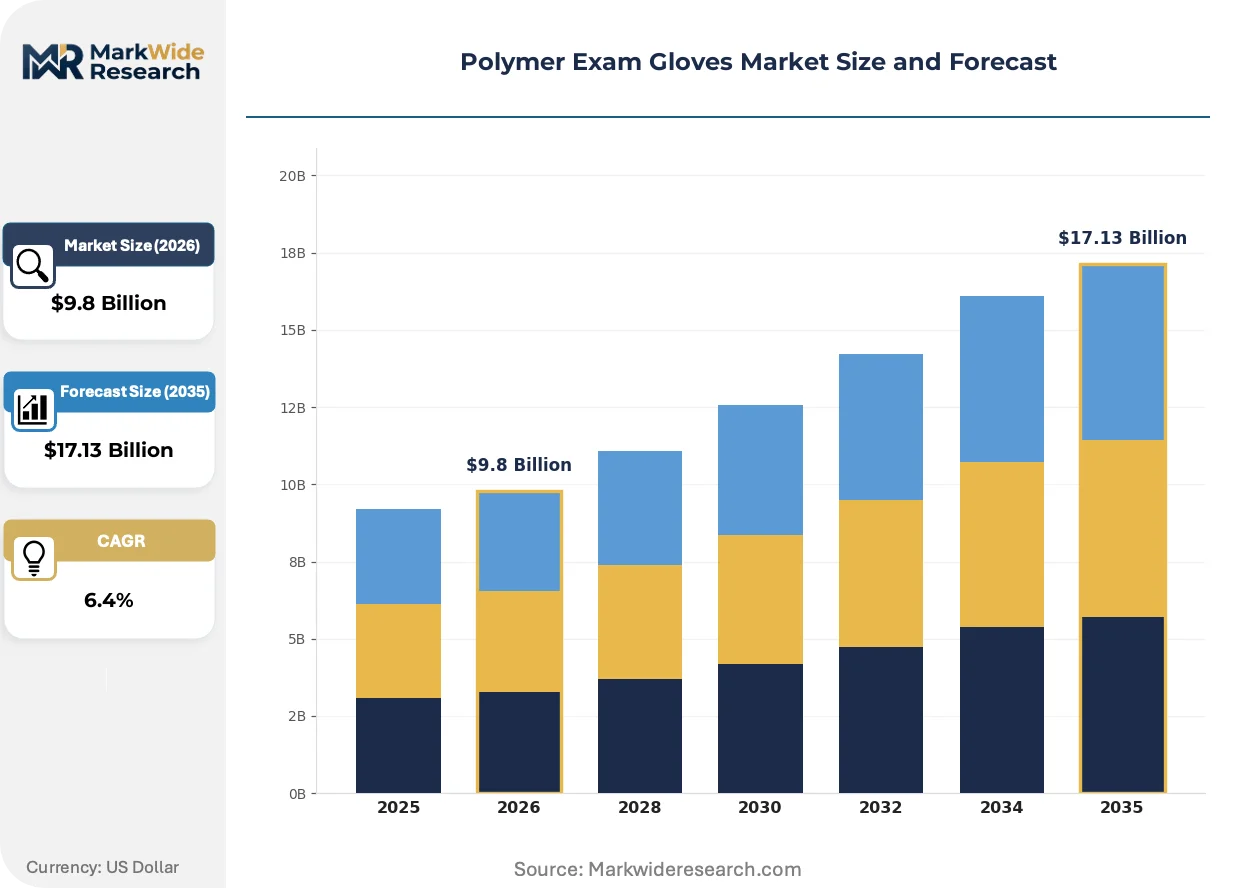
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Latex, Vinyl, Neoprene End User: Hospitals, Clinics, Laboratories, Dental Offices Size: Small, Medium, Large, X-Large Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Ansell Limited, Cardinal Health, Medline Industries, Semperit AG Holding, Intco Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Exam Gloves Market Trends and Innovations
Polymer glove manufacturing is converging with advanced materials science and digital quality systems, reshaping how barrier performance is engineered, verified, and procured across clinical settings.
Chlorinated nitrile surface treatment is rendering obsolete powdered latex and cornstarch donning aids in surgical applications. Major hospital systems in Germany and France are specifying polymer-coated chlorinated surfaces exclusively, eliminating particulate contamination risks in orthopedic and microsurgical procedures. This technology is rendering obsolete decades-old donning powder infrastructure and associated cleanroom filtration investments.
The EU Medical Device Regulation's post-market surveillance obligations are forcing manufacturers to maintain batch-level traceability databases accessible to national competent authorities. Malaysian exporters must now deploy serialized production records and adverse event reporting systems that previously applied only to Class III implants. Dental distributors in Italy and Spain are demanding MDR-compliant technical documentation as a procurement prerequisite, filtering non-compliant suppliers from tender eligibility.
Direct hospital contracting is displacing layered distribution through medical supply wholesalers in high-volume markets. Large health systems in Texas and California are negotiating multi-year nitrile supply agreements directly with Selangor manufacturers, bypassing traditional distributor markups. This pattern is most visible in integrated delivery networks with centralized procurement functions, where volume consolidation enables specification customization and dedicated production line allocation.
Polymer Exam Gloves Market Segmentation
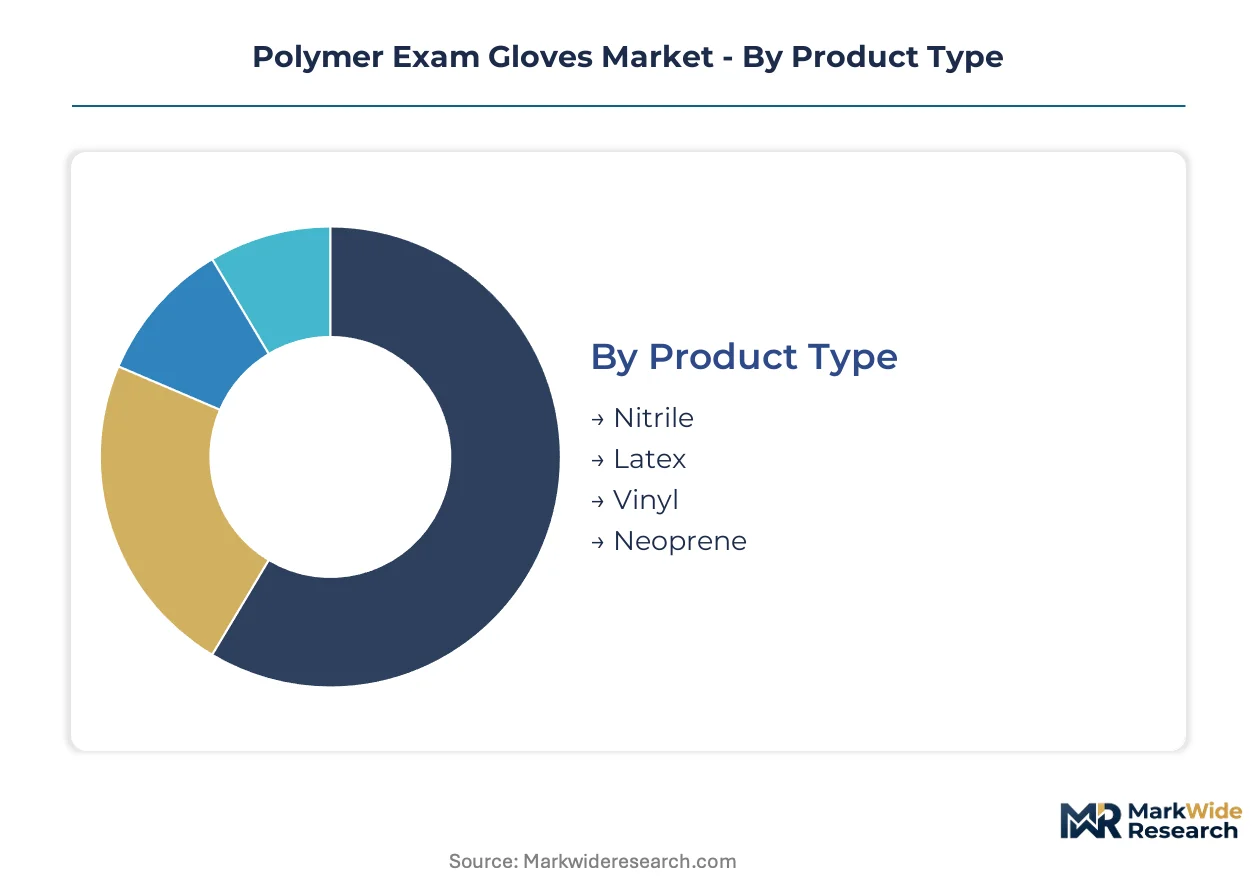
Polymer exam glove procurement splits across material chemistry, clinical setting, fit specification, and purchase pathway. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Material selection governs barrier performance, allergenicity risk, and unit economics across clinical applications.
- Nitrile:Synthetic copolymer of acrylonitrile and butadiene delivers puncture resistance three times superior to latex. Hospital systems in Germany and Japan are mandating nitrile for all invasive procedures as FDA 510(k) clearance rates for novel latex formulations stall.
- Latex:Natural rubber hevea brasiliensis derivative maintains unmatched tactile sensitivity for microsurgical applications. Demand concentrates in emerging markets where cost sensitivity outweighs allergy documentation requirements.
- Vinyl:Polyvinyl chloride formulation occupies economy tier for low-risk examination tasks. India's primary health centers under Ayushman Bharat deploy vinyl for non-invasive screening where barrier integrity demands are minimal.
- Neoprene:Chloroprene polymer resists chemical permeation from chemotherapy agents and cytotoxic drugs. Oncology infusion centers in the United States specify neoprene for hazardous drug handling per USP 800 guidelines.
Established volume favors nitrile; emerging adoption favors neoprene.
End User:
Clinical setting determines specification stringency and contract structure.
- Hospitals:Tertiary care institutions drive premium specification with ASTM D6319 compliance, lot traceability, and chlorinated surface treatment. Integrated delivery networks in Texas negotiate direct multi-year supply agreements with Malaysian manufacturers.
- Dental Offices:Outpatient chains in Indonesia and Philippines are adopting surgical-grade barrier protocols previously restricted to hospital settings. This segment is climbing the fastest as infection control standards broaden beyond surgical suites.
- Clinics:Primary care and urgent care facilities balance cost containment with regulatory minimums. India's expanding health and wellness centers under government insurance schemes are standardizing on mid-tier nitrile.
- Laboratories:Research and diagnostic facilities prioritize chemical resistance and powder-free specifications. Academic medical centers in France require MDR-compliant technical documentation as tender prerequisites.
Procurement concentration favors hospitals; specification upgrade favors dental offices.
Size:
Fit dimension aligns with workforce demographics and ergonomic safety protocols.
- Medium:Dominant volume tier matching average hand dimensions across healthcare workforces. Malaysian manufacturers optimize production line allocation to this specification for inventory efficiency.
- Large:Secondary volume position serving male-skewed surgical and emergency medicine specialties. Direct hospital contracting enables customized large-size allocation for specific departments.
- Small:Critical for pediatric care and female-majority nursing populations in Southeast Asian markets. Stockout risk runs higher due to production line prioritization toward medium and large.
- X-Large:Niche specification for specialized surgical and emergency response teams. Premium pricing reflects batch size inefficiencies in dipping line configuration.
Production efficiency centers on medium; underserved demand concentrates in small.
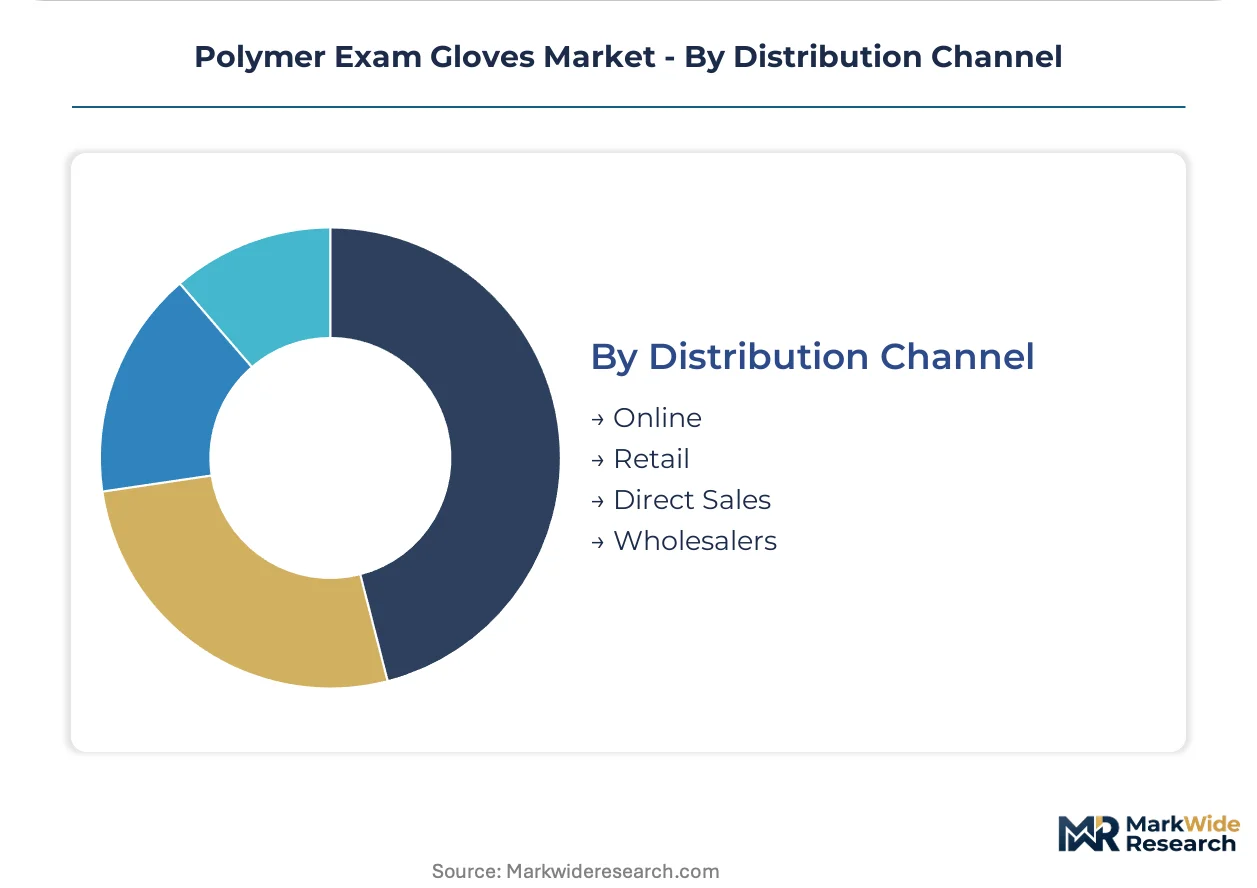
Distribution Channel:
Purchase pathway determines margin capture and customer relationship depth.
- Direct Sales:Manufacturer-to-hospital contracts eliminate distributor markups for high-volume integrated delivery networks. Selangor producers deploy dedicated account teams for Texas and California health systems.
- Wholesalers:Traditional medical supply distributors serve fragmented clinic and laboratory demand. Italian and Spanish dental distributors are filtering non-MDR-compliant suppliers from tender eligibility.
- Online:E-commerce platforms accelerate small-volume procurement for dental and laboratory segments. Amazon Business and specialized medical marketplaces compress delivery timelines to 24-48 hours.
- Retail:Pharmacy and medical supply stores serve individual practitioners and small practices. India's Apollo Pharmacy network stocks standardized nitrile for walk-in professional purchase.
Margin retention favors direct sales; geographic reach favors wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance requirements and ASTM D6319 standards govern United States market access, while Malaysia's MDA and Thailand's TFDA administer parallel conformity frameworks that shape export eligibility for Southeast Asian manufacturers.
United States
Hospital procurement consolidation under integrated delivery networks in Texas and California is accelerating direct manufacturer contracting. FDA 510(k) clearance timelines for novel glove coatings extend 12-18 months, compressing revenue windows before specification shifts. Selangor-based exporters maintain dedicated account teams for these health systems.
Germany
Chlorinated nitrile surface treatment specifications from major hospital systems in Germany are eliminating powdered latex and cornstarch donning aids. REACH chemical migration limits on nitrile oligomers favor integrated petrochemical-to-glove manufacturers with in-house polymerization control. The EU MDR's post-market surveillance obligations require batch-level traceability databases.
India
Ayushman Bharat's expanding tertiary care network is mandating single-use barrier protocols in surgical and diagnostic settings. Domestic healthcare infrastructure expansion is tightening glove consumption standards across primary health centers. India's health and wellness centers under government insurance schemes are standardizing on mid-tier nitrile specifications.
Malaysia
Selangor and Perak production clusters contain over 60 percent of global nitrile glove capacity within 200 kilometers of the Klang Valley. The country's MDA compliance framework reinforces export eligibility alongside FDA requirements. Top Glove Corporation Bhd leverages integrated nitrile production from petrochemical feedstock to finished goods in this concentration.
Japan
Rising documented latex sensitization rates among healthcare workers are rendering natural rubber uncompetitive in premium clinical procurement. METI guidelines on medical device quality systems align with international standards for barrier performance verification. Dental distributors are demanding technical documentation as tender prerequisites.
Polymer Exam Gloves Market Competitive Landscape
Vertically integrated petrochemical-to-glove manufacturers and specialized high-automation producers split the market between cost control and specification differentiation. Malaysian entities dominate volume through feedstock integration and regulatory compliance infrastructure. Two strategic archetypes prevail: integrated conglomerates with captive nitrile polymerization and automation-focused specialists with reduced labor dependency. Competitive moves center on geographic diversification into Vietnam and direct hospital contracting that eliminates distributor markups.
Within the Malaysian integrated tier, Top Glove Corporation Bhd exemplifies petrochemical-to-finished-goods control, while Hartalega Holdings Berhad represents the automation-specialist archetype with high-speed manufacturing lines. Kossan Rubber Industries Bhd occupies a position in specialty formulation segments. These three entities anchor the competitive structure through distinct capability configurations rather than scale alone.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Ansell Limited |
| Cardinal Health |
| Medline Industries |
| Semperit AG Holding |
| Intco Medical Technology |
| Others |
Pricing and Supply Chain Analysis
Selangor-Perak capacity utilization above 85 percent has compressed supplier pricing flexibility and forced buyers into longer-term contracting postures. Malaysian manufacturers leverage this tightness to enforce minimum volume commitments from hospital systems in Texas and California, while non-integrated competitors absorb margin erosion from acrylonitrile feedstock volatility without recourse.
Pricing Analysis
Geographic price spreads between Malaysian direct-contract hospital supply and European wholesale distribution exceed 30 percent at equivalent specification tiers. Three-tier pricing structure across premium chlorinated nitrile, standard powder-free nitrile, and economy vinyl governs procurement segmentation, with FDA 510(k) certification tier and volume scale as the primary differentiation drivers. Cost compression in the vinyl economy tier is intensifying because hospital procurement committees in India and Southeast Asia are upgrading minimum specifications to mid-tier nitrile. Primary care clinics under government insurance schemes exhibit the highest price sensitivity, while integrated delivery networks with dedicated production line allocation show the least.
Supply Chain Analysis
Contract manufacturing concentration among Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd controls over 60 percent of global nitrile glove capacity from Selangor and Perak facilities. Geographic supply concentration centers on Malaysia, Thailand, and emerging Vietnam satellite plants, with raw material dependencies drawing from butadiene and acrylonitrile petrochemical feedstocks plus chlorination surface treatment chemicals. Single-source vulnerability from Klang Valley concentration within 200 kilometers creates systemic disruption exposure to localized energy shortages or labor actions. Distribution runs through direct manufacturer-to-hospital contracts for high-volume integrated delivery networks, supplemented by medical supply wholesalers serving fragmented clinic and dental demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense imperatives as chlorinated nitrile surface treatments render powdered latex obsolete and biodegradable alternatives threaten petrochemical-based formulations. The priority is locking in specification standards before regulatory momentum shifts.
For Market Incumbents: Entrench chlorinated nitrile specifications through direct hospital contracting that eliminates distributor intermediaries and captures procurement committee influence. Accelerate backward integration into acrylonitrile polymerization to buffer margin compression from feedstock volatility, while deploying dedicated account teams for integrated delivery networks in Texas and California to preempt competitor access.
For New Entrants and Emerging Players: Vietnam manufacturing relocation into Bac Ninh and Hai Phong offers tariff-advantaged EU market access and geographic risk diversification away from Malaysian concentration. Target dental clinic vertical expansion in Indonesia and Philippines where surgical-grade barrier protocol adoption outpaces established supplier coverage, penetrating through e-commerce platforms with 24-48 hour delivery commitments.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance cost escalation and FDA 510(k) clearance timeline extensions filter marginal producers from export eligibility. Acquisition targets should display captive nitrile polymerization or high-automation production lines with AI-driven quality inspection. The signal to watch is REACH chemical migration limit tightening on nitrile oligomers, which favors integrated petrochemical-to-glove manufacturers with in-house formulation control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Polymerization | Captive feedstock supply buffers margin compression from butadiene price cyclicality. |
| Vietnam Manufacturing Footprint Expansion | EU-Vietnam FTA tariff advantages diversify geographic risk from Malaysian concentration. |
| Direct Hospital System Partnership | Texas and California integrated delivery networks enable specification customization and dedicated production allocation. |
| Chlorinated Surface Treatment Certification | German and French hospital mandates for polymer-coated chlorinated nitrile eliminate powdered latex competitors. |
| AI-Driven Quality Inspection Deployment | High-speed dipping lines with automated defect detection compress unit labor costs below manual process thresholds. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, GPO contracts specialists, biomedical engineers, and Malaysian plant operations directors and refined through secondary validation. FDA 510(k) clearance databases, EU MDR technical documentation filings, customs trade data for nitrile glove exports, and SEC filings from listed manufacturers provided triangulation anchors. Bottom-up volume modeling from individual production facility outputs converged with top-down demand estimation from hospital bed counts and infection control protocol adoption rates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning material chemistry, clinical setting, fit specification, and purchase pathway. Modeled variables included nitrile versus vinyl versus neoprene formulation splits, hospital versus dental versus laboratory end-use concentration, and direct sales versus wholesaler versus online channel evolution. CAGRs were derived from regression analysis of historical volume trends against explanatory variables including healthcare infrastructure expansion, regulatory compliance cost indices, and feedstock price series.
Practitioners should monitor acrylonitrile price volatility, REACH chemical migration limit revisions, and biodegradable certification standard emergence for early signals of forecast revision necessity. Quarterly review of FDA 510(k) clearance timelines, Selangor-Perak capacity utilization reports, and integrated delivery network procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Medical Liners Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Global Lancets Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Foley Trays Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Intravenous (IV) Fluid Bags Market