
 Luer Lock Syringe Market | 2026-2036
Luer Lock Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Luer Lock Syringe Market Foresight
Hospital procurement consolidation is restructuring how Luer lock syringe volumes flow through distribution channels, with integrated delivery networks now commanding multi-year supply agreements. Becton, Dickinson and Company leverages its scale to secure these centralized contracts, while B. Braun Melsungen AG anchors its position through backward integration into polymer compounding. Terumo Corporation differentiates via precision molding expertise that reduces dead-space volumes in safety-engineered designs.
A Luer lock syringe employs a standardized tapered fitting with helical threads that create a secure, leak-resistant connection between the barrel and needle hub, typically manufactured through injection molding of medical-grade polypropylene with silicone-treated elastomer plunger seals. Safety syringes command premium positioning as needlestick prevention regulations harden across jurisdictions, while single-use plastic variants dominate volume due to their disposability and infection control profile. The 3 mL and 5 mL sizes concentrate hospital demand where medication dosing precision intersects with high throughput.
The FDA enforces 510(k) premarket notification for safety-engineered devices under the Needlestick Safety and Prevention Act, while the EU Medical Device Regulation mandates clinical evidence for Class IIa syringe systems. India's CDSCO aligns with ISO 7886 standards through the Bureau of Indian Standards certification pathway. Stakeholders must monitor how evolving material regulations around cyclic olefin polymers and prop 65 compliance in California reshape formulation strategies and supplier qualification timelines.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while favoring manufacturers with captive polymer compounding and automated molding capacity. This structural force is accelerating the displacement of fragmented regional suppliers by integrated players capable of multi-year tender execution.
Growth Catalysts
- Safety-engineered device mandates:The FDA's updated 510(k) pathway for needlestick prevention devices under the Needlestick Safety and Prevention Act is accelerating hospital conversions from conventional to retractable and shielded Luer lock designs.
- India's hospital infrastructure buildout:Government tenders under the PLI scheme are channeling volume toward domestic manufacturers with backward integration into medical-grade polypropylene compounding.
- Cyclic olefin polymer adoption:Advanced resin formulations with superior barrier properties and reduced protein adsorption are displacing conventional polypropylene in biologic drug delivery applications.
Market Restraints
- Medical-grade polypropylene supply concentration:LyondellBasell and Borealis control over 60% of pharmaceutical-grade resin capacity, creating input cost volatility during energy price spikes.
- EU MDR clinical evidence requirements:The Medical Device Regulation's expanded documentation burden for Class IIa syringe systems is extending certification timelines by 12-18 months for new entrants.
- Prefilled syringe substitution:Glass and polymer prefilled formats are capturing chronic disease administration volumes previously served by conventional Luer lock systems.
Strategic Opportunities
- Vietnam's manufacturing relocation:Medical device producers are establishing molding operations in Ho Chi Minh City and Hanoi to access ASEAN tariff preferences and lower labor costs.
- Home healthcare channel expansion:Direct-to-patient distribution models for insulin and anticoagulant administration are creating demand for compact, unit-of-use packaging configurations.
- ISO 80369-7 small-bore connector convergence:The international standard's enforcement is enabling cross-compatible designs that reduce hospital SKU complexity and inventory carrying costs.
Industry Challenges
- Precision molding talent scarcity:Dead-space reduction to sub-50 microliter specifications requires specialized tool design expertise concentrated in Switzerland and Japan.
- Multi-site quality system harmonization:FDA 21 CFR Part 820 compliance across geographically dispersed molding facilities demands centralized statistical process control infrastructure.
- Legacy ERP integration friction:Hospital IDN procurement portals require EDI connectivity that smaller suppliers struggle to implement without third-party middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luer Lock Syringe Market |
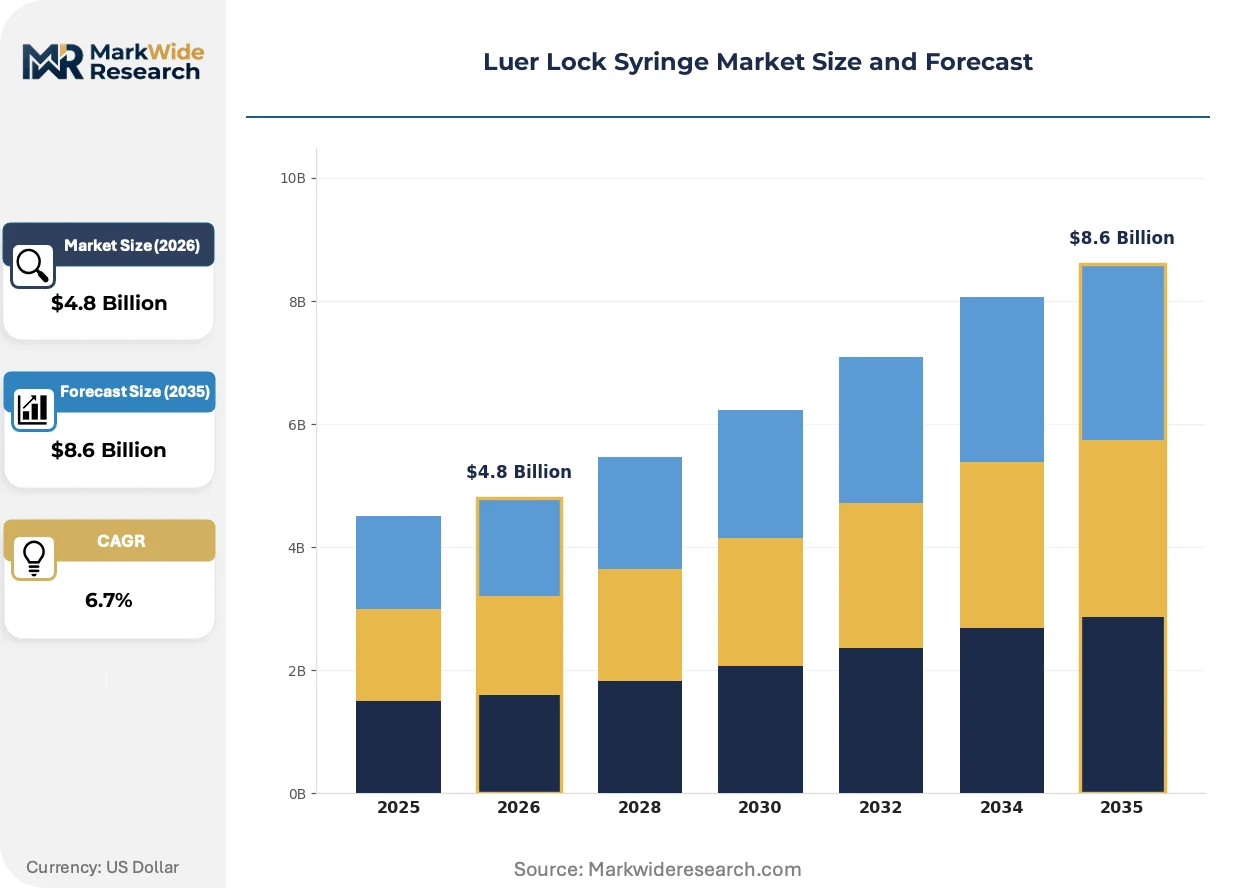
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Syringes, Reusable Syringes, Safety Syringes, Insulin Syringes Size: 1 mL, 3 mL, 5 mL, 10 mL End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Material: Plastic, Glass, Stainless Steel, Rubber |
| Companies Covered | Terumo Corporation, Nipro Corporation, Becton, Dickinson and Company, Schreiner MediPharm, Cardinal Health, B. Braun Melsungen AG, Hindustan Syringes & Medical Devices Limited, Plas-Tech Engineering, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luer Lock Syringe Market Shifts & Advancements
Active needlestick prevention mechanisms and connected device formats are redefining product architecture in the Luer lock segment. These developments are compressing development cycles while raising the capital threshold for competitive participation.
Passive safety systems with automatic needle retraction are overtaking manual shielding designs in hospital procurement specifications. These devices eliminate user-activation variability that compromises protection rates. Integrated delivery networks in Germany and the United States are mandating passive formats in centralized tenders, forcing suppliers to retool molding lines and validate new plunger-elastomer interactions.
The EU Medical Device Regulation's clinical evidence requirements for Class IIa systems are extending time-to-market for novel safety mechanisms. Manufacturers must now submit biocompatibility testing and human factors validation that exceeds the previous Medical Device Directive scope. Small-cap specialists in Italy and Spain are partnering with notified bodies early in development to preempt regulatory rejection.
Consolidated procurement through integrated delivery networks is compressing distributor tiers in North American hospital supply. Third-party logistics providers are losing volume to direct manufacturer-IDN contracts with 3-5 year terms and price-volume bands. This concentration is most visible in the United States, where Ascension and CommonSpirit's combined purchasing power exceeds $10 billion in annual medical-surgical spend.
Luer Lock Syringe Market Segmentation
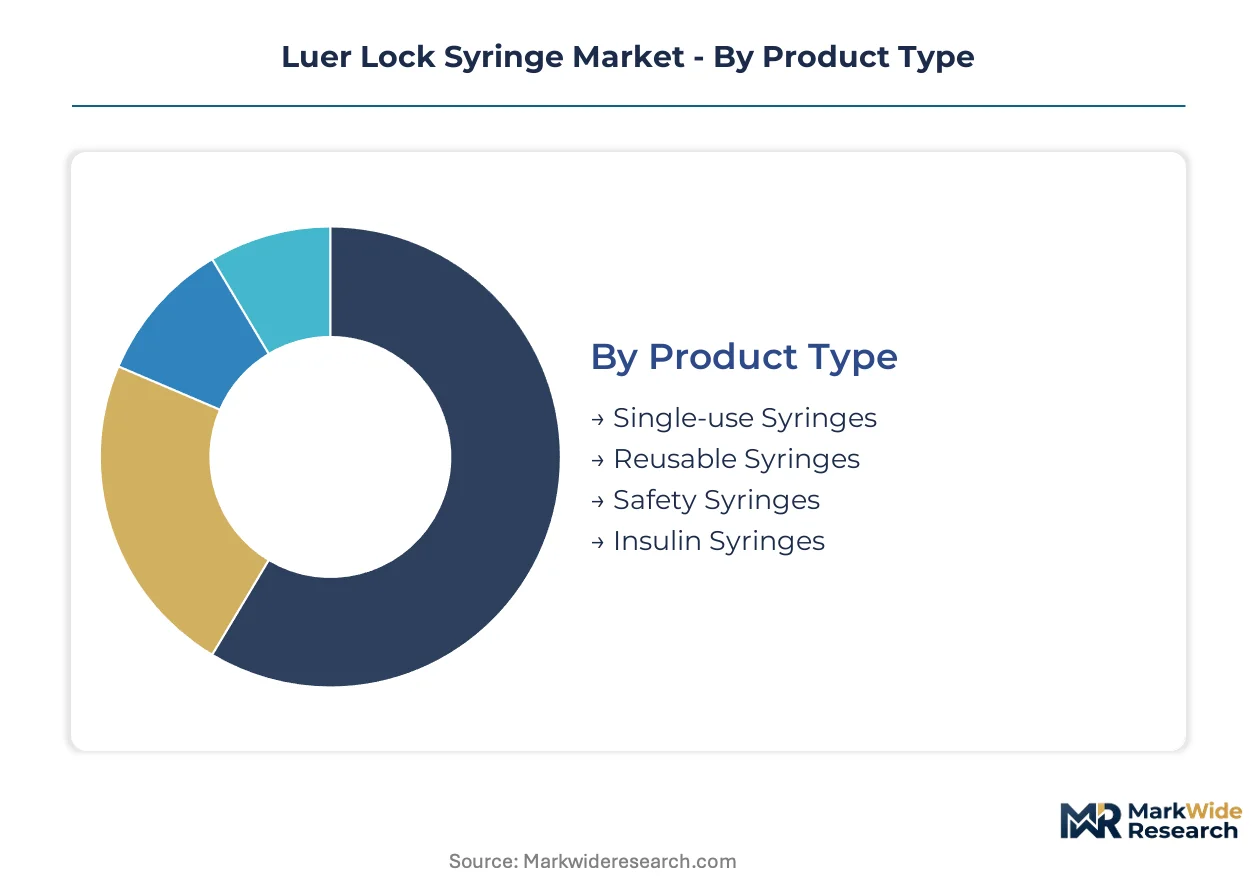
Segmentation in the Luer lock syringe market reveals how procurement specifications, clinical workflows, and material science converge to create distinct competitive arenas. Manufacturers must align molding capabilities and regulatory dossiers with the exacting requirements of each product category and end-use environment.
Product Type:
Product architecture determines sterilization protocols, needlestick prevention mechanisms, and reimbursement pathways across clinical settings.
- Safety Syringes:These devices integrate passive or active needlestick prevention mechanisms—retractable needles, sliding shields, or hinged guards—manufactured through multi-component injection molding with medical-grade polypropylene barrels and silicone-lubricated elastomer seals. Hospital procurement consolidation in Germany and the United States now mandates passive safety formats in centralized tenders, displacing conventional designs and forcing suppliers to validate new plunger-barrel interactions under ISO 7886-4.
- Single-use Syringes:Polypropylene barrels with bonded Luer lock hubs dominate volume through disposability economics and infection control imperatives. India's hospital infrastructure expansion under the PLI scheme channels tender volume toward domestic manufacturers with backward integration into medical-grade resin compounding.
- Insulin Syringes:Ultra-fine 31-gauge needles with unit-scale barrel markings serve diabetes management protocols in home care and clinic settings.
- Reusable Syringes:Glass-barrel designs with replaceable needles persist in veterinary and research applications where sterilization infrastructure supports cyclic use.
Safety syringes lead on scale through regulatory mandates; insulin syringes lead on momentum through home healthcare channel expansion.
Size:
Barrel capacity specifications align with dosing precision requirements and medication viscosity across therapeutic categories.
- 3 mL:The clinical workhorse for subcutaneous and intramuscular injections, this size balances precision graduation with ergonomic handling. Hospital pharmacies in the United States and France standardize on 3 mL formats for antibiotic and vaccine administration, driving multi-year supply agreements with integrated delivery networks.
- 5 mL:Larger-volume medication delivery—including contrast media and parenteral nutrition—concentrates demand in imaging centers and intensive care units. The format's thicker barrel walls require modified injection molding parameters to maintain Luer lock thread tolerance.
- 1 mL:Tuberculin-scale graduation supports pediatric dosing and allergen immunotherapy in clinic settings.
- 10 mL:Irrigation and enteral feeding applications utilize this capacity in surgical and long-term care environments.
The 3 mL format anchors hospital procurement volume; 1 mL designs are climbing the fastest through precision dosing protocols.
End User:
Clinical environment dictates packaging configuration, sterility assurance levels, and connectivity requirements for procurement systems.
- Hospitals:Integrated delivery networks command bulk sterile packaging with EDI-enabled procurement portals and 3-5 year price-volume contracts. Safety-engineered designs with passive needlestick prevention dominate specifications in the United States and Germany.
- Home Care:Unit-of-use packaging with patient-centric instructions and compact storage profiles serves insulin and anticoagulant self-administration. Direct-to-patient distribution models are reshaping logistics requirements.
- Clinics:Outpatient settings balance cost sensitivity with safety compliance, often sourcing through group purchasing organizations.
- Diagnostic Laboratories:Blood collection and specimen handling prioritize minimal dead-space designs for accurate volume recovery.
Hospitals concentrate procurement scale; home care channels are gaining share fastest through chronic disease management decentralization.
Material:
Substrate selection governs barrier properties, protein adsorption characteristics, and regulatory biocompatibility dossiers.
- Plastic:Medical-grade polypropylene dominates through injection molding efficiency, gamma sterilization compatibility, and disposability economics. LyondellBasell and Borealis supply concentration creates input cost volatility during energy price spikes.
- Glass:Borosilicate formats persist in prefilled and biologic drug delivery applications where inertness and visibility outweigh breakage risk.
- Stainless Steel:Reusable needle hubs and specialty research applications utilize this substrate.
- Rubber:Bromobutyl and chlorobutyl elastomer plunger seals provide gas barrier and lubrication properties.
Plastic commands manufacturing scale; glass maintains position in biologic delivery applications with the steepest expansion trajectory for cyclic olefin polymer alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's integrated delivery networks command longer contract terms than India's fragmented hospital procurement, yet both markets are accelerating safety syringe conversions through regulatory pressure and infrastructure investment respectively.
United States
Ascension and CommonSpirit's combined purchasing power shapes multi-year supply agreements with price-volume bands. The FDA enforces 510(k) premarket notification for needlestick prevention devices under the Needlestick Safety and Prevention Act. Manufacturing clusters in New Jersey and Illinois concentrate precision molding capacity for passive safety designs.
Germany
Hospital procurement consolidation through university hospital networks favors suppliers with ISO 13485-certified quality systems. The EU Medical Device Regulation mandates clinical evidence for Class IIa syringe systems. Baden-Württemberg hosts specialized tool design expertise for dead-space reduction below 50 microliters.
India
Government tenders under the PLI scheme channel volume toward domestic manufacturers with backward integration into medical-grade polypropylene. The CDSCO aligns with ISO 7886 standards through Bureau of Indian Standards certification. Gujarat and Maharashtra concentrate molding operations serving hospital infrastructure expansion.
Japan
Precision dosing protocols in aging-care facilities drive demand for ultra-low dead-space designs. The PMDA maintains stringent biocompatibility requirements for elastomer plunger seals. The Kansai region around Osaka anchors specialized molding expertise for safety-engineered formats.
Vietnam
Medical device producers establish molding operations to access ASEAN tariff preferences and lower labor costs. The national pharmaceutical regulator enforces medical device registration aligned with ASEAN harmonization. Ho Chi Minh City and Hanoi concentrate emerging manufacturing capacity for export-oriented production.
Luer Lock Syringe Market Competitive Landscape
North American producers anchor one tier; Japanese and German specialists hold differentiated positions in precision safety engineering. The vendor base splits between integrated conglomerates with captive polymer supply and focused mid-cap manufacturers with specialized molding expertise. Three archetypes dominate: scale-driven contract winners, precision-engineering specialists, and vertically integrated regional champions. Competitive dynamics center on multi-year tender execution capability and regulatory dossier breadth rather than price alone.
Among Japanese manufacturers, Terumo Corporation exemplifies the precision-engineering archetype through its molding expertise heritage. Becton, Dickinson and Company represents the scale-driven contract tier with centralized procurement penetration. B. Braun Melsungen AG anchors the European vertically integrated position with polymer compounding control. These three occupy positions that illustrate how geographic origin and structural integration map to distinct competitive vectors in safety syringe procurement.
| Leading Market Players |
|---|
| Terumo Corporation |
| Nipro Corporation |
| Becton, Dickinson and Company |
| Schreiner MediPharm |
| Cardinal Health |
| B. Braun Melsungen AG |
| Hindustan Syringes & Medical Devices Limited |
| Plas-Tech Engineering |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Multi-component injection molding for passive safety mechanisms is compressing per-unit economics while concentrating production among manufacturers with validated tool design capabilities. This technological transition simultaneously raises capital barriers and rewards scale, reshaping how procurement contracts are priced across integrated delivery networks.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for standard single-use Luer lock syringes, forcing incumbent suppliers to differentiate through ISO 80369-7 certification tiers and dead-space specifications. Three-tier pricing structure across premium, standard, and economy levels separates safety-engineered retractable designs from conventional shielded formats and basic single-use variants. Cost compression in the economy tier is intensifying because of PLI-subsidized domestic production in India. Hospital procurement committees demonstrate lowest price sensitivity for passive safety devices with sub-50 microliter dead-space, while clinic group purchasing organizations drive hard bargaining on standard single-use volumes.
Supply Chain Analysis
Dual-sourcing requirements from Ascension and CommonSpirit mandate that suppliers qualify secondary resin providers and backup molding facilities, extending qualification timelines but reducing single-source vulnerability. Medical-grade polypropylene compounding concentrates in Germany, the United States, and Saudi Arabia, with LyondellBasell and Borealis anchoring pharmaceutical-grade supply. Finished syringe production draws from injection molding clusters in New Jersey, Baden-Württemberg, and Gujarat. Tariff exposure on Chinese-origin elastomer plunger seals creates input cost volatility for manufacturers without captive rubber compounding. Distribution runs through direct manufacturer-IDN contracts with third-party logistics providers losing share to centralized procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Luer Lock Syringe Market functions as a stable compounder where regulatory mandates for needlestick prevention create predictable replacement demand across hospital infrastructure cycles.
For Market Incumbents: Cement multi-year tender lock-ins with integrated delivery networks by securing ISO 13485-certified quality systems across geographically dispersed molding facilities. Invest in captive medical-grade polypropylene compounding to defend margin position against PLI-subsidized Indian competitors. Prioritize backward integration into elastomer seal manufacturing to reduce exposure to bromobutyl supply concentration.
For New Entrants and Emerging Players: Enter via Vietnam-based molding operations to access ASEAN tariff preferences and serve Japanese precision dosing demand with lower labor cost structures. Target home healthcare insulin administration with compact unit-of-use packaging configurations that incumbent hospital-focused suppliers underserve. Pursue direct-to-patient distribution partnerships with chronic disease management platforms.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European specialists with ISO 80369-7 tooling expertise but limited IDN contract penetration. Five-to-ten year viability hinges on regulatory dossier breadth rather than manufacturing scale alone. Monitor FDA 510(k) submission volumes for passive safety mechanisms as the inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369-7 Small-Bore Connector Certification | Cross-compatible designs reduce hospital SKU complexity and inventory carrying costs across integrated delivery networks. |
| Backward Integration into Polymer Compounding | Captive medical-grade polypropylene supply insulates margin from LyondellBasell and Borealis pricing volatility during energy spikes. |
| Passive Safety Mechanism FDA 510(k) Submission | Premarket notification under the Needlestick Safety and Prevention Act unlocks Ascension and CommonSpirit centralized tender access. |
| Vietnam Manufacturing Footprint Establishment | ASEAN tariff preferences and lower labor costs enable competitive positioning in Japanese precision dosing segments. |
| Home Healthcare Direct-to-Patient Distribution | Unit-of-use packaging for insulin and anticoagulant self-administration captures chronic disease decentralization momentum. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts managers, and polymer compounding specialists grounded the qualitative framework. Secondary validation drew from FDA 510(k) filings, CDSCO medical device registration databases, EU MDR notified body guidance documents, and Bureau of Indian Standards certification records. Bottom-up volume estimates triangulated against top-down hospital infrastructure spend projections across the analysis window.
Segmentation outputs reflect modeling across product type, end-use environment, barrel capacity specification, and material substrate categories. CAGRs were derived from regression analysis of procurement volume trends and regulatory conversion timelines. Forecast inputs incorporated PLI scheme tender awards, IDN contract renewal cycles, and cyclic olefin polymer adoption curves in biologic drug delivery applications.
Inputs from FDA premarket notification databases and EU notified body clinical evidence requirements were available through the study window; gaps in private hospital procurement contract terms introduce uncertainty bands around integrated delivery network volume assumptions. Deviation in India's PLI scheme disbursement schedules or EU MDR certification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Cryotubes Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Global Swab Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Cryogenic Vials and Tubes Market