
 Global Pneumonia Therapeutics Market | 2026-2036
Global Pneumonia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pneumonia Therapeutics Market Foresight
Hospital procurement consolidation is realigning purchasing power toward centralized pharmacy committees and integrated delivery networks. Pfizer Inc. leverages its manufacturing scale to secure multi-year hospital supply contracts. AstraZeneca plc anchors its position through sustained R&D investment in respiratory anti-infectives.
Pneumonia therapeutics comprise antimicrobial agents, immunomodulatory compounds, and prophylactic vaccines formulated to achieve minimum inhibitory concentrations against Streptococcus pneumoniae, Haemophilus influenzae, and atypical pathogens in lung tissue. These products serve to reduce mortality from acute lower respiratory tract infections and prevent recurrence in high-risk populations. Antibiotics within the product-type segment command the largest revenue share due to entrenched prescribing protocols in emergency departments. Vaccines represent the fastest-expanding category as national immunization programs in Brazil and Nigeria expand pneumococcal coverage. The intravenous delivery mode captures premium pricing in intensive care settings where rapid attainment of therapeutic drug levels determines clinical outcomes.
FDA's Qualified Infectious Disease Product designation and EMA's PRIME eligibility criteria accelerate development timelines for novel pneumonia therapies. WHO prequalification requirements shape access to procurement through UN agencies and national essential medicine programs. Stakeholders must monitor antimicrobial stewardship mandates that restrict broad-spectrum antibiotic use and redirect formulary placement toward narrow-spectrum alternatives.
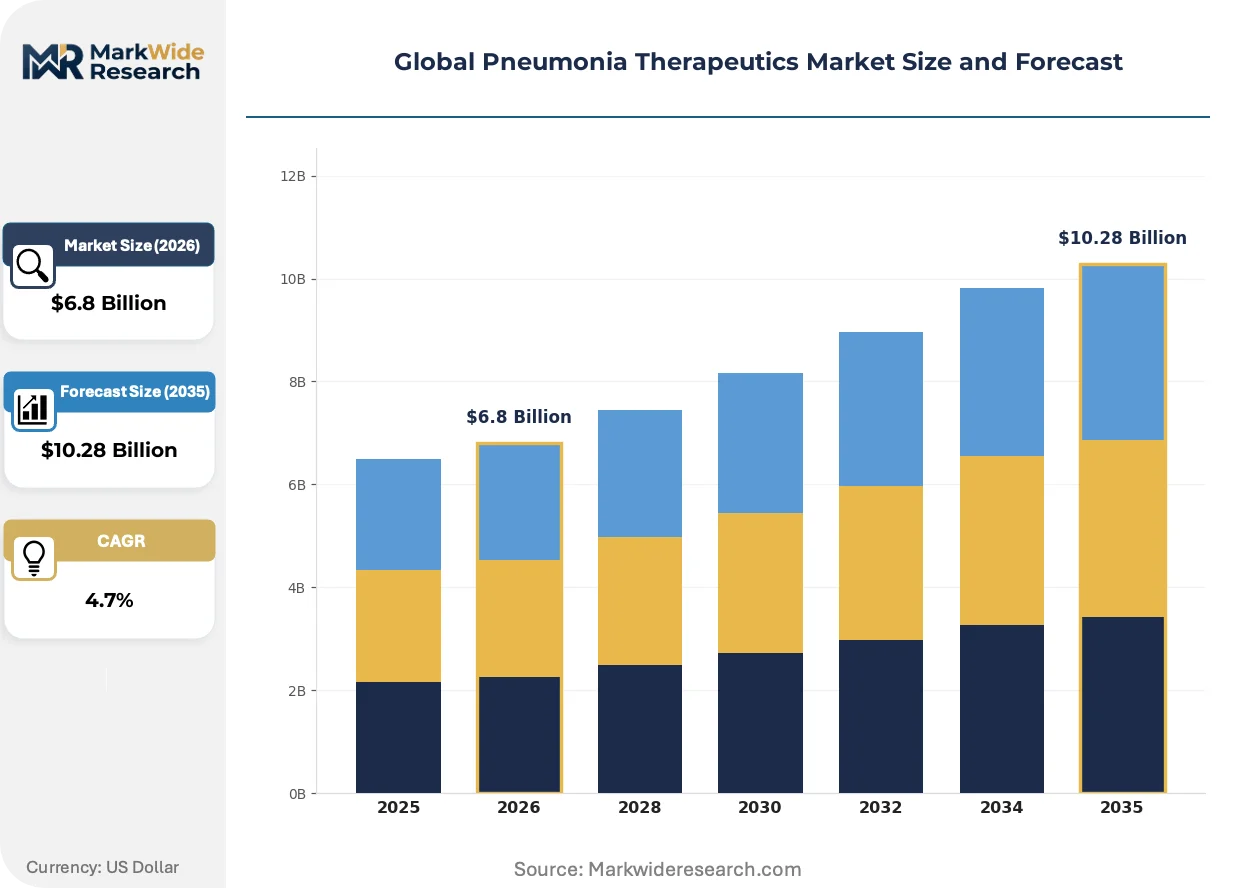
Market Dynamics
Hospital procurement consolidation is concentrating purchasing authority within centralized pharmacy committees and integrated delivery networks, fundamentally altering how pneumonia therapeutics reach acute-care settings and reshaping manufacturer-contractor relationships.
Growth Catalysts
- EMA PRIME Eligibility:Accelerated assessment pathways for anti-infectives compress development timelines and reduce regulatory uncertainty for novel pneumonia therapies entering European markets.
- National Immunization Scale-Up:Expanded pneumococcal coverage programs in Brazil and Nigeria are pulling vaccine volumes into public-sector procurement channels.
- Antimicrobial Stewardship Mandates:Institutional protocols restricting broad-spectrum antibiotic use are redirecting formulary placement toward narrow-spectrum alternatives with superior resistance profiles.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for key pneumonia antibiotics clusters in specific Asian supply basins, exposing procurement to geopolitical disruption and quality inconsistency risks.
- Clinical Trial Complexity:Endpoint definition challenges for community-acquired pneumonia trials prolong development timelines and inflate study costs beyond traditional anti-infective benchmarks.
- Generic Substitution Pressure:Patent-expired macrolides and fluoroquinolones commoditize standard-of-care segments, compressing reimbursement ceilings for branded entrants.
Strategic Opportunities
- WHO Prequalification Pathway:Prequalification requirements unlock access to UN agency procurement and national essential medicine programs across low-income markets.
- Combination Antibiotic-Adjuvant Platforms:Pairing existing agents with resistance-breaker compounds addresses escalating multidrug-resistant pathogen prevalence in intensive care units.
- Point-of-Care Diagnostics Integration:Rapid pathogen identification at hospital admission enables targeted therapy selection, creating pull-through for companion diagnostic-therapeutic bundles.
Industry Challenges
- Specialized Clinical Pharmacology Talent:Shortage of investigators experienced in pulmonary drug disposition studies constrains development programs for inhaled anti-infective formulations.
- Legacy Manufacturing Retrofit Requirements:Conversion of oral-solid facilities to aseptic injectable capacity demands capital deployment that mid-tier developers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pneumonia Therapeutics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Community-Acquired, Hospital-Acquired, Ventilator-Associated, Aspiration Product Type: Antibiotics, Antiviral Drugs, Corticosteroids, Immunomodulators, Vaccines End User: Hospitals, Clinics, Outpatient Care Centers, Nursing Facilities Delivery Mode: Oral, Intravenous, Inhalation, Intramuscular, Subcutaneous |
| Companies Covered | Pfizer Inc., AstraZeneca plc, Novartis AG, Sanofi S.A., Merck & Co., Inc., F. Hoffmann-La Roche Ltd., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pneumonia Therapeutics Market Shifts & Advancements
Respiratory anti-infective development is pivoting toward precision-targeted modalities and delivery innovations that promise to overcome established resistance mechanisms and improve lung tissue penetration.
RNA-based therapeutics targeting conserved bacterial virulence factors are rewriting the feasibility of pathogen-specific intervention in polymicrobial pneumonia. Academic medical centers in Germany and the Netherlands have initiated early feasibility programs. The modality is compressing traditional antibiotic discovery timelines by bypassing cell-wall permeability constraints that have stalled small-molecule programs.
FDA's Qualified Infectious Disease Product designation creates regulatory fast lanes for novel pneumonia therapies addressing resistant gram-negative pathogens. The incentive structure grants extended market exclusivity and priority review vouchers. Hospital systems in the United States are building formularies around QIDP-designated agents to preempt stewardship committee restrictions on older broad-spectrum alternatives.
Centralized hospital procurement committees now mandate pharmacoeconomic documentation for formulary inclusion, displacing traditional physician-driven prescribing autonomy. Integrated delivery networks in California and Texas have implemented therapeutic interchange protocols that override individual clinician preferences. This behavioral shift concentrates volume with manufacturers capable of producing real-world evidence packages and outcomes-based contract structures.
Global Pneumonia Therapeutics Market Segmentation
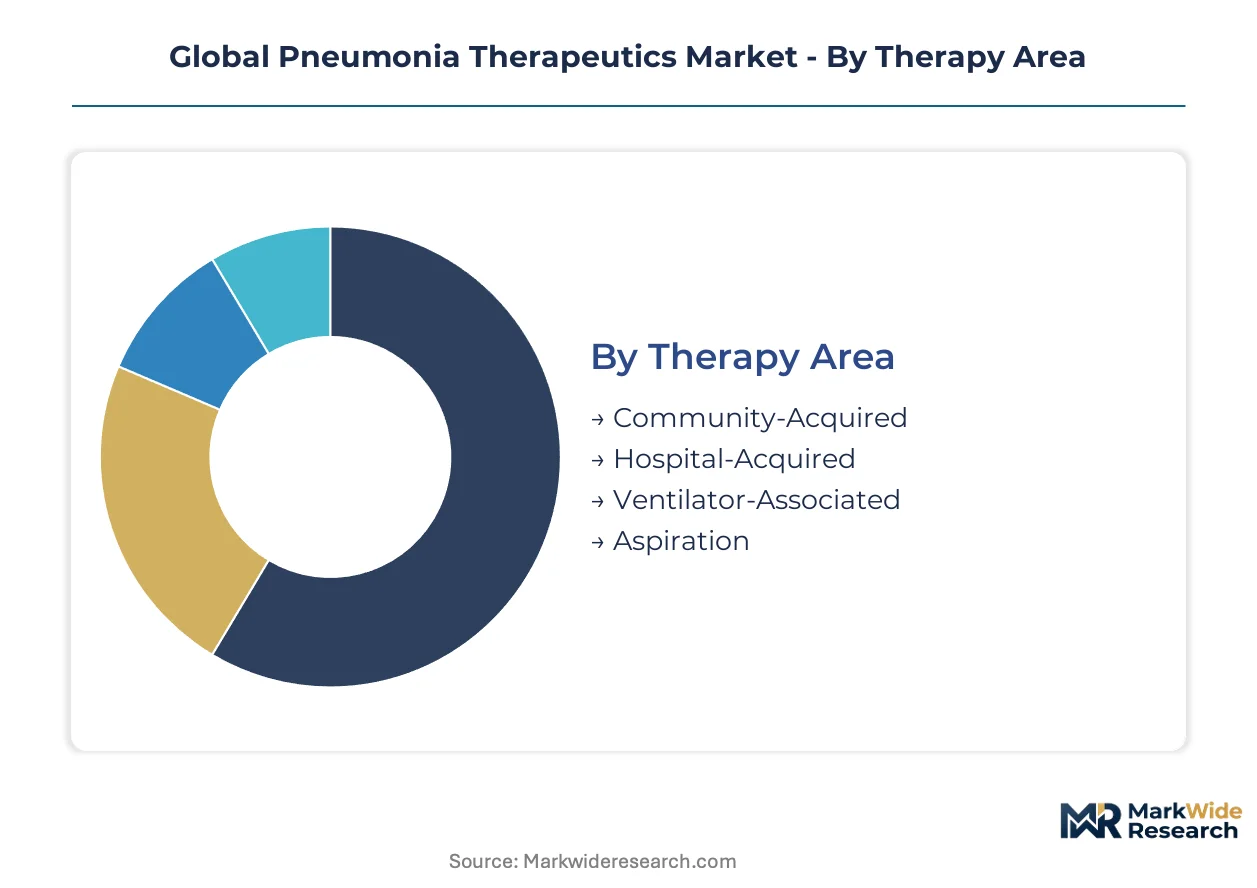
Pneumonia therapeutics segmentation reveals divergent margin structures across therapy settings and administration routes. Hospital procurement committees weight product-type decisions against stewardship mandates, while delivery-mode selection follows severity stratification protocols in emergency departments.
Therapy Area:
Volume concentrates in high-turnover emergency settings, while premium pricing attaches to complex intensive-care presentations requiring specialized antimicrobial stewardship.
- Community-Acquired:Outpatient and emergency department presentations of Streptococcus pneumoniae and atypical pathogen infections. Demand clusters in India and Nigeria where government tenders for first-line antibiotics dominate public procurement channels.
- Hospital-Acquired:Nosocomial infections arising after 48 hours of admission, typically involving multidrug-resistant gram-negative organisms. German and Dutch academic medical centers drive protocol development for narrow-spectrum de-escalation strategies.
- Ventilator-Associated:Lower respiratory infections developing in mechanically ventilated patients. Brazil's expanding intensive-care infrastructure pulls volume for inhaled antibiotic formulations.
- Aspiration:Chemical and bacterial pneumonitis following oropharyngeal content inhalation. Nursing facilities in Japan and South Korea generate concentrated demand for prophylactic positioning protocols.
Today's leader: Community-Acquired. Tomorrow's challenger: Hospital-Acquired.
Product Type:
Antibiotics command formulary dominance through entrenched prescribing habits, while vaccines gain share through national immunization program expansions.
- Antibiotics:Beta-lactams, macrolides, and respiratory fluoroquinolones targeting bacterial cell-wall synthesis or protein synthesis. WHO Essential Medicines List revisions in low-income markets prioritize amoxicillin and ceftriaxone procurement.
- Antiviral Drugs:Neuraminidase inhibitors and polymerase inhibitors for influenza-associated pneumonia. Seasonal demand spikes in US and European winter months strain hospital pharmacy inventory systems.
- Corticosteroids:Adjunctive dexamethasone and methylprednisolone for inflammatory lung injury modulation. EMA guidance on severe community-acquired pneumonia drives standardized adjuvant protocols.
- Immunomodulators:Monoclonal antibodies and cytokine inhibitors targeting dysregulated host response. Academic medical centers in Switzerland and Australia pilot precision-dosing programs.
- Vaccines:Pneumococcal conjugate and polysaccharide formulations for prevention. Nigeria and Brazil government tenders represent the steepest expansion trajectory as national programs scale coverage.
Antibiotics anchor current revenue. Vaccines are climbing the fastest.
End User:
Procurement authority centralization favors large-scale contract manufacturers capable of integrated delivery network compliance.
- Hospitals:Acute-care institutions with centralized pharmacy committees and therapeutic interchange protocols. California and Texas integrated delivery networks mandate pharmacoeconomic documentation for formulary inclusion.
- Clinics:Outpatient diagnostic and treatment facilities managing uncomplicated presentations. India's urban clinic networks generate high-volume oral antibiotic dispensing.
- Outpatient Care Centers:Ambulatory settings for observation and short-stay therapy. US Medicare reimbursement shifts pull lower-acuity cases from inpatient admission.
- Nursing Facilities:Long-term care institutions managing aspiration risk and recurrent infection. Japan's aging demographic concentrates demand for prophylactic vaccine programs.
Hospitals retain procurement dominance. Outpatient Care Centers gain procedural volume.
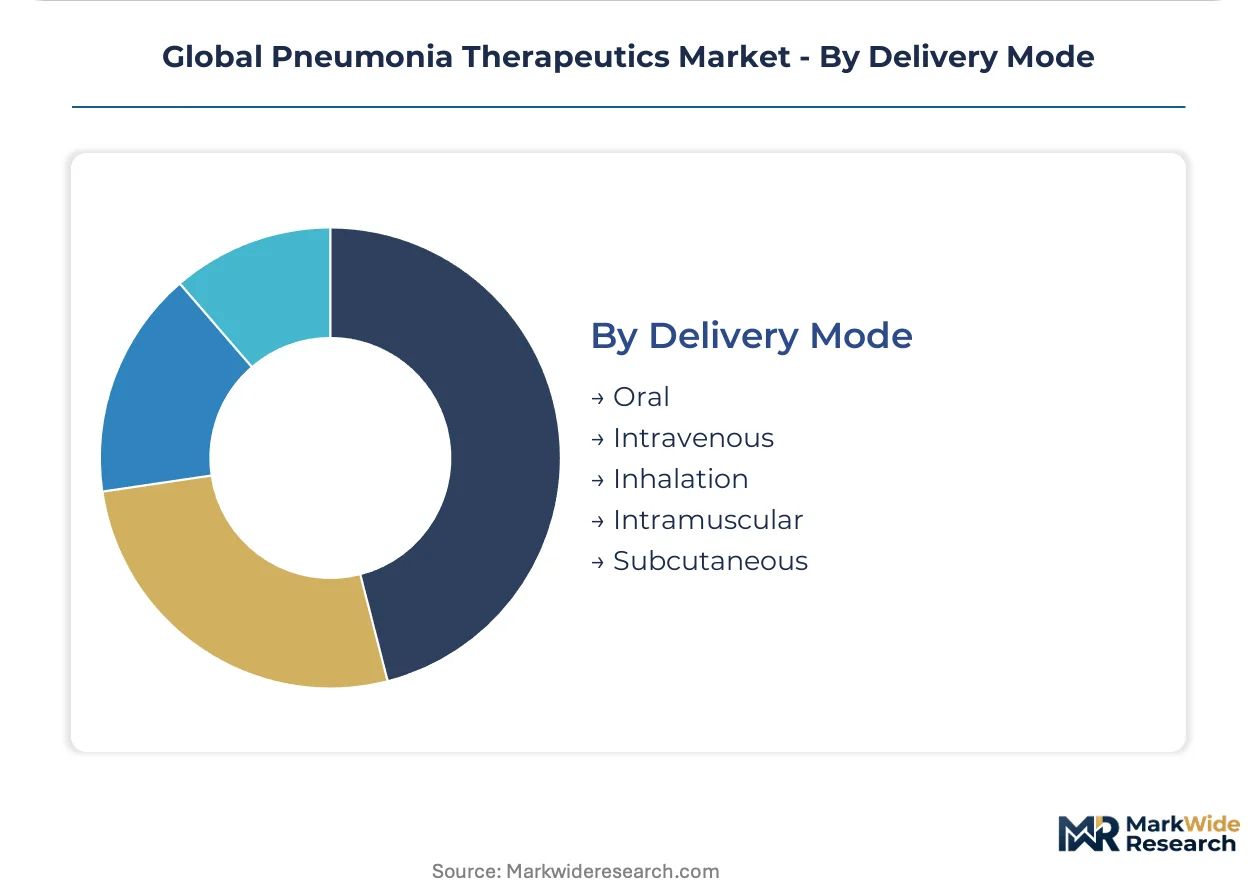
Delivery Mode:
Route selection follows severity stratification, with parenteral administration commanding intensive-care premium pricing.
- Oral:Tablet and suspension formulations for stable patients with intact gastrointestinal function. Community pharmacies in India and Nigeria process high-volume government tender distributions.
- Intravenous:Direct vascular administration for rapid therapeutic drug level attainment in critical illness. Intensive-care settings in Germany and the Netherlands prioritize this mode for severe presentations.
- Inhalation:Aerosolized antibiotics for localized lung deposition in ventilator-associated cases. Brazil's expanding critical-care infrastructure drives nebulizer-compatible formulation demand.
- Intramuscular:Depot injections for vaccine delivery and extended-release antibiotics. Nigeria's national immunization program relies on cold-chain-compatible intramuscular administration.
- Subcutaneous:Immunomodulator and prophylactic antibiotic delivery for outpatient self-administration. Swiss and Australian precision-medicine programs pilot home-based subcutaneous protocols.
Intravenous commands critical-care premiums. Inhalation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates higher tender volumes for first-line pneumonia antibiotics than Germany, yet German academic centers drive narrow-spectrum de-escalation protocols that shape stewardship standards worldwide.
United States
FDA's Qualified Infectious Disease Product designation accelerates novel therapy approvals while hospital systems build formularies around QIDP-designated agents. California and Texas integrated delivery networks mandate pharmacoeconomic documentation for formulary inclusion. The Boston-Cambridge cluster anchors respiratory anti-infective R&D programs.
Germany
EMA PRIME eligibility criteria compress development timelines for anti-infectives entering European markets. Academic medical centers in Heidelberg and Munich pilot precision-dosing protocols for immunomodulators. The Rhine-Main region concentrates pharmacovigilance expertise for post-market surveillance.
India
Government tender volumes for amoxicillin and ceftriaxone dominate public-sector procurement channels. CDSCO streamlined approval pathways accelerate access to WHO-prequalified generics. Mumbai-Pune pharmaceutical corridors manufacture active pharmaceutical ingredients for global antibiotic supply chains.
Brazil
ANVISA regulatory harmonization with PAHO standards facilitates pneumococcal vaccine program expansion. Expanding intensive-care infrastructure in São Paulo and Rio de Janeiro pulls volume for inhaled antibiotic formulations. The national immunization program represents the steepest vaccine volume expansion trajectory in Latin America.
Nigeria
WHO prequalification requirements unlock procurement through UN agencies and national essential medicine programs. Cold-chain-compatible intramuscular vaccine administration reaches rural populations through expanded primary health care networks. Lagos and Abuja anchor distribution hubs for Gavi-funded pneumococcal conjugate vaccines.
Global Pneumonia Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and delivery technology tiers. Market structure consolidates around manufacturers capable of integrated delivery network compliance and multi-year hospital supply contracting. Three archetypes dominate: multinational pharmaceutical conglomerates with respiratory portfolios, generic antibiotic specialists with API-to-finished-dose integration, and vaccine-focused biologics developers with cold-chain infrastructure. Competitive moves center on manufacturing scale expansion and resistance-breaker compound licensing.
Within the multinational conglomerate tier, Pfizer Inc. and AstraZeneca plc occupy positions defined by manufacturing scale and sustained R&D investment in respiratory anti-infectives. Novartis AG exemplifies the diversified pharmaceutical archetype with vaccine and generic medicine capabilities spanning multiple therapeutic modalities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca plc |
| Novartis AG |
| Sanofi S.A. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient costs originating in Mumbai-Pune pharmaceutical corridors cascade through three-tier pricing structures across premium, standard, and economy levels, with WHO prequalification status determining final procurement tier placement in government tender channels.
Pricing Analysis
Capacity additions in India are reshaping price floors for generic beta-lactams and macrolides. Contract-based long-term offtake dominates hospital procurement, with price differentiation driven by FDA QIDP designation tier and volume scale commitments. Pricing pressure stems from patent-expired fluoroquinolone commoditization in standard-of-care segments. Government tender buyers in Nigeria and India exhibit highest price sensitivity; US integrated delivery networks demonstrate lowest sensitivity due to outcomes-based contract structures.
Supply Chain Analysis
WHO prequalification and FDA QIDP designation serve as the primary gating mechanisms for supplier eligibility in UN agency and US hospital procurement channels. API manufacturing concentrates in India and China, with finished-dose formulation in Germany and the United States. Supply chains draw from fermentation-derived intermediates, sterile packaging components, and cold-chain logistics infrastructure. Single-source vulnerability persists in penicillin core intermediate production. Distribution runs through centralized pharmacy committees at integrated delivery networks and government medical stores depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between Indian API production and German formulation finishing creates margin expansion opportunities for cross-border supply chain architectures.
For Market Incumbents: Extend manufacturing scale advantages through backward integration into penicillin G intermediate production to offset API supply concentration risk. Anchor hospital formulary position by expanding real-world evidence generation for QIDP-designated agents facing antimicrobial stewardship committee restrictions. For New Entrants and Emerging Players: Enter via WHO prequalification pathway for amoxicillin and ceftriaxone to access Gavi-funded procurement in Nigeria and government tender channels in India. Target Brazil's ventilator-associated pneumonia segment with nebulizer-compatible formulations where ANVISA harmonization reduces regulatory entry barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier developers lack capital for aseptic injectable facility retrofit. Five-to-ten year viability favors API-to-finished-dose integrated specialists with cold-chain vaccine infrastructure. Signal to monitor: EMA PRIME eligibility announcements signaling accelerated European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Pfizer's multi-year hospital supply contracts demonstrate procurement consolidation leverage. |
| Regulatory Approval Pathway | FDA QIDP designation unlocks extended exclusivity for resistant gram-negative therapeutics. |
| Backward Integration | Captive API production insulates against Mumbai-Pune supply basin disruption risks. |
| Clinical Trial Advancement | RNA-based virulence factor programs in Heidelberg and Munich compress discovery timelines. |
| Licensing Agreement | Resistance-breaker compound partnerships address ICU multidrug-resistant pathogen prevalence. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists were validated against secondary sources including FDA QIDP designation databases, EMA PRIME eligibility records, WHO prequalification listings, and government tender documentation. Triangulation across these inputs ensures segmentation integrity.
Input-output matrices map therapy area demand against product-type supply capacity across the projection horizon. Segmentation dimensions span therapy setting, product type, end user, and delivery mode, with regional regulatory clusters as an overlay. CAGRs derive from slope analysis of tender volume trajectories and immunization program scale-up schedules. Forecast inputs include antimicrobial stewardship mandate adoption curves and pneumococcal coverage expansion timelines.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-world outcomes data for novel immunomodulators introduce uncertainty bands around precision-dosing adoption forecasts. A model refresh is warranted upon material change in WHO Essential Medicines List antibiotic tier placement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Emphysema Treatment Market